
 Specification Management Software Market | 2026-2036
Specification Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Specification Management Software Market Outlook
The capability gap between cloud-native specialists and legacy on-premises vendors is redrawing competitive boundaries in specification management. Specright leverages API-first architecture to capture multi-tier supplier data across food and consumer goods chains. Emerson Electric Co. sustains entrenched positions in process manufacturing through deep PLC and MES integration. Lascom competes on European regulatory depth, particularly around REACH compliance documentation and multilingual specification templates.
Specification management software governs the creation, revision, distribution, and audit of product and material specifications across distributed supply networks, typically operating through centralized databases with version control, approval workflows, and attribute-level traceability. Cloud-based deployment leads absolute revenue contribution due to lower implementation friction and faster multi-site rollout, though hybrid architectures are gaining traction among aerospace and pharmaceutical users with air-gapped quality systems. Workflow automation solutions command premium pricing by reducing specification approval cycles from weeks to days, while compliance tracking modules show the fastest growth trajectory as regulators mandate electronic record-keeping.
FDA's 21 CFR Part 11 electronic records requirements, the EU's CSRD supply chain disclosure mandates, and China's GB standards digitization push are elevating specification software from operational convenience to regulatory necessity. EMA's evolving eCTD specification standards for pharmaceutical submissions further tighten validation requirements. Stakeholders must evaluate whether their current platforms can absorb emerging AI-driven specification extraction and automated deviation detection without core architecture replacement.
Market Dynamics
Cloud-native specification platforms are compressing implementation timelines from months to weeks, forcing legacy vendors to rearchitect or lose multi-site deployments in food and automotive supply chains.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in pharmaceutical manufacturing are converting paper-based specification workflows into validated software systems, creating replacement demand across US drug production facilities.
- Automotive supplier digitization:Tier-1 and Tier-2 component manufacturers in Germany are deploying specification management to synchronize material declarations with OEM compliance portals.
- API-first architectures:RESTful integration capabilities are enabling real-time specification synchronization between ERP, PLM, and supplier quality management systems without custom middleware development.
Market Restraints
- Legacy system entrenchment:On-premises specification databases in aerospace and defense contain decades of validated records that resist cloud migration due to air-gapped security requirements.
- Implementation cost concentration:Mid-market food manufacturers face six-figure professional services bills for data migration and workflow configuration that compress software ROI timelines.
- Substitution by generic PLM:Industrial equipment makers are extending existing product lifecycle management licenses to cover material specifications rather than purchasing dedicated specification software.
Strategic Opportunities
- EU CSRD supply chain disclosure:The Corporate Sustainability Reporting Directive mandates granular upstream emissions and material data that specification platforms are uniquely positioned to capture and audit.
- AI-driven specification extraction:Natural language processing tools that parse unstructured PDF supplier certificates into structured attribute databases represent a greenfield automation layer.
- India PLI scheme manufacturing:Production-linked incentive recipients in pharmaceuticals and electronics must demonstrate domestic value addition through documented specification compliance, creating localized demand.
Industry Challenges
- Data steward talent scarcity:Organizations struggle to hire specification administrators who combine domain expertise in chemistry or engineering with database governance skills.
- Multi-jurisdiction validation overhead:Pharmaceutical companies must maintain parallel specification instances for FDA, EMA, and NMPA submission formats, tripling compliance documentation effort.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specification Management Software Market |
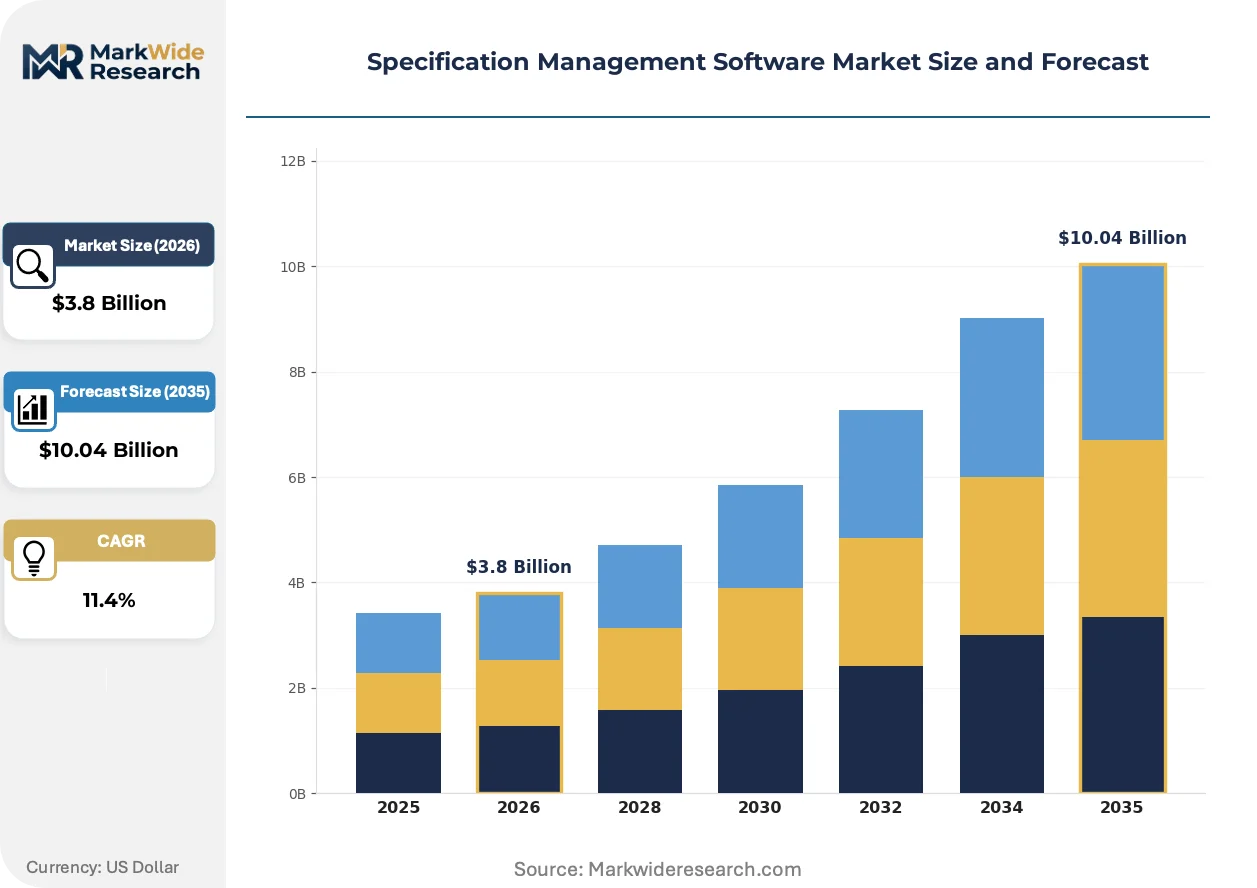
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Manufacturers, Retailers, Distributors, Engineers Solution: Data Management, Compliance Tracking, Workflow Automation, Collaboration Tools Industry Vertical: Construction, Automotive, Consumer Goods, Electronics |
| Companies Covered | Specright, Accompa, DocXellent, Esko, Emerson Electric Co., Isolocity, Lascom, PiLog Group, QADEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specification Management Software Market Strategic Shifts
Specification management is converging with supply chain traceability and sustainability disclosure, transforming standalone document repositories into networked compliance infrastructure.
AI-powered specification extraction is miniaturizing data entry workloads by automatically parsing supplier certificates, material safety data sheets, and test reports into structured attribute libraries. Food and beverage quality teams are deploying these tools to onboard new ingredient suppliers in days rather than weeks. The technology is compressing specification creation cycles and reducing manual transcription errors that previously triggered regulatory deviations.
EMA's evolving eCTD specification standards for pharmaceutical submissions are tightening validation requirements for electronic common technical document formatting. Drug manufacturers must now ensure specification software outputs meet precise XML schema and metadata tagging rules for regulatory acceptance. European pharmaceutical quality systems are responding by embedding eCTD validation engines directly into specification approval workflows.
Direct supplier portal access is displacing email-based specification distribution in tiered manufacturing supply chains. Automotive and electronics buyers are granting vetted suppliers self-service update capabilities for material declarations and certificates of analysis, with automated compliance checks replacing manual review queues. Germany and Japan anchor this shift, where OEMs have mandated portal-based specification exchange for new supplier qualifications.
Specification Management Software Market Segmentation
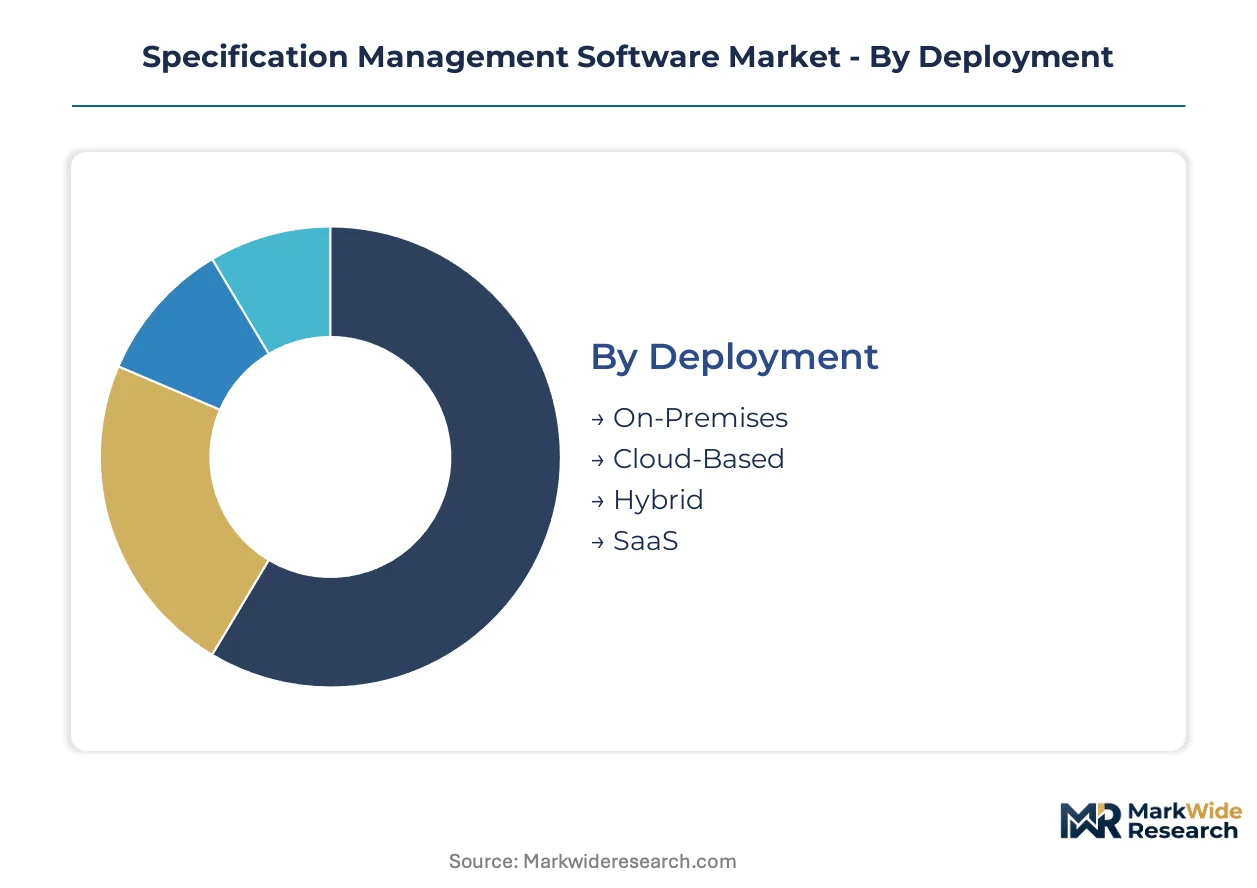
Specification management software segments reflect divergent deployment economics and compliance intensity across buyer types. Cloud-native architectures compress implementation timelines for mid-market manufacturers while hybrid models preserve air-gapped validation for pharmaceutical and defense contractors. Understanding segment boundaries clarifies where workflow automation commands premium pricing versus where compliance modules drive replacement demand.
Deployment:
Channel mix varies sharply by deployment mode: cloud-based and SaaS offerings flow through direct vendor sales and AWS/Azure marketplaces, while on-premises and hybrid deployments require systems integrators and regional VARs with vertical certifications.
- Cloud-Based:Multi-tenant architectures with RESTful APIs enable real-time specification synchronization across distributed supplier networks. Food and beverage manufacturers in Germany and the United States are concentrating demand here, driven by FDA 21 CFR Part 11 mandates and EU Green Deal documentation requirements that reward rapid multi-site rollout without capital infrastructure.
- SaaS:Subscription pricing with pre-configured workflow templates accelerates time-to-value for mid-market consumer goods producers lacking dedicated IT specification teams. Automotive tier-1 suppliers in Japan leverage SaaS portals to synchronize material declarations with OEM compliance systems.
- On-Premises:Validated installations in pharmaceutical manufacturing maintain decades of electronic batch records under FDA and EMA audit trails. Aerospace and defense contractors in the United States retain these deployments for air-gapped security compliance.
- Hybrid:Split architectures isolate sensitive formulation data on-premises while exposing supplier collaboration interfaces through cloud gateways. Chemical producers in Switzerland and France adopt this model to satisfy REACH documentation requirements without exposing proprietary compound specifications.
By volume, cloud-based deployments lead. By growth pace, SaaS is gaining share fastest as mid-market buyers abandon capital-intensive on-premises implementations.
End User:
Cost tier stratification separates these segments: manufacturers and engineers invest in full-featured platforms with PLM integration, while retailers and distributors prioritize lightweight collaboration modules with lower per-seat pricing.
- Manufacturers:Process and discrete manufacturers deploy end-to-end specification lifecycle management with version control, approval workflows, and attribute-level traceability. Pharmaceutical manufacturers in the United States and Ireland drive demand for FDA-validated systems with electronic signature capabilities and audit trail immutability.
- Engineers:R&D and quality engineering teams require deep parametric search and cross-reference capabilities for material substitution analysis. Automotive and electronics engineers in Germany and South Korea concentrate adoption where REACH and RoHS compliance documentation must link directly to CAD and simulation tools.
- Distributors:Industrial and specialty chemical distributors utilize specification portals to aggregate supplier certificates of analysis and material safety data sheets for downstream customer self-service. North American and European distributors lead this segment.
- Retailers:Private-label retailers deploy specification tracking to manage contract manufacturer compliance with product claims, nutritional labeling, and sustainability certifications. Food retailers in the United Kingdom and France are expanding adoption to satisfy CSRD supply chain disclosure mandates.
Manufacturers dominate absolute spending. Retailers are expanding most quickly as sustainability disclosure requirements penetrate consumer-facing supply chains.
Solution:
Application maturity separates established data management from emerging automation layers: compliance tracking and workflow automation represent newer spend categories while data management constitutes replacement and upgrade cycles.
- Compliance Tracking:Regulatory validation engines automate deviation detection, audit preparation, and multi-jurisdiction submission formatting for FDA, EMA, and NMPA requirements. Pharmaceutical quality teams in the United States and Switzerland pay premium pricing for eCTD-compliant output generation.
- Workflow Automation:Configurable approval chains with electronic signatures compress specification revision cycles from weeks to days. Food and beverage quality teams in Germany and the Netherlands deploy these tools to accelerate new ingredient supplier onboarding.
- Data Management:Centralized specification repositories with version control and attribute-level search form the foundational layer. Process manufacturers across all geographies treat this as table stakes, with replacement demand driven by end-of-life legacy database migrations.
- Collaboration Tools:Supplier portal access with self-service update capabilities and automated compliance checking displaces email-based specification distribution. Automotive OEMs in Germany and Japan mandate portal-based exchange for new supplier qualifications.
Data management leads by installed base. Compliance tracking shows the steepest expansion trajectory as regulators mandate electronic record-keeping across jurisdictions.
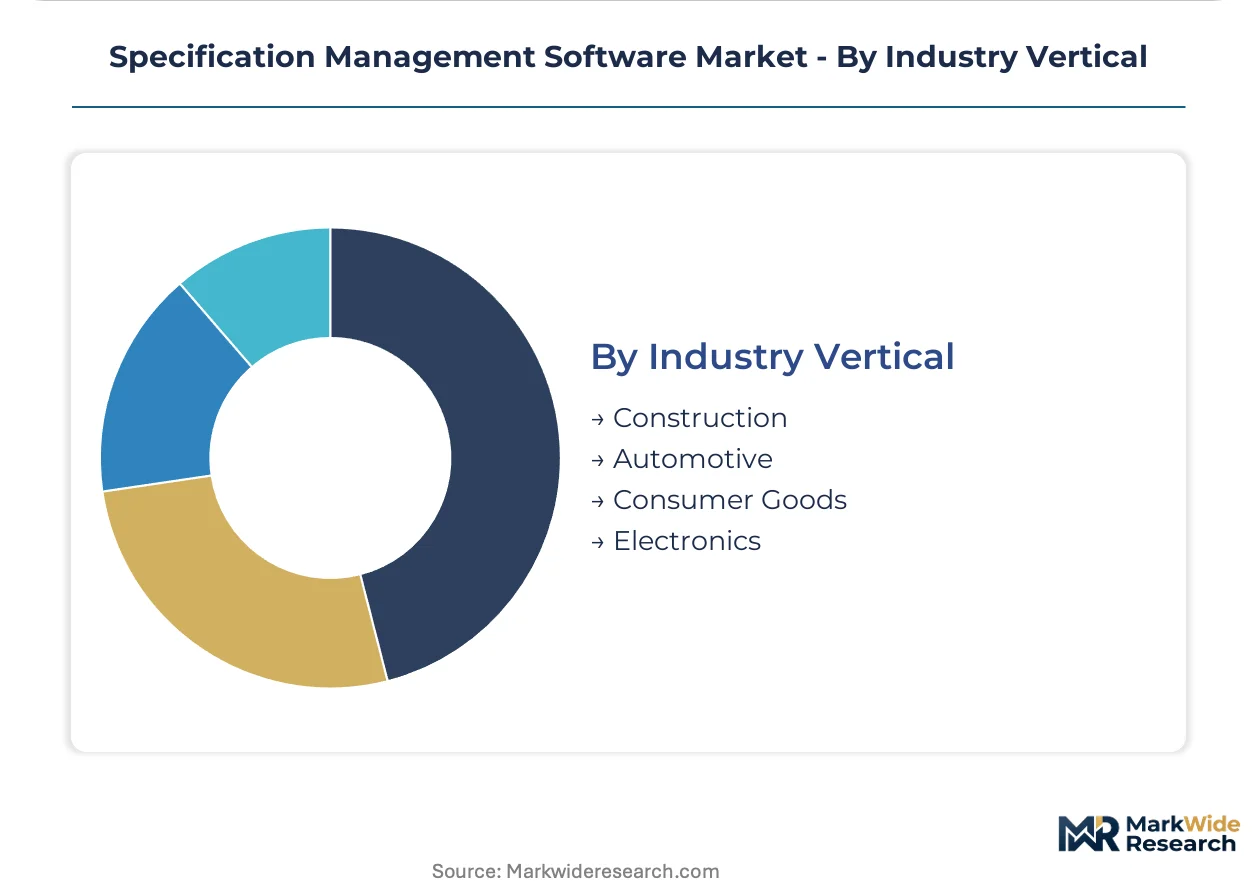
Industry Vertical:
Supply concentration shapes competitive dynamics: automotive and electronics buyers cluster in Germany and East Asia with standardized OEM requirements, while construction and consumer goods fragment across regional specifications and certification regimes.
- Automotive:Material declaration synchronization with IMDS and OEM compliance portals drives specification management adoption across tier-1 and tier-2 component suppliers. German automotive suppliers lead deployment scale, with Japanese and South Korean manufacturers following OEM-mandated digitization timelines.
- Electronics:RoHS, REACH, and conflict mineral documentation requirements create complex multi-tier supplier data collection challenges. Taiwanese and South Korean electronics contract manufacturers concentrate demand for API-first platforms integrating with PLM and ERP systems.
- Consumer Goods:Private-label and branded goods manufacturers track ingredient specifications, nutritional claims, and sustainability certifications across global contract manufacturing networks. European and North American consumer goods producers lead adoption driven by CSRD and FTC labeling enforcement.
- Construction:Building product manufacturers manage material specifications for LEED, BREEAM, and national building code compliance. French and German construction materials producers deploy specification systems to track environmental product declarations and embodied carbon data.
Automotive leads by contract value concentration. Consumer goods is climbing the fastest as sustainability disclosure mandates expand beyond Europe into North American and Asian regulatory frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specification management software trade flows track manufacturing digitization intensity. Net importers cluster in Western Europe and North America where regulatory complexity exceeds domestic vendor capacity. Net exporters concentrate in the United States and Germany where platform development precedes regulatory mandates elsewhere.
United States
FDA 21 CFR Part 11 enforcement and pharmaceutical manufacturing reshoring drive specification software procurement. The FDA mandates electronic records for drug production facilities, converting paper workflows into validated systems. New Jersey and Massachusetts pharmaceutical clusters deploy these platforms to maintain audit trails for domestic and export markets.
Germany
Automotive supplier digitization and REACH documentation requirements anchor European demand. The EU Green Deal tightens supply chain disclosure rules for material sourcing. Bavaria and Baden-Württemberg automotive tier-1 suppliers synchronize material declarations with OEM compliance portals using API-first platforms.
China
GB standards digitization and pharmaceutical manufacturing expansion create specification management demand. NMPA electronic submission requirements tighten validation standards for drug manufacturers. Yangtze River Delta pharmaceutical producers adopt compliant systems to serve domestic and export markets simultaneously.
Japan
Automotive OEM-mandated supplier digitization and METI industrial data standards shape procurement patterns. PMDA pharmaceutical regulations require electronic common technical document formatting. Nagoya and Osaka manufacturing clusters deploy specification portals for tiered supplier network management.
India
PLI scheme manufacturing incentives and CDSCO pharmaceutical digitization drive adoption. Production-linked incentive recipients must demonstrate domestic value addition through documented specification compliance. Gujarat and Maharashtra pharmaceutical and electronics producers invest in compliance-tracking modules to qualify for subsidy disbursement.
Specification Management Software Market Competitive Environment
Concentration sits with cloud-native specialists and legacy industrial software incumbents. The vendor base splits between API-first platforms capturing multi-tier supply chain data and entrenched process manufacturing systems with deep PLC integration. Two strategic archetypes dominate: regulatory compliance specialists and workflow automation generalists. Competitive moves center on M&A for data extraction capabilities and strategic partnerships with ERP vendors to embed specification modules.
Within the cloud-native tier, Specright and Lascom exemplify divergent geographic positioning. Specright anchors North American food and consumer goods supply chain digitization. Lascom occupies a position emphasizing European regulatory depth. Emerson Electric Co. represents the industrial incumbent archetype, sustaining market presence through process manufacturing system integration rather than standalone specification offerings.
| Leading Market Players |
|---|
| Specright |
| Accompa |
| DocXellent |
| Esko |
| Emerson Electric Co. |
| Isolocity |
| Lascom |
| PiLog Group |
| QADEX |
| Others |
Value Chain & Pricing Dynamics
Long-term SaaS subscription contracts with capacity reservation clauses lock in multi-year supply access for specification management platforms while fixing price visibility for pharmaceutical and automotive buyers. These structures bundle implementation services, validation support, and tiered user licenses into predictable annual commitments that shield vendors from churn while constraining buyer flexibility.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing that stratifies across enterprise, professional, and essential tiers. Certification grade — FDA 21 CFR Part 11 validation versus standard ISO compliance — drives price differentiation alongside integration complexity with ERP and PLM systems. Cost compression in the essential tier intensifies as mid-market food manufacturers substitute generic PLM licenses for dedicated specification software. Pharmaceutical quality teams exhibit least price sensitivity due to regulatory non-negotiability, while construction material distributors face acute margin pressure from commoditized collaboration modules.
Supply Chain Analysis
Cloud infrastructure concentration in the United States, Germany, and Ireland underwrites specification software delivery latency and data residency compliance. Platform development draws from specialized talent pools in software engineering hubs, with implementation services sourced from regional systems integrators holding vertical certifications. Single-source vulnerability concentrates in hyperscaler compute dependencies that expose buyers to cross-border data transfer restrictions. Distribution runs through direct vendor sales teams and AWS/Azure marketplaces for cloud-native deployments, with hybrid implementations requiring certified regional VARs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification management software sits in early-cycle expansion as regulatory digitization mandates convert paper workflows into validated electronic systems across pharmaceutical and food manufacturing. FDA 21 CFR Part 11 enforcement and EU CSRD supply chain disclosure requirements are accelerating replacement demand beyond natural upgrade cycles.
For Market Incumbents: Secure API-first architecture leadership by acquiring natural language processing specialists for automated specification extraction, insulating against cloud-native entrants. Deepen MES and PLC integration in process manufacturing to raise switching costs for Emerson Electric Co. and legacy industrial software accounts. Certification investment in EMA eCTD and NMPA electronic submission formats preserves multi-jurisdiction pharmaceutical contracts. For New Entrants and Emerging Players: Anchor in India's PLI scheme manufacturing recipients, where production-linked incentive compliance documentation creates localized demand underserved by global vendors. Target mid-market chemical distributors in Europe requiring REACH documentation portals without enterprise-grade implementation overhead. A partner-first go-to-market through SAP and Oracle implementation channels accelerates time-to-revenue without direct sales buildout. For Investors and Strategic Acquirers: Cloud-native specialists with proven FDA validation engines and multi-tier supplier network density represent the most defensible acquisition profile. Long-term viability hinges on platform absorption of AI-driven deviation detection and automated compliance checking without core architecture replacement. Watch for inflection when EMA finalizes eCTD specification standards, triggering pharmaceutical validation refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Natural language processing targets compress supplier onboarding from weeks to days for food quality teams. |
| Strategic Partnership | ERP vendor embedding exposes specification modules to manufacturing procurement workflows at scale. |
| Product Launch | AI-powered extraction layers unlock unstructured PDF certificate parsing for automated attribute libraries. |
| Platform Integration | PLM and MES connectivity preserves incumbent position in pharmaceutical process manufacturing accounts. |
| Geographic Expansion | India PLI scheme localization captures pharmaceutical and electronics compliance documentation demand. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with software vendor executives, pharmaceutical quality directors, automotive procurement leads, and food manufacturing IT managers; and secondary validation through FDA 21 CFR Part 11 guidance documents, EMA eCTD specifications, EU CSRD regulatory texts, and hyperscaler marketplace deployment disclosures. Bottom-up sizing triangulated against top-down regulatory mandate penetration curves.
Across the analysis window, the forecasting framework modeled deployment mode, end-user archetype, solution type, and industry vertical with regional adoption pattern overlays. CAGRs derived from segment-level penetration rates applied to addressable manufacturing facility counts and software spend per seat. Pharmaceutical manufacturing reshoring intensity and automotive supplier digitization timelines anchored regional growth differentials.
Material uncertainties — regulatory enforcement variance, AI extraction accuracy trajectories, hyperscaler pricing volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions on mandate adoption curves and vendor implementation capacity scaling. Practitioners should keep alternative scenarios live as EMA eCTD finalization and NMPA electronic submission requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Avionics Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Audit Management Software Market
Software & Services
Point of Sale (Pos) Software Market
Software & Services
Enterprise Application Market
Software & Services
K8s Market
Software & Services
Interview Scheduling Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Chromatography Data System (CDS) Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Legal Software Market
Software & Services
Trading Software Market
Software & Services
Global Software Quality Assurance Market
Software & Services
Non-Profit Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Winery Management Software Market