
 Mobile Application Testing Services (MATS) Market | 2026-2036
Mobile Application Testing Services (MATS) Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Application Testing Services (MATS) Market Foresight
Open-source test automation frameworks are hardening as the default substrate for functional validation pipelines, displacing licensed tool stacks that carried heavier per-seat economics. Accenture PLC leverages its cloud-native testing labs to anchor large enterprise contracts across North America and Western Europe. Cognizant Technology Solutions Corporation sustains delivery density through its India-based engineering centers, while EPAM Systems Inc. differentiates via specialized digital platform testing for retail and fintech clients.
Mobile Application Testing Services encompass systematic validation of software functionality, performance, security, and user experience across iOS and Android operating systems, device hardware configurations, and network conditions. These services employ emulators, physical device farms, and cloud-distributed test grids to detect defects before production release, ensuring application reliability for end-users. Automation Tools and AI-Driven Testing represent the fastest-expanding technology segments, as machine learning-based test generation reduces script maintenance overhead and accelerates release cycles. Cloud-Based Solutions dominate deployment preferences, though Hybrid models retain traction among regulated industries requiring on-premises data custody for sensitive test environments.
The EU AI Act and GDPR impose algorithmic transparency and data protection mandates that directly shape security testing scope for MATS providers serving European clients. India's BIS standards and TRAI guidelines on data localization influence how offshore delivery centers architect test infrastructure and handle client data. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to inflate testing costs for cross-border application deployments.
Market Dynamics
Machine learning-based test generation is compressing release cycles and forcing providers to restructure delivery models around continuous validation pipelines rather than discrete testing phases.
Growth Catalysts
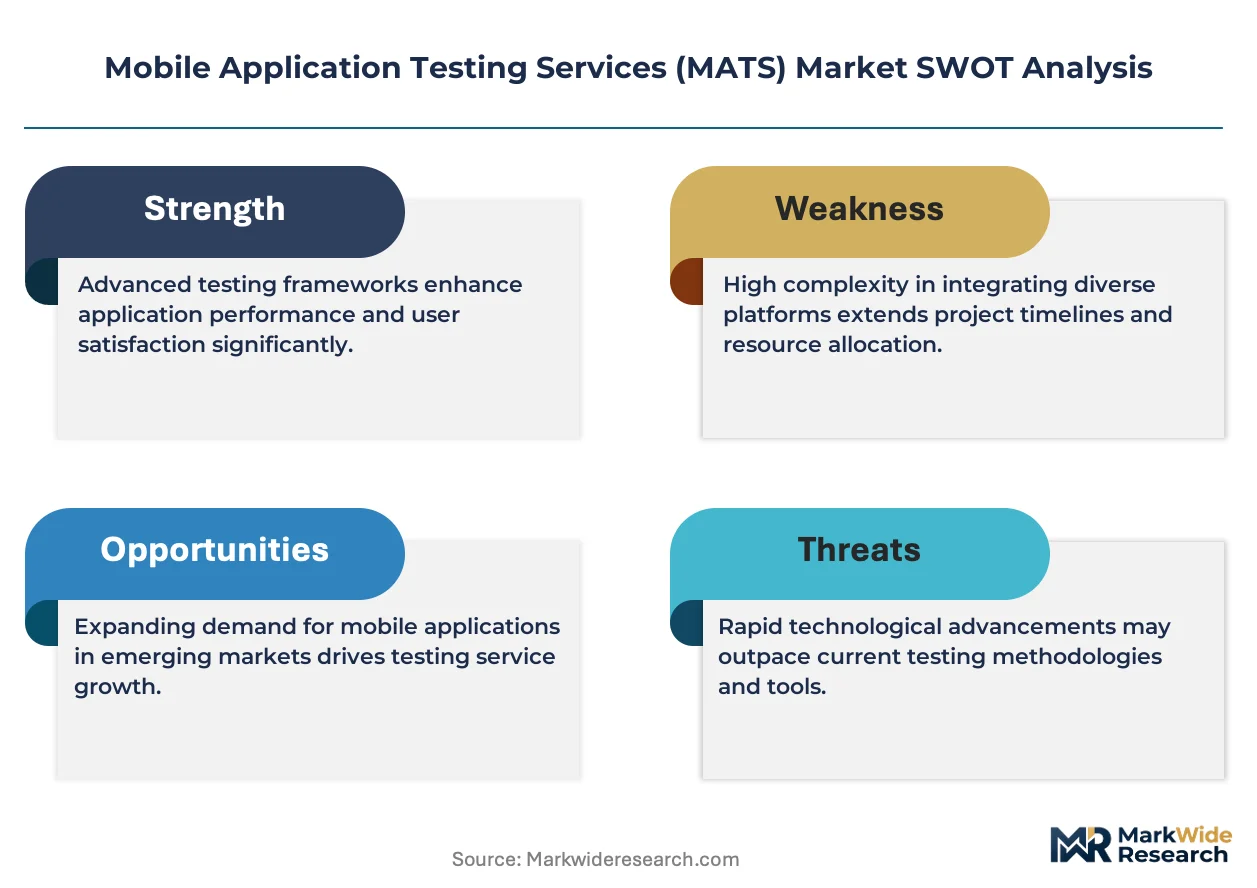
- EU AI Act compliance mandates:European financial services firms require automated algorithmic transparency validation for mobile payment platforms, expanding security testing scope.
- Cloud-distributed test grids:These architectures enable parallel execution across thousands of device configurations, reducing time-to-market for retail and fintech applications.
- India delivery center concentration:Bangalore and Hyderabad host engineering density that supports 24-hour validation cycles for North American and European clients.
Market Restraints
- Physical device farm capex intensity:Maintaining representative hardware libraries across iOS and Android generations requires continuous capital replenishment as OEM release cycles accelerate.
- GDPR data localization friction:European client data residency requirements complicate test environment architecture for offshore delivery centers.
- Emulator fidelity limitations:Synthetic environments fail to reproduce hardware-specific edge cases in biometric authentication and sensor-dependent workflows.
Strategic Opportunities
- 5G network condition simulation:Latency and bandwidth variability testing for next-generation mobile applications remains underdeveloped in current service portfolios.
- Outcome-based pricing models:Defect escape rate guarantees and release velocity commitments are displacing time-and-material contracts in enterprise procurement.
- Automotive infotainment convergence:Connected vehicle platforms require mobile application testing expertise applied to embedded Android and proprietary OEM systems.
Industry Challenges
- Test automation engineer scarcity:Proficiency in both mobile platform specifics and CI/CD pipeline integration remains concentrated among senior practitioners.
- Fragmented certification timelines:BIS standards in India, CE marking in Europe, and FCC requirements in the US create divergent compliance pathways for cross-border deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Application Testing Services (MATS) Market |
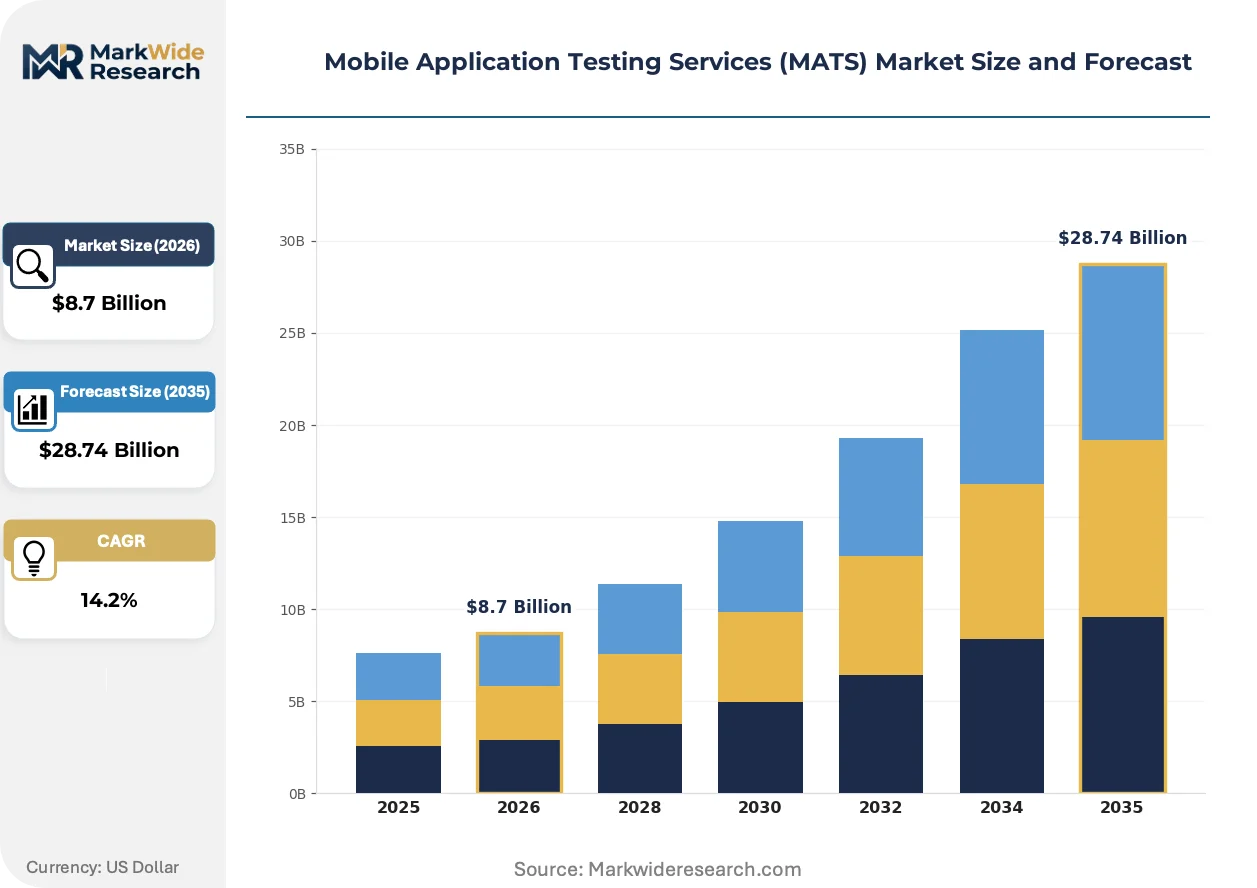
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Functional Testing, Performance Testing, Security Testing, Usability Testing Technology: Automation Tools, Manual Testing, Cloud-Based Solutions, AI-Driven Testing Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Enterprises, Startups, Freelancers, Agencies |
| Companies Covered | Accenture PLC, Capgemini SE, Cognizant Technology Solutions Corporation, EPAM Systems Inc., IBM Corporation, Wipro Ltd, Tata Consultancy Services Limited, Cigniti Technologies Ltd, Infosys Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Application Testing Services (MATS) Market Shifts & Advancements
Artificial intelligence is restructuring how test cases are generated, maintained, and prioritized, compressing the labor intensity that historically dominated functional validation economics.
Self-healing test scripts are integrating machine learning models that automatically update locators and assertions when application interfaces change. Retail and fintech QA teams are adopting these capabilities fastest, with pilot deployments scaling to production pipelines within six-month windows. This integration is reducing script maintenance overhead by half and enabling validation teams to redeploy engineering hours toward exploratory testing.
The EU AI Act's algorithmic transparency requirements are mandating documented testing protocols for automated decision systems in mobile applications. Financial services providers must now maintain audit trails linking training data to model outputs through validation stages. European deployments of AI-driven personalization features face the steepest compliance burden, with providers building specialized documentation pipelines to satisfy regulator review.
Enterprise procurement of MATS is consolidating around multi-year platform partnerships that bundle tooling, infrastructure, and engineering talent. Discrete project-based engagements are losing share to embedded delivery models where providers station teams within client DevOps organizations. This pattern is most pronounced among North American Fortune 500 enterprises modernizing legacy mobile applications.
Mobile Application Testing Services (MATS) Market Segmentation
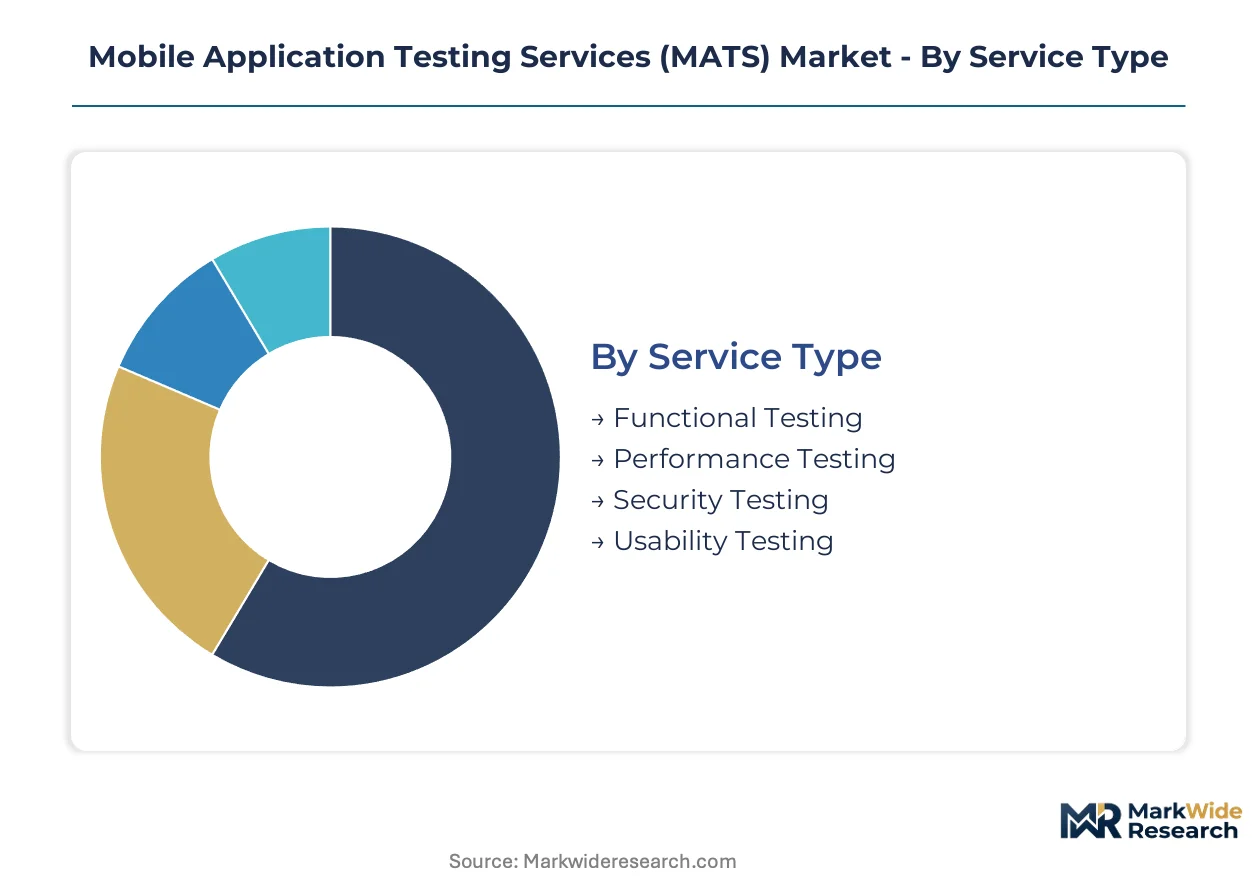
Mobile Application Testing Services (MATS) providers structure their portfolios around distinct technical capabilities and delivery models. Each segmentation axis reveals different buyer priorities—from security mandates in financial services to velocity requirements at venture-backed startups.
Service Type:
Procurement patterns diverge sharply between compliance-driven validation and velocity-focused functional coverage.
- Functional Testing:Systematic validation of user workflows, API integrations, and cross-platform compatibility. Retail and e-commerce enterprises in the United States concentrate spend here, prioritizing release velocity over exhaustive edge-case coverage.
- Security Testing:Penetration testing, vulnerability assessment, and encryption protocol validation for mobile payment architectures. European financial services firms under GDPR and EU AI Act mandates drive premium pricing for this segment.
- Performance Testing:Load testing and latency measurement across device and network conditions.
- Usability Testing:Accessibility compliance and user experience validation for consumer-facing applications.
Volume sits with Functional Testing; growth tilts toward Security Testing.
Technology:
Engineering talent density determines competitive positioning across automation maturity tiers.
- AI-Driven Testing:Machine learning models generate test cases, prioritize execution queues, and auto-heal broken scripts. Bangalore and Hyderabad delivery centers deploy these capabilities for North American fintech clients seeking compressed release cycles.
- Automation Tools:Open-source frameworks and licensed platforms execute repetitive validation without human intervention. Startups and mid-market enterprises favor these for cost predictability.
- Manual Testing:Human validation of exploratory scenarios and subjective user experience factors.
- Cloud-Based Solutions:Distributed test grids spanning device farms and emulator networks.
Automation Tools command current volume; AI-Driven Testing is climbing the fastest.
Deployment Model:
Data custody requirements fragment procurement between regulated and unregulated verticals.
- Hybrid:Sensitive test data remains on-premises while execution scales through cloud burst capacity. European healthcare and banking clients under GDPR residency rules require this architecture.
- Cloud-Based:Fully managed infrastructure with pay-per-execution economics. Technology startups and digital agencies prefer this for zero capital deployment.
- On-Premises:Captive infrastructure for classified or critical national infrastructure applications.
- Managed Services:Outsourced engineering teams embedded within client DevOps organizations.
Hybrid deployments anchor revenue; Cloud-Based solutions are gaining share fastest.
End User:
Contract structure and pricing mechanics vary by organizational scale and technical sophistication.
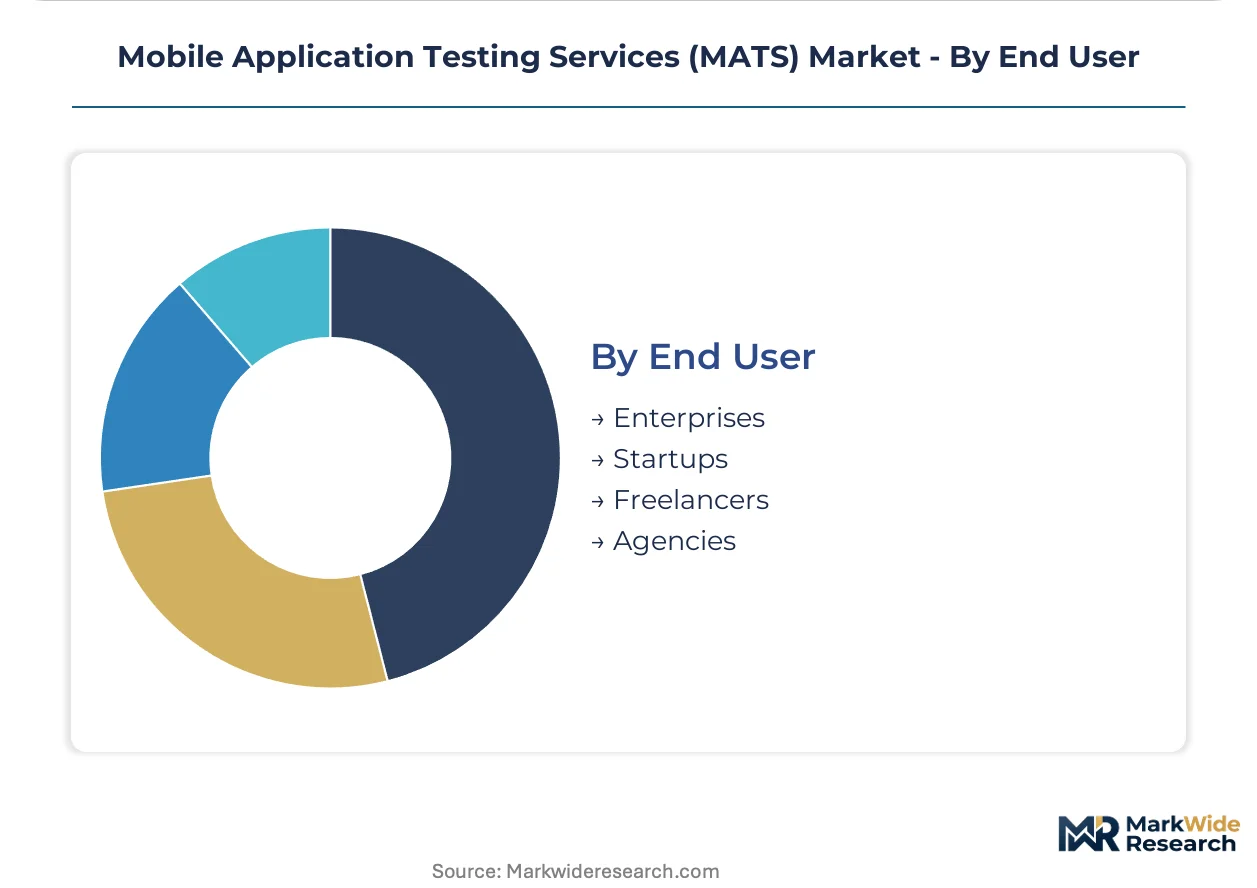
- Enterprises:Multi-year platform partnerships with outcome-based pricing tied to defect escape rates. Fortune 500 companies in the United States consolidate vendor relationships around embedded delivery models.
- Startups:Project-based engagements with aggressive velocity guarantees and minimal process overhead. Venture-backed fintechs in India negotiate fixed-price sprints for minimum viable product validation.
- Agencies:White-label testing capacity for creative and development shops serving brand clients.
- Freelancers:Individual practitioners supplying niche platform expertise.
Enterprises dominate contract value; Startups represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Software Technology Parks of India (STPI) scheme and Special Economic Zones in Bangalore and Hyderabad concentrate delivery capacity for North American and European clients. These tax-advantaged zones host engineering density that supports continuous validation cycles across time zones.
United States
Fortune 500 enterprises in financial services and retail drive premium demand for embedded testing partnerships. FCC requirements for mobile payment security and data transmission standards shape procurement specifications. Silicon Valley and New York Metro clusters anchor cloud-native testing lab investments from Accenture PLC and IBM Corporation.
Germany
Automotive OEMs and industrial conglomerates require validation for connected vehicle infotainment systems and Industry 4.0 mobile interfaces. CE marking and GDPR compliance mandates from ECHA and EU AI Act provisions elevate security testing scope. Munich and Stuttgart engineering centers concentrate specialized digital platform expertise.
India
Offshore delivery centers in Bangalore and Hyderabad execute 24-hour validation cycles for global fintech and retail clients. BIS standards and TRAI data localization guidelines govern test infrastructure architecture. Telangana's IT corridor and Karnataka's Electronics City host the deepest automation engineering talent pools.
United Kingdom
London-based financial services firms under FCA supervision procure algorithmic transparency validation for AI-driven mobile applications. GDPR and emerging UK AI regulation post-Brexit create compliance complexity. The Thames Valley corridor sustains delivery partnerships with Indian offshore centers.
Japan
Consumer electronics manufacturers and mobile carriers demand rigorous quality assurance for domestic market releases. METI guidelines on data security and PMDA-aligned protocols for health-adjacent applications shape testing scope. Tokyo and Osaka metropolitan areas concentrate specialized localization testing capacity.
Mobile Application Testing Services (MATS) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform-integrated providers commanding enterprise accounts while boutique firms capture niche security mandates. The vendor base concentrates around three tiers: global consultancies with cloud-native infrastructure, India-based delivery specialists with scale advantages, and digital engineering boutiques with vertical expertise. Strategic moves center on embedded delivery model expansion and AI-driven tooling acquisitions that compress script maintenance economics.
Among global consultancies, Accenture PLC and IBM Corporation exemplify platform-integrated positioning through cloud-native testing labs and multi-year enterprise partnerships. Cognizant Technology Solutions Corporation occupies a scale-driven position rooted in India-based engineering density. EPAM Systems Inc. represents specialized digital platform testing archetype serving retail and fintech verticals.
| Leading Market Players |
|---|
| Accenture PLC |
| Capgemini SE |
| Cognizant Technology Solutions Corporation |
| EPAM Systems Inc. |
| IBM Corporation |
| Wipro Ltd |
| Tata Consultancy Services Limited |
| Cigniti Technologies Ltd |
| Infosys Limited |
| Others |
Supply & Pricing Matrix
EU AI Act algorithmic transparency mandates gate qualified supply for premium-tier security validation contracts, as only providers with documented compliance protocols access European financial services procurement. This regulatory filter concentrates pricing power among firms with established GDPR-aligned delivery architectures, while compressing margins for commoditized functional testing tiers lacking certification differentiation.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid deployment commitments with premium positioning, while extended delivery windows trigger standard-tier discounts. The dominant structure stratifies across premium, standard, and economy tiers tied to compliance certification depth and automation maturity. Price differentiation hinges on GDPR audit trail completeness and ISO 27001 security certification status. Pricing pressure stems from open-source framework proliferation eroding licensed tool premiums. Mid-market enterprises exhibit highest price sensitivity; regulated financial services firms demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Logistics and freight costs for physical device farm replenishment exert persistent pressure on offshore delivery center economics. Supply concentrates in India, the United States, and Germany, with Bangalore and Hyderabad anchoring execution density. The chain draws from specialized automation engineering talent, cloud infrastructure provisioning, and OEM device procurement channels. Single-source vulnerability sits with concentrated device farm hardware sourcing from Asia-Pacific manufacturing clusters. Distribution runs through embedded delivery partnerships and multi-year platform agreements rather than transactional project structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning-based test generation is displacing script-heavy legacy validation pipelines, compressing delivery economics and restructuring competitive positioning around AI-native tooling investments.
For Market Incumbents: Deepen vertical integration into cloud-native testing infrastructure to defend margin position against AI-driven automation commoditization. Accenture PLC and Cognizant Technology Solutions Corporation anchor enterprise relationships through embedded delivery density; challengers threaten this position with self-healing script capabilities that reduce maintenance overhead. Priority levers include acquisition of specialized digital platform testing boutiques and expansion of Bangalore and Hyderabad delivery center automation engineering capacity. For New Entrants and Emerging Players: EU AI Act compliance mandates in Germany and France open a window for boutique security validation specialists targeting algorithmic transparency documentation gaps. White-space targets include 5G network condition simulation services and automotive infotainment convergence testing. The most penetrable segment comprises mid-tier fintechs in India seeking GDPR-aligned validation without incumbent overhead. Go-to-market positioning should emphasize fixed-price defect escape rate guarantees displacing time-and-material contracts. For Investors and Strategic Acquirers: Outcome-based pricing adoption in North American Fortune 500 procurement is the leading indicator that embedded delivery models are consolidating vendor relationships and extending contract tenures. Long-term viability favors platform-integrated providers with cloud-native infrastructure and multi-year partnership structures. Acquisition target archetype: digital engineering boutiques with vertical specialization in retail or fintech and demonstrated EU AI Act compliance documentation capabilities. Signal to monitor: enterprise procurement shift from project-based engagements to embedded DevOps team stationing.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Testing Platform Integration | Machine learning-based test generation reduces script maintenance overhead for retail and fintech QA teams. |
| Embedded Delivery Model Expansion | Multi-year platform partnerships with Fortune 500 enterprises displace discrete project-based engagements. |
| EU AI Act Compliance Documentation Pipeline | Specialized audit trail capabilities satisfy ECHA and European financial services regulator review requirements. |
| 5G Network Condition Simulation Capability | Latency and bandwidth variability testing addresses underdeveloped service portfolios for next-generation applications. |
| Automotive Infotainment Testing Specialization | Connected vehicle platform expertise applies mobile validation to embedded Android and proprietary OEM systems. |
Research Methodology
Document review covered SEC filings from Accenture PLC and Cognizant Technology Solutions Corporation, EU AI Act implementation guidance, and BIS standards documentation, complemented by interviews with CTOs at North American financial services enterprises, IT procurement officers at European retail conglomerates, platform engineers at India-based delivery centers, and integration specialists at cloud infrastructure providers. Secondary validation drew from TRAI data localization guidelines, GDPR enforcement case databases, and hyperscaler capex disclosures. Bottom-up service line revenue analysis and top-down market sizing triangulated volume estimates.
Cross-referencing historical automation adoption curves against panel input from delivery center executives shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology tier, deployment architecture, and end-user scale. CAGRs derived from regression against comparable software services expansion patterns, with specific inputs including cloud-distributed test grid penetration rates and AI-driven testing pilot deployment scaling timelines.
The model assumes a particular technology adoption path for machine learning-based test generation; alternative pathways for self-healing script maturity would alter the outlook for manual testing displacement velocity. Forecasts reflect assumptions regarding EU AI Act enforcement intensity and GDPR data localization friction evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
Global Business Card Software Market
Software & Services
Point Cloud Processing Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Global Custom Software Development Services Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
Global Document Management Software Market
Software & Services
Advanced Process Control Software Market
Software & Services
Period-Tracking Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Specification Management Software Market
Software & Services
Asia-Pacific Database Management Software Market
Software & Services
Europe HR Payroll Software Market
Software & Services
Taxi Booking Software Market
Software & Services
Performing Arts Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market