
 Skin Grafts Market | 2026-2036
Skin Grafts Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Grafts Market Intelligence
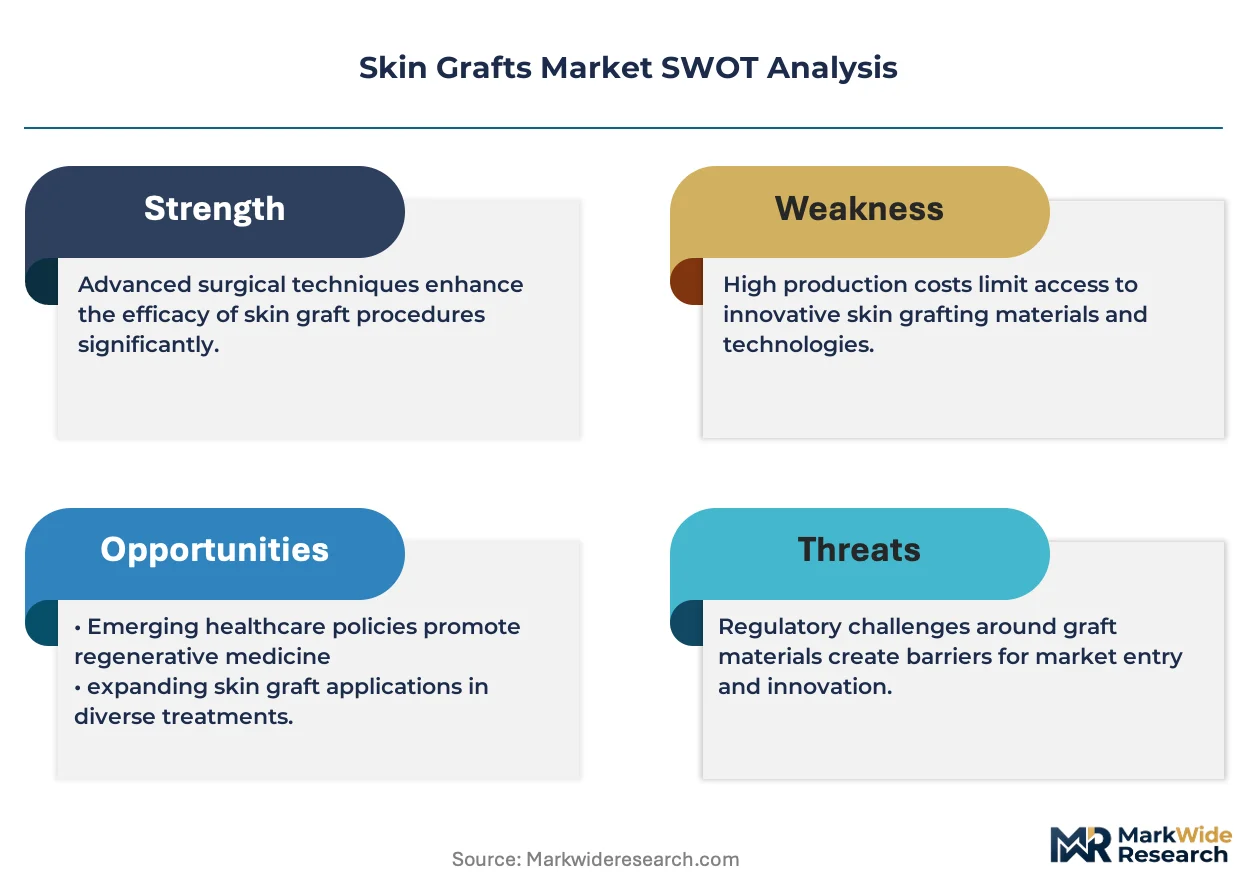
The European Union's Medical Device Regulation (MDR) is pivoting market access strategies by raising clinical data requirements for approval. This stringent framework increases development costs and timelines for all graft types. Integra LifeSciences leverages its extensive portfolio of regenerative medicine products to navigate these complex regulatory pathways. Smith & Nephew competes through its strong global distribution network, ensuring its advanced wound care products reach key hospital systems.
Skin grafts are segments of dermal and epidermal tissue used to repair defects from burns, trauma, or surgery. These biological or synthetic materials must facilitate revascularization and integrate with host tissue to ensure successful wound closure. Autografts remain a standard of care, but allografts and synthetic grafts are gaining share due to reduced donor site morbidity. The burn treatment application segment commands the largest portion of the market, driven by the critical need for immediate and effective wound coverage.
Regulatory bodies including the U.S. FDA, the European Medicines Agency (EMA), and Japan's PMDA enforce rigorous standards for skin graft products. These regulations mandate extensive clinical trials and quality control, especially for allografts and xenografts, to ensure patient safety and product efficacy. The fundamental strategic decision for providers will be balancing investment between advancing traditional biological grafts and developing next-generation synthetic alternatives.
Market Dynamics
The central tension in the skin grafts market is the competition between established autograft procedures and the rise of advanced bioengineered substitutes. This dynamic is shaped by clinical demands for reduced donor site morbidity and regulatory pressures for enhanced safety.
Growth Catalysts
- Biodegradable Polymers:Innovations in materials like polyglycolic acid are enabling the creation of synthetic scaffolds that promote tissue regeneration and then safely dissolve, reducing the need for secondary removal surgeries.
- Chronic Wound Incidence:An aging global population and rising diabetes prevalence are increasing the number of chronic wounds, such as diabetic foot ulcers, that require advanced skin graft interventions, particularly in North America.
- Burn Center Specialization:Dedicated burn treatment centers are consolidating demand for high-performance grafts, driving adoption of the most effective products to manage severe, large-area burns and improve survival rates.
Market Restraints
- High Product Costs:The significant expense associated with bioengineered skin substitutes and cellular therapies limits their accessibility, particularly in healthcare systems with constrained budgets or unfavorable reimbursement policies.
- Immunological Rejection:Allografts and xenografts carry an inherent risk of triggering an immune response from the host, which can lead to graft failure and necessitates immunosuppressive therapy for the patient.
- EU MDR Compliance:The European Union's Medical Device Regulation (MDR) imposes stringent clinical evidence requirements, significantly increasing the cost and timeline for bringing new graft products to the European market.
Strategic Opportunities
- Emerging Market Penetration:Improving healthcare infrastructure and rising disposable incomes in countries like Brazil and India present significant growth opportunities for skin graft manufacturers willing to navigate local regulatory systems like ANVISA.
- Antimicrobial Integration:There is a clear opportunity to develop grafts that incorporate antimicrobial agents, such as silver ions, to proactively combat infection in burn and trauma wounds, a major cause of graft failure.
- Reconstructive Surgery:The use of skin grafts in elective and reconstructive procedures, including post-cancer surgery and scar revision, represents an expanding application segment beyond acute trauma and burns.
Industry Challenges
- Specialized Skill Scarcity:A shortage of surgeons and nurses trained in the application and post-operative management of advanced bioengineered and synthetic grafts limits their adoption outside of major academic medical centers.
- Cold Chain Logistics:Maintaining the viability of cellular-based allografts and other biological products requires a complex and unbroken cold chain from manufacturing to the operating room, posing significant logistical hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Grafts Market |
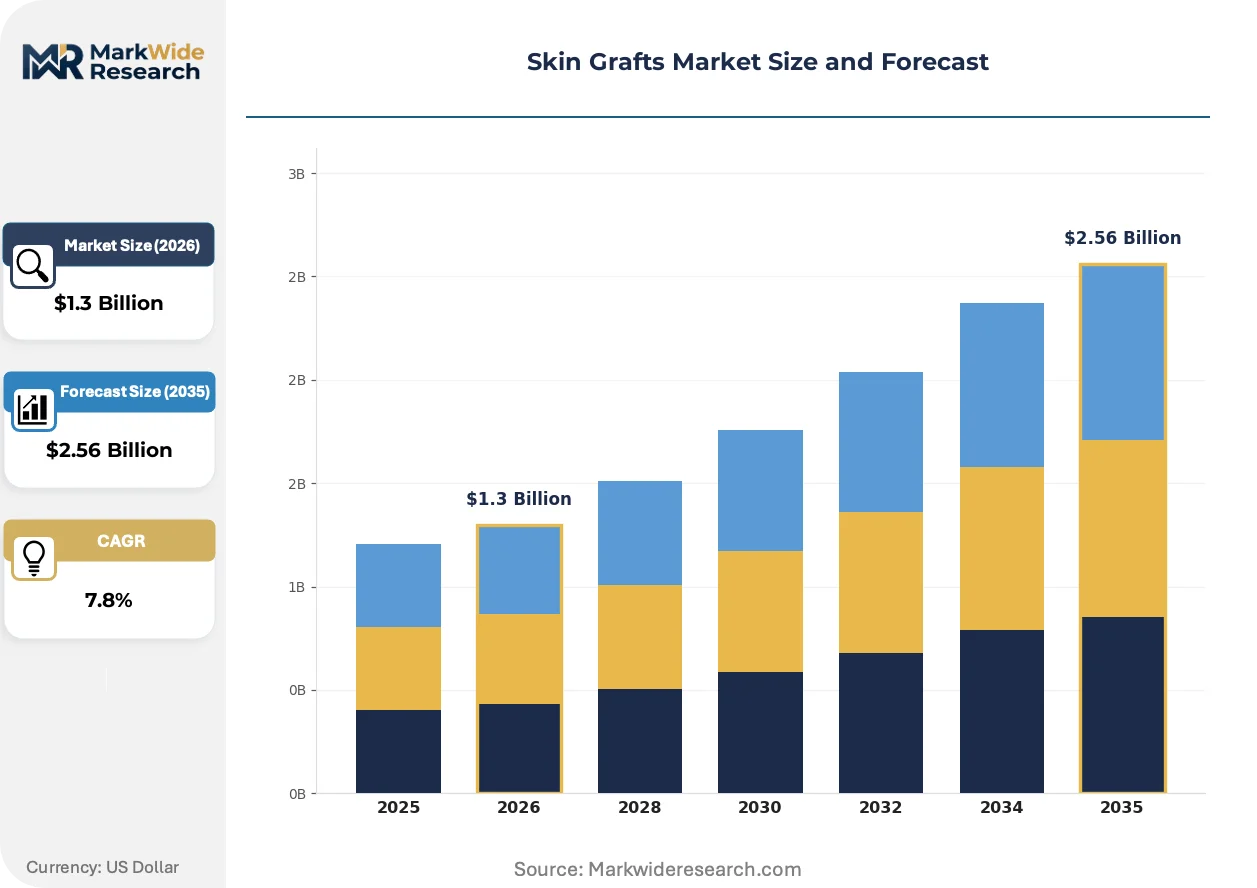
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.56 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autografts, Allografts, Xenografts, Synthetic Grafts Application: Burn Treatment, Surgical Wound Healing, Trauma Management, Cosmetic Surgery Material: Collagen, Biodegradable Polymers, Biological Membranes, Hydrogel End User: Hospitals, Clinics, Research Institutions, Home Care |
| Companies Covered | MTF Biologics, Integra LifeSciences, Zimmer Biomet, Kerecis, LifeNet Health, AlloSource, Smith & Nephew, AVITA Medical, MIMEDX Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Grafts Market Strategic Shifts & Innovations
The convergence of materials science and cell biology is transforming wound closure from a simple coverage procedure into a regenerative process. This evolution is driven by technological breakthroughs, evolving regulatory frameworks, and new hospital procurement models that prioritize long-term patient outcomes.
3D bioprinting technology allows for the layer-by-layer construction of patient-specific skin tissues using a patient's own cells. Specialized academic medical centers and regenerative medicine startups are pioneering its use for complex wound geometries. This advanced manufacturing method is integrating cellular material, structural scaffolds, and signaling molecules into a single, cohesive, and functional tissue replacement.
Japan's PMDA offers a conditional, time-limited approval pathway for regenerative medicine products that demonstrate probable benefit and safety. This policy significantly shortens the time-to-market for innovative cell-based skin substitutes compared to traditional routes. Consequently, developers of tissue-engineered products are increasingly targeting Japan for early commercialization and clinical data generation, a strategy that affects global development pipelines.
Value-based purchasing models are gaining traction within large hospital networks, especially in the United States. This approach evaluates skin grafts based on their ability to reduce total treatment costs by minimizing infection rates, revision surgeries, and length of stay. It displaces procurement decisions based solely on unit price, favoring grafts with robust clinical outcome data and proven efficacy.
Skin Grafts Market Segmentation
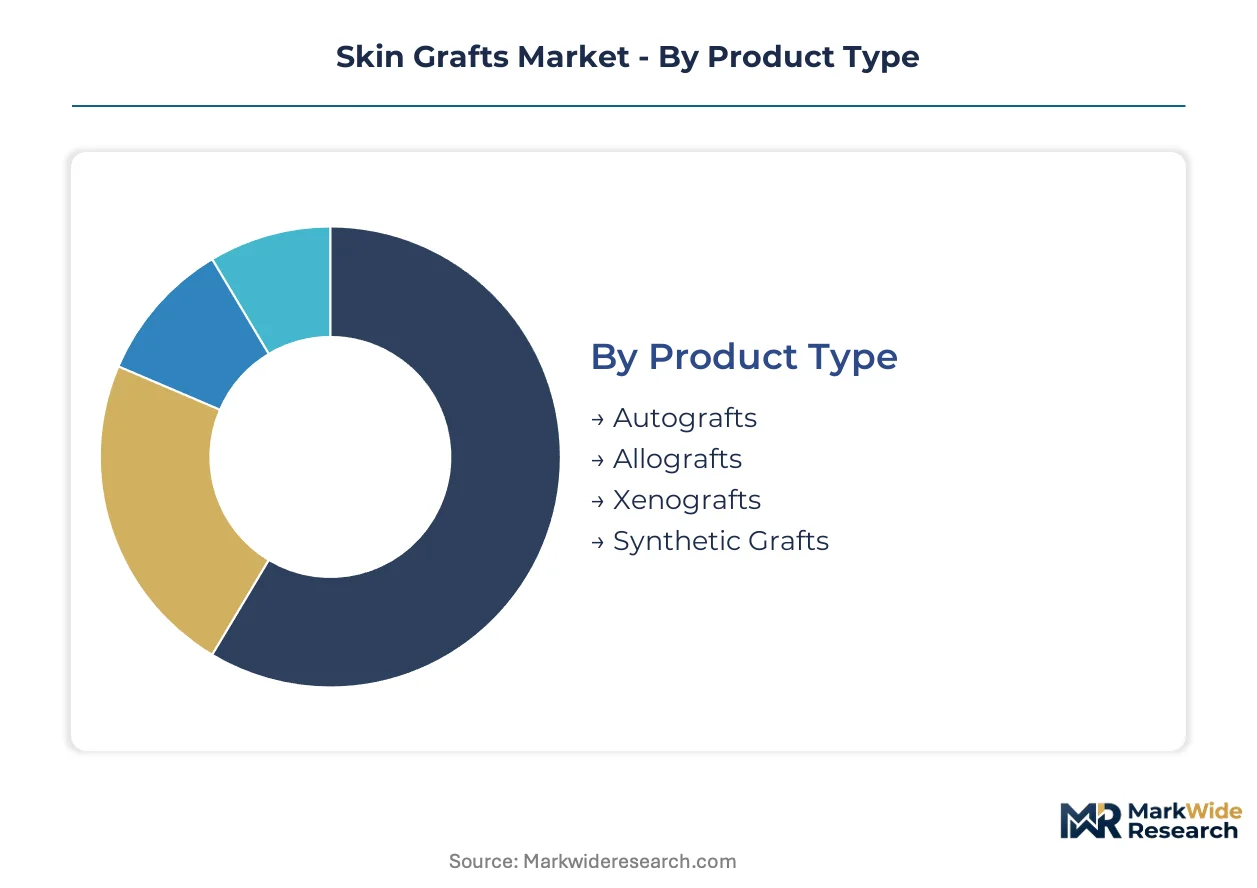
The skin grafts market segments reveal distinct dynamics driven by material innovation, clinical application needs, and regulatory oversight. Understanding these differentiations allows manufacturers to strategically allocate research and development resources and tailor market access strategies effectively.
Product Type:
The regulatory burden for skin graft products varies significantly by their biological origin and processing methods, impacting development timelines and market entry costs.
- Autografts:These grafts involve transplanting a patient's own skin, representing the gold standard due to zero risk of immune rejection. They require surgical harvesting from a healthy donor site on the same individual, primarily used in burn treatment centers across the United States.
- Synthetic Grafts:Engineered from biocompatible materials like biodegradable polymers, these grafts offer off-the-shelf availability and eliminate donor site morbidity. Innovations focus on promoting tissue regeneration without an immune response, driving demand in reconstructive surgery.
- Allografts:Derived from human donors, allografts provide temporary wound coverage but carry a risk of immune rejection, necessitating stringent screening and processing. Regulatory bodies like the U.S. FDA and European Medicines Agency (EMA) enforce strict safety and efficacy requirements.
- Xenografts:Sourced from animal tissue, primarily porcine, these grafts serve as biological dressings and require extensive processing to minimize immunogenicity. Japan's PMDA has specific guidelines for their preclinical evaluation.
Leading the category by volume: Autografts. Growing fastest: Synthetic Grafts.
Application:
Clinical utility and patient outcomes dictate the adoption patterns across various application segments, influencing product design and market focus.
- Burn Treatment:This segment commands the largest portion of the market, driven by the critical need for immediate and effective wound coverage for severe burns. Specialized burn centers globally, including those in Germany and Canada, prioritize high-performance grafts that facilitate rapid healing and reduce infection risk.
- Surgical Wound Healing:Grafts are essential for closing large or complex surgical defects, particularly after tumor excisions or debridement procedures. Demand is concentrated in advanced healthcare systems where complex surgeries are common, such as in the UK and Australia.
- Trauma Management:Skin grafts are vital for repairing extensive tissue damage resulting from accidents, military injuries, or other traumatic events. Rapid deployment and integration are critical factors for product selection in emergency and trauma centers.
- Cosmetic Surgery:Grafts find application in aesthetic procedures like scar revision, skin resurfacing, and reconstruction following cosmetic complications. Patient demand for minimal scarring and natural appearance drives innovation in this segment.
High-volume procedures center on Burn Treatment. Expanding clinical utility features Surgical Wound Healing.
Material:
Material innovation and biocompatibility are central to developing effective skin graft products, shaping their integration properties and patient safety profiles.
- Biodegradable Polymers:Materials such as polyglycolic acid and polylactic acid form scaffolds that support cell growth and then safely resorb into the body. These polymers are key to developing synthetic grafts that promote true tissue regeneration, particularly for chronic wounds in North America.
- Collagen:A fundamental component of natural skin, collagen-based grafts provide a biological matrix that supports cell adhesion and proliferation. These materials are widely used for their biocompatibility and ability to facilitate wound healing, especially in reconstructive surgery.
- Biological Membranes:These materials, often derived from amnion or other natural sources, offer a protective barrier and release growth factors to aid healing. They are increasingly used in specialized clinics for difficult-to-heal wounds.
- Hydrogel:Composed primarily of water, hydrogels provide a moist wound environment conducive to healing and can be loaded with therapeutic agents. Their flexibility makes them suitable for irregular wound surfaces.
Material science advancements drive Biodegradable Polymers. Established performance anchors Collagen.
End User:
The primary settings for skin graft application reflect the complexity of procedures and the level of specialized care required for patients.
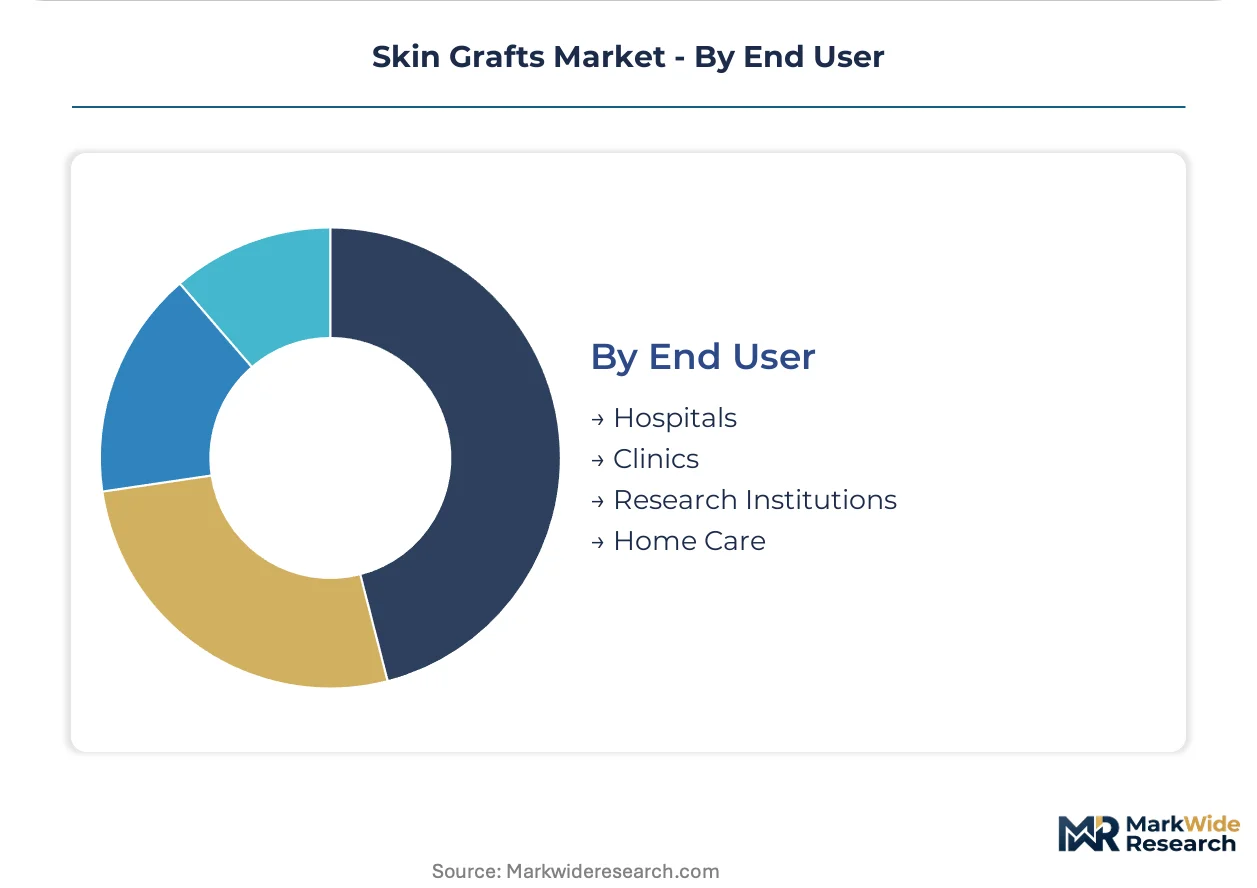
- Hospitals:These institutions represent the largest end-user segment due to their capacity for complex surgical procedures, specialized burn units, and critical care facilities. High procedural volumes across the United States and European Union drive significant demand.
- Clinics:Specialized wound care clinics and dermatology clinics utilize grafts for chronic wound management, minor surgical repairs, and cosmetic procedures. These facilities often focus on specific patient populations, such as those with diabetic foot ulcers.
- Research Institutions:Academic and private research laboratories are actively involved in developing next-generation skin graft technologies, including 3D bioprinting and cell-based therapies. Their procurement is focused on innovative materials for clinical trials and basic science.
- Home Care:While less common for initial graft application, home care settings increasingly manage post-operative graft sites and chronic wounds with advanced dressings. This segment relies on user-friendly and less invasive graft solutions.
Primary care delivery occurs in Hospitals. Emerging care models include Home Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's conditional approval pathway for regenerative medicine products acts as a specialized regulatory zone, accelerating the time-to-market for innovative cell-based skin substitutes. This policy significantly influences global development pipelines by attracting early commercialization efforts. Advanced healthcare infrastructure across key economies further shapes regional demand patterns.
United States
United States demand for skin grafts stems from its advanced healthcare infrastructure and high procedural volumes, particularly in burn treatment. The U.S. FDA enforces rigorous safety and efficacy requirements for allografts. Major academic medical centers in Boston and Houston drive research into next-generation synthetic grafts.
Germany
Germany's specialized burn centers and complex surgical procedures generate substantial demand for high-performance grafts. The European Union's Medical Device Regulation (MDR) imposes stringent clinical evidence requirements. Medical technology hubs in Munich and Berlin focus on developing advanced biodegradable polymer solutions.
Japan
Japan exhibits strong demand for innovative cell-based therapies and reconstructive surgery applications. Japan's PMDA offers a conditional, time-limited approval pathway for regenerative medicine products. Regenerative medicine startups in Tokyo and Osaka are pioneering clinical use of 3D bioprinting for complex wounds.
Brazil
Brazil's improving healthcare infrastructure and rising disposable incomes contribute to a growing need for advanced skin graft interventions. ANVISA navigates local regulatory systems, presenting significant growth opportunities. Medical device manufacturing clusters in São Paulo are expanding production of cost-effective synthetic graft alternatives.
Canada
Canada's demand for high-performance grafts stems from its specialized burn centers and advanced wound care needs. Health Canada enforces strict safety and efficacy standards for all medical devices. Research institutions in Toronto and Montreal are collaborating on integrating antimicrobial agents into graft materials.
Skin Grafts Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, shaping the skin grafts market structure. The market exhibits a tiered competitive environment, ranging from established medical device giants to innovative regenerative medicine startups. Strategic archetypes include large-scale manufacturers leveraging extensive portfolios and niche players focusing on advanced bioengineered solutions. Companies are pursuing strategic partnerships and portfolio diversification to enhance market presence.
Among established medical device companies, Integra LifeSciences represents a player with an extensive portfolio of regenerative medicine products, leveraging its expertise to navigate complex regulatory pathways. Smith & Nephew, a UK-based public limited company, occupies a position in advanced wound care through its strong global distribution network, ensuring product reach to key hospital systems. Zimmer Biomet, an Indiana-based corporation, exemplifies a broader medical technology company with a presence in various surgical solutions. These entities anchor different market segments, from specialized biological grafts to innovative synthetic alternatives.
| Leading Market Players |
|---|
| MTF Biologics |
| Integra LifeSciences |
| Zimmer Biomet |
| Kerecis |
| LifeNet Health |
| AlloSource |
| Smith & Nephew |
| AVITA Medical |
| MIMEDX Group |
| Others |
Cost & Logistics Intelligence
Value-based purchasing models in large hospital networks are shifting procurement focus from unit price to total treatment costs, compelling manufacturers to demonstrate long-term efficacy and justify premium pricing for advanced skin grafts. This demand-side shift directly influences investment in clinical data.
Pricing Analysis
Short lead times for readily available synthetic grafts command a premium over custom-ordered biological products that require extensive processing. The dominant pricing model remains per-unit transactional, influenced by product complexity and regulatory approval. Price differentiation stems from clinical outcome data and specialized material composition, such as biodegradable polymers. High product costs for bioengineered substitutes create pricing pressure, making clinics and emerging markets highly price-sensitive, while specialized burn centers prioritize efficacy over cost.
Supply Chain Analysis
Reverse logistics for expired or rejected allografts and xenografts presents complex disposal and return challenges due to biological material handling requirements. Geographic supply concentration for allografts centers on donor tissue banks in the United States and Europe, while synthetic graft manufacturing expands in Brazil and Germany. Raw material dependencies include specialized biodegradable polymers, collagen, and cellular materials for advanced substitutes. Cold chain logistics for cellular-based products create a significant structural risk, impacting distribution models that run through specialized hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The skin grafts market operates as a supply-constrained environment, primarily due to the scarcity of specialized manufacturing capabilities for advanced bioengineered substitutes. This capacity bottleneck props up pricing for innovative, high-performance graft solutions.
For Market Incumbents: Deploy targeted R&D investment into next-generation synthetic alternatives to counter the threat of donor site morbidity associated with autografts. Consolidate market share by leveraging extensive global distribution networks to reach specialized burn centers and hospital systems. Invest in advanced material science, such as biodegradable polymers, to reduce immunological rejection and improve patient outcomes, thereby reinforcing a value-based pricing strategy.
For New Entrants and Emerging Players: A price-point gap exists between premium bioengineered grafts and more accessible, cost-effective options, creating an entry opportunity. Target emerging markets like Brazil and India with cost-effective synthetic graft alternatives, leveraging local manufacturing clusters for market penetration. Focus on specific application segments, such as reconstructive surgery, where patient demand for minimal scarring offers a clear go-to-market angle with novel materials.
For Investors and Strategic Acquirers: The window for entry favors investors seeking long-term growth in regenerative medicine, with a 5-10 year viability horizon driven by technological advancements. Acquire niche players specializing in 3D bioprinting or antimicrobial integration to gain access to cutting-edge intellectual property. A key signal to watch is the acceleration of conditional regulatory approvals in regions like Japan, indicating market readiness for novel cell-based therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Data Generation | Strengthens product efficacy claims for value-based purchasing models. |
| Antimicrobial Agent Integration | Reduces graft failure rates, improving patient safety in burn treatment. |
| 3D Bioprinting R&D | Enables patient-specific tissue construction for complex wound geometries. |
| Emerging Market Expansion | Captures growth from improving healthcare infrastructure in Brazil. |
| Regulatory Pathway Optimization | Accelerates market access for innovative grafts in the European Union. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and academic literature underwrites the qualitative findings and quantitative projections of this study. Primary interviews with clinicians, hospital procurement managers, and regenerative medicine executives provided critical insights. Secondary validation drew from U.S. FDA submissions, EMA guidelines, and PMDA policies. This approach employed both bottom-up market sizing and top-down validation to ensure robust data integrity.
The rate-of-change decomposition framing informed the quantitative analysis, segmenting the market by product type, application, material, end user, and regional regulatory frameworks. Compound annual growth rates were derived from historical data trends and projected adoption rates of advanced synthetic grafts across the analysis window. Forecast inputs included chronic wound incidence rates and the prevalence of specialized burn treatment centers.
Inputs from regulatory body publications and company financial disclosures were available through the study window; gaps in early-stage clinical trial data introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and healthcare expenditure patterns. Practitioners should monitor shifts in reimbursement policies and new material science breakthroughs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Myasthenia Gravis Treatment Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Psittacosis Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Transplantation Market
Medical Treatment
Global Nano Therapy Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
Cytokine Release Syndrome Management Market