
 Refuse Truck Market | 2026-2036
Refuse Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Refuse Truck Market Insights
Municipal sanitation departments is bifurcating from private waste haulers as the dominant procurement force in refuse truck demand. Heil Environmental leverages its automated arm technology to anchor North American municipal contracts. McNeilus Truck and Manufacturing sustains its position through backward integration into chassis manufacturing. Dennis Eagle competes aggressively across European urban fleet renewals with compact electric configurations.
A refuse truck is a specialized heavy-duty vehicle engineered with hydraulic lifting mechanisms, compaction chambers achieving density ratios exceeding 800 kg per cubic meter, and reinforced steel bodies designed for repetitive loading cycles. Its primary commercial purpose is the mechanized collection, compression, and transport of solid waste from residential, commercial, and industrial sources to disposal or processing facilities. Side loader configurations now dominate municipal contracts where one-operator efficiency determines total cost of ownership, while electric fuel type segments absorb disproportionate R&D investment despite diesel retaining volume leadership in heavy-duty applications. Recycling application demand is maturing in developed markets whereas hazardous waste segments command premium pricing due to specialized containment engineering.
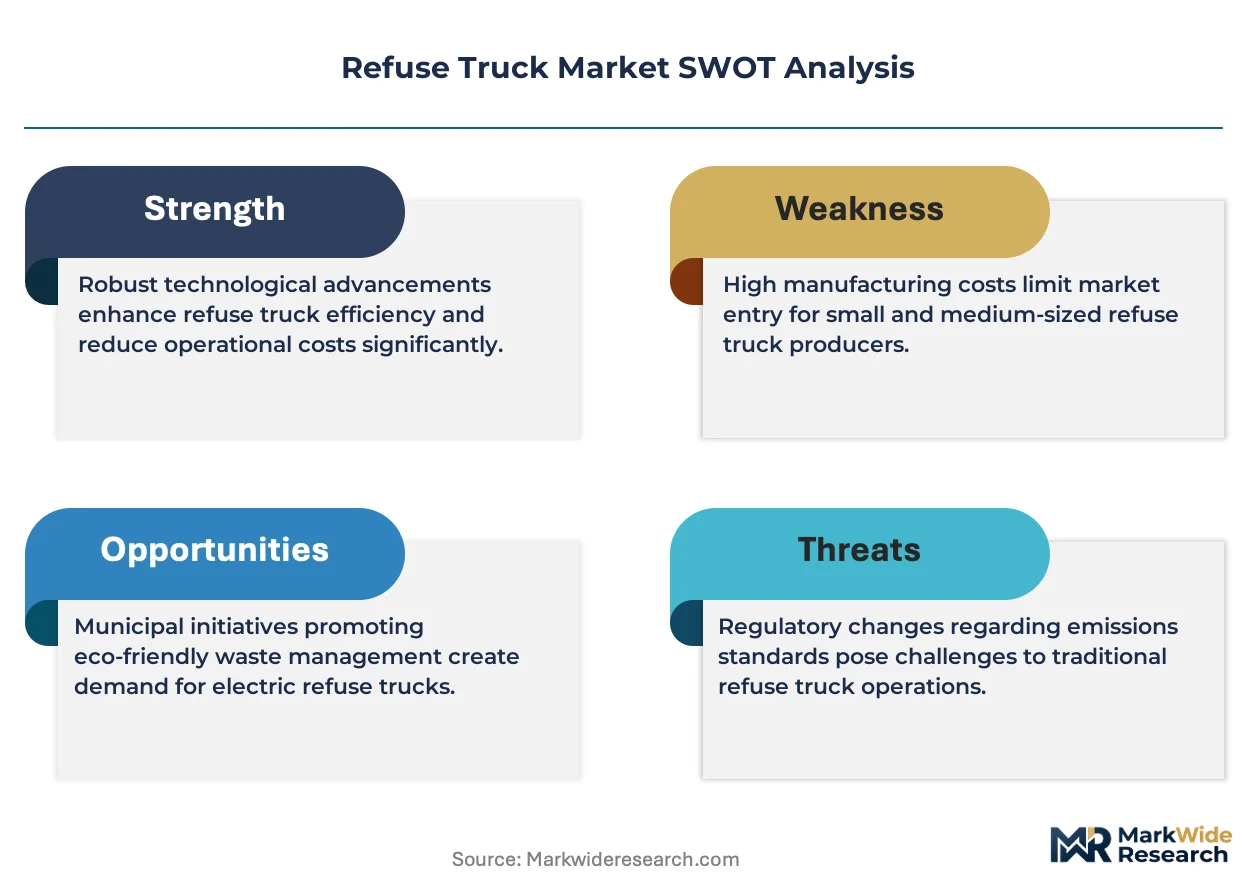
EPA Phase 3 greenhouse gas standards, California Air Resources Board zero-emission mandates, and EU F-Gas Regulation collectively reshape powertrain development timelines and market access conditions for diesel-dependent manufacturers. NHTSA brake and stability standards further constrain chassis modification protocols. Stakeholders must monitor battery energy density thresholds and charging infrastructure commitments before committing fleet electrification capital.
Market Dynamics
Electric powertrain adoption is bifurcating fleet procurement strategies as municipal operators confront California Air Resources Board mandates and EPA Phase 3 greenhouse gas standards while diesel-dependent haulers defer capital commitments.
Growth Catalysts
- Automated Side-Loader Technology:One-operator efficiency requirements from municipal sanitation departments are accelerating deployment of hydraulic arm systems that eliminate manual bin handling.
- EU F-Gas Regulation:Refrigerant containment standards for waste transport vehicles are compressing replacement cycles for aging diesel fleets across German and French urban contracts.
- Battery Energy Density Thresholds:Lithium-ion pack configurations achieving 300+ watt-hours per kilogram are enabling electric refuse trucks to match diesel range profiles on residential collection routes.
Market Restraints
- Chassis Supply Concentration:North American refuse body manufacturers remain dependent on Ford and Daimler chassis allocations, creating procurement bottlenecks during fleet renewal windows.
- Charging Infrastructure Gaps:Municipal depot electrification requires utility-scale grid upgrades that lag vehicle procurement timelines in mid-sized US cities.
- Steel and Hydraulics Input Volatility:High-strength steel plate and specialized hydraulic cylinder costs fluctuate with construction equipment demand cycles, compressing bodybuilder margins.
Strategic Opportunities
- India Urban Local Body Modernization:Smart Cities Mission funding is creating first-mover advantages for automated compaction technology in Delhi, Mumbai, and Bangalore municipal tenders.
- Hydrogen Fuel Cell Convergence:Proton exchange membrane stacks paired with battery buffers are emerging as range-extended alternatives for high-density commercial waste corridors.
- Extended Producer Responsibility Mandates:EU packaging waste directives are expanding separate collection fleet requirements beyond traditional municipal boundaries into retail and logistics operator domains.
Industry Challenges
- Electric Powertrain Technician Scarcity:High-voltage battery maintenance and motor controller diagnostics require skill sets absent from legacy diesel mechanic workforces.
- Homologation Timeline Compression:NHTSA brake and stability certification for modified electric chassis is extending delivery schedules beyond municipal budget cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refuse Truck Market |
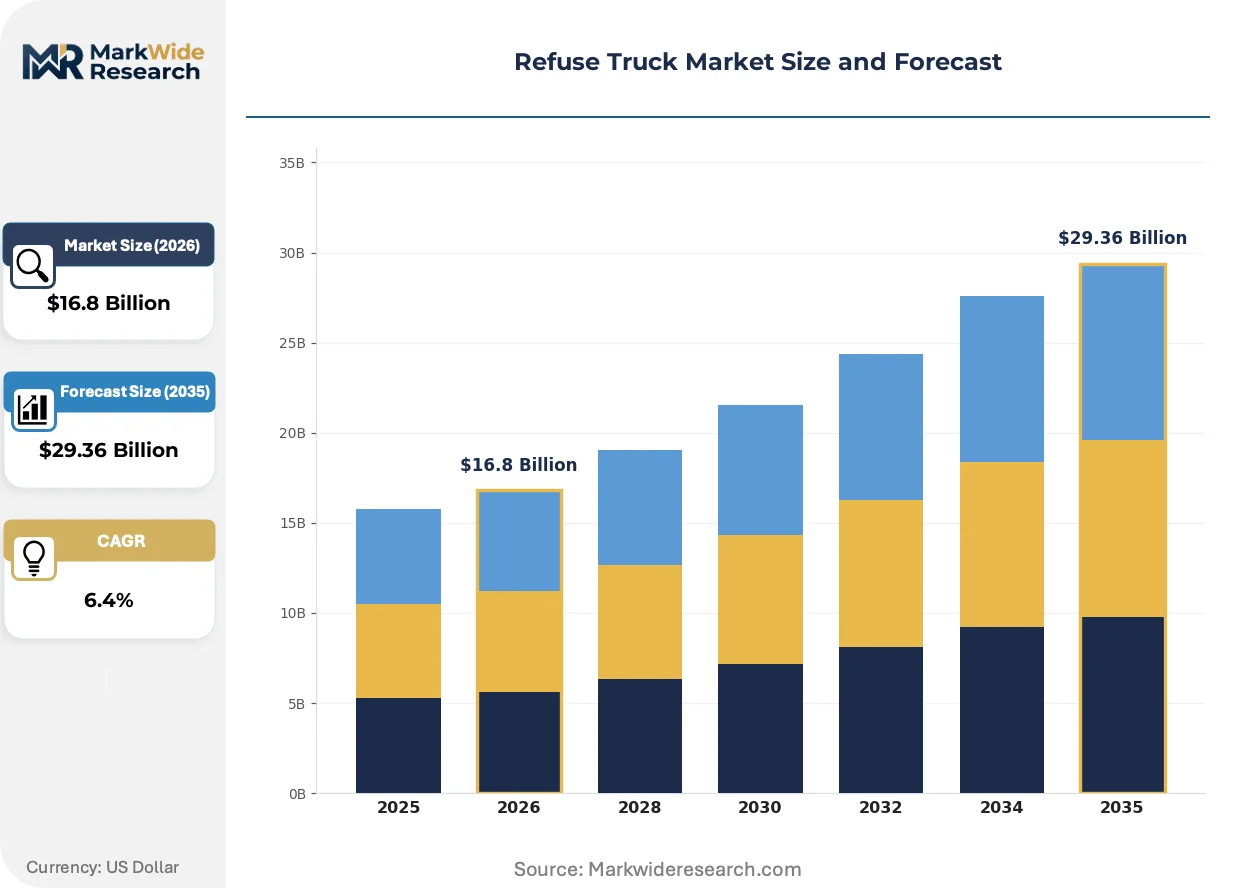
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Side Loader, Rear Loader, Front Loader, Automated Application: Municipal Waste, Construction Debris, Recycling, Hazardous Waste Size: Compact, Mid-Size, Full-Size, Heavy-Duty Fuel Type: Diesel, Electric, Hybrid, CNG |
| Companies Covered | Heil Environmental, McNeilus Truck and Manufacturing, New Way Trucks, Labrie Enviroquip Group, Autocar LLC, Kirchhoff Group, FAUN Umwelttechnik, Dennis Eagle, Fujian Longma Environmental Sanitation Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refuse Truck Market Trends and Innovations
Powertrain electrification is compressing product development cycles while automated collection mechanisms and connected fleet management systems reshape operator economics and maintenance protocols.
Electric refuse truck architectures are bifurcating between purpose-built battery-electric chassis and diesel-electric retrofit platforms. Municipal operators in California and Germany are prioritizing ground-up designs for route efficiency optimization. This technology divergence is forcing body manufacturers to engineer dual mounting systems and control interfaces, fragmenting R&D allocation across incompatible electrical architectures.
California Air Resources Board zero-emission mandates are prohibiting diesel refuse truck sales in 2035, compressing manufacturer transition timelines. The regulation is accelerating joint ventures between chassis suppliers and battery pack integrators. Heavy-duty electric configurations face the steepest compliance burden, as range and payload requirements exceed current energy density thresholds.
Lifecycle service contracting is displacing traditional equipment ownership models among private waste haulers. Fleet operators in Texas and Florida are unbundling maintenance from capital expenditure, pressuring manufacturers to establish captive service networks. This financing shift concentrates purchasing power with national account managers and erodes regional dealer influence over specification decisions.
Refuse Truck Market Segmentation
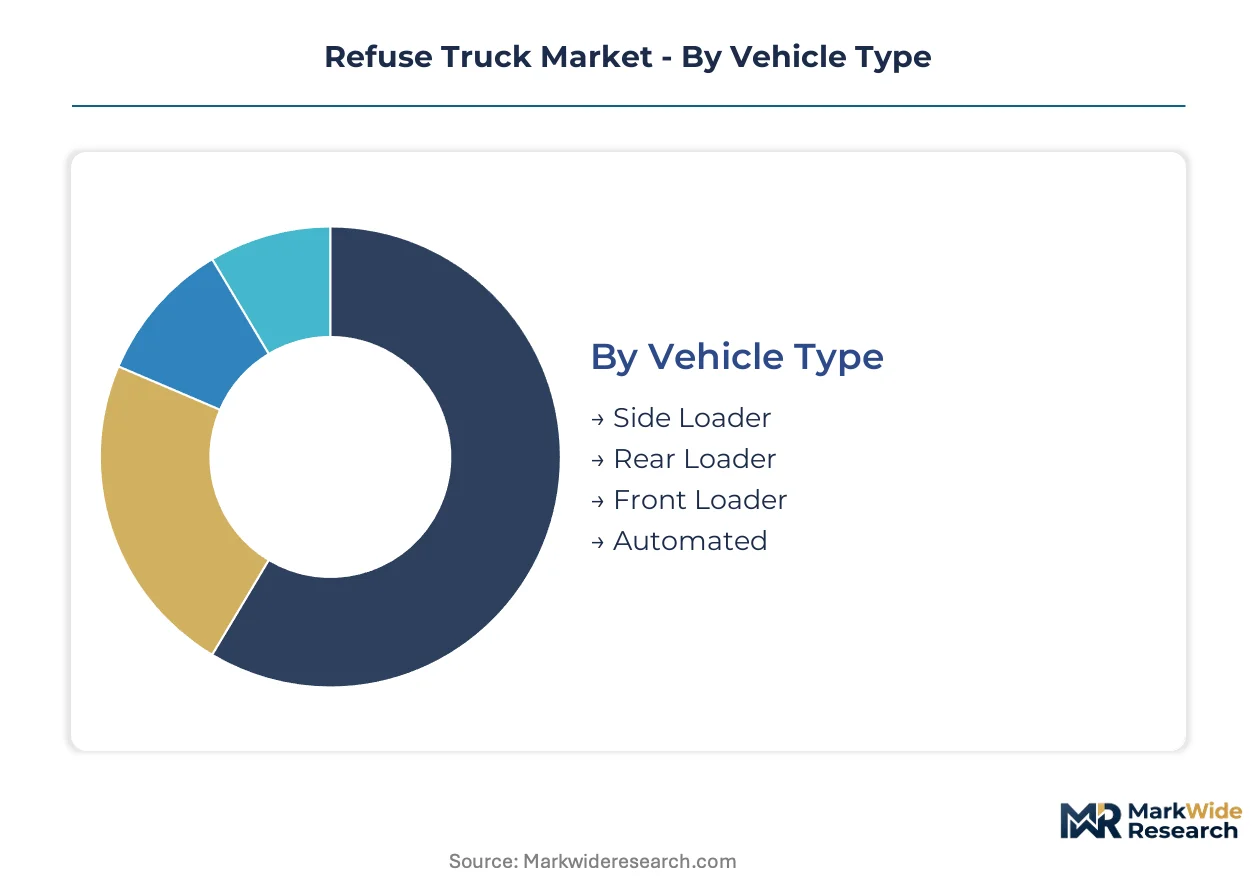
Refuse truck procurement channels diverge sharply between municipal fleet operators and private waste contractors, with each segment demanding distinct specifications, financing structures, and service commitments. Understanding how vehicle configurations, fuel technologies, and size classes map to these channel economics determines manufacturer positioning and margin capture.
Vehicle Type:
Channel economics favor side-loader and automated configurations for municipal contracts where one-operator efficiency drives total cost of ownership calculations, while rear-loader units dominate private hauler procurement through lower upfront capital requirements.
- Side Loader:Hydraulic arm mechanisms enable single-operator collection from curb-aligned containers, eliminating manual bin handling. Municipal sanitation departments in Germany and California concentrate procurement here as labor costs escalate and union staffing ratios tighten.
- Automated:Fully autonomous lifting and compaction systems integrate with RFID container tracking and route optimization software. This configuration commands premium pricing in dense urban contracts where route density exceeds 800 stops per day.
- Rear Loader:Traditional hopper-fed designs with manual or semi-automated loading persist in private waste hauler fleets and smaller municipal operations.
- Front Loader:Heavy-duty arm systems service commercial dumpsters and industrial containers, anchoring construction debris and commercial waste contracts.
By volume, rear-loader configurations lead due to legacy fleet penetration. By growth pace, automated systems are expanding most quickly as municipal operators confront staffing constraints.
Application:
Cost tier stratification separates commodity municipal waste collection from premium-priced hazardous waste containment, with recycling applications occupying a mid-tier position shaped by extended producer responsibility mandates.
- Municipal Waste:Residential and light commercial collection routes constitute the baseline application, with procurement dominated by city sanitation departments operating on annual budget cycles. EPA emissions compliance and California Air Resources Board zero-emission mandates are compressing replacement timelines for aging diesel fleets.
- Hazardous Waste:Specialized containment engineering with sealed compartments, vapor recovery systems, and DOT-certified pressure vessels commands substantial price premiums. Industrial generators and environmental remediation contractors drive demand in Texas, Louisiana, and German chemical corridor regions.
- Recycling:Multi-compartment body designs accommodate source-separated materials, with demand maturing in developed markets where landfill diversion targets tighten.
- Construction Debris:Reinforced steel bodies with abrasion-resistant liners handle dense, irregular materials, serving demolition contractors and roll-off container operators.
By volume, municipal waste collection dominates unit shipments. By margin contribution, hazardous waste applications are ahead due to engineering specialization and regulatory compliance barriers.
Size:
Geography determines size-class distribution, with compact configurations penetrating historic European city centers and heavy-duty units anchoring North American suburban sprawl and commercial corridors.
- Compact:Narrow-body designs with sub-2.5-meter width navigate medieval street networks and restricted access zones. Dennis Eagle and European specialists concentrate R&D here for Paris, Rome, and Amsterdam municipal renewals.
- Heavy-Duty:High-capacity compaction chambers exceeding 18 cubic meters serve commercial waste corridors and high-density residential towers. This segment absorbs disproportionate chassis engineering investment as electrification challenges mount for maximum payload configurations.
- Mid-Size:Versatile platforms bridge municipal and light commercial applications, offering route flexibility for mixed fleet operators.
- Full-Size:Standard residential collection configurations balance capacity with maneuverability across suburban and small urban environments.
By volume, full-size and mid-size platforms lead procurement tallies. By technology transition velocity, compact electric configurations are gaining share fastest as urban access restrictions proliferate.
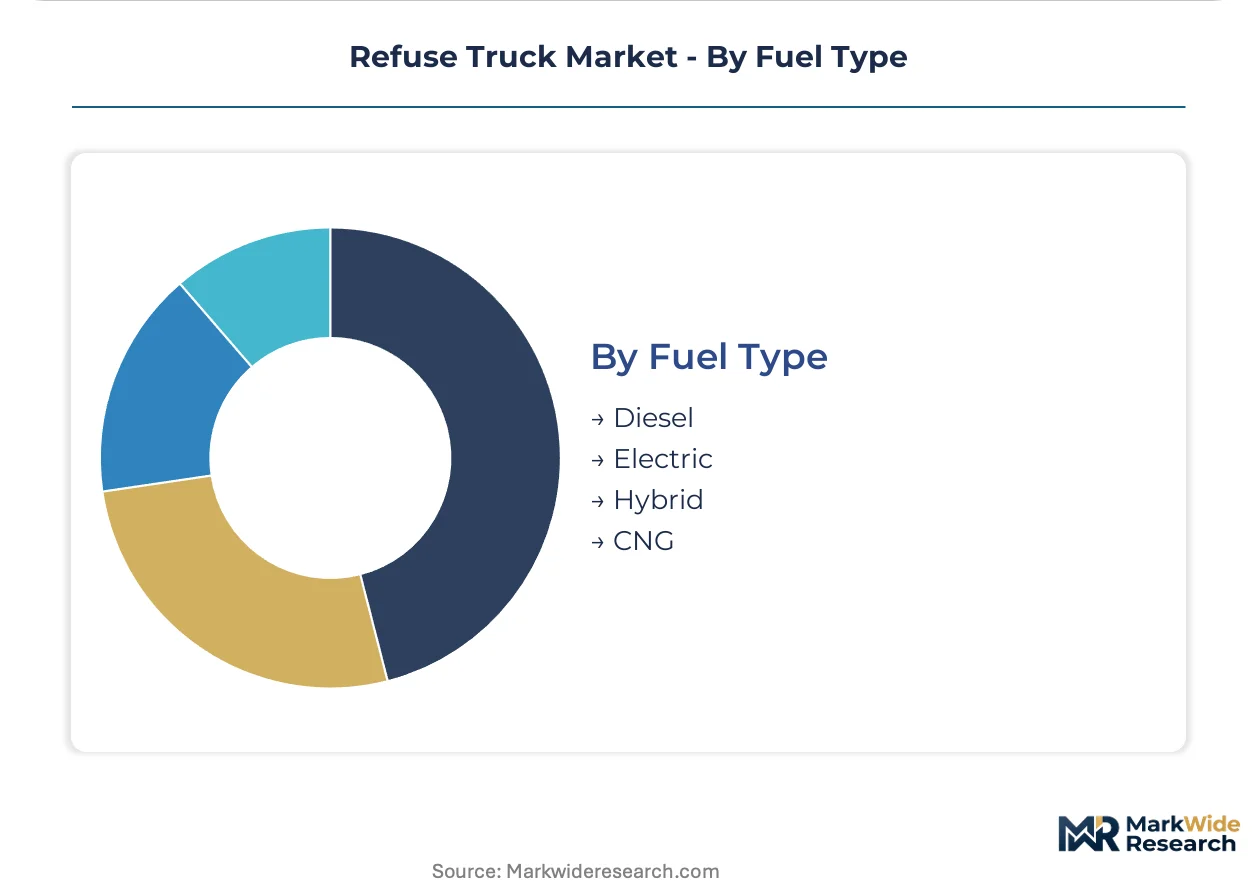
Fuel Type:
Customer type bifurcation separates municipal operators confronting regulatory mandates from private haulers deferring capital commitments, with electric and CNG segments capturing divergent procurement rationales.
- Electric:Battery-electric architectures with 300+ kWh pack configurations are achieving route parity with diesel on residential collection cycles. California Air Resources Board sales prohibitions and EU Green Deal funding are accelerating municipal adoption in Germany, Netherlands, and California cities.
- Diesel:Compression-ignition powertrains retain volume leadership in heavy-duty applications where energy density requirements exceed current battery thresholds. Private waste haulers in Texas, Florida, and Midwestern US states continue procurement as total cost of ownership calculations favor mature technology.
- Hybrid:Diesel-electric parallel architectures offer transitional compliance for operators navigating uncertain electrification timelines and charging infrastructure gaps.
- CNG:Compressed natural gas configurations serve operators with captive fueling infrastructure, particularly in regions with pipeline access and emissions pricing mechanisms.
By volume, diesel powertrains maintain leadership across heavy-duty and private hauler segments. By capital allocation intensity, electric fuel type is climbing the fastest as manufacturer R&D and joint venture activity concentrates on battery integration and thermal management systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German refuse truck manufacturers export automated side-loader systems to municipal operators across France, Netherlands, and Scandinavian markets, establishing a dominant trade corridor in European fleet modernization.
United States
Municipal sanitation departments in California and Texas are accelerating fleet electrification timelines as labor costs escalate. EPA Phase 3 greenhouse gas standards and California Air Resources Board zero-emission mandates compress replacement cycles for aging diesel vehicles. Los Angeles and San Francisco anchor West Coast procurement concentration for automated collection systems.
Germany
Urban fleet operators prioritize compact electric configurations for historic city center access. EU F-Gas Regulation refrigerant standards and EU Green Deal funding mechanisms reshape municipal tender specifications. Berlin and Hamburg municipal authorities lead contract awards for narrow-body automated side-loaders.
China
Urban Local Body modernization programs in megacities drive first-mover procurement of automated compaction technology. National dual carbon goals and MIIT new energy vehicle mandates accelerate electric chassis integration. Shanghai and Beijing municipal clusters concentrate domestic manufacturer deployment.
India
Smart Cities Mission funding creates tender opportunities for automated collection systems in Delhi, Mumbai, and Bangalore. Central Pollution Control Board emission norms and BIS vehicle certification standards tighten fleet replacement criteria. Municipal corporations in Maharashtra and Karnataka states lead contract issuance.
France
Extended Producer Responsibility mandates expand separate collection fleet requirements beyond traditional municipal boundaries. ANSM waste transport regulations and EU packaging waste directives reshape operator procurement scope. Paris and Lyon urban authorities anchor automated side-loader deployment in dense residential corridors.
Refuse Truck Market Competitive Landscape
Listed leaders compete with private specialists across chassis-body integration capabilities, creating a tiered structure where scale advantages concentrate with diversified industrial conglomerates while regional fabricators retain municipal contract proximity. The vendor base separates into three strategic archetypes: integrated chassis-body manufacturers, specialized bodybuilders dependent on third-party chassis, and municipal-service captive operators. Dominant competitive moves include backward integration into chassis manufacturing and joint venture formations with battery pack integrators to secure electric powertrain supply.
Among North American integrated manufacturers, Heil Environmental and McNeilus Truck and Manufacturing exemplify the chassis-control archetype, while Dennis Eagle represents European compact-configuration specialization. These three companies anchor distinct competitive positioning vectors—Heil through automated arm technology, McNeilus through captive chassis supply, and Dennis Eagle through narrow-body electric architectures—each occupying a defensible tier in diverging procurement channel economics.
| Leading Market Players |
|---|
| Heil Environmental |
| McNeilus Truck and Manufacturing |
| New Way Trucks |
| Labrie Enviroquip Group |
| Autocar LLC |
| Kirchhoff Group |
| FAUN Umwelttechnik |
| Dennis Eagle |
| Fujian Longma Environmental Sanitation Equipment |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion battery pack substitution for diesel powertrains is redrawing supply geography toward Chinese and South Korean cell manufacturers while compressing upfront pricing premiums for municipal fleet operators negotiating total cost of ownership contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ground-up electric chassis from diesel-electric retrofits and legacy diesel configurations. Price differentiation hinges on battery energy density certification tiers and after-sales service bundling intensity. Cost compression in standard-tier diesel units is intensifying because private waste haulers in Texas and Florida defer electrification capital commitments. Municipal sanitation departments exhibit lowest price sensitivity due to CARB mandate compliance deadlines, while independent regional haulers anchor economy-tier procurement.
Supply Chain Analysis
Strategic stockpile preferences dominate chassis procurement as municipal fleet operators secure Ford and Daimler allocations ahead of electrification transition windows. Geographic supply concentration centers on Germany for compact automated body systems, the United States for heavy-duty chassis integration, and China for battery cell and electric drive module production. Raw material dependencies draw from high-strength steel plate, specialized hydraulic cylinders, and lithium carbonate. Single-source vulnerability in North American chassis allocations creates procurement bottlenecks during fleet renewal cycles. Distribution runs through municipal procurement departments and national account managers for private hauler fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lifecycle service contracting layers expand faster than hardware shipments as private waste haulers in Texas and Florida unbundle maintenance from capital expenditure, creating recurring revenue pools that outpace unit sales growth.
For Market Incumbents: Fortify captive chassis supply through backward integration into Ford and Daimler allocation agreements to defend against electric powertrain joint ventures disrupting traditional bodybuilder economics. Deepen aftermarket service network density in California and Germany where CARB and EU Green Deal mandates compress replacement cycles and lock in multi-year maintenance contracts. For New Entrants and Emerging Players: Aftermarket high-voltage technician training gaps where incumbents under-serve create entry points for specialized service providers targeting municipal fleets confronting electric powertrain maintenance skill shortages. Penetrate mid-sized US cities with depot electrification lagging vehicle procurement timelines, offering bundled charging infrastructure and fleet management software alongside automated collection units. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional bodybuilders holding municipal contract proximity but lacking electric chassis integration capabilities, presenting consolidation targets for diversified industrial platforms. Watch battery energy density threshold announcements from South Korean and Chinese cell manufacturers as the inflection signal determining electric refuse truck route parity viability and fleet electrification capital commitment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Chassis-Body Joint Venture Formation | Secures battery pack supply from CATL and LG Energy Solution for CARB-compliant municipal tenders. |
| Automated Arm Technology Licensing | Heil Environmental's hydraulic system IP transfers to European compact-configuration specialists. |
| Lifecycle Service Contract Expansion | Captures recurring revenue from Texas and Florida private haulers unbundling maintenance spend. |
| Depot Electrification Partnership | Utility-scale grid upgrades in mid-sized US cities unlock fleet procurement bottlenecks. |
| Hydrogen Fuel Cell Pilot Deployment | Proton exchange membrane stacks extend range for high-density commercial waste corridors. |
Research Methodology
Operator-level perspectives from municipal fleet managers, private waste hauler procurement directors, chassis manufacturing engineers, and aftermarket service technicians anchored the qualitative base. Primary interview data combined with secondary validation from EPA emissions filings, CARB regulatory dockets, EU F-Gas Regulation implementation reports, and municipal tender databases. Bottom-up unit shipment tallies by configuration and fuel type triangulated against top-down fleet replacement cycle analysis across the projection horizon.
Sensitivity analysis tested forecast outputs against battery cost decline trajectories, steel price volatility scenarios, and regulatory mandate acceleration possibilities. Segmentation dimensions modeled include vehicle type, application, size class, fuel technology, and procurement channel economics. CAGRs derived from replacement cycle velocity analysis and electrification penetration curves. Industry-specific inputs incorporated chassis allocation lead times and municipal budget cycle alignment.
Forecasts assume regulatory continuity in CARB zero-emission mandates, EPA Phase 3 greenhouse gas standards, and EU Green Deal funding mechanisms; material policy shifts would require re-modeling. Revision becomes warranted when battery energy density thresholds for heavy-duty configurations cross commercial viability thresholds or chassis supply concentration triggers sustained allocation rationing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Full-Service Carrier Market
Transportation Services
Ship Management Software Market
Transportation Services
India Taxi Market
Transportation Services
MUV Rental Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Global Taxi Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
Bike Rental Market
Transportation Services
Driving Vacation Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Drayage Services Market