
 Driving Vacation Market | 2026-2036
Driving Vacation Market Size, Share, and Industry Trends Forecast 2026-2036
Driving Vacation Market Foresight
Solo traveler bookings is restructuring demand patterns across the driving vacation landscape, pulling operators toward modular, self-guided itineraries. Black Tomato leverages its expertise in hyper-personalized routing to capture this shift, while roadsurfer anchors its growth in camper van fleet expansion across European pickup points. Audley Travel differentiates through curated self-drive programs that blend independent vehicle travel with pre-vetted accommodation networks.
A driving vacation denotes a leisure journey where travelers use personal or rented vehicles—cars, RVs, motorhomes, or vans—to traverse predetermined routes, typically spanning multiple days and incorporating stops at scenic, cultural, or recreational sites; the core technical parameter involves route optimization balancing drive time with experiential density. Road trips and scenic drives dominate current revenue pools due to lower capital requirements and broader demographic accessibility, while RV and motorhome segments command premium pricing through integrated lodging functionality. National parks and coastal routes attract the highest repeat visitation rates, creating concentrated demand corridors that shape regional infrastructure investment.
FAA regulations govern aerial tour integrations with ground-based driving routes in the United States, while EPA emissions standards influence fleet composition for rental operators. ESG disclosure requirements under CSRD pressure European operators to document carbon intensity per kilometer traveled. Stakeholders must monitor charging infrastructure buildout timelines and carbon accounting mandates to align fleet and route strategies with evolving compliance thresholds.
Market Dynamics
Remote work permanence and electric vehicle charging infrastructure buildout are restructuring route selection and trip duration patterns across the driving vacation landscape, compressing traditional seasonal booking windows into year-round demand.
Growth Catalysts
- Charging Infrastructure Expansion:Federal and state-level EV corridor investments in the United States are eliminating range anxiety along coastal and mountain routes, unlocking new multi-day itineraries previously constrained by battery limitations.
- CSRD Carbon Disclosure Mandates:European fleet operators face documented emissions reporting requirements per kilometer traveled, accelerating fleet electrification and route optimization investments that reduce operational carbon intensity.
- Adventure Tourism Segment Growth:Solo travelers and experience-seeking demographics are pulling operators toward modular, self-guided product architectures with flexible pickup and drop-off nodes.
Market Restraints
- Vehicle Acquisition Cost Inflation:Camper van and RV manufacturing input costs, particularly lithium battery packs and semiconductor-dependent control systems, constrain fleet expansion timelines for rental operators.
- Permitting Bottlenecks:National park corridor access permits and overnight parking regulations in high-demand coastal zones create supply rigidities that limit route capacity expansion.
- Substitution by Rail and Low-Cost Aviation:European high-speed rail network extensions and intra-continental budget carriers capture price-sensitive leisure travelers on overlapping origin-destination pairs.
Strategic Opportunities
- Norwegian Fjord Circuit Development:Underdeveloped EV charging density along Norway's western fjord routes presents first-mover positioning for integrated lodging-charging station networks.
- Telematics-Enabled Usage-Based Insurance:Convergence of connected vehicle data streams with parametric insurance products creates new revenue layers for fleet operators managing driver behavior risk.
- Australia's Remote Work Visa Programs:Extended-stay visa categories targeting digital nomads generate demand for month-long vehicle-based itineraries connecting outback destinations with coastal coworking hubs.
Industry Challenges
- Route Optimization Talent Scarcity:Fleet operators struggle to hire data scientists capable of balancing drive-time algorithms with experiential density metrics across fragmented geographic databases.
- Cross-Border Compliance Complexity:Multi-country European itineraries require navigation of divergent emissions zones, toll systems, and camping regulations that increase operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driving Vacation Market |
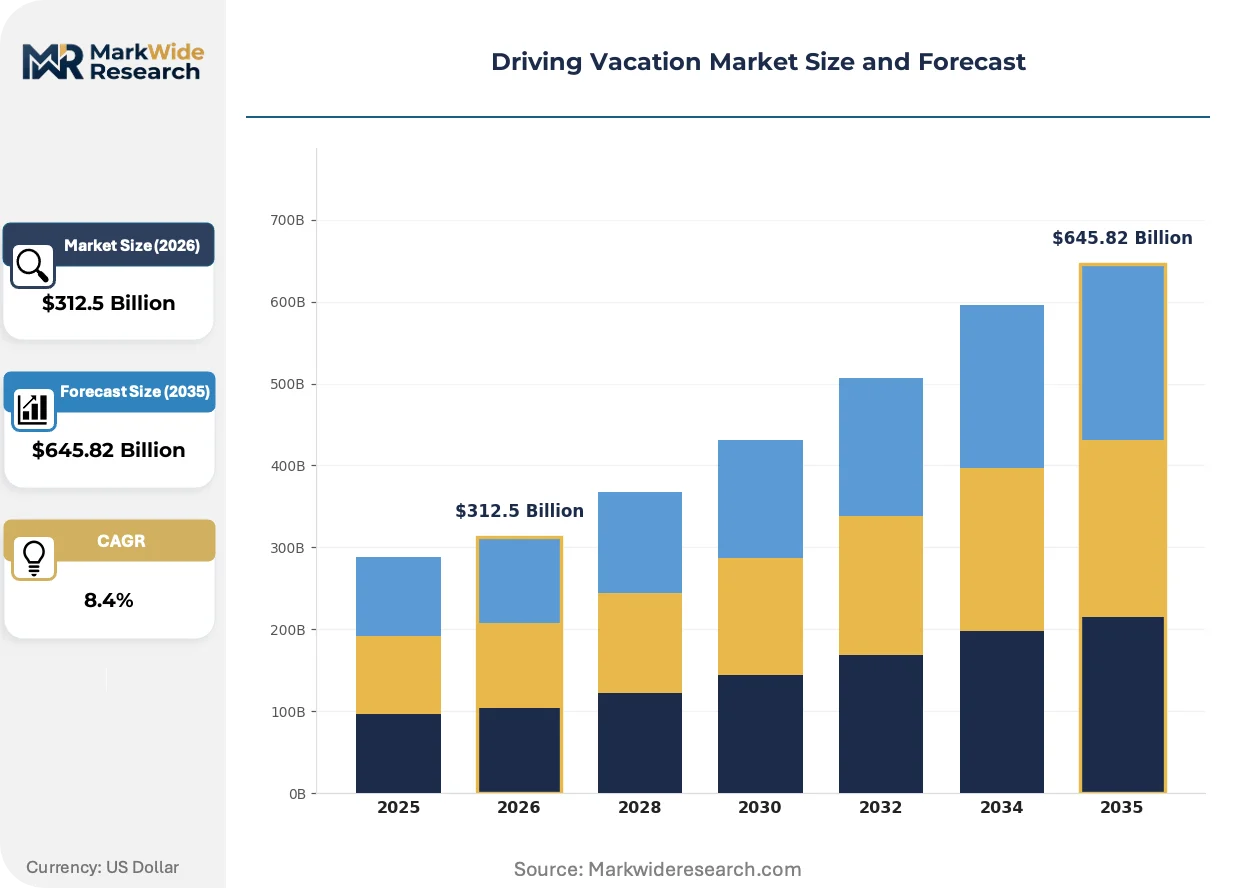
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $645.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Travel Type: Road Trips, Scenic Drives, Family Getaways, Weekend Escapes Vehicle Type: Cars, RVs, Motorhomes, Vans Destination Type: National Parks, Coastal Routes, Historical Sites, Urban Destinations Customer Segment: Families, Couples, Solo Travelers, Adventure Seekers |
| Companies Covered | Black Tomato, Untamed Travelling, Audley Travel, roadsurfer, HunterMoss, Scott Dunn, All Roads North, Crush Global, WEXAS Travel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driving Vacation Market Shifts & Advancements
Vehicle powertrain transformation and digital itinerary platforms are compressing the gap between transportation and lodging, creating integrated mobility-accommodation products that redefine trip economics.
Battery-electric camper vans with integrated solar charging and bidirectional power capability are electrifying the product architecture of self-drive vacations. Adventure-seeking demographics and remote work professionals are adopting these vehicles at accelerating rates, particularly along United States national park corridors. This technology is electrifying revenue model possibilities by enabling off-grid camping without generator dependency, extending viable stopover locations beyond established campground infrastructure.
The European Union's Corporate Sustainability Reporting Directive imposes granular carbon intensity disclosure obligations on fleet operators documenting emissions per passenger-kilometer. This regulatory pressure forces capital reallocation toward zero-emission vehicle procurement and route optimization software investments. Premium self-drive program providers face the steepest compliance cost gradients, driving consolidation among mid-sized European operators unable to absorb disclosure infrastructure investments.
Subscription-based vehicle access models are displacing traditional per-rental transactions in urban departure markets. Younger demographics in United States coastal metros and Australian capital cities favor monthly membership structures providing flexible vehicle swaps across van classes and geographic pickup networks. This behavioral shift concentrates booking platform power with integrated providers offering nationwide fleet access rather than regional specialists.
Driving Vacation Market Segmentation
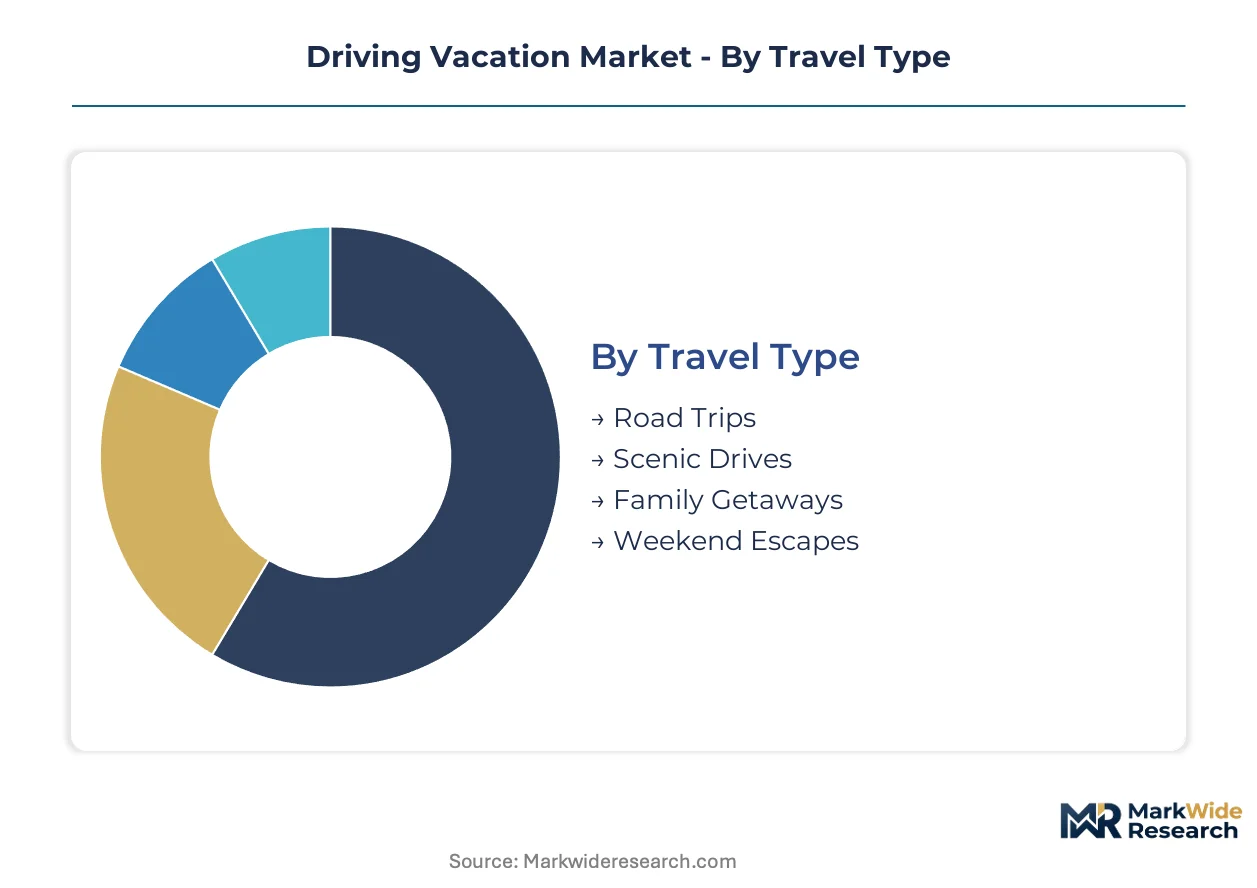
Segmentation in the driving vacation market reveals how capital deployment, vehicle specifications, and traveler psychographics create distinct profit pools. Operators must align fleet composition and route packaging with the technical requirements and booking behaviors of each slice.
Travel Type:
Capital intensity varies sharply across travel type segments, with multi-day road trips demanding the highest upfront investment in vehicle fleets and accommodation partnerships while weekend escapes minimize fixed asset exposure.
- Road Trips:Multi-day itineraries spanning hundreds of kilometers require integrated vehicle-lodging packages and route optimization software. Demand concentrates along United States coastal corridors and Australian outback circuits, where extended vehicle rentals generate recurring revenue through fuel partnerships and campground commissions.
- Scenic Drives:Single-day or short-loop experiences prioritize vehicle accessibility over overnight infrastructure. Norway's fjord routes and California's Pacific Coast Highway anchor demand, with electric vehicle charging density now determining viable route extensions.
- Family Getaways:Mid-duration trips balancing drive time with child-friendly stops. Operators target school holiday calendars in Australia and United States national park gateway cities.
- Weekend Escapes:Short-haul departures within 200 kilometers of urban centers. European operators leverage camper van subscription models to capture repeat bookings from remote work professionals.
Road trips absorb the bulk of installed fleet capacity; weekend escapes are expanding most quickly.
Vehicle Type:
Vehicle selection dictates margin structure through depreciation schedules, maintenance protocols, and fuel or charging cost profiles.
- RVs:Integrated lodging and mobility command premium nightly rates but require substantial capital deployment and specialized storage infrastructure. United States national park corridors and Australian coastal routes concentrate demand, though lithium battery cost inflation constrains fleet expansion timelines.
- Motorhomes:Larger chassis with expanded amenities target extended-stay travelers. European operators face CSRD emissions disclosure requirements per kilometer traveled, accelerating consolidation among mid-sized fleet owners.
- Cars:Lowest barrier to entry with broadest demographic accessibility. Rental operators compete on pickup network density and telematics-enabled insurance products.
- Vans:Modular camper conversions bridge car accessibility with RV functionality. Subscription-based access models gain traction in United States coastal metros and Australian capital cities.
RVs capture the highest revenue per trip; vans are climbing the fastest as younger travelers prioritize flexibility over amenities.
Destination Type:
Geographic clustering shapes infrastructure investment and permit acquisition strategies.
- National Parks:Restricted access corridors and overnight parking regulations create supply rigidities that limit capacity expansion. United States operators navigate FAA regulations for aerial tour integrations and NHTSA vehicle safety standards.
- Coastal Routes:Highest repeat visitation rates concentrate demand along Norway's western fjords, Australia's Great Ocean Road, and California Highway 1. EV charging infrastructure buildout determines route viability for electric fleets.
- Historical Sites:Itinerary packaging requires curation partnerships with regional heritage organizations. European operators manage divergent toll systems and emissions zones across multi-country routes.
- Urban Destinations:Parking scarcity and congestion charging compress margins. Operators prioritize one-way rental structures and peripheral pickup nodes.
National parks anchor the highest-margin bookings; coastal routes are gaining share fastest as charging infrastructure eliminates range constraints.
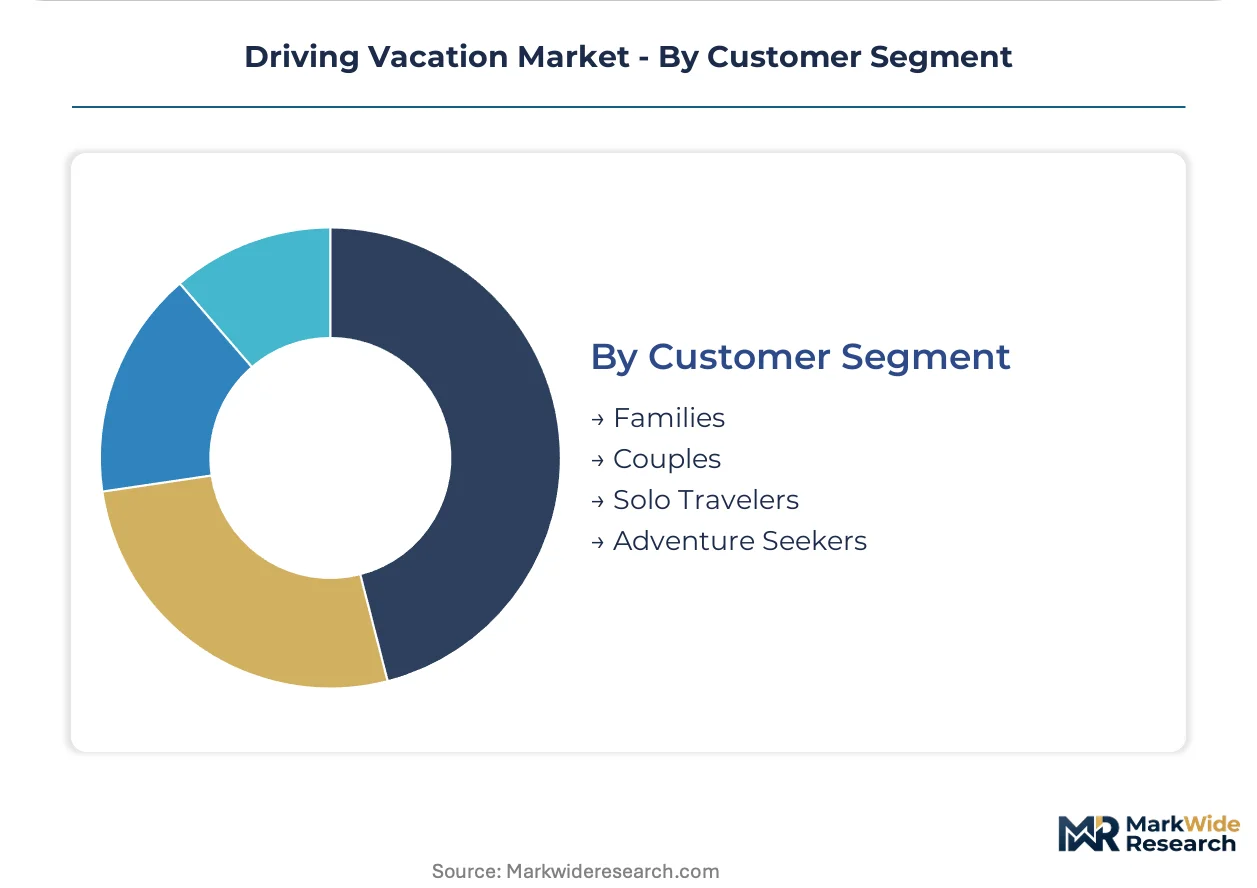
Customer Segment:
Demographic targeting determines marketing spend allocation and product architecture complexity.
- Solo Travelers:Modular, self-guided itineraries with flexible pickup and drop-off nodes. Black Tomato and roadsurfer target this segment through hyper-personalized routing and expanded European pickup networks.
- Adventure Seekers:Experience-density prioritization over destination comfort. Australia's remote work visa programs generate month-long vehicle-based demand connecting outback destinations with coastal coworking hubs.
- Families:Safety certification and child-specific amenities drive vehicle selection. School holiday timing concentrates booking windows.
- Couples:Premium accommodation integration and romantic route curation. Shorter booking lead times require dynamic pricing capabilities.
Families represent the largest volume base; solo travelers are expanding most quickly as remote work permanence extends trip duration flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the largest share of driving vacation capacity, while Norway and Australia emerge as production centers for specialized fleet vehicles and route infrastructure. Fleet operators and charging network developers concentrate capital deployment along coastal corridors and national park gateways.
United States
FAA regulations govern aerial tour integrations with ground-based driving routes, while EPA emissions standards shape rental fleet composition. California's Pacific Coast Highway and Utah's national park corridors anchor the highest-margin booking concentrations, with EV charging buildout eliminating range constraints on mountain routes.
Norway
Western fjord circuits attract premium self-drive demand despite underdeveloped charging density along remote stretches. The country's national transport regulator oversees toll system harmonization across county boundaries. Bergen and Ålesund serve as pickup nodes for electric camper van fleets targeting adventure-seeking demographics.
Australia
Extended-stay visa categories for digital nomads generate month-long vehicle-based itineraries connecting outback destinations with coastal coworking infrastructure. The national tourism infrastructure program funds remote charging station deployment. Queensland's coastal routes and South Australia's desert circuits concentrate fleet operator investments.
Germany
CSRD disclosure requirements pressure mid-sized fleet operators to document carbon intensity per kilometer traveled, accelerating consolidation among undercapitalized regional players. KBA vehicle certification standards govern camper van safety modifications. Bavaria's Alpine routes and Baden-Württemberg's Black Forest anchor domestic demand clusters.
United Kingdom
Subscription-based vehicle access models displace per-rental transactions in London and Edinburgh departure markets. DVSA operator licensing requirements create compliance overhead for cross-border European itineraries. Scotland's North Coast 500 and Wales's coastal routes attract repeat visitation from remote work professionals seeking flexible durations.
Driving Vacation Market Competitive Landscape
Top-tier vendors anchor premium self-drive programming, while mid-cap regional specialists compete on pickup network density and route customization depth. The vendor base stratifies across three tiers: integrated platform operators with nationwide fleet access, curated itinerary specialists blending vehicle rental with accommodation networks, and single-destination regional operators. Strategic archetypes include telematics-enabled insurers, modular camper conversion fabricators, and charging-lodging hybrid developers. Competitive moves concentrate on fleet electrification partnerships and cross-border permit acquisition capabilities.
Within the curated itinerary tier, Black Tomato and Audley Travel exemplify hyper-personalized routing architectures, while roadsurfer anchors the subscription-based vehicle access model across European pickup networks. These three entities represent divergent strategic bets on traveler behavioral shifts: Black Tomato and Audley Travel occupy positions emphasizing experiential density and accommodation integration, whereas roadsurfer exemplifies asset-light fleet scaling through membership structures. Untamed Travelling and Scott Dunn sit within adjacent premium positioning brackets, though their precise market footprints remain archetype-dependent rather than volume-dominant.
| Leading Market Players |
|---|
| Black Tomato |
| Untamed Travelling |
| Audley Travel |
| roadsurfer |
| HunterMoss |
| Scott Dunn |
| All Roads North |
| Crush Global |
| WEXAS Travel |
| Others |
Supply & Pricing Matrix
Backward integration into camper van conversion and charging-lodging hybrid development anchors supply position and pricing power for fleet operators navigating lithium battery cost inflation and CSRD disclosure mandates. This integration choice compresses third-party margin extraction while enabling premium capture through controlled experiential density across route networks.
Pricing Analysis
Short lead-time bookings command premium rates against discounted spot inventory released within cancellation windows. Three-tier pricing structure across premium, standard, and economy levels segments demand by experiential density and accommodation integration depth. Pricing pressure stems from vehicle acquisition cost inflation in lithium-dependent powertrains. Families exhibit highest price sensitivity due to school holiday timing constraints, while solo travelers accept premium positioning for modular flexibility.
Supply Chain Analysis
Dual-sourcing requirements for semiconductor-dependent control systems and battery management modules now dominate fleet procurement protocols. Manufacturing concentrates in Germany, China, and the United States for chassis platforms, with modular conversion components sourced from Poland and Vietnam. Supply chain risk centers on single-source vulnerability for lithium battery packs amid commodity price volatility. Distribution runs through subscription platform aggregators consolidating regional pickup networks under nationwide access memberships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European Union's Corporate Sustainability Reporting Directive erects a compliance moat that consolidates advantage among fleet operators with pre-existing carbon accounting infrastructure. This regulatory barrier-to-entry story rewards early capital deployment into disclosure systems.
For Market Incumbents: To counter subscription-based platform aggregation threatening per-rental transaction volumes, incumbent fleet operators should deepen route optimization software investments and acquire charging-lodging hybrid developers in Norway's western fjord corridors. Certification investment in telematics-enabled usage-based insurance products creates defensive differentiation against asset-light entrants.
For New Entrants and Emerging Players: The price-point gap between premium curated itineraries and economy van rentals opens white-space positioning for mid-market modular products targeting Australia's remote work visa holders with month-long vehicle-based itineraries. Norway's underdeveloped EV charging density along fjord routes presents the most penetrable geography. Go-to-market execution should anchor in coastal coworking hub partnerships rather than traditional campground networks.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays and charging-lodging infrastructure roll-ups across the medium-term horizon. Acquisition targets should display integrated carbon accounting systems and cross-border permit navigation capabilities. The signal to watch is federal EV corridor investment acceleration in the United States, which would validate fleet electrification capex strategies and compress payback timelines for charging station developers.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Aligns vehicle procurement with EPA emissions standards and CSRD disclosure timelines. |
| Cross-Border Permit Acquisition | Reduces operational overhead for multi-country European itineraries under divergent camping regulations. |
| Charging-Lodging Hybrid Development | Captures first-mover positioning along Norway's western fjord routes with integrated station networks. |
| Telematics Insurance Integration | Creates parametric revenue layers from connected vehicle data streams managing driver behavior risk. |
| Subscription Platform Migration | Consolidates booking power with urban departure markets favoring monthly membership structures. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with fleet operations directors, campground network managers, charging infrastructure developers, and tourism board officials provided demand-side validation. Secondary sources included FAA aerial tour integration records, EPA emissions compliance databases, EU CSRD implementation guidance, and national park corridor access permit registries. Bottom-up fleet capacity modeling and top-down tourism expenditure triangulation reconciled volume estimates.
Data-stream reconciliation across vehicle registration databases, charging station deployment trackers, and accommodation booking platforms informed the analytical framework. Segmentation dimensions modeled include travel type, vehicle powertrain architecture, destination corridor density, and customer psychographic cluster. CAGRs were derived from trend extrapolation calibrated against infrastructure buildout timelines. Forecast inputs incorporated remote work permanence indices and EV charging density projections.
Inputs from charging network developers and visa policy administrators were available through the study window; gaps in real-time fleet utilization telemetry introduce uncertainty bands around capacity utilization assumptions. Forecasts reflect documented assumptions regarding lithium battery cost trajectories and permitting timeline stability. Deviation in federal EV corridor funding appropriations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
Vietnam Taxi Market
Transportation Services
Global Garbage Truck Market
Transportation Services
Full-Service Carrier Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Scooter Rental Market
Transportation Services
Benchmarking Services for Transportation Rates Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
United States Car Rental Market
Transportation Services
Truck Sharing Market
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
Car Rental Service Market
Transportation Services
Compact Road Sweepers Market