
 Refrigerated Liquid Eggs Market | 2026-2036
Refrigerated Liquid Eggs Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Liquid Eggs Market Insights
The gap between premium cage-free liquid egg offerings and commodity conventional grades is expanding across food service procurement channels. Rose Acre Farms leverages its integrated layer operations to sustain volume commitments for national restaurant chains. Cal-Maine Foods anchors its position through geographic dominance across the southeastern United States. Michael Foods differentiates via specialized extended-shelf-life processing technology for institutional buyers.
Refrigerated liquid eggs consist of shell eggs broken, homogenized, and pasteurized at temperatures exceeding 60 degrees Celsius before rapid cooling to 4 degrees Celsius, delivering microbial safety for commercial kitchens without shell handling. Whole egg formulations occupy the largest volume share due to universal recipe compatibility across hot and cold applications. Egg whites represent the fastest-growing product type as protein-forward menu development accelerates in fitness-oriented food service segments. Bulk packaging dominates margin pools through direct-to-manufacturer contracts that minimize per-unit handling costs.
USDA grading standards and FDA pasteurization mandates under the Egg Safety Rule define minimum thermal processing thresholds for interstate commerce. State-level cage-free transition laws in California and Massachusetts reshape layer housing requirements upstream of liquid processing facilities. Stakeholders must monitor evolving state ballot initiatives and food service sustainability pledges to anticipate supply contract specifications before procurement cycles finalize.
Market Dynamics
Food service procurement consolidation is compressing supplier margins while mandating extended-shelf-life specifications that favor processors with captive layer operations and integrated cold-chain infrastructure.
Growth Catalysts
- USDA Egg Safety Rule pasteurization mandates:Interstate commerce requirements for liquid egg products create regulatory moats for compliant processors while eliminating small-scale competitors lacking thermal processing capital.
- Quick-service restaurant operational standardization:National chains specify refrigerated liquid eggs to eliminate shell-egg handling variability and reduce kitchen labor allocation for breakfast daypart expansion.
- High-pressure processing technology:Non-thermal pasteurization methods preserve functional protein properties for specialized bakery and confectionery applications beyond conventional heat treatment capabilities.
Market Restraints
- Feed grain price volatility:Corn and soybean meal input costs constitute 60-70% of layer production economics, transmitting commodity swings directly to liquid egg processor margin structures.
- Midwest supply concentration:Iowa, Indiana, and Ohio house over 40% of US layer capacity, creating geographic risk exposure to regional disease outbreaks and weather-driven logistics disruptions.
- Plant-based egg substitution:Mung bean and chickpea protein formulations target food service baking applications where functional properties outweigh flavor requirements.
Strategic Opportunities
- California Proposition 12 compliance premiums:Cage-free liquid egg specifications command 15-25% price premiums in West Coast food service contracts through 2025 implementation deadlines.
- E-commerce direct-to-restaurant distribution:Specialized cold-chain logistics platforms bypass traditional broadline distributors for independent restaurant segments seeking smaller minimum order quantities.
- Extended-shelf-life and ESL packaging convergence:Modified atmosphere packaging combined with aseptic filling extends refrigerated distribution radius for processors lacking national plant networks.
Industry Challenges
- HACCP-certified plant engineering talent scarcity:Thermal process validation and sanitary design expertise commands premium compensation in rural processing locations distant from food science university clusters.
- Legacy ERP integration with cold-chain IoT sensors:Real-time temperature monitoring systems require custom middleware development to interface with established inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Liquid Eggs Market |
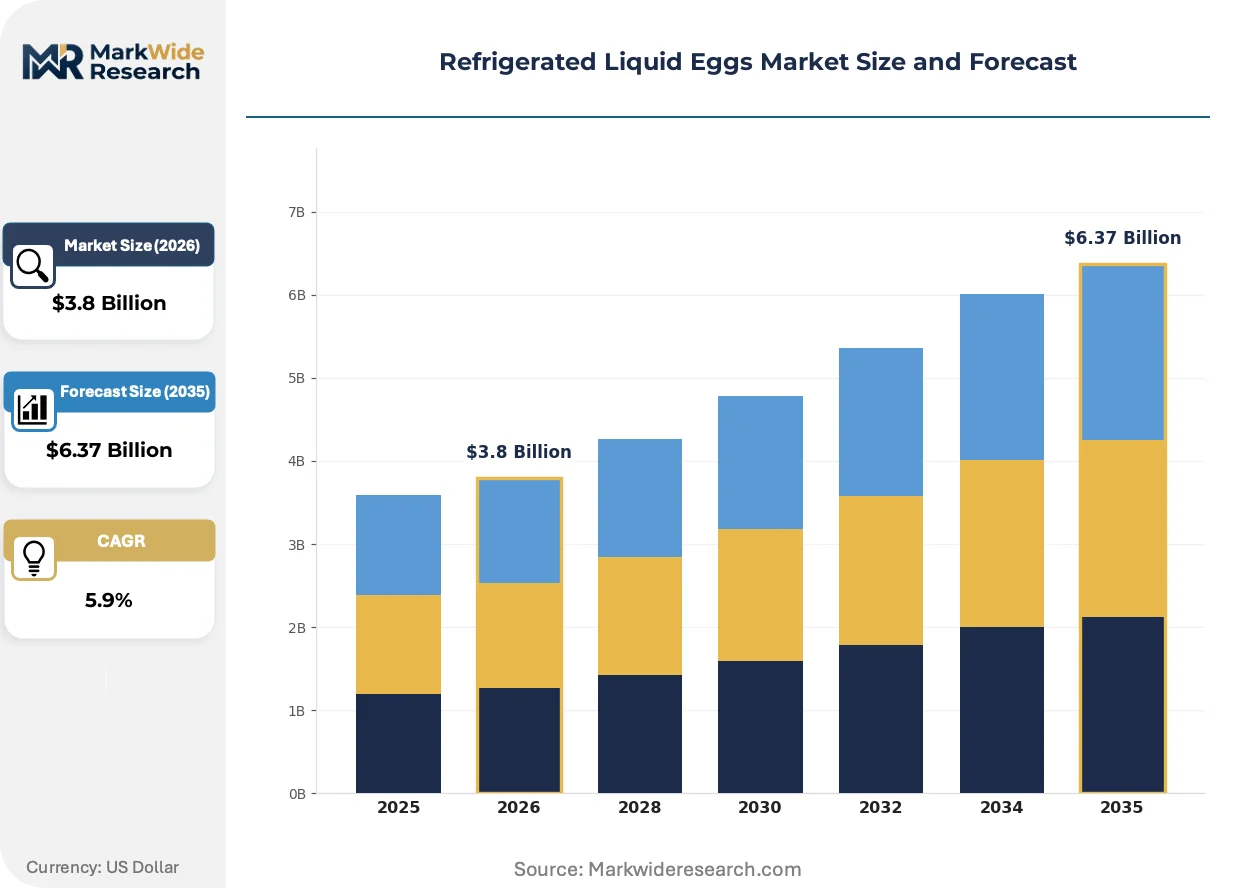
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Egg, Egg Whites, Egg Yolks, Flavored Egg End User: Food Service, Retail, Bakery, Food Processing Packaging Type: Bottle, Carton, Pouch, Bulk Distribution Channel: Online, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | Cargill Incorporated, Rose Acre Farms, Rembrandt Enterprises, Cal-Maine Foods, Michael Foods, Nest Fresh Eggs, Global Food Group, Ready Egg Products, Bumble Hole Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Liquid Eggs Market Trends and Innovations
Processing automation and regulatory compliance technology are converging to reshape competitive economics, while procurement centralization reconfigures buyer-supplier power dynamics across food service channels.
Robotic egg-breaking and separation systems is automating shell removal and yolk-white fractionation at throughputs exceeding 300,000 eggs per hour. Major quick-service restaurant suppliers deploy these lines to reduce labor dependency and contamination risk in high-volume operations. The technology is automating quality consistency that previously required skilled manual grading, compressing the viable supplier base to capital-intensive processors.
The FDA Food Safety Modernization Act preventive controls rule imposes hazard analysis requirements on liquid egg facilities previously exempt under traditional inspection protocols. Processors must now implement environmental monitoring programs and supply-chain verification for incoming shell eggs. Small-to-midscale operations in the southeastern United States face disproportionate compliance costs relative to integrated competitors with dedicated food safety infrastructure.
Centralized procurement through group purchasing organizations is consolidating restaurant buying power into fewer decision-makers with standardized specification templates. Independent operators increasingly source through broadline distributors rather than direct processor relationships, compressing available margin for branded liquid egg positioning. This concentration is most pronounced in the Northeast corridor, where healthcare and hospitality institutional buyers have consolidated purchasing through multi-year sole-source agreements.
Refrigerated Liquid Eggs Market Segmentation
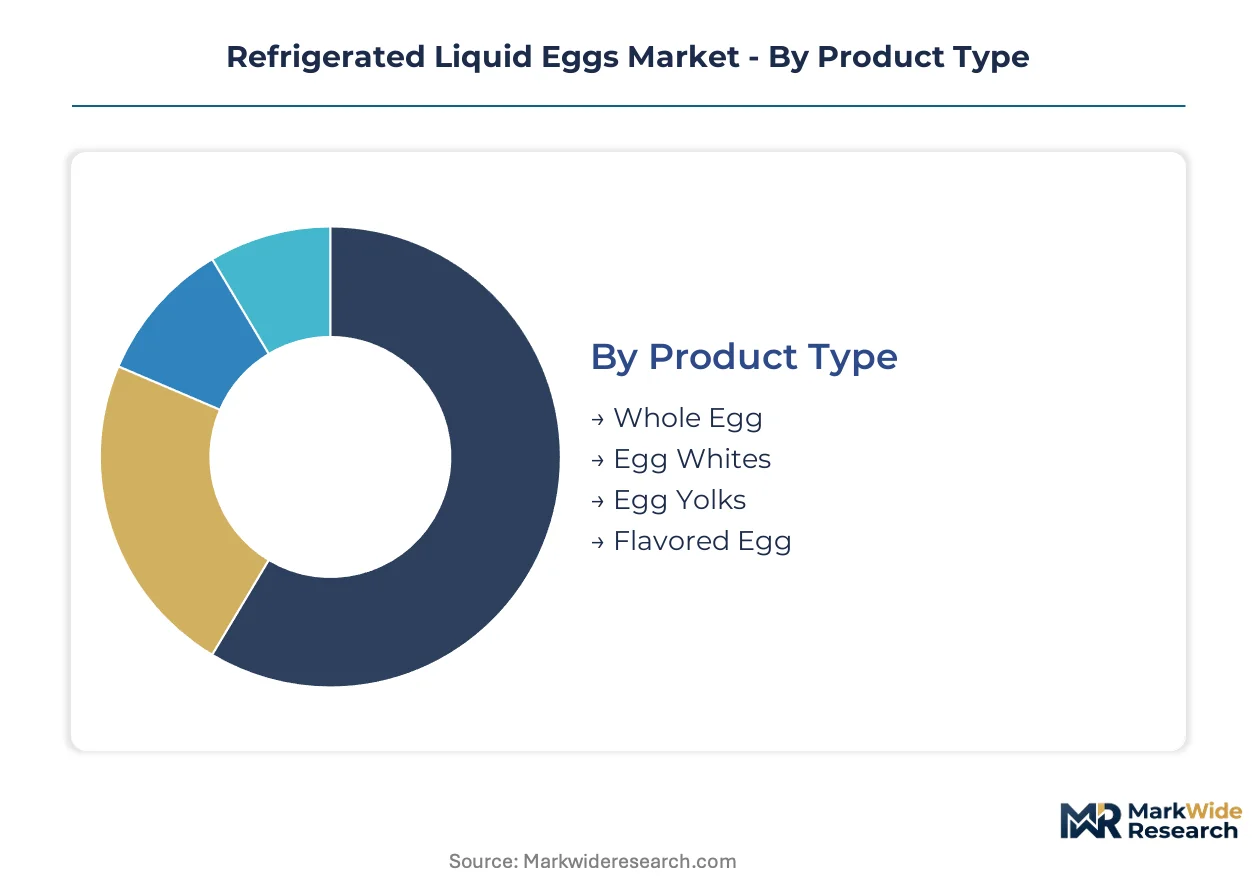
Refrigerated liquid egg procurement channels demand distinct product specifications, packaging formats, and shelf-life profiles. Each segment category reflects divergent cost structures and operational requirements across food service and retail channels.
Product Type:
Volume leadership concentrates in commodity-grade formulations, while premium fractions command specialized processing premiums.
- Whole Egg:Homogenized blend of yolk and white in natural proportions delivers universal recipe compatibility across hot and cold applications. Food service operators in quick-service restaurant chains specify this grade for breakfast menu standardization and labor reduction.
- Egg Whites:Separated albumen fraction pasteurized for high-protein applications. Fitness-oriented food service segments and health-focused retail channels are expanding procurement of this specification fastest.
- Egg Yolks:Concentrated lipid fraction serves emulsification requirements in sauce and dressing manufacturing.
- Flavored Egg:Pre-seasoned formulations reduce kitchen preparation steps for institutional feeding operations.
Mature deployment sits with Whole Egg. Newer deployment is concentrated in Egg Whites.
End User:
Customer type determines order scale, delivery frequency, and specification complexity across the value chain.
- Food Service:National restaurant chains and institutional feeders drive bulk procurement with extended-shelf-life requirements. Cold-chain reliability and consistent portion control outweigh per-unit price sensitivity in contract negotiations.
- Retail:Supermarket and specialty store channels demand consumer-ready packaging with clear labeling for home cooking applications. Smaller pack sizes and premium positioning dominate this segment.
- Bakery:Commercial bakeries prioritize functional protein properties for volume, texture, and shelf-life extension in finished goods.
- Food Processing:Ingredient buyers in sauce, dressing, and prepared food manufacturing seek tanker-load quantities with custom specifications.
Contract consolidation is reshaping Food Service procurement. Direct-to-processor relationships are expanding fastest in Food Processing.
Packaging Type:
Format selection trades handling efficiency against distribution radius and customer handling capabilities.
- Bulk:Tanker and tote delivery systems serve high-volume manufacturers with captive receiving infrastructure. Direct contracts eliminate per-unit packaging costs and maximize margin capture for processors with national plant networks.
- Bottle:Rigid polyethylene containers target retail and small food service accounts requiring pourable convenience. Modified atmosphere options extend refrigerated shelf life for distant distribution.
- Carton:Gable-top paperboard dominates retail shelf presence with established consumer familiarity and recycling credentials.
- Pouch:Flexible film formats reduce shipping cube and storage footprint for space-constrained operators.
Established infrastructure supports Bulk deployment. Pouch formats are gaining traction fastest among independent restaurant operators.
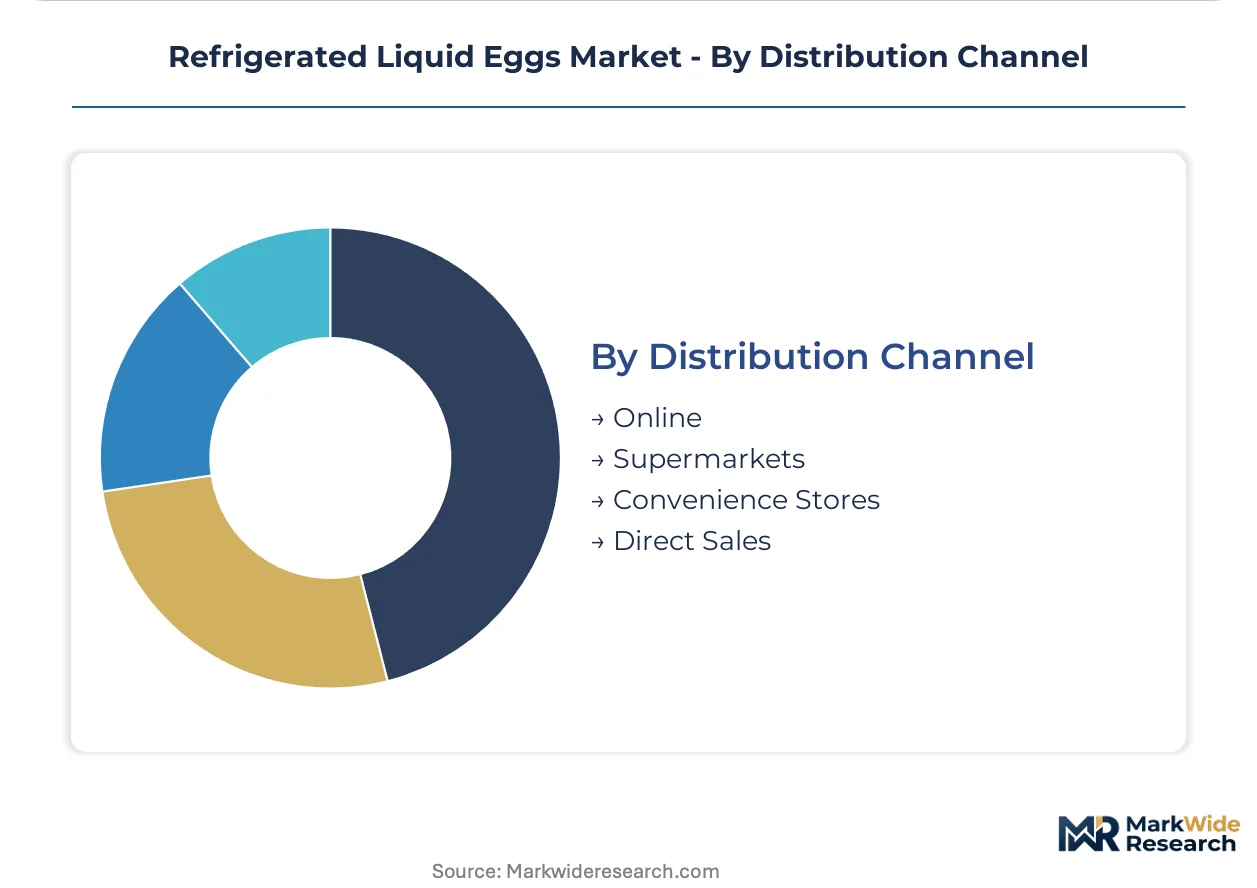
Distribution Channel:
Channel structure determines price transparency, minimum order thresholds, and cold-chain custody requirements.
- Direct Sales:Processor-to-operator relationships bypass distributor markups for national accounts with volume commitments and dedicated logistics. Food service chains with centralized procurement favor this channel for specification control.
- Supermarkets:Retail grocery placement requires slotting fees and promotional support for refrigerated case positioning. Regional grocery consolidation is compressing supplier negotiation leverage.
- Online:E-commerce platforms serve independent restaurants and small food manufacturers with fractional pallet quantities. Specialized cold-chain logistics providers are emerging to support this channel.
- Convenience Stores:Limited refrigerated space restricts assortment to high-velocity whole egg SKUs in smaller pack configurations.
Traditional strength resides with Direct Sales. Online channel infrastructure is expanding most rapidly for independent operator segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors refrigerated liquid egg processing capacity through its central logistics position connecting Iowa layer farms to national food service distribution networks.
United States
Iowa, Indiana, and Ohio concentrate over 40% of domestic layer capacity, feeding Midwest processing plants with shell egg supply. The USDA Egg Safety Rule mandates pasteurization thresholds for interstate liquid egg commerce, eliminating non-compliant processors. Chicago-based facilities leverage rail and refrigerated trucking corridors to serve quick-service restaurant chains nationwide.
Canada
Ontario and Quebec house the majority of Canadian liquid egg processing infrastructure, supplying institutional food service across provincial healthcare systems. Health Canada enforces parallel pasteurization standards aligned with FDA thermal processing benchmarks. Toronto-area processors benefit from cross-border supply agreements with US layer operations in the Great Lakes region.
Mexico
Central Mexico's poultry belt around Querétaro and Guanajuato is expanding liquid egg capacity for food manufacturing and hospitality sectors. The country's national food safety regulator applies Codex Alimentarius pasteurization guidelines for processed egg products. Mexico City metro area demand concentrates procurement through centralized institutional feeding contracts.
Brazil
São Paulo state dominates South American liquid egg processing, serving domestic bakery and prepared food manufacturers with regional supply security. ANVISA oversees pasteurization compliance for processed egg derivatives in interstate commerce. Campinas industrial corridor hosts integrated layer-to-liquid processing facilities with captive cold-chain distribution.
United Kingdom
East Anglia and the Midlands retain liquid egg processing clusters despite declining domestic layer flock sizes post-EU exit. The Food Standards Agency maintains Salmonella control programs for liquid egg entering food manufacturing supply chains. Lincolnshire processing plants source shell eggs from remaining regional layer farms and Irish cross-border supply.
Refrigerated Liquid Eggs Market Competitive Landscape
Premium-margin players sit above commodity-margin players across cage-free certification and extended-shelf-life processing capabilities. The market structure consolidates around integrated layer-to-liquid processors with captive supply chains and regional independents serving localized food service accounts. Three archetypes dominate: national-scale integrated operators with multi-plant networks, regional specialists with single-facility concentration, and private-label processors serving distributor house brands. Capacity expansion and backward integration into layer operations represent the dominant competitive moves as procurement consolidation intensifies.
Among US-based integrated operators, Rose Acre Farms and Cal-Maine Foods exemplify the national-scale archetype with geographic coverage spanning multiple processing regions. Michael Foods occupies a position representing specialized extended-shelf-life processing capabilities for institutional contract segments. These three entities anchor the competitive structure through distinct positioning across volume commitment, geographic density, and technical specification depth.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Rose Acre Farms |
| Rembrandt Enterprises |
| Cal-Maine Foods |
| Michael Foods |
| Nest Fresh Eggs |
| Global Food Group |
| Ready Egg Products |
| Bumble Hole Foods |
| Others |
Pricing and Supply Chain Analysis
Quick-service restaurant procurement consolidation is mandating extended-shelf-life specifications that force processors to invest in captive layer operations and integrated cold-chain infrastructure, compressing margins for non-integrated suppliers while rewarding scale.
Pricing Analysis
Yield-per-unit throughput anchors value-based pricing for high-volume food service contracts, with cage-free certification premiums commanding substantial markups over commodity grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification status and shelf-life extension capabilities. Pricing pressure stems from feed grain cost volatility transmitting directly to processor margins. National restaurant chains exhibit lowest price sensitivity due to operational standardization requirements, while independent operators remain most responsive to per-unit cost fluctuations.
Supply Chain Analysis
Direct-to-manufacturer channels handle hyperscale food processing demand through tanker-load contracts that eliminate distributor markups and maximize margin capture. Supply concentrates in Iowa, Indiana, and Ohio, where over 40% of US layer capacity feeds Midwest processing plants. The chain draws from corn and soybean meal inputs alongside specialized pasteurization equipment. Single-source vulnerability runs through geographic concentration of layer farms exposed to regional disease outbreaks. Distribution runs through refrigerated trucking corridors anchored by Chicago logistics hubs serving national quick-service restaurant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cage-free layer housing conversion timelines represent the binding capacity constraint, with California Proposition 12 compliance deadlines propping premium pricing through supply scarcity.
For Market Incumbents: Deploy backward integration into layer operations to secure captive shell egg supply for extended-shelf-life processing commitments. Invest in high-pressure processing technology to defend against plant-based egg substitution threats in bakery applications. Control direct sales channels to national accounts to preserve specification authority against distributor consolidation. For New Entrants and Emerging Players: Launch via e-commerce direct-to-restaurant distribution platforms serving independent operators with fractional pallet quantities and smaller minimum order thresholds. Target West Coast food service contracts demanding cage-free certification where incumbent capacity constraints create procurement gaps. Pursue specialized cold-chain logistics partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors regional processors with single-facility concentration and untapped cage-free conversion potential. Long-term viability hinges on securing layer supply agreements upstream of liquid processing capacity. Monitor state ballot initiatives on layer housing regulations as the critical inflection signal for supply contract repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Cage-Free Layer Housing Conversion | California Proposition 12 deadlines force capital deployment into compliant facilities to maintain West Coast contract access. |
| Extended-Shelf-Life Technology Investment | High-pressure processing preserves functional proteins for bakery applications beyond conventional heat treatment limits. |
| Direct-to-Restaurant E-Commerce Launch | Specialized cold-chain platforms bypass broadline distributors for independent operators seeking flexible procurement. |
| Backward Integration into Layer Operations | Captive shell egg supply insulates processors from feed grain volatility and geographic supply disruptions. |
| Group Purchasing Organization Partnership | Multi-year sole-source agreements with healthcare and hospitality institutional buyers lock in volume commitments. |
Research Methodology
Multi-period observation of layer housing conversion rates, pasteurization capacity additions, and food service procurement contract awards anchored the trend analysis, supplemented by interviews with liquid egg processing plant managers, quick-service restaurant supply chain directors, layer farm operations executives, and broadline distributor category buyers. Secondary validation drew from USDA shell egg production reports, FDA Egg Safety Rule compliance filings, state-level cage-free transition law texts, and SEC 10-K disclosures from publicly traded layer operations. Bottom-up volume modeling triangulated against top-down food service spending allocation estimates.
Input-output matrices mapped shell egg supply from Iowa, Indiana, and Ohio layer concentrations through Midwest processing plants to downstream food service, retail, and food manufacturing demand segments across the projection horizon. Segmentation dimensions included product type, end-user category, packaging format, and distribution channel. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory compliance deadlines and procurement consolidation patterns. Forecast inputs incorporated feed grain price indices and quick-service restaurant breakfast daypart expansion rates.
The model assumes a particular technology adoption path for high-pressure processing equipment; alternative pathways for non-thermal pasteurization scale-up would alter the outlook for specialized bakery segment penetration. Forecasts reflect assumptions about state-level cage-free law implementation timelines and food service sustainability pledge fulfillment rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Europe Dehydrated Food Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Frozen Processed Meat Market
Processed and Frozen Foods
South America RTE Food Market
Processed and Frozen Foods
Middle East and Africa Ice Cream Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Frozen Novelty Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market