
 Latin America Frozen Finger Chips Market | 2026-2036
Latin America Frozen Finger Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Frozen Finger Chips Market Intelligence
Food service buyer concentration in Brazil and Mexico is decoupling from traditional wholesale channels as quick-service chains build direct supplier relationships. McCain Foods leverages its Parana production complex to anchor supply contracts with major Brazilian restaurant groups. J.R. Simplot competes through specialized high-yield potato varieties bred for consistent fry color and texture under tropical storage conditions. Lamb Weston sustains its position by controlling cold-chain logistics from Andean processing plants to Pacific coast ports.
Frozen finger chips are par-fried potato strips, typically blanched at 85-95°C and quick-frozen at minus 35°C to preserve cellular structure and reduce oil uptake upon final frying; they serve commercial kitchens and retail consumers seeking consistent preparation speed and portion control. Classic formulations still dominate volume, though sweet potato variants are capturing margin pools in Mexican and Colombian premium retail. Food service distribution channels generate the highest throughput, while single-serve packaging is expanding fastest in Brazilian convenience stores. Online retail remains structurally underdeveloped for frozen potato logistics outside major metropolitan zones.
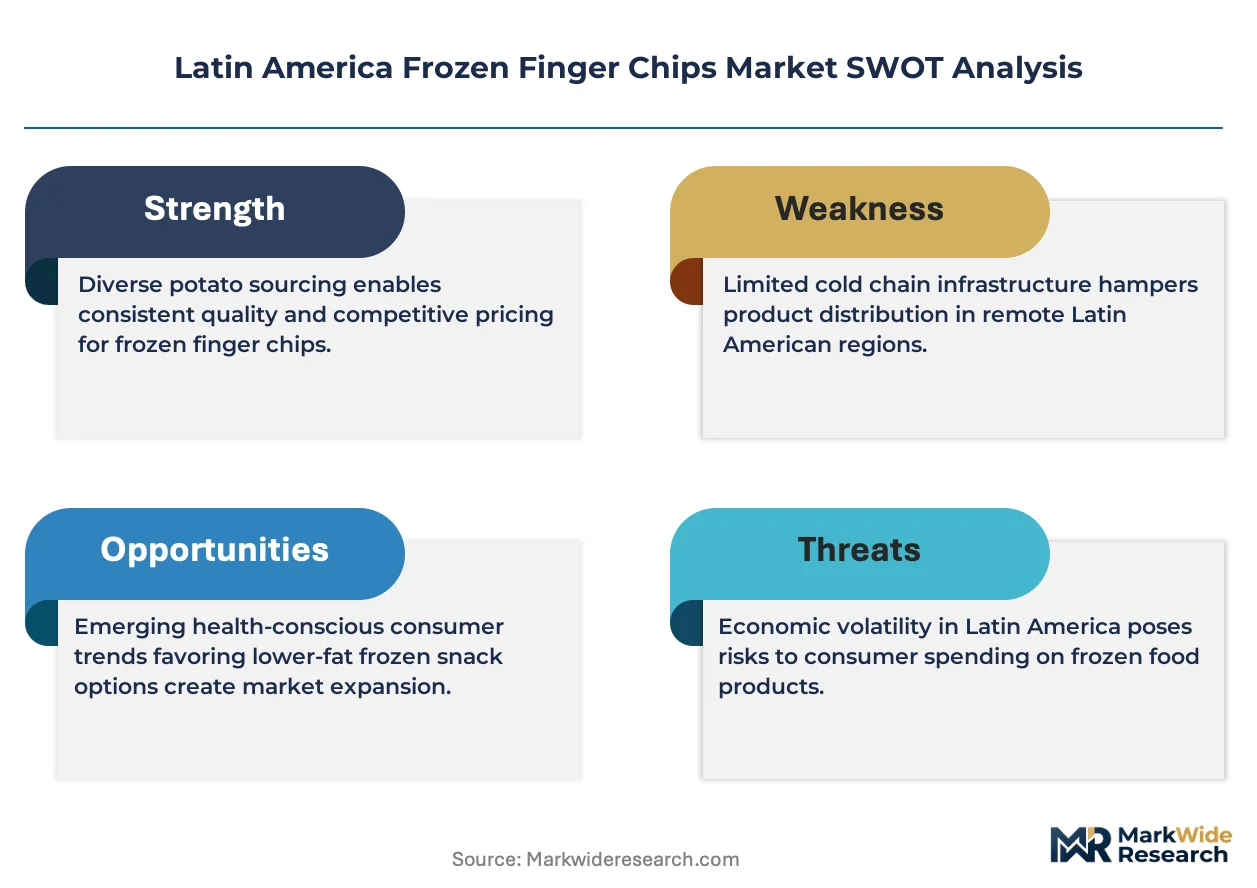
ANVISA governs frozen food safety and additive limits in Brazil, while Mexico's COFEPRIS enforces parallel standards that shape cross-border product formulation strategies; both agencies are tightening sodium disclosure requirements that affect breading and pre-salt recipes. Argentina's national food code adds another compliance layer for Mercosur-integrated suppliers. Stakeholders must monitor how diverging national labeling rules reshape SKU proliferation and whether regional cold-chain infrastructure investments keep pace with food service expansion into secondary cities.
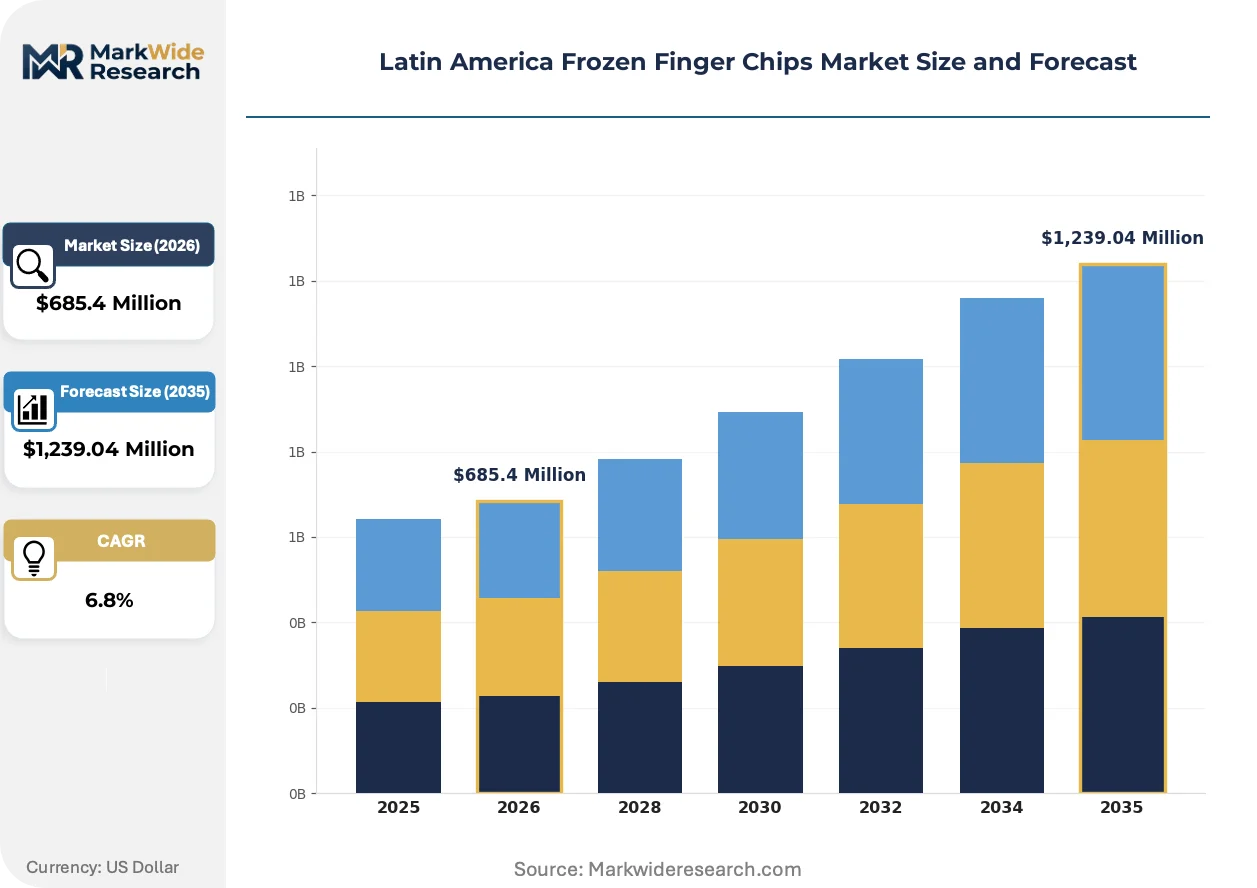
Market Dynamics
Cold-chain infrastructure expansion across Brazil and Mexico is decoupling frozen finger chip procurement from traditional wholesale intermediaries, enabling direct manufacturer-to-restaurant contracts that compress margin layers and reshape distributor economics.
Growth Catalysts
- ANVISA labeling modernization:Brazil's updated frozen food disclosure standards are accelerating cleaner-ingredient R&D investments, creating first-mover advantages for compliant suppliers.
- Quick-service restaurant densification:São Paulo state's concentrated food service network is pulling volume through specialized distributor channels that prioritize frozen potato throughput.
- Blanching automation:Continuous 85-95°C par-fry systems are standardizing cellular structure preservation, reducing oil uptake variance and lowering final-frying operational costs for commercial kitchens.
Market Restraints
- Andean cold-chain gaps:Lamb Weston's Pacific coast logistics control masks persistent temperature-break risks in secondary Colombian and Peruvian city distribution, limiting market penetration depth.
- Input potato price volatility:Tropical storage condition requirements for J.R. Simplot's specialized high-yield varieties create yield-risk concentration that amplifies raw material cost swings.
- COFEPRIS-ANVISA formulation divergence:Mexico and Brazil's tightening sodium disclosure thresholds are forcing parallel SKU development, fragmenting production runs and elevating compliance overhead.
Strategic Opportunities
- Colombian premium retail white space:Sweet potato variant margins remain underexploited outside Bogotá and Medellín metro corridors, with convenience store penetration trailing Brazilian benchmarks.
- Single-serve packaging channel innovation:Brazilian convenience store freezer-door expansion is creating dedicated velocity slots for portion-controlled formats absent in traditional food service bulk.
- Mercosur-integrated Argentina compliance:The national food code's alignment trajectory offers regulatory arbitrage potential for suppliers achieving dual Brazil-Argentina certification efficiency.
Industry Challenges
- Specialized technician scarcity:Continuous quick-freeze system maintenance at minus 35°C operational parameters requires skill sets concentrated in São Paulo and Mexico City industrial corridors.
- Multi-jurisdiction certification timelines:Simultaneous ANVISA, COFEPRIS, and Mercosur code approvals extend product launch cycles, compressing revenue realization windows for seasonal formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Frozen Finger Chips Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Spicy, Cheese, Sweet Potato Distribution Channel: Supermarket, Online Retail, Convenience Store, Food Service End User: Retail Consumers, Restaurants, Cafeterias, Food Manufacturers Packaging Type: Bags, Boxes, Bulk, Single Serve |
| Companies Covered | McCain Foods, J.R. Simplot, Lamb Weston, Farm Frites, Aviko, Agristo, BRF, Aurora Alimentos, The Kraft Heinz Co, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Frozen Finger Chips Market Strategic Shifts & Innovations
Processing technology standardization and regulatory disclosure tightening are converging to reshape competitive differentiation mechanisms, shifting value capture from scale economies toward formulation agility and cold-chain reliability certification.
Individual quick-freezing tunnel systems with zone-controllable air velocity are modularizing production line configurations for Latin American processors. Mid-scale Brazilian manufacturers are adopting these units to switch between classic and sweet potato variants within single shifts. This flexibility is compressing minimum efficient scale thresholds and enabling regional specialists to contest volume contracts previously captured by integrated complexes.
ANVISA's sodium disclosure mandates are forcing breading and pre-salt recipe reformulations across Brazilian production facilities. Industrial consequence includes accelerated clean-label ingredient sourcing and revised nutrition panel testing protocols. Quick-service chains with centralized menu development are responding fastest, pressuring suppliers to deliver compliant batches ahead of full enforcement timelines.
Direct procurement contracts between frozen potato manufacturers and Brazilian restaurant groups are displacing traditional food service distributor intermediaries. Major São Paulo-based chain operators are consolidating supplier panels and negotiating volume commitments with logistics control provisions. This pattern is most visible in Brazil's southeastern state cluster, where cold-chain reliability metrics now dominate supplier selection criteria alongside unit pricing.
Latin America Frozen Finger Chips Market Segmentation
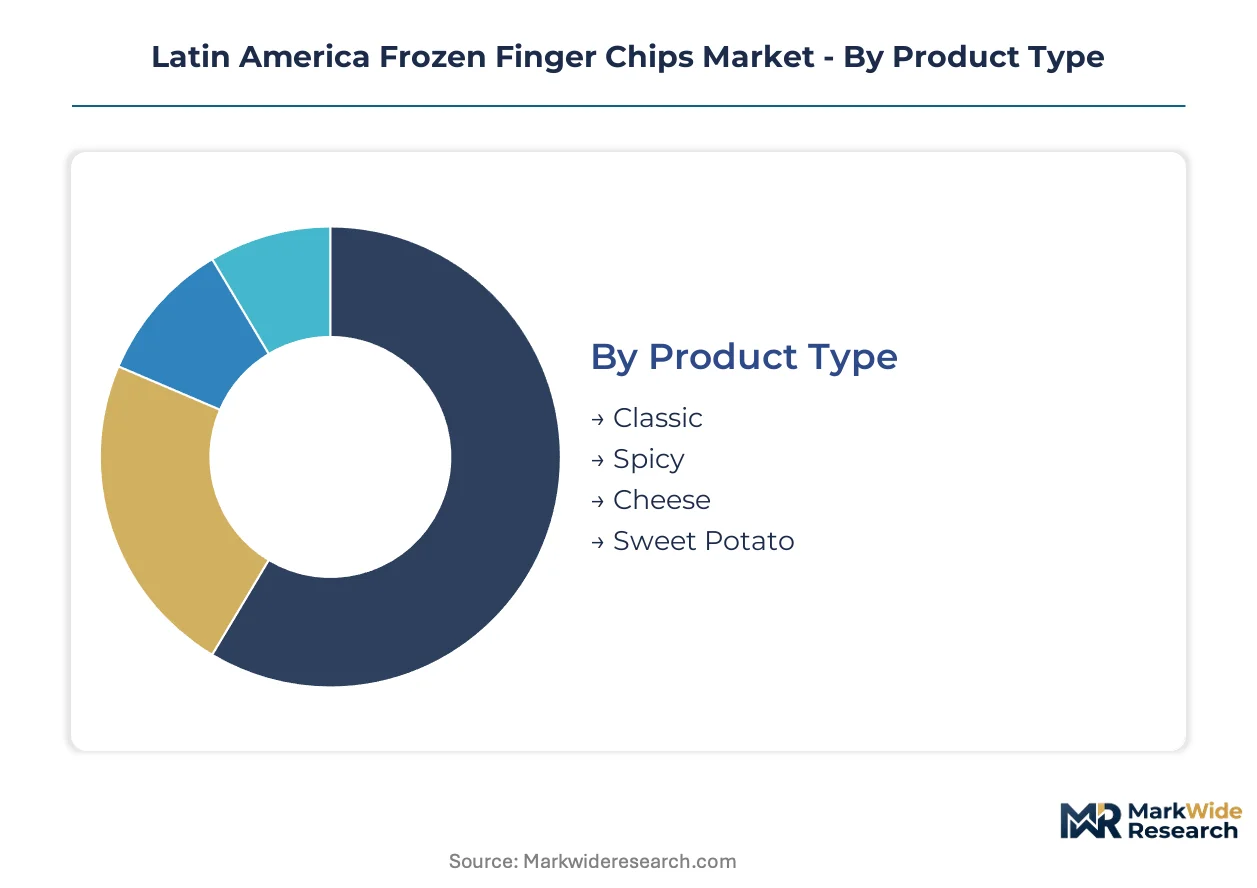
Frozen finger chip purchasing in Latin America splits across formulation preferences, channel access, and operational scale. Each segmentation dimension reveals distinct margin structures and cold-chain requirements that shape supplier strategy.
Product Type:
Buyer choice hinges on fry performance consistency and menu differentiation potential.
- Classic:Standard-cut par-fried strips dominate Brazilian quick-service procurement. São Paulo restaurant groups specify these for centralized kitchen operations where oil uptake variance must stay below threshold limits.
- Sweet Potato:Orange-fleshed variants command premium placement in Mexican and Colombian retail. Bogotá and Medellín convenience stores are expanding freezer-door allocation for these higher-margin formats.
- Spicy:Chile-infused coatings targeting younger demographics in Mexican urban centers.
- Cheese:Powder-coated formats concentrated in Argentine supermarket frozen aisles.
Volume sits with Classic; growth tilts toward Sweet Potato.
Distribution Channel:
Cold-chain reliability thresholds determine which channels manufacturers can serve profitably.
- Food Service:Direct contracts with Brazilian restaurant groups bypass traditional distributors. McCain Foods leverages its Parana complex to anchor these relationships with guaranteed temperature-controlled delivery.
- Convenience Store:Brazilian freezer-door expansion creates dedicated velocity slots. Single-serve packaging formats are climbing the fastest in this channel as urban consumers prioritize portion control.
- Supermarket:Traditional retail concentration in Mexico City and São Paulo metro corridors.
- Online Retail:Structurally constrained by last-mile frozen logistics outside major metropolitan zones.
Revenue concentrates in Food Service; margin expansion favors Convenience Store.
End User:
Operational scale dictates packaging format and procurement frequency.
- Restaurants:Brazilian quick-service chains drive bulk procurement through specialized distributor networks. ANVISA-compliant labeling requirements are accelerating supplier consolidation among large operators.
- Retail Consumers:Colombian premium retail segments show underexploited white space outside major metros.
- Cafeterias:Institutional buyers in Mexican education and corporate segments.
- Food Manufacturers:Ingredient-input purchasers for further-processed potato products.
Throughput centers on Restaurants; penetration gaps persist with Retail Consumers.
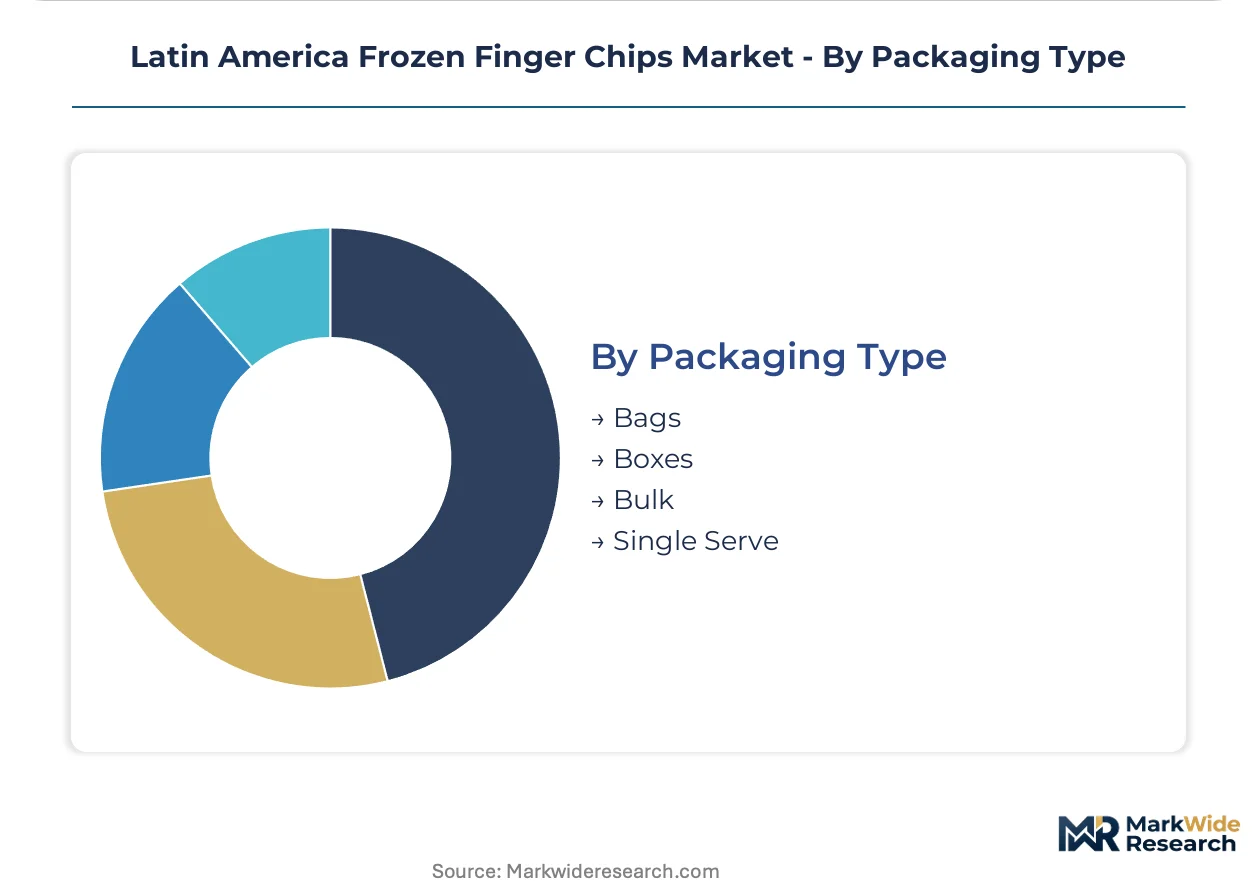
Packaging Type:
Portion control requirements and storage constraints shape format selection.
- Bulk:Food service kitchens in São Paulo state prioritize 10kg+ formats for fryer efficiency. COFEPRIS sodium disclosure rules are forcing reformulation of pre-salt bulk recipes.
- Single Serve:Brazilian convenience stores are the primary expansion vector. Lamb Weston's Andean-to-Pacific logistics network supports this format's temperature sensitivity.
- Bags:Standard retail packaging across Latin American supermarkets.
- Boxes:Premium positioning for gift and specialty retail segments.
Shipment weight favors Bulk; velocity gains concentrate in Single Serve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant procurement concentrates in Brazil's southeastern corridor and Mexico's central plateau, with cold-chain investments decoupling frozen potato supply from traditional wholesale intermediaries.
Brazil
São Paulo state anchors regional demand through dense food service distributor networks serving major restaurant groups. ANVISA's updated frozen food labeling standards are accelerating cleaner-ingredient R&D investments among domestic processors. The Paraná production complex anchors supply contracts with Brazilian quick-service chains seeking guaranteed temperature-controlled delivery.
Mexico
Quick-service restaurant densification in Mexico City and Guadalajara metro corridors drives bulk frozen potato procurement. COFEPRIS enforces sodium disclosure requirements that shape breading and pre-salt recipe formulations across production facilities. Northern border states are seeing cold-chain infrastructure expansion supporting direct manufacturer-to-restaurant contracts.
Argentina
Mercosur-integrated suppliers navigate Argentina's national food code alongside Brazilian compliance requirements. The country's central agricultural provinces supply raw potato inputs to regional processing networks. Buenos Aires province concentrates retail distribution for cheese-coated frozen potato formats in supermarket frozen aisles.
Colombia
Sweet potato variant demand is capturing premium retail margins in Bogotá and Medellín metro corridors. Cold-chain gaps persist in secondary city distribution, limiting penetration depth outside major urban zones. Convenience store freezer-door expansion is creating dedicated velocity slots for portion-controlled formats.
Chile
Andean processing plants supply Pacific coast export corridors with cold-chain logistics control as a competitive differentiator. Santiago's concentrated food service network pulls volume through specialized distributor channels. The country's agricultural valleys provide raw potato inputs with tropical storage condition requirements.
Latin America Frozen Finger Chips Market Key Industry Players
Brazilian producers anchor one tier; European specialists hold premium formulation positions. The market structures around three to five integrated complexes with Parana-scale production capabilities alongside regional mid-scale processors. Strategic archetypes include cold-chain logistics controllers, clean-label formulation leaders, and tropical-storage breeding specialists. Competitive moves concentrate on direct procurement contract capture and blanching automation deployment.
Among the integrated multinational tier, McCain Foods, J.R. Simplot, and Lamb Weston occupy positions defined by geographic production anchoring and logistics control. McCain Foods represents the Brazilian production complex archetype with Parana-based supply contract anchoring. J.R. Simplot exemplifies specialized high-yield variety breeding for tropical storage conditions. Lamb Weston sits within the Andean-to-Pacific logistics control archetype, managing cold-chain reliability from processing plants to coastal ports.
| Leading Market Players |
|---|
| McCain Foods |
| J.R. Simplot |
| Lamb Weston |
| Farm Frites |
| Aviko |
| Agristo |
| BRF |
| Aurora Alimentos |
| The Kraft Heinz Co |
| Others |
Cost & Logistics Intelligence
Continuous 85-95°C par-fry blanching automation is compressing per-unit processing costs while concentrating production scale among Brazilian and Mexican facilities equipped for thermal precision control. This technology shift simultaneously reduces oil uptake variance for commercial kitchen buyers and reinforces margin advantages for processors with capital-intensive thermal systems, tightening the competitive perimeter around integrated complexes.
Pricing Analysis
Volume concentrates in bulk food service contracts while margin expansion tilts toward single-serve retail formats. Classic par-fried strips trade on commodity-like per-kilogram terms anchored to raw potato input costs, whereas sweet potato variants in Colombian and Mexican premium channels capture spread premiums based on fry color consistency and tropical storage performance. Price differentiation rests on cold-chain certification tiers and ANVISA compliance status, with non-compliant batches facing rejection penalties from São Paulo restaurant groups. Pricing pressure stems from J.R. Simplot's specialized variety yield risks amplifying raw material cost swings. Quick-service chains with centralized procurement show lowest price sensitivity; independent regional distributors exhibit highest.
Supply Chain Analysis
Mercosur domestic-content alignment requirements are reshaping sourcing patterns for Brazil-Argentina integrated suppliers seeking dual certification efficiency. Geographic supply concentration centers on Brazil's Paraná complex, Mexico's central plateau processing corridors, and Chile's Andean agricultural valleys feeding Pacific export routes. Raw material dependencies rest on high-yield potato varieties bred for tropical storage, specialized frying oils, and clean-label breading inputs. Supply chain risk hinges on Andean cold-chain gaps creating temperature-break exposure in secondary Colombian and Peruvian distribution. Distribution runs through direct manufacturer-to-restaurant contracts displacing traditional wholesale intermediaries in Brazil's southeastern corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's sodium disclosure mandates and labeling modernization are erecting compliance moats that favor incumbent processors with established clean-label R&D infrastructure and testing protocol investments.
For Market Incumbents: To counter mid-scale Brazilian manufacturers adopting modular quick-freezing tunnel systems, anchor food service relationships through guaranteed temperature-controlled delivery metrics and accelerate backward integration into specialized high-yield potato breeding programs. Prioritize ANVISA-compliant batch certification ahead of full enforcement timelines to lock in quick-service chain supplier panel consolidation.
For New Entrants and Emerging Players: Direct-to-convenience-store digital ordering platforms offer the most penetrable route around entrenched distributor networks, targeting Brazilian urban freezer-door expansion with portion-controlled single-serve formats absent from traditional bulk channels. Colombian premium retail white space outside Bogotá and Medellín metros presents secondary geography with underexploited sweet potato variant margins.
For Investors and Strategic Acquirers: Exit pathways concentrate in cold-chain logistics controllers and clean-label formulation leaders with dual Brazil-Argentina certification efficiency. Long-term viability favors processors with captive supply of tropical-storage potato varieties and direct procurement contract density with São Paulo restaurant groups. Monitor ANVISA enforcement timeline acceleration as the inflection signal for compliant batch premium realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Blanching Automation Deployment | Continuous 85-95°C par-fry systems standardize cellular structure preservation for São Paulo restaurant groups. |
| Cold-Chain Logistics Certification | Temperature-controlled delivery metrics dominate supplier selection alongside unit pricing in Brazilian procurement. |
| Clean-Label Reformulation Investment | ANVISA sodium disclosure mandates force breading and pre-salt recipe redesigns across production facilities. |
| Direct Procurement Contract Capture | Manufacturer-to-restaurant agreements displace traditional distributor intermediaries in southeastern Brazil. |
| Specialized Variety Breeding Program | High-yield potatoes bred for tropical storage conditions reduce yield-risk concentration from climate volatility. |
Research Approach
Independent corroboration across food service procurement directors, cold-chain logistics operators, and regulatory compliance officers underwrites the qualitative findings. Primary fieldwork encompassed interviews with Brazilian quick-service chain menu development leads, Mexican distributor network managers, and ANVISA regulatory affairs specialists. Secondary validation drew from COFEPRIS formulation disclosure filings, Mercosur trade integration documentation, and customs records tracking frozen potato cross-border flows. Bottom-up volume estimates from processing facility throughput combined with top-down food service channel expenditure analysis.
Rate-of-change decomposition across the analysis window separates volume expansion from price-mix effects and channel shift contributions. Segmentation dimensions modeled include product formulation type, distribution channel structure, end-user operational scale, and packaging format requirements. CAGRs derived from logistic curve fitting to historical penetration rates, adjusted for cold-chain infrastructure investment trajectories and quick-service restaurant densification patterns. Industry-specific forecast inputs incorporate ANVISA compliance timeline assumptions and tropical storage yield variance projections.
The model holds under sustained cold-chain infrastructure investment and stable regulatory enforcement timelines; deviation in ANVISA acceleration or Andean logistics disruption would shift volume realization patterns. Forecasts reflect documented assumptions regarding par-fry technology adoption curves and direct procurement contract penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Frozen Baby Food Market
Processed and Frozen Foods
Frozen Desserts Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
Frozen Food Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Frozen French Fries Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Smoked Salmon Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
South America Freeze Dried Products Market