
 Global Frozen Fish and Seafood Market | 2026-2036
Global Frozen Fish and Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Global Frozen Fish and Seafood Market Intelligence
Premium-grade IQF and blast-frozen specifications is rotating toward the center of procurement decisions for institutional buyers. Leroy Seafood Group leverages its integrated aquaculture-to-retail chain to sustain margin capture across Atlantic salmon. Trident Seafoods anchors Alaskan pollock supply through shore-based processing dominance. Thai Union Frozen Products controls global shrimp sourcing networks that extend into private-label retail across Europe.
Frozen fish and seafood encompasses finfish, crustaceans, and mollusks preserved at temperatures below minus 18 degrees Celsius to halt microbial activity and maintain nutritional integrity; blast freezing and individual quick freezing preserve cellular structure for texture retention upon thawing, serving foodservice and retail channels requiring year-round supply consistency. Frozen salmon occupies the highest margin pool among product type categories due to aquaculture volume reliability and brand recognition. Foodservice application channels lead volume throughput, while retail vacuum-pack formats capture growing home-meal-preparation demand. Supermarkets and hypermarkets within the customer type dimension dominate procurement scale, though specialty stores differentiate through provenance labeling and MSC certification.
FDA HACCP mandates and EU IUU Regulation enforcement shape import compliance costs and documentation intensity for cross-border frozen seafood trade. China's SAMR food safety standards and GB frozen product specifications govern market access for foreign suppliers targeting domestic distribution. Japan's METI cold-chain guidelines and JIS quality benchmarks influence premium segment specifications across Asia-Pacific procurement. Stakeholders must monitor evolving traceability mandates and carbon-accounting requirements that will reshape supplier qualification criteria and logistics partner selection.
Market Dynamics
Cold-chain infrastructure reliability is consolidating procurement authority among institutional buyers who now demand blast-frozen specifications and full traceability documentation as baseline qualification criteria.
Growth Catalysts
- EU IUU Regulation enforcement:Importers are investing in blockchain-enabled traceability systems to satisfy catch documentation requirements, creating technology upgrade cycles across European distribution networks.
- Foodservice channel expansion:North American restaurant chains are standardizing frozen seafood SKUs to reduce waste and stabilize protein costs across seasonal demand fluctuations.
- Urban China consumption pivot:Tier-one city households are substituting fresh wet-market purchases with value-added frozen fillets as retail cold-chain penetration reaches supermarket doorstep delivery.
Market Restraints
- Input cost volatility:Wild-catch feedstock prices fluctuate with North Atlantic quota allocations and Peruvian anchovy harvest variability, compressing processor margins on commodity whitefish.
- Supply concentration risk:Alaskan pollock and Norwegian Atlantic salmon production clusters face single-point vulnerability from climate-driven stock migration and disease outbreak.
- Technical limitation:Texture degradation in slow-frozen crustaceans limits premium positioning against fresh alternatives in sushi-grade applications.
Strategic Opportunities
- Underpenetrated India market:Cold-chain infrastructure gaps in secondary cities present first-mover advantage for blast-frozen shrimp distributors targeting emerging middle-class protein demand.
- Regulatory tailwind from EU Green Deal:Carbon-accounting disclosure requirements favor suppliers with verified low-carbon aquaculture operations and shore-based processing energy efficiency.
- Direct-to-institution platforms:B2B procurement marketplaces are disintermediating traditional wholesale layers for hospital and university foodservice contracts.
Industry Challenges
- Certification timeline compression:MSC and ASC chain-of-custody audits require 12-18 month implementation cycles that delay market entry for new supplier qualification.
- Skill scarcity in cold-chain logistics:Refrigerated transport operators face qualified technician shortages for maintaining minus-18 Celsius integrity across multi-modal handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Frozen Fish and Seafood Market |
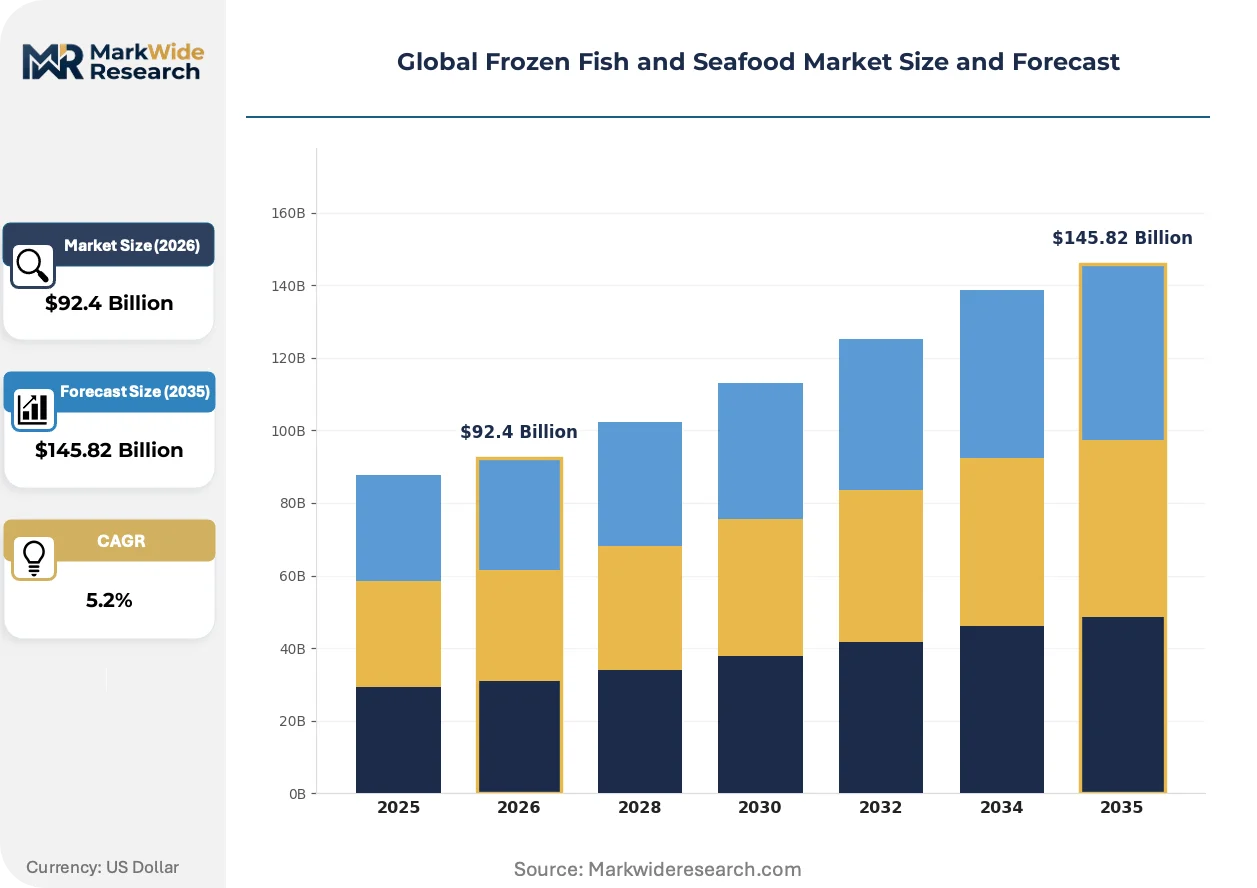
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $145.82 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Shrimp, Frozen Salmon, Frozen Cod, Frozen Squid, Frozen Crab Application: Foodservice, Retail, Hospitality, Catering, Institutional Kitchens Packaging Type: Vacuum Pack, Tray Pack, Bulk Bags, Poly Bags, Box Pack Customer Type: Supermarkets, Hypermarkets, Seafood Distributors, Wholesalers, Specialty Stores |
| Companies Covered | Leroy Seafood Group, Austevoll Seafood ASA, Mowi ASA, Trident Seafoods Corp., Grieg Seafood ASA, Thai Union Frozen Products, Iglo Group, Nutreco N.V., High Liner Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Frozen Fish and Seafood Market Strategic Shifts & Innovations
Processing technology and regulatory transparency mandates are redistributing competitive advantage toward vertically integrated operators with captive cold-chain assets and real-time traceability infrastructure.
High-pressure processing for shellfish shucking and pathogen reduction is fragmenting traditional thermal-processing equipment markets. Premium retail brands in Japan and South Korea are adopting HPP-treated crab and lobster meat to extend shelf life without texture compromise. This technology is fragmenting capital expenditure patterns as mid-scale processors defer blast-freezer investments in favor of outsourced HPP tolling arrangements.
EU CSRD sustainability reporting requirements and the F-Gas Regulation phase-down are forcing cold-storage operators to retrofit ammonia-CO2 cascade systems or face operational penalties. Norwegian and Scottish salmon processors are consolidating energy audits to qualify for green financing instruments tied to Scope 3 disclosure. The premium branded segment is absorbing compliance costs through provenance-marketing premiums rather than volume discounting.
Home-meal-preparation demand is rotating vacuum-pack retail formats toward portion-controlled, sauce-accompanied SKUs that displace foodservice occasions. German and UK supermarket private-label buyers are specifying individually quick-frozen marinated fillets that reduce consumer preparation steps. This behavioral shift concentrates shelf-space negotiations around meal-solution merchandising rather than commodity protein pricing.
Global Frozen Fish and Seafood Market Segmentation
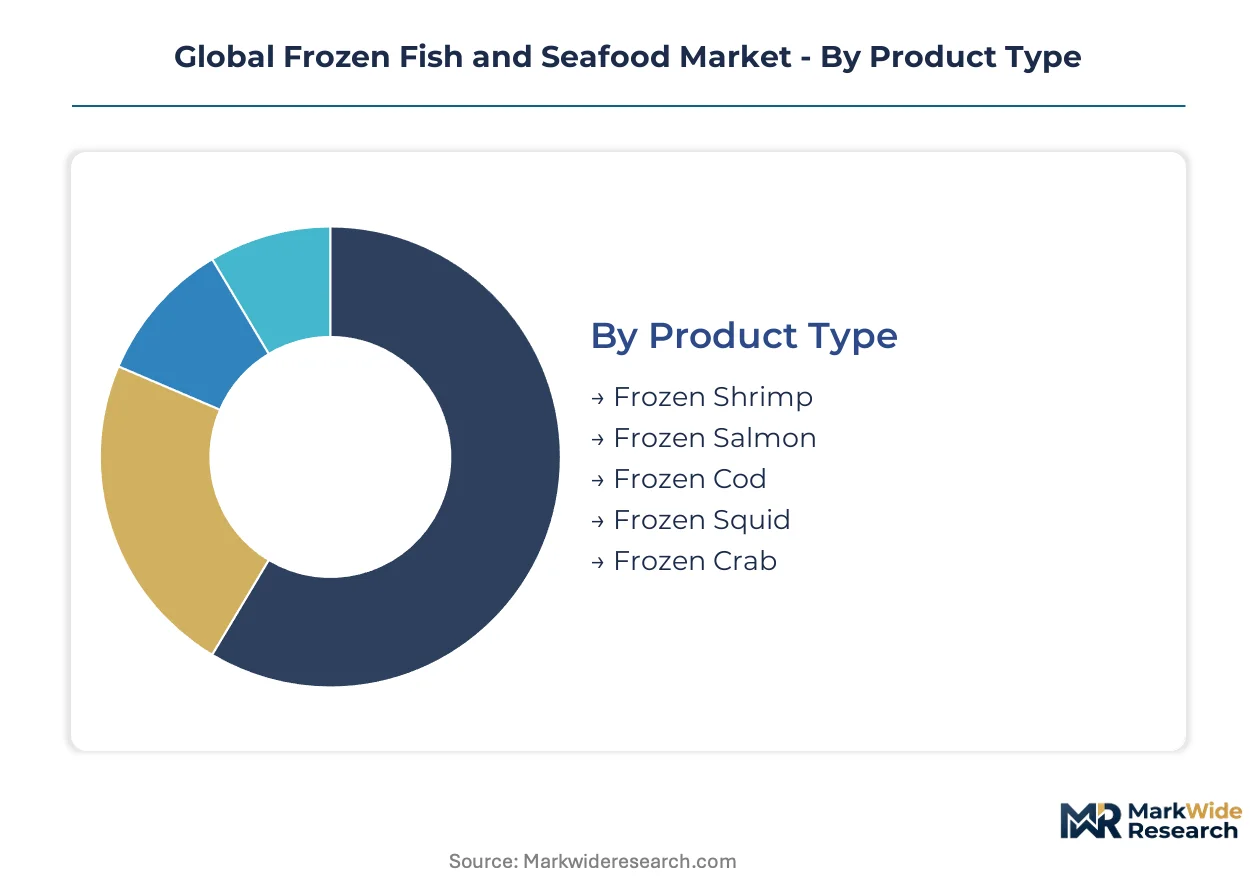
Segmentation in frozen fish and seafood reveals how cold-chain capabilities and regulatory compliance reshape procurement authority across distinct buyer profiles. Each dimension exposes different margin pools and qualification barriers.
Product Type:
FDA HACCP and EU IUU Regulation enforcement create divergent compliance burdens across species categories, with aquaculture-origin products facing distinct documentation intensity versus wild-catch alternatives.
- Frozen Salmon:Aquaculture volume reliability from Norwegian and Chilean farms supports year-round supply consistency. Foodservice chains in the United States specify blast-frozen Atlantic salmon fillets for menu standardization, absorbing premium positioning through brand recognition and MSC certification premiums.
- Frozen Shrimp:Individual quick freezing preserves cellular structure for texture retention in value-added retail applications. Urban China households in Shanghai and Beijing substitute wet-market purchases with IQF peeled shrimp as cold-chain penetration reaches supermarket doorstep delivery.
- Frozen Cod:North Atlantic quota allocations constrain wild-catch feedstock availability for commodity whitefish processors.
- Frozen Squid:Argentine and Chinese distant-water fleets supply raw material for tube-and-tentacle retail packs.
- Frozen Crab:High-pressure processing adoption in Japan and South Korea extends shelf life for HPP-treated king crab meat.
Established volume favors frozen salmon; emerging adoption favors frozen shrimp.
Application:
Channel-specific cold-chain requirements concentrate procurement authority among operators with captive logistics assets or verified third-party qualification.
- Foodservice:North American restaurant chains standardize frozen seafood SKUs to reduce waste and stabilize protein costs across seasonal demand fluctuations. Hospital and university contracts are migrating toward B2B procurement marketplaces that disintermediate traditional wholesale layers.
- Retail:German and UK supermarket private-label buyers specify individually quick-frozen marinated fillets that reduce consumer preparation steps. Vacuum-pack formats capture home-meal-preparation demand through portion-controlled, sauce-accompanied SKUs.
- Hospitality:Cruise line and resort procurement demands full traceability documentation as baseline qualification criteria.
- Catering:Event-service operators prioritize bulk bag formats for volume throughput in banquet applications.
- Institutional Kitchens:Government and military contracts specify blast-frozen specifications with extended shelf-life requirements.
Foodservice commands procurement scale; retail captures margin expansion through value-added formats.
Packaging Type:
Packaging selection reflects the tension between shelf-life extension, portion control, and logistics efficiency across distribution channels.
- Vacuum Pack:Oxygen-barrier films extend shelf life for retail premium positioning while reducing freezer burn incidence in home storage environments.
- Tray Pack:Modified atmosphere configurations support supermarket fresh-frozen merchandising with visible product presentation.
- Bulk Bags:Foodservice distributors specify 10-20 kg poly-lined formats for institutional kitchen portion control and inventory efficiency.
- Poly Bags:Economy retail positioning in emerging markets relies on cost-optimized single-layer construction.
- Box Pack:Export logistics favor corrugated containment with gel-pack insulation for intermodal cold-chain integrity.
Bulk bags dominate foodservice throughput; vacuum packs capture retail premiumization.
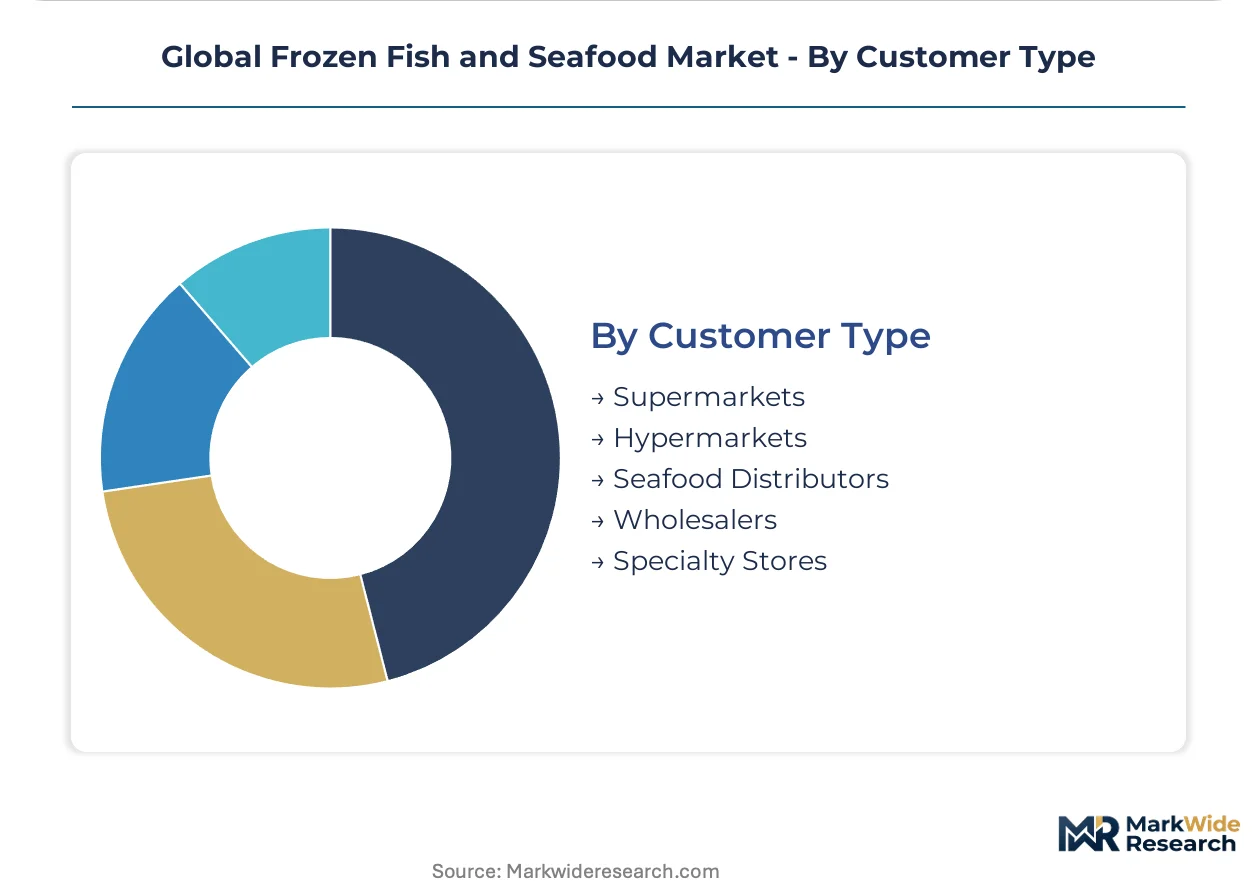
Customer Type:
Buyer scale and certification requirements fragment procurement patterns across mass-market and differentiated channels.
- Supermarkets:Private-label buyers in Germany and the United Kingdom negotiate directly with processors for marinated fillet specifications, displacing traditional wholesale intermediaries. Meal-solution merchandising concentrates shelf-space negotiations around preparation convenience rather than commodity protein pricing.
- Hypermarkets:Volume concentration in French and Spanish retail chains supports dedicated freezer aisle allocation for value-added frozen seafood.
- Seafood Distributors:Independent operators face margin compression from integrated aquaculture-to-retail chains that bypass wholesale layers.
- Wholesalers:Traditional merchant distributors retain relevance in secondary city penetration where cold-chain gaps persist.
- Specialty Stores:Provenance labeling and MSC certification differentiation command price premiums in Japanese and South Korean urban markets.
Supermarkets absorb procurement scale; specialty stores extract certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major trading blocs, with surplus nations leveraging aquaculture scale while deficit markets absorb cold-chain investments to reduce import dependency.
United States
Foodservice chains in California and Texas standardize frozen salmon SKUs to stabilize protein costs across seasonal fluctuations. FDA HACCP mandates shape import compliance intensity for Asian whitefish shipments entering West Coast ports. Seattle-based processors anchor Alaskan pollock supply through shore-based infrastructure dominance.
China
Urban households in Shanghai and Beijing substitute wet-market purchases with value-added frozen fillets as doorstep delivery cold-chains mature. SAMR food safety standards and GB frozen product specifications govern market access for foreign suppliers targeting domestic distribution. Qingdao and Dalian processing clusters concentrate shrimp IQF capacity for European export contracts.
Norway
Aquaculture volume reliability from Atlantic salmon farms supports year-round supply consistency for German and UK retail buyers. EU Green Deal carbon-accounting requirements favor Norwegian processors with verified low-carbon operations and shore-based energy efficiency. Bergen and Trondheim clusters consolidate green financing qualification through Scope 3 disclosure consolidation.
Japan
Premium retail brands adopt high-pressure processing for crab and lobster meat to extend shelf life without texture compromise. METI cold-chain guidelines and JIS quality benchmarks influence procurement specifications across Asia-Pacific institutional buyers. Tokyo and Osaka metropolitan markets command provenance-labeling premiums for MSC-certified frozen seafood.
Germany
Supermarket private-label buyers negotiate directly with processors for marinated fillet specifications, displacing traditional wholesale intermediaries. EU CSRD sustainability reporting requirements and F-Gas Regulation phase-down force cold-storage retrofit toward ammonia-CO2 cascade systems. Hamburg and Bremerhaven logistics hubs absorb compliance costs through meal-solution merchandising premiums rather than volume discounting.
Global Frozen Fish and Seafood Market Key Industry Players
Listed leaders compete with private specialists across aquaculture-to-retail integration depth, creating a tiered structure where scale-driven public companies anchor volume contracts while family-owned operators capture niche certification premiums. Strategic archetypes include integrated aquaculture-to-retail chains, shore-based wild-catch processors, and global shrimp sourcing network controllers. Dominant competitive moves center on backward integration into feedstock supply and B2B marketplace disintermediation targeting institutional foodservice contracts.
Within the integrated aquaculture tier, Leroy Seafood Group and Mowi ASA exemplify Norwegian-listed operators with captive cold-chain assets spanning hatchery to retail shelf. Trident Seafoods Corp. anchors the North American wild-catch processor archetype through Alaskan pollock shore-based infrastructure. Thai Union Frozen Products occupies the global sourcing network position, extending shrimp supply control into European private-label retail channels.
| Leading Market Players |
|---|
| Leroy Seafood Group |
| Austevoll Seafood ASA |
| Mowi ASA |
| Trident Seafoods Corp. |
| Grieg Seafood ASA |
| Thai Union Frozen Products |
| Iglo Group |
| Nutreco N.V. |
| High Liner Foods |
| Others |
Cost & Logistics Intelligence
Blast-freezing technology substitution for traditional slow-freezing methods is redrawing supply geography toward Norwegian and Chilean salmon clusters while compressing margin pools for commodity whitefish processors unable to fund capital upgrades. This equipment transition simultaneously concentrates pricing power among integrated aquaculture-to-retail chains and erodes spot-market leverage for independent merchant distributors.
Pricing Analysis
Foodservice chains anchor contract-based long-term offtake structures that stabilize protein costs across seasonal fluctuations. Price differentiation separates MSC-certified premium fillets from commodity ungraded blocks, with volume scale and cold-chain reliability as secondary tiering factors. Cost compression in commodity whitefish is intensifying because North Atlantic quota constraints tighten feedstock availability. Small-scale regional distributors exhibit highest price sensitivity; integrated retail chains absorb modest premiums for traceability documentation.
Supply Chain Analysis
Container availability constraints on the Asia-Europe trade lane are forcing inventory positioning shifts among shrimp importers. Supply concentrates in Norway, Chile, and Vietnam for salmon and shrimp feedstock, with raw material dependencies on fishmeal from Peruvian anchovy harvests, soy protein concentrates, and aquaculture antibiotics. Single-source vulnerability from climate-driven stock migration in North Atlantic waters threatens supply continuity. Distribution runs through captive cold-chain assets of integrated processors rather than independent wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled traceability platforms are redefining supplier qualification as an interoperability standard, with EU IUU Regulation enforcement creating network-effect advantages for early platform adopters.
For Market Incumbents: Compound data-asset advantages by extending blockchain traceability infrastructure downstream into foodservice procurement portals. Deepen upstream control over hatchery operations to secure feedstock against climate-driven quota volatility. MSC certification investment defends margin position against private-label encroachment in German and UK retail channels.
For New Entrants and Emerging Players: ASC chain-of-custody fast-track programs open qualification pathways for mid-scale shrimp processors targeting European retail. Underpenetrated secondary cities in India present white-space opportunity for blast-frozen distributors with mobile cold-chain units. Direct-to-institution B2B platforms offer go-to-market angle that bypasses entrenched wholesale intermediaries.
For Investors and Strategic Acquirers: Capital is best deployed toward shore-based processing operators with verified low-carbon footprints qualifying for EU Green Deal financing instruments. Long-term viability hinges on Scope 3 disclosure consolidation and ammonia-CO2 cascade retrofit completion. Watch for inflection in carbon-accounting mandate enforcement timelines as signal for accelerated M&A consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Platform Deployment | EU IUU Regulation enforcement rewards early adopters with preferred supplier status in European retail. |
| Backward Integration into Hatchery Operations | Norwegian and Chilean salmon clusters secure volume reliability against climate-driven stock migration. |
| High-Pressure Processing Capacity Addition | Japanese and South Korean premium brands extend shelf life for crab and lobster without texture compromise. |
| Ammonia-CO2 Cascade Cold-Storage Retrofit | German operators absorb F-Gas Regulation penalties through meal-solution merchandising premiums. |
| Direct-to-Institution B2B Marketplace Launch | North American hospital and university contracts disintermediate traditional wholesale distribution layers. |
Research Approach
Desk research of customs trade databases, aquaculture production statistics, and regulatory filing repositories preceded structured interviews with cold-chain logistics operators, seafood procurement managers at foodservice chains, retail category buyers, and aquaculture farm managers. Primary fieldwork validated secondary estimates through bottom-up triangulation against top-down trade flow analysis.
Variance decomposition across product type, application channel, packaging format, and customer segment dimensions shaped analytical framework construction throughout the projection horizon. CAGRs derived from segment-level volume trajectories and price elasticity modeling incorporated feedstock quota allocations, cold-chain penetration curves, and certification adoption rates as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained cold-chain infrastructure investment, stable regulatory enforcement timelines, or unimpeded trade lane access would require recalibration. Forecasts reflect documented assumptions regarding aquaculture volume growth, wild-catch quota stability, and traceability technology adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Chilled Soup Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Canned Vegetables Market
Processed and Frozen Foods
Frozen Basil Leaves Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
Frozen Baby Food Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Dumplings Market