
 Europe Dehydrated Food Market | 2026-2036
Europe Dehydrated Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dehydrated Food Market Foresight
Food service procurement is recalibrating toward dehydrated ingredients as operators seek resilience against energy price volatility and cold-chain disruption. Nestlé S.A. leverages its pan-European manufacturing footprint to supply standardized dehydrated bases to institutional kitchens. European Freeze Dry Ltd. specializes in premium freeze-dried fruit segments for bakery and confectionery channels. Arla Foods amba anchors dairy-adjacent dehydration through its whey and milk powder operations across Nordic and Central European markets.
Dehydrated food encompasses products from which moisture content has been reduced to typically below 10 percent through thermal drying, freeze-drying, or osmotic processes, yielding lightweight shelf-stable inputs for reconstitution or direct incorporation. The primary commercial purpose centers on extending storage duration, reducing transport mass, and enabling formulation flexibility across prepared food manufacturing. Fruit and vegetable powders command structural priority within product type segmentation due to their integration into clean-label formulations and infant nutrition applications. Snacks represent the fastest-growing product type as air-dried and vacuum-fried formats displace conventional fried alternatives in retail assortments. Online sales channels are deepening penetration into residential consumers through subscription-based emergency preparedness and outdoor recreation kits.
EFSA purity standards and EU Green Deal sustainability disclosures are reshaping ingredient sourcing requirements, compelling processors to document water recycling and renewable energy use in dehydration facilities. REACH chemical safety protocols govern residual solvent limits in extracted flavor carriers used alongside dehydrated bases. The EU F-Gas Regulation is accelerating equipment replacement in freeze-drying operations, altering capital deployment timelines for capacity expansion. Stakeholders must monitor evolving Ecodesign requirements for industrial drying equipment and assess whether carbon border adjustment mechanisms will redirect sourcing of tropical dehydrated inputs toward certified supply chains.
Market Dynamics
Energy cost volatility across Central and Eastern European processing zones is compressing operating margins for thermal dehydration facilities, forcing operators toward heat-pump retrofits and renewable energy sourcing to maintain throughput economics.
Growth Catalysts
- EU Green Deal carbon accounting mandates:Food manufacturers face Scope 3 disclosure requirements that favor dehydrated inputs with documented low-carbon processing footprints, accelerating substitution for frozen alternatives in ready-meal formulations.
- Industrial bakery automation:Automated dosing systems for fruit and vegetable powders enable precise moisture control in high-speed production lines, reducing waste and batch inconsistency across German and Polish facilities.
- Nordic emergency preparedness stockpiling:Civil defense agencies in Sweden, Finland, and Norway are expanding strategic reserves of shelf-stable nutrition, creating institutional demand for long-duration dehydrated meal components.
Market Restraints
- Natural gas price exposure:Convection and drum drying operations remain tethered to natural gas feedstocks, with facilities in Netherlands and Belgium facing input cost swings that erode contract pricing stability.
- Freeze-drying equipment concentration:Vacuum chamber and refrigeration system suppliers cluster in Germany and Switzerland, creating procurement bottlenecks for capacity expansion timelines.
- Sensory degradation thresholds:Thermal processes above 60°C compromise volatile aromatic compounds in herb and spice matrices, limiting application scope in premium culinary segments.
Strategic Opportunities
- Romanian and Bulgarian agricultural zones:Underutilized fruit and vegetable growing regions offer proximity advantages for new dehydration facilities serving Southeast European markets with reduced transport mass.
- Plant-based meat analog binders:Dehydrated pea and potato protein isolates are gaining traction as texturizing agents, opening formulation partnerships with alternative protein manufacturers in Netherlands and UK.
- CSRD supply chain transparency rules:Early compliance with corporate sustainability reporting requirements enables premium positioning for dehydrated ingredients with verified water stewardship and renewable energy credentials.
Industry Challenges
- Freeze-drying technician scarcity:Specialized knowledge of sublimation curve optimization and vacuum system maintenance is concentrated among aging workforces in Alpine regions, constraining operational scale-up.
- EFSA novel food authorization timelines:Emerging dehydration methods using ultrasonic or infrared technologies face multi-year safety assessment queues, delaying commercial deployment of efficiency-improving processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dehydrated Food Market |
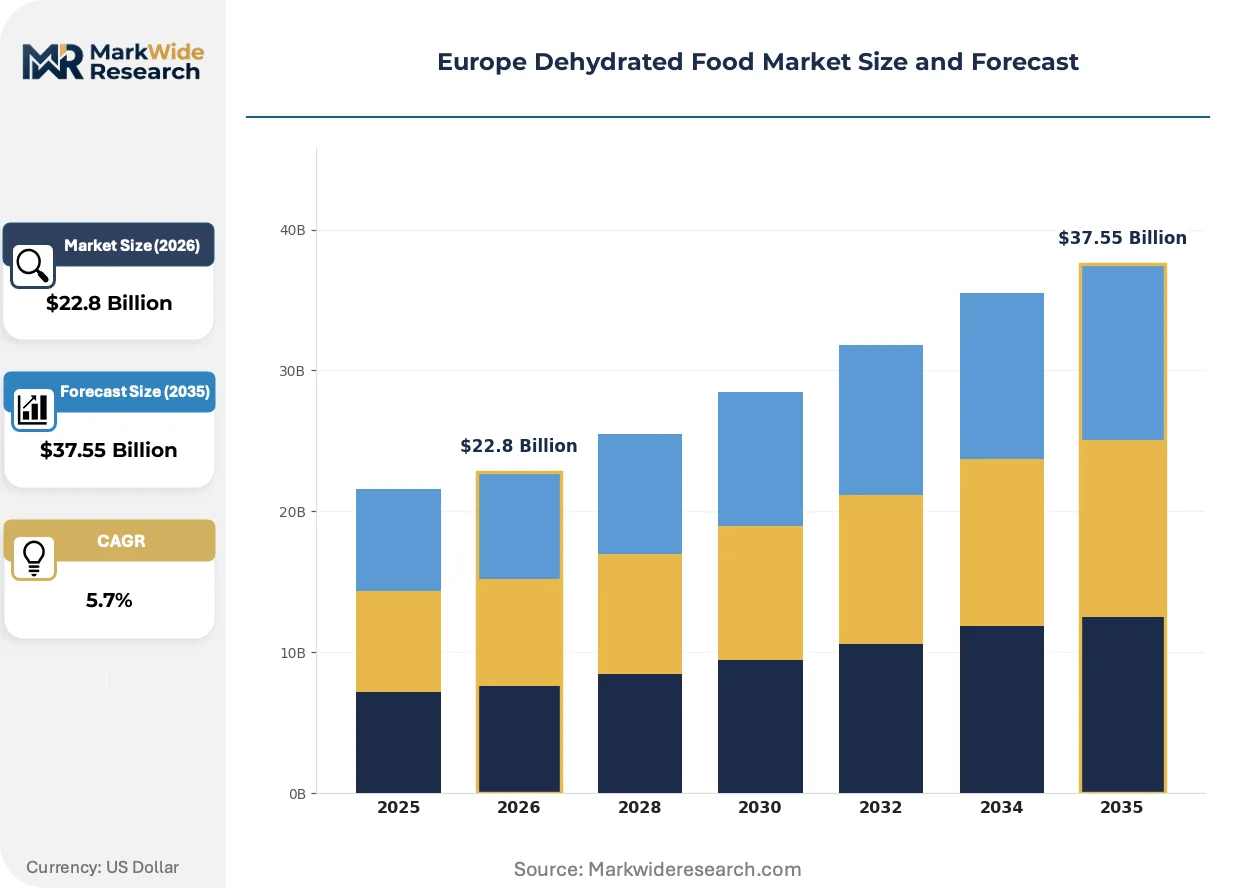
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $37.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Meals, Snacks End User: Residential Consumers, Food Service, Retail, Catering Sales Channel: Online, Supermarkets, Specialty Stores, Convenience Stores Packing Type: Bags, Pouches, Tins, Jars |
| Companies Covered | Nestlé S.A., Arla Foods amba, Asahi Group Holdings Ltd., European Freeze Dry Ltd., Olam Group, Symrise AG, Ajinomoto Co. Inc., Unilever PLC, Lyo Food Sp. z o.o., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dehydrated Food Market Shifts & Advancements
Processing technology convergence with renewable energy systems is redefining facility economics, while regulatory disclosure requirements and shifting procurement patterns reshape competitive positioning across ingredient tiers.
Hybrid solar-thermal drying arrays are unifying photovoltaic generation with convection dehydration in Spanish and Italian fruit processing cooperatives. Mid-scale operators in Valencia and Sicily are adopting these integrated systems to reduce grid dependency during peak harvest windows. The technology is unifying energy cost hedging with carbon footprint reduction in sustainability-sensitive supply contracts.
REACH chemical safety protocols are tightening residual solvent limits for extraction processes used in flavor carrier production alongside dehydrated bases. Manufacturers must now validate hexane and ethanol removal rates through expanded testing regimes. The regulation most acutely affects spice and herb processors in France and Italy supplying compound seasoning blends to industrial food manufacturers.
Food service operators are consolidating supplier relationships around vertically integrated dehydration houses capable of certifying full chain-of-custody documentation. Single-source contracting is displacing fragmented multi-vendor procurement in institutional catering and airline meal segments. This concentration is most visible in German and UK contract catering, where Sodexo and Compass Group affiliates demand batch-level traceability for allergen management.
Europe Dehydrated Food Market Segmentation
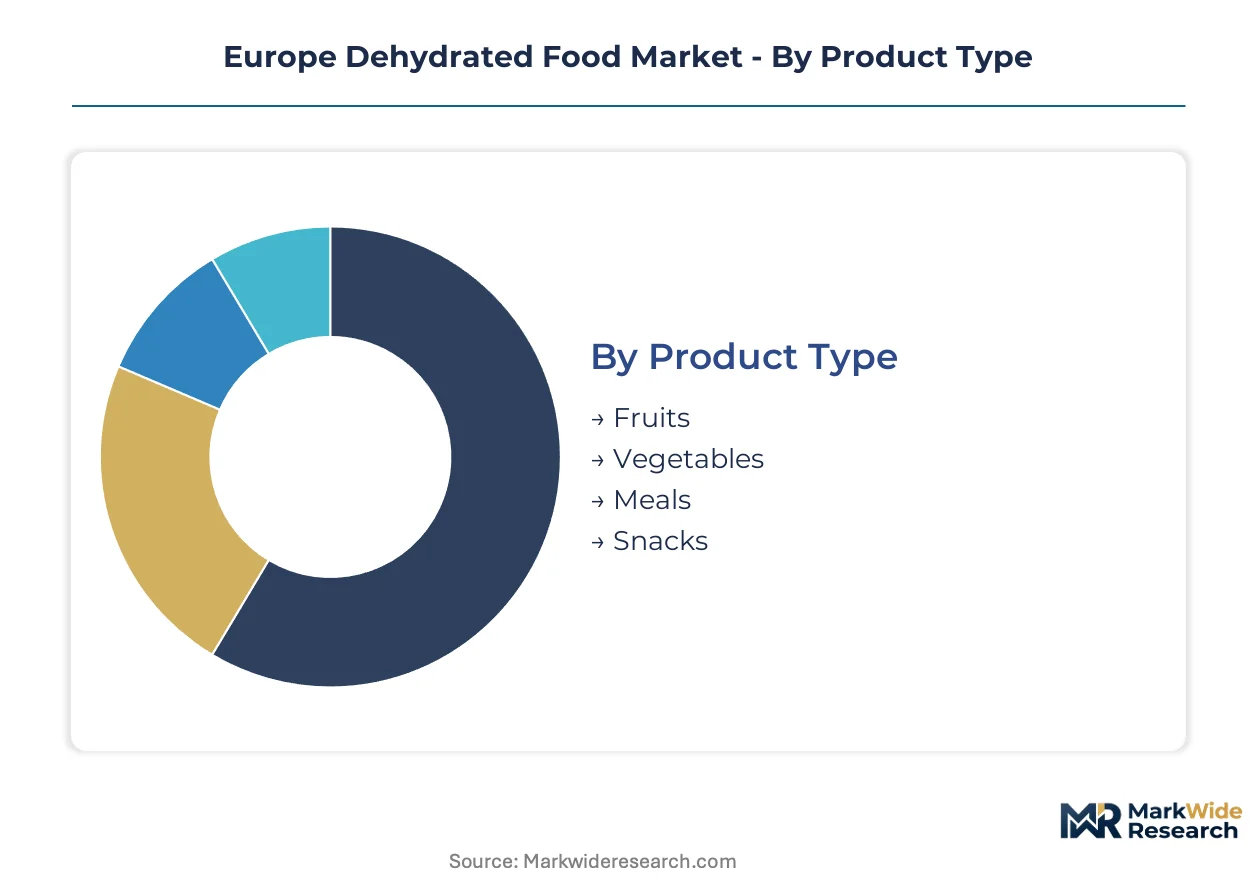
Segmentation in the Europe Dehydrated Food Market reveals divergent margin structures across product formats and channel economics. Procurement patterns vary sharply between institutional buyers optimizing for shelf stability and residential consumers prioritizing convenience and sensory appeal.
Product Type:
Volume concentration sits with commodity powders, while premium pricing attaches to intact-structure formats.
- Fruits:Freeze-dried berries and tropical segments retain cellular structure for premium bakery and confectionery applications. German industrial bakeries anchor procurement of strawberry and raspberry powders for clean-label filling formulations.
- Vegetables:Dehydrated onion, garlic, and tomato powders serve as foundational flavor carriers across ready-meal manufacturing. Polish and Hungarian processing facilities supply bulk quantities to Central European soup and sauce producers facing EFSA additive restrictions.
- Meals:Complete dehydrated dishes target emergency preparedness and outdoor recreation segments with extended shelf-life claims.
- Snacks:Air-dried and vacuum-fried fruit and vegetable crisps displace conventional fried alternatives in retail assortments.
Mature deployment sits with vegetable powders in industrial formulations. Newer deployment is concentrated in snack formats gaining shelf space in German and UK supermarkets.
End User:
Procurement scale separates institutional buyers from fragmented residential demand.
- Food Service:Contract caterers and institutional kitchens source standardized dehydrated bases for portion control and allergen management. Compass Group and Sodexo affiliates in Germany and the UK demand batch-level traceability documentation.
- Catering:Airline and event catering operations prioritize lightweight meal components to reduce transport mass and handling complexity.
- Residential Consumers:Subscription-based emergency preparedness kits and outdoor recreation packs drive online channel penetration.
- Retail:Private-label dehydrated ingredients occupy middle-shelf positioning between premium freeze-dried and economy thermal-dried alternatives.
Established volume flows through food service procurement. Residential subscription models represent the steepest expansion trajectory.
Sales Channel:
Channel economics diverge between direct-to-consumer subscription mechanics and retail slotting fee structures.
- Online:Direct-to-consumer platforms capture emergency preparedness and outdoor recreation segments through subscription bundling. Nordic civil defense stockpiling programs route through specialized procurement portals.
- Supermarkets:Mainstream retail chains in Germany, France, and the UK allocate expanding shelf space to private-label dehydrated snacks and cooking ingredients.
- Specialty Stores:Gourmet and health-focused retailers curate premium freeze-dried fruit selections for clean-label conscious consumers.
- Convenience Stores:Limited assortment formats stock single-serve dehydrated meal cups targeting urban commuter demand.
Traditional strength rests with supermarket distribution. Digital channel infrastructure is deepening fastest in German and Nordic markets.
Packing Type:
Packaging format selection tracks moisture sensitivity and resealability requirements across use cases.
- Pouches:Flexible laminated structures dominate snack and meal kit applications with high barrier properties against oxygen and light degradation.
- Bags:Bulk powder formats for industrial bakery and ready-meal manufacturing utilize multi-wall paper and polyethylene constructions.
- Tins:Metal canisters preserve volatile aromatic compounds in premium herb and spice segments for extended duration.
- Jars:Glass packaging supports visual product assessment in specialty retail channels for freeze-dried fruit presentations.
Industrial procurement favors bag formats for handling efficiency. Pouch configurations are gaining share fastest in consumer-facing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Special Economic Zones attract dehydration equipment manufacturers with tax holidays and infrastructure subsidies, concentrating thermal processing capacity near Warsaw and Łódź. These zones anchor Central European supply chains for vegetable powder exports.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia drive bulk procurement of fruit powders for clean-label formulations. The EU Green Deal's Scope 3 disclosure rules pressure manufacturers to document renewable energy use in dehydration facilities. Stuttgart-based equipment suppliers cluster around freeze-drying vacuum chamber production.
United Kingdom
Contract caterers demand batch-level traceability for allergen management in institutional meal programs. CSRD supply chain transparency requirements accelerate documentation investments by ingredient processors. Yorkshire houses specialty freeze-dried fruit operations serving premium confectionery channels.
Netherlands
Plant-based meat analog manufacturers source dehydrated pea protein isolates as texturizing agents. The F-Gas Regulation forces accelerated replacement of refrigeration systems in freeze-drying operations. Wageningen anchors research partnerships between food technology institutes and dehydration equipment developers.
Spain
Valencia fruit cooperatives deploy hybrid solar-thermal drying arrays to reduce grid dependency during peak harvest windows. EFSA purity standards reshape sourcing requirements for imported tropical inputs. Murcia's vegetable processing belt supplies dehydrated tomato and pepper powders to Mediterranean ready-meal manufacturers.
Sweden
Civil defense agencies expand strategic reserves of shelf-stable nutrition, creating institutional demand for long-duration meal components. REACH chemical safety protocols govern residual solvent limits in extraction processes. Skåne hosts Nordic emergency preparedness procurement portals routing dehydrated ingredient contracts.
Europe Dehydrated Food Market Competitive Landscape
Top-tier vendors anchor diversified food conglomerate positions, while mid-scale specialists occupy technology-specific niches. The market structure splits between pan-European ingredient suppliers with integrated dehydration divisions and focused freeze-drying houses serving premium segments. Strategic archetypes include conglomerate nutrition platforms, Alpine equipment-technology integrators, and agricultural cooperative processors. Competitive moves concentrate on backward integration into raw material sourcing and heat-pump retrofit partnerships with energy service companies.
Within the diversified nutrition platform tier, Nestlé S.A. and Unilever PLC represent archetypal scale advantages in standardized base supply to institutional kitchens. European Freeze Dry Ltd. occupies a position among technology-specialist operators, while Arla Foods amba anchors dairy-adjacent dehydration through milk powder operations across Nordic markets. These three exemplify how geographic footprint breadth and processing technology depth determine competitive positioning under tightening EFSA and EU Green Deal compliance requirements.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Arla Foods amba |
| Asahi Group Holdings Ltd. |
| European Freeze Dry Ltd. |
| Olam Group |
| Symrise AG |
| Ajinomoto Co. Inc. |
| Unilever PLC |
| Lyo Food Sp. z o.o. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap processors across Poland and Hungary anchor supply discipline through patient capital deployment, insulating contract pricing from short-term energy volatility while squeezing spot-market traders lacking backward integration into agricultural sourcing.
Pricing Analysis
Short lead-time premiums attach to freeze-dried fruit orders from German industrial bakeries facing just-in-time production schedules, while spot inventory of thermal-dried vegetable powders trades at discounts in Polish wholesale markets. Three-tier pricing structure across premium freeze-dried, standard air-dried, and economy drum-dried levels stratifies by moisture uniformity and volatile aromatic retention. Cost compression in thermal processing tiers is intensifying because natural gas price exposure erodes contract pricing stability in Netherlands and Belgian facilities. Retail private-label buyers exhibit highest price sensitivity, whereas institutional caterers prioritize batch-level traceability over unit cost.
Supply Chain Analysis
Workforce availability constraints in Alpine regions concentrate freeze-drying technician expertise among aging populations in Switzerland and southern Germany, limiting operational scale-up for vacuum chamber expansion. Geographic supply concentration centers on Poland, Hungary, and Spain for thermal dehydration capacity, with Germany and Switzerland anchoring freeze-drying equipment production. Raw material dependencies draw from seasonal fruit harvests in Valencia and Murcia, vegetable belts in Poland, and imported tropical inputs subject to EFSA purity verification. Single-source vulnerability sits with German-Swiss vacuum chamber suppliers creating procurement bottlenecks. Distribution runs through vertically integrated dehydration houses consolidating supplier relationships for institutional catering traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeze-drying equipment scarcity props pricing power for incumbent operators, constraining supply response to demand expansion across premium bakery and confectionery channels.
For Market Incumbents: Acquire distressed thermal dehydration assets in Romanian and Bulgarian agricultural zones to secure proximity advantages for Southeast European market supply. Anchor capacity addition in solar-thermal integrated facilities to hedge energy cost volatility under EU Green Deal carbon accounting mandates. Consolidate backward integration into fruit and vegetable sourcing to defend margin position against commodity spot traders lacking captive supply. For New Entrants and Emerging Players: Capture white-space demand in plant-based meat analog texturizing agents through dehydrated pea and potato protein isolate partnerships with Netherlands and UK alternative protein manufacturers. Target Nordic civil defense procurement portals routing emergency preparedness stockpiling contracts. Penetrate through CSRD compliance-as-a-service positioning, offering verified water stewardship and renewable energy documentation to premium ingredient buyers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale solar-thermal integrated cooperatives in Valencia and Sicily with harvest-window grid independence and sustainability-sensitive supply contracts. Long-term viability hinges on equipment-technology integrators capable of heat-pump retrofit partnerships with energy service companies. Monitor EFSA novel food authorization timelines for ultrasonic and infrared dehydration methods as inflection signal for process efficiency disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Retrofit Partnership | Energy service company alliances enable margin defense against natural gas volatility in Central European thermal facilities. |
| CSRD Compliance Certification | Early water stewardship and renewable energy documentation unlocks premium positioning under corporate sustainability reporting rules. |
| Alpine Technician Training Program | Workforce development in sublimation curve optimization addresses scarcity constraining freeze-drying operational scale-up. |
| Solar-Thermal Array Integration | Photovoltaic-convection unification reduces grid dependency for Valencia and Sicily fruit cooperatives during peak harvest. |
| Novel Food Authorization Pipeline | EFSA pre-submission engagement accelerates commercial deployment of ultrasonic and infrared dehydration efficiency gains. |
Research Methodology
Trade association filings, EU regulatory databases, and customs export records formed the secondary backbone for volume and trade flow calibration. Primary interviews with dehydration plant managers, procurement leads at German industrial bakeries, contract catering operators, and specialty freeze-drying equipment engineers combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up modeling tracked product-level throughput across fruit powders, vegetable bases, and intact-structure formats, while top-down validation cross-checked against food service procurement spend and retail channel inventory data. Segmentation dimensions spanned product type, end-user archetype, sales channel mechanics, and packaging format moisture sensitivity. CAGRs derived from installed capacity expansion timelines, regulatory compliance cost trajectories, and substitution elasticity between dehydrated and frozen alternatives. Forecast inputs incorporated EU Green Deal Scope 3 disclosure adoption curves and F-Gas Regulation equipment replacement schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to energy price volatility, EFSA novel food authorization delays, and carbon border adjustment mechanism implementation on tropical input sourcing. Forecasts reflect assumptions around regulatory timeline adherence and technology adoption rates without guarantee. Material deviation in natural gas price regimes or freeze-drying equipment supplier delivery schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Frozen Yogurt Market
Processed and Frozen Foods
North America French Fries Market
Processed and Frozen Foods
Dehydrated Food Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
Frozen Mushroom Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Taiyaki Ice Cream Market