
 Frozen Noodles and Rice Products Market | 2026-2036
Frozen Noodles and Rice Products Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Noodles and Rice Products Market Insights
EU F-Gas Regulation is recalibrating capital requirements for blast freezer retrofits across European production facilities. Toyo Suisan Kaisha leverages its integrated noodle manufacturing network to control raw wheat sourcing costs. Nissin Foods Holdings anchors its competitive position through R&D intensity in flash-freezing technology. Thai President Foods dominates Southeast Asian distribution channels with specialized regional flavor portfolios.
Frozen noodles and rice products comprise pre-cooked or par-cooked starchy foods preserved at sub-zero temperatures through individual quick freezing or blast freezing, maintaining texture via rapid ice crystal formation for microwave or stovetop reconstitution. The category serves commercial foodservice operators and retail consumers seeking shelf-stable meal solutions with minimal preparation time. Frozen noodles leads product type contribution due to entrenched consumption patterns across East Asian markets, while frozen dumplings represents the fastest-growing segment driven by premiumization in Western retail channels. Online stores distribution channel is capturing disproportionate growth as direct-to-consumer cold chain logistics mature, though supermarkets retain the deepest margin pools through private label penetration.
FDA oversees frozen food safety standards in the United States through Hazard Analysis Critical Control Point enforcement, while EFSA governs additive limits and labeling requirements across European markets. Japan's Food Sanitation Act and JIS standards further define microbiological thresholds for exported frozen noodle products. China's SAMR implements GB standards for frozen starch product classification and shelf-life declaration. Stakeholders must monitor evolving cold chain energy regulations as jurisdictions tighten emissions standards for refrigeration infrastructure.
Market Dynamics
Blast freezing technology is forcing capital reallocation across production networks as energy efficiency mandates tighten operational parameters for frozen starch product manufacturers.
Growth Catalysts
- Quick-service restaurant expansion:Southeast Asian foodservice chains are scaling frozen noodle procurement to offset rising labor costs in urban centers.
- F-Gas Regulation compliance:The EU's phasedown of hydrofluorocarbon refrigerants is accelerating equipment upgrade cycles in European blast freezing facilities.
- Flash-freezing R&D intensity:Japanese manufacturers are deploying advanced cryogenic tunnel systems to preserve noodle texture through controlled ice crystal formation.
Market Restraints
- Wheat price volatility:Raw grain input costs fluctuate with Black Sea supply disruptions and climate-induced harvest variability.
- Cold chain infrastructure gaps:Last-mile refrigerated logistics remain underdeveloped in secondary Indonesian and Vietnamese cities.
- Fresh noodle substitution:Wet noodle producers in East Asian urban markets compete on perceived quality and shorter ingredient lists.
Strategic Opportunities
- Direct-to-consumer cold chain maturation:Online grocery platforms in South Korea and Japan are building dedicated frozen food fulfillment networks.
- Industrial food processing zone clustering:Thailand's Bangkok periphery zones offer consolidated freezing, packaging, and port access for export-oriented manufacturers.
- SAMR shelf-life standardization:China's updated GB classification framework creates compliance clarity for foreign entrants targeting retail distribution.
Industry Challenges
- Flash-freezing technician scarcity:Cryogenic system operation and maintenance expertise concentrates in Japanese and South Korean training pipelines.
- Blast freezer retrofit capex cycles:European producers face compressed timelines to replace HFC-dependent equipment before F-Gas phase-down deadlines.
- Multi-jurisdiction labeling harmonization:Divergent EFSA additive limits and FDA HACCP documentation requirements complicate cross-border product standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Noodles and Rice Products Market |
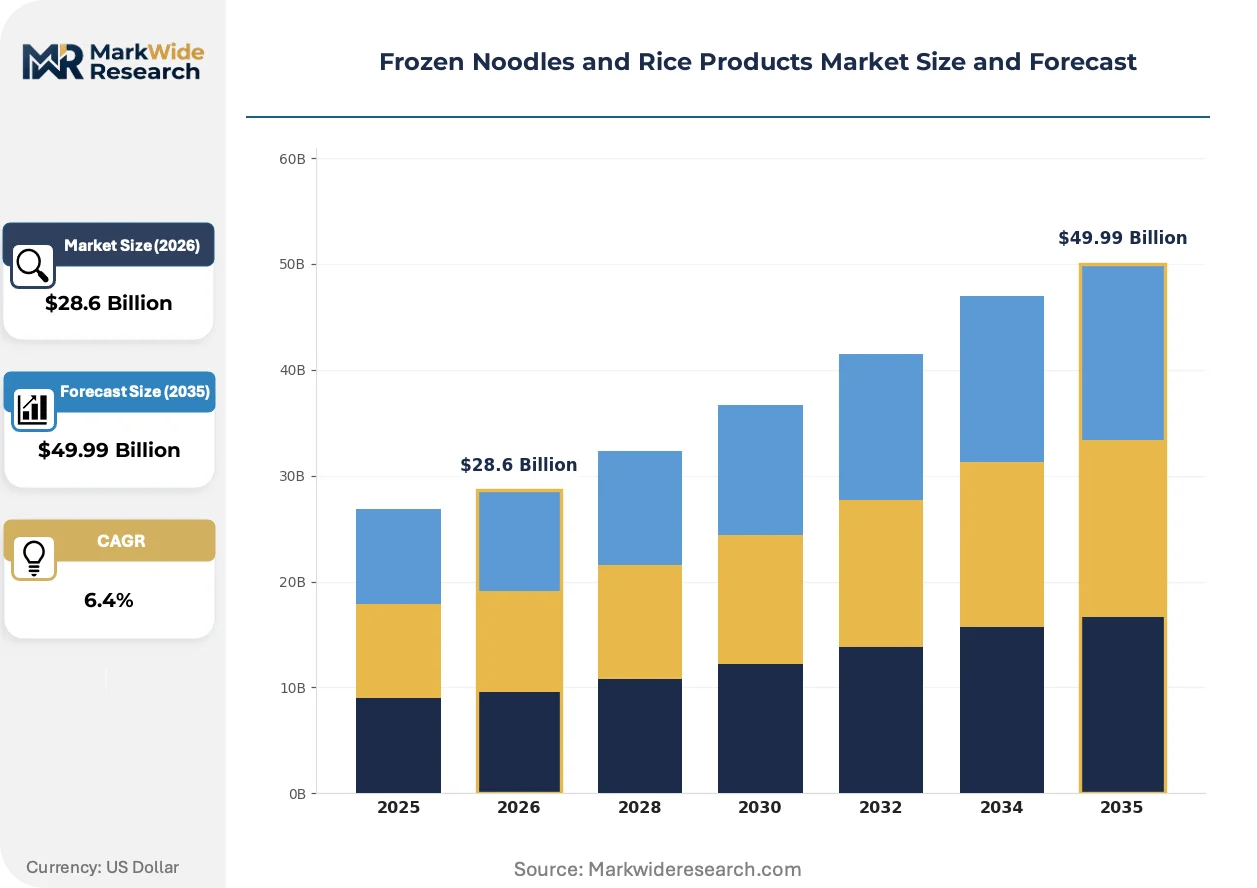
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Noodles, Frozen Rice, Frozen Dumplings, Frozen Spring Rolls End User: Restaurants, Food Services, Retail Consumers, Food Processors Distribution Channel: Supermarkets, Hypermarkets, Online Stores, Specialty Stores Packaging Type: Plastic Bags, Vacuum Packs, Boxes, Trays |
| Companies Covered | Toyo Suisan Kaisha, Thai President Foods, Nissin Foods Holdings, Charoen Pokphand Group, Nongshim, Ajinomoto, Nestlé, Sanquan Foods, CJ CheilJedang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Noodles and Rice Products Market Trends and Innovations
Individual quick freezing systems are consolidating control over texture preservation standards as microwave-ready meal formats expand across retail and foodservice channels.
Blast freezing equipment is consolidating around ammonia-CO2 cascade systems that slash energy consumption per ton of frozen product. Thai and Vietnamese processors are retrofitting facilities at accelerated pace to qualify for EU export certification. The technology is consolidating smaller producers into shared freezing cooperatives to amortize capital outlays.
REACH chemical safety protocols are extending scrutiny to food-contact materials in freezing and packaging equipment. European manufacturers must now document substance migration risks from conveyor belts and storage containers. Frozen dumpling exporters targeting EU retail channels are reformulating wrapper compositions to preempt authorization delays.
Foodservice procurement is compressing supplier lists as chain operators consolidate frozen noodle sourcing through approved vendor programs. Direct supplier relationships are displacing traditional wholesale intermediaries in South Korean and Taiwanese institutional channels. Quick-service operators in Bangkok and Seoul now specify flash-freezing certification as a mandatory qualification criterion.
Frozen Noodles and Rice Products Market Segmentation
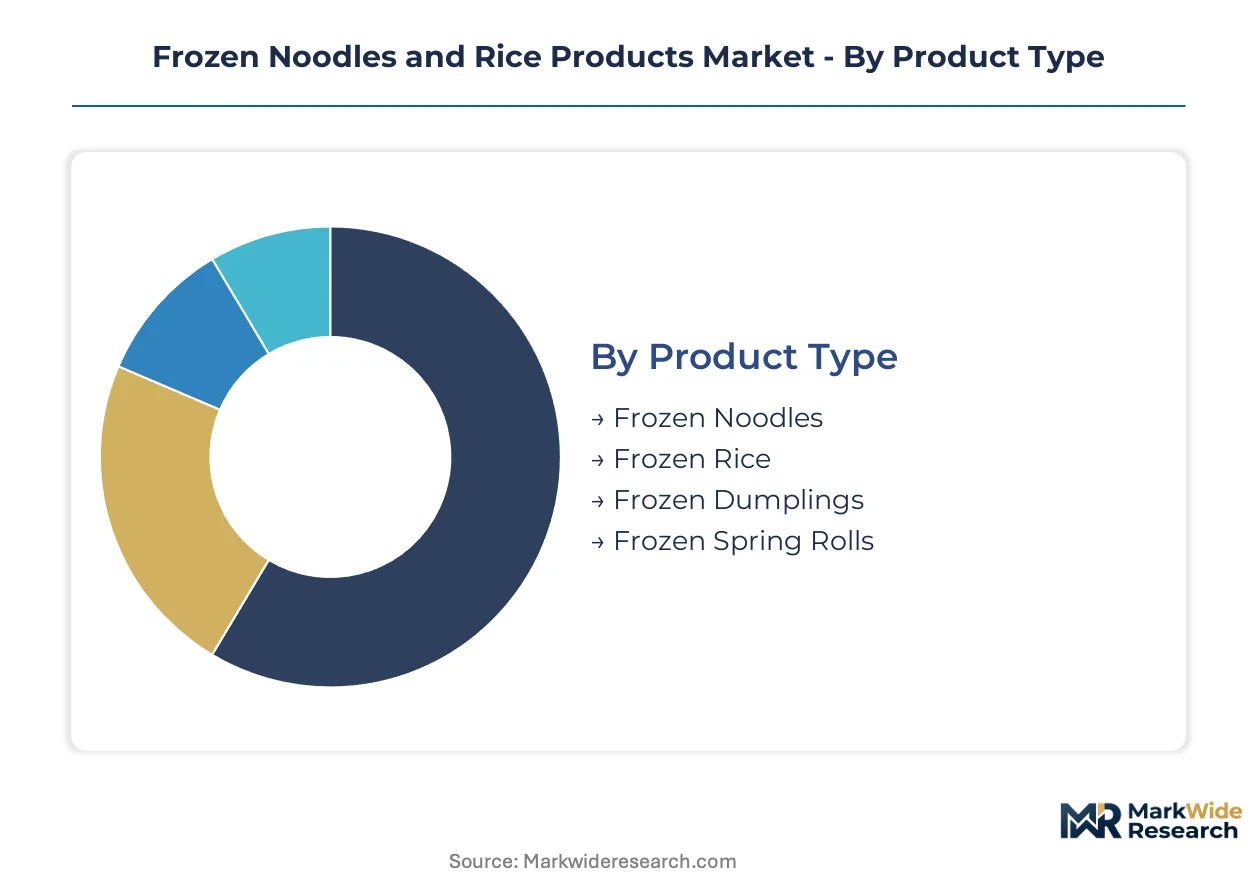
Frozen noodles and rice products fragment across four structural dimensions that determine margin capture and capital allocation. Product type and distribution channel together dictate cold chain investment intensity, while end-user concentration shapes regional production clustering.
Product Type:
Supply concentration in flash-freezing equipment tilts manufacturing capacity toward segments with the highest texture preservation requirements and foodservice penetration.
- Frozen Noodles:Par-cooked wheat or rice noodles flash-frozen through cryogenic tunnel systems to maintain elasticity upon reconstitution. Quick-service chains across Bangkok, Seoul, and Tokyo specify IQF certification for procurement contracts, locking in dedicated production lines at Thai and Japanese facilities.
- Frozen Dumplings:Stuffed wheat or rice wrappers with meat, seafood, or vegetable fillings requiring controlled ice crystal formation to prevent wrapper fracture. Premium retail channels in Western Europe and North America are absorbing capacity expansions as dumpling formats displace frozen pizza in weekly meal planning.
- Frozen Rice:Pre-cooked grain portions blast-frozen for institutional foodservice rethermalization.
- Frozen Spring Rolls:Rolled appetizers with varying wrapper compositions and filling densities.
Frozen noodles absorbs the bulk of installed capacity; frozen dumplings is expanding most quickly.
End User:
Cost tier differentiation separates high-volume institutional buyers from fragmented retail households with divergent price sensitivity and specification rigor.
- Restaurants:Independent and chain operators purchasing bulk-format frozen noodles for menu integration with minimal kitchen labor. Bangkok's Chinatown district and Seoul's Gangnam corridor concentrate procurement volume for hand-pulled noodle substitutes.
- Food Services:Institutional caterers, airline meal providers, and corporate dining contractors with standardized portion requirements. Japanese bento suppliers and Taiwanese convenience store chains specify frozen rice products with 180-day shelf stability for inventory rotation efficiency.
- Retail Consumers:Household purchasers selecting single-serve or family-pack formats through grocery channels.
- Food Processors:Industrial buyers incorporating frozen starch inputs into composite meal manufacturing.
Food services commands the deepest volume commitments; retail consumers is gaining share fastest through e-commerce channel maturation.
Distribution Channel:
Geography of cold chain maturity determines which channels can sustain frozen product integrity from production through final sale.
- Supermarkets:Conventional grocery retailers with dedicated frozen food aisles and private label penetration. South Korean Emart and Japanese Aeon chains operate captive blast freezing cooperatives that consolidate smaller noodle producers under uniform quality specifications.
- Online Stores:Direct-to-consumer platforms with emerging last-mile refrigerated logistics. South Korea's Coupang and Japan's Rakuten are building dedicated frozen fulfillment centers in Gyeonggi and Saitama prefectures to bypass traditional wholesale layers.
- Hypermarkets:Large-format retailers with bulk purchasing and extended frozen storage capacity.
- Specialty Stores:Ethnic grocery channels targeting diaspora populations with regional flavor authenticity.
Supermarkets retains the widest SKU breadth; online stores is climbing the fastest as dedicated cold chain infrastructure reaches secondary cities.
Packaging Type:
Margin structure correlates with barrier technology investment and shelf-life extension capability.
- Vacuum Packs:Oxygen-excluded flexible films extending frozen noodle shelf life while preventing freezer burn. Japanese manufacturers deploying multi-layer EVOH laminates for export shipments to EU markets facing REACH substance migration scrutiny.
- Trays:Rigid polypropylene containers with lidding films for microwave-ready meal formats. Thai President Foods and Nissin specification engineers favor tray formats for premium positioning in Japanese convenience store channels.
- Plastic Bags:Standard polyethylene pouches for commodity bulk frozen rice and noodle formats.
- Boxes:Corrugated or folding carton secondary packaging for retail shelf presentation.
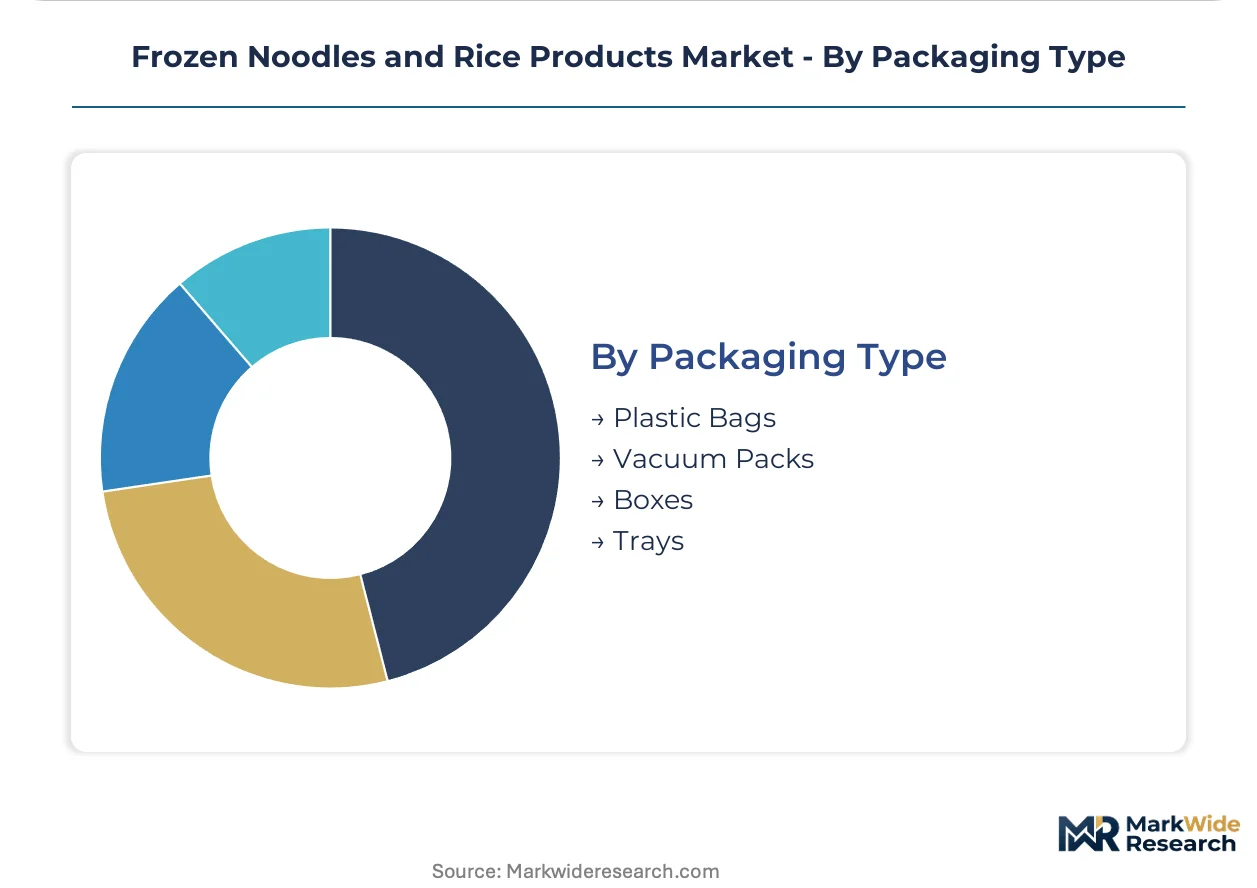
Vacuum packs dominates export-oriented production; trays is gaining share fastest through ready-meal premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand concentrates frozen noodle demand through Bangkok's quick-service restaurant density and export-oriented industrial zones. Japanese and South Korean consumers drive premium flash-frozen formats. European retrofit cycles accelerate under F-Gas compliance deadlines.
Thailand
Bangkok's Chinatown district and peripheral industrial zones anchor frozen noodle procurement for domestic foodservice and EU export channels. The country's Board of Investment incentivizes cold chain infrastructure through tax privileges for blast freezing cooperatives. Pathum Thani and Samut Prakan provinces cluster shared freezing facilities that consolidate smaller producers under uniform quality specifications.
Japan
Tokyo-Osaka corridor consumers sustain premium flash-frozen noodle demand through convenience store and bento supplier channels. METI enforces JIS standards for microbiological thresholds on exported frozen starch products. Kanto region manufacturers deploy cryogenic tunnel systems to preserve elasticity specifications for institutional buyers.
South Korea
Seoul Capital Area quick-service chains compress supplier lists through approved vendor programs specifying flash-freezing certification. MFDS regulates additive limits and shelf-life declarations for domestic retail distribution. Gyeonggi province hosts dedicated frozen fulfillment centers that bypass traditional wholesale layers for direct-to-consumer platforms.
Germany
Foodservice distributors across Bavaria and North Rhine-Westphalia accelerate blast freezer retrofits to meet F-Gas hydrofluorocarbon phasedown timelines. ECHA REACH protocols extend scrutiny to food-contact materials in freezing equipment. Baden-Württemberg processing facilities consolidate around ammonia-CO2 cascade systems that slash energy consumption per ton.
China
Yangtze River Delta and Pearl River Delta industrial zones absorb capacity expansions for frozen dumpling exports to Western retail channels. SAMR implements updated GB standards for frozen starch product classification and shelf-life declaration. Sichuan-Chongqing region processors target compliance clarity for foreign entrants navigating multi-jurisdiction labeling requirements.
Frozen Noodles and Rice Products Market Competitive Landscape
Japanese producers anchor one tier; Thai specialists hold export-oriented scale positions. The vendor base splits between integrated noodle manufacturers controlling upstream wheat sourcing and regional distributors with captive freezing cooperatives. Three archetypes dominate: flash-freezing technology specialists, private-label supermarket suppliers, and shared-facility cooperatives amortizing capital outlays. Competitive moves concentrate on equipment retrofit partnerships and direct-to-consumer cold chain investments.
Among Japan-based manufacturers, Nissin Foods Holdings and Toyo Suisan Kaisha occupy positions emphasizing R&D intensity in texture preservation systems. Thai President Foods represents the Southeast Asian distribution archetype with regional flavor portfolio specialization. Ajinomoto and CJ CheilJedang exemplify diversified food conglomerates with frozen starch segments integrated into broader meal solution portfolios.
| Leading Market Players |
|---|
| Toyo Suisan Kaisha |
| Thai President Foods |
| Nissin Foods Holdings |
| Charoen Pokphand Group |
| Nongshim |
| Ajinomoto |
| Nestlé |
| Sanquan Foods |
| CJ CheilJedang |
| Others |
Pricing and Supply Chain Analysis
Wheat futures volatility from Black Sea supply corridors feeds through frozen noodle pricing tiers, compressing margins at commodity-grade producers while flash-freezing specialists capture premium spreads through texture certification.
Pricing Analysis
Lead-time contracting separates frozen starch procurement into three distinct pricing bands: spot inventory trades at discounts for bulk frozen rice and standard-grade noodles, while certified IQF flash-frozen formats command premiums for two-week delivery windows. Price differentiation hinges on flash-freezing certification tier and volume commitment scale, with Bangkok quick-service chains showing lowest sensitivity due to labor-cost substitution calculus. Pricing pressure intensifies from ammonia-CO2 blast freezer retrofit capex cycles, forcing European producers to pass equipment amortization through contract renegotiations.
Supply Chain Analysis
Refrigerated container rates from Bangkok and Ho Chi Minh City to Rotterdam and Hamburg anchor landed cost calculations for Southeast Asian exporters targeting EU retail channels. Raw material flows draw from Australian and Canadian wheat belts, Thai rice paddies, and Chinese wrapper starch processors, creating multi-origin dependency chains. Single-source vulnerability concentrates in cryogenic tunnel system components sourced from Japanese and South Korean engineering houses. Distribution runs through Bangkok periphery freezing cooperatives consolidating smaller producers under uniform EU export specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
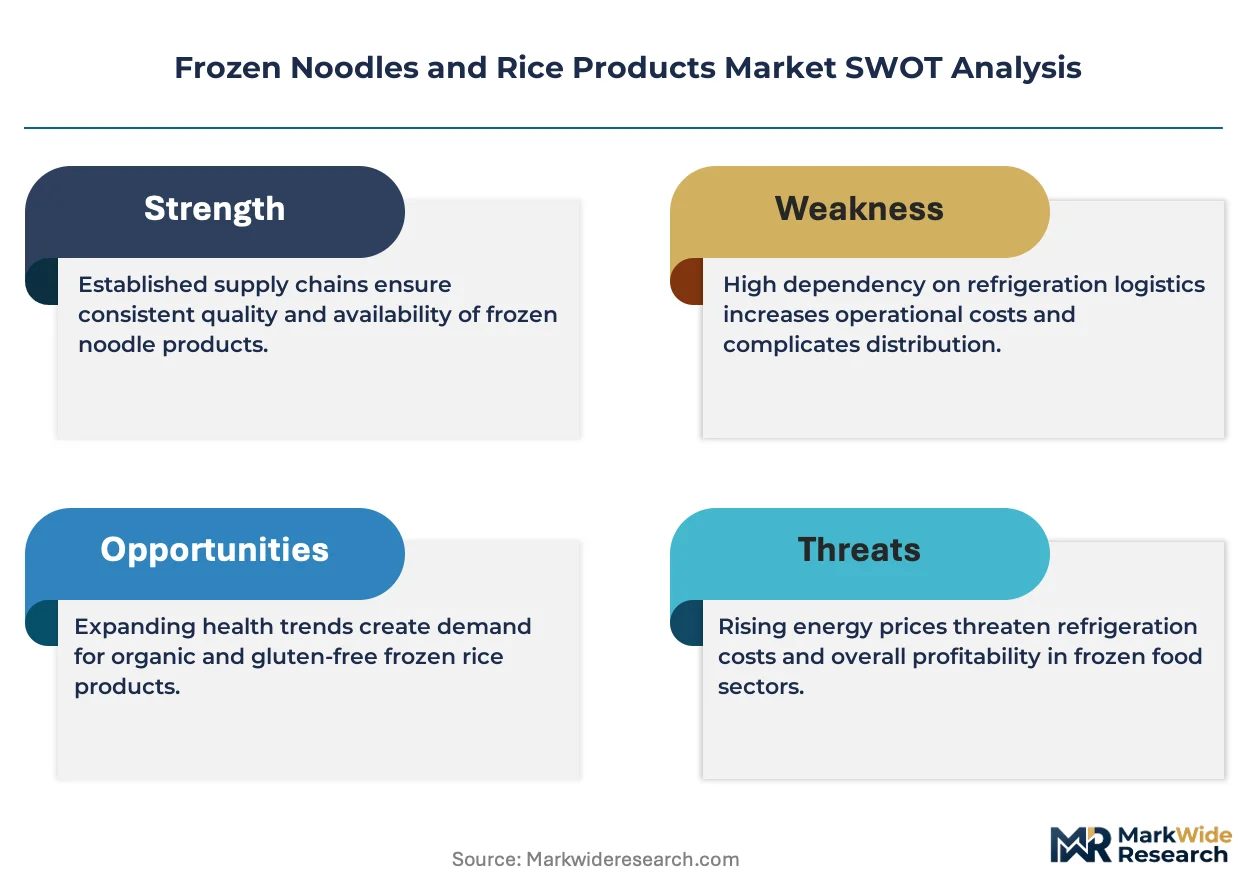
EU F-Gas compliance deadlines are compressing weaker European producers into distressed asset sales, creating acquisition opportunities for capital-rich Asian manufacturers with ammonia-CO2 retrofit expertise.
For Market Incumbents: Anticipate flash-freezing technician scarcity by locking exclusive training pipeline partnerships with South Korean technical institutes before competitor consolidation. Secure captive wheat sourcing through backward integration into Australian grain procurement or long-term offtake with Black Sea suppliers to buffer price volatility. Defend against fresh noodle substitution in Tokyo and Seoul convenience channels through R&D investment in sub-90-second microwave reconstitution formats. For New Entrants and Emerging Players: Cryogenic tunnel system leasing models offer a technology-first wedge into European retrofit demand without full capex exposure. Target Indonesia's secondary cities where last-mile cold chain gaps exclude incumbent frozen dumpling suppliers from retail penetration. Lead with direct-to-consumer subscription formats in South Korea's Gyeonggi province, bypassing wholesale layers that incumbent distributors control. For Investors and Strategic Acquirers: Thai Board of Investment tax privilege expiration announcements are the leading indicator that Bangkok periphery freezing cooperatives will face margin compression and consolidation pressure. Five-to-ten-year viability favors acquirers of distressed European blast freezing assets with EU export certification already in place. Watch for SAMR shelf-life standardization enforcement clarity as the signal that Chinese retail channel entry barriers are falling for foreign frozen starch brands.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-CO2 Blast Freezer Retrofit | EU F-Gas phasedown deadlines force equipment replacement cycles at German and Thai processing facilities. |
| Flash-Freezing Certification Investment | IQF credentials unlock procurement contracts with Bangkok and Seoul quick-service restaurant chains. |
| Direct-to-Consumer Cold Chain Buildout | South Korea's Coupang and Japan's Rakuten are constructing dedicated frozen fulfillment centers in Gyeonggi and Saitama. |
| Wheat Sourcing Backward Integration | Australian grain procurement partnerships buffer Black Sea supply disruption exposure for noodle manufacturers. |
| Shared Freezing Cooperative Formation | Pathum Thani and Samut Prakan provinces cluster smaller producers under uniform EU export quality specifications. |
Research Methodology
Multi-period observation of blast freezer equipment installation rates, wheat futures spreads, and EU F-Gas compliance filing timelines anchored the trend analysis, supplemented by interviews with frozen food plant managers, quick-service chain procurement directors, cold chain logistics operators, and EFSA regulatory affairs specialists. Secondary validation drew from customs trade databases, SEC filings of listed Asian food manufacturers, SAMR GB standard update notices, and Bangkok Board of Investment incentive disclosure records. Bottom-up capacity tallies across Thai and Japanese processing zones were triangulated against top-down demand estimates from foodservice procurement surveys.
Input-output matrices mapped frozen starch product flows across product type, end-user concentration, distribution channel maturity, and packaging technology tiers throughout the projection horizon. CAGRs were derived from segmented volume trajectory modeling incorporating flash-freezing equipment penetration rates, quick-service restaurant expansion pipelines, and online grocery cold chain investment disclosures. Industry-specific forecast inputs included ammonia-CO2 cascade system adoption curves and REACH substance migration protocol amendment tracking.
Several conditions sit outside the modeled scope, including unscheduled F-Gas regulation acceleration, Black Sea wheat export embargo extensions, and cryogenic coolant supply chain disruptions. Forecasts reflect documented assumptions about equipment replacement timelines and trade corridor stability. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Chilled Meal Kits Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
Freeze Dried Mangos Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
Frozen Soup Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market