
 South America RTE Food Market | 2026-2036
South America RTE Food Market Size, Share, and Industry Trends Forecast 2026-2036
South America RTE Food Market Analytics
Multi-source procurement for protein inputs is repositioning how Brazilian and Argentine processors secure supply. JBS leverages its vertically integrated beef and poultry operations to control raw material flows for frozen meal lines. BRF sustains dominance in chilled processed meats through dedicated cold-chain distribution. Nestlé Brasil Ltda anchors premium frozen meal growth via brand equity built on localized flavor portfolios.
Ready-to-eat food encompasses thermally processed, pre-cooked, or minimally prepared products requiring no further preparation beyond reheating, with shelf-life extension achieved through pasteurization, blast freezing, retort sterilization, or modified-atmosphere packaging at core temperatures between minus 18 and 4 degrees Celsius depending on category. Frozen meals lead value generation due to extended preservation windows and established retail penetration across Carrefour and GPA networks. Chilled meals represent the fastest-expanding product type as Brazilian consumers prioritize freshness indicators and shorter ingredient lists. Flexible packaging captures margin concentration through multilayer barrier films that reduce weight and extend shelf stability versus rigid alternatives.
Brazil's ANVISA enforces microbiological standards and labeling requirements that dictate reformulation timelines for sodium and preservative content. Argentina's national food code and Chile's front-of-package warning label law shape product development priorities and market access conditions across the Mercosur trade zone. Stakeholders must monitor evolving technical barriers to trade and alignment gaps between national food safety regimes as regional integration deepens.
Market Dynamics
ANVISA's updated food additive regulations are forcing Brazilian and Argentine processors to accelerate sodium reduction timelines and reformulate preservative systems across frozen and chilled meal portfolios.
Growth Catalysts
- Chilled meal freshness preference:Brazilian consumers in São Paulo and Curitiba are prioritizing shorter ingredient lists and visible freshness indicators, expanding the addressable market for high-turnover refrigerated SKUs.
- ANVISA microbiological standards alignment:Harmonized safety protocols across Mercosur are reducing cross-border technical barriers and enabling centralized production for multi-country distribution.
- Campinas-Curitiba processing corridor concentration:Proximity to southeastern Brazil's logistics infrastructure and cold-chain networks is lowering last-mile distribution costs for temperature-sensitive products.
Market Restraints
- Beef and poultry input cost volatility:JBS and BRF's captive supply chains insulate partially, but spot market protein prices swing with feed grain costs and export demand fluctuations.
- Argentina's national food code divergence:Labeling and additive restrictions that exceed Mercosur baselines create formulation complexity for regional product standardization.
- Modified-atmosphere packaging technical ceiling:Shelf-life extension for chilled meals hits practical limits at 21-28 days, constraining distribution radius expansion.
Strategic Opportunities
- Chile's front-of-package warning label compliance:Early reformulation to meet sodium and sugar thresholds opens preferential retail placement in Santiago's dominant supermarket networks.
- Flexible packaging barrier film convergence:Multilayer coextrusion with oxygen scavenger integration is reducing packaging weight 15-20% versus rigid trays while extending shelf stability.
- Ecuador and Peru underpenetration:Cold-chain infrastructure gaps in Andean cities present first-mover advantages for blast-frozen meal formats with ambient distribution tolerance.
Industry Challenges
- Retort sterilization technician scarcity:Qualified operators for high-pressure thermal processing equipment are concentrated in São Paulo state, constraining plant expansion in secondary Brazilian markets.
- Legacy ERP-cold chain integration complexity:Temperature monitoring systems from warehouse to retail require real-time data handoffs that many mid-tier distributors have not automated.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America RTE Food Market |
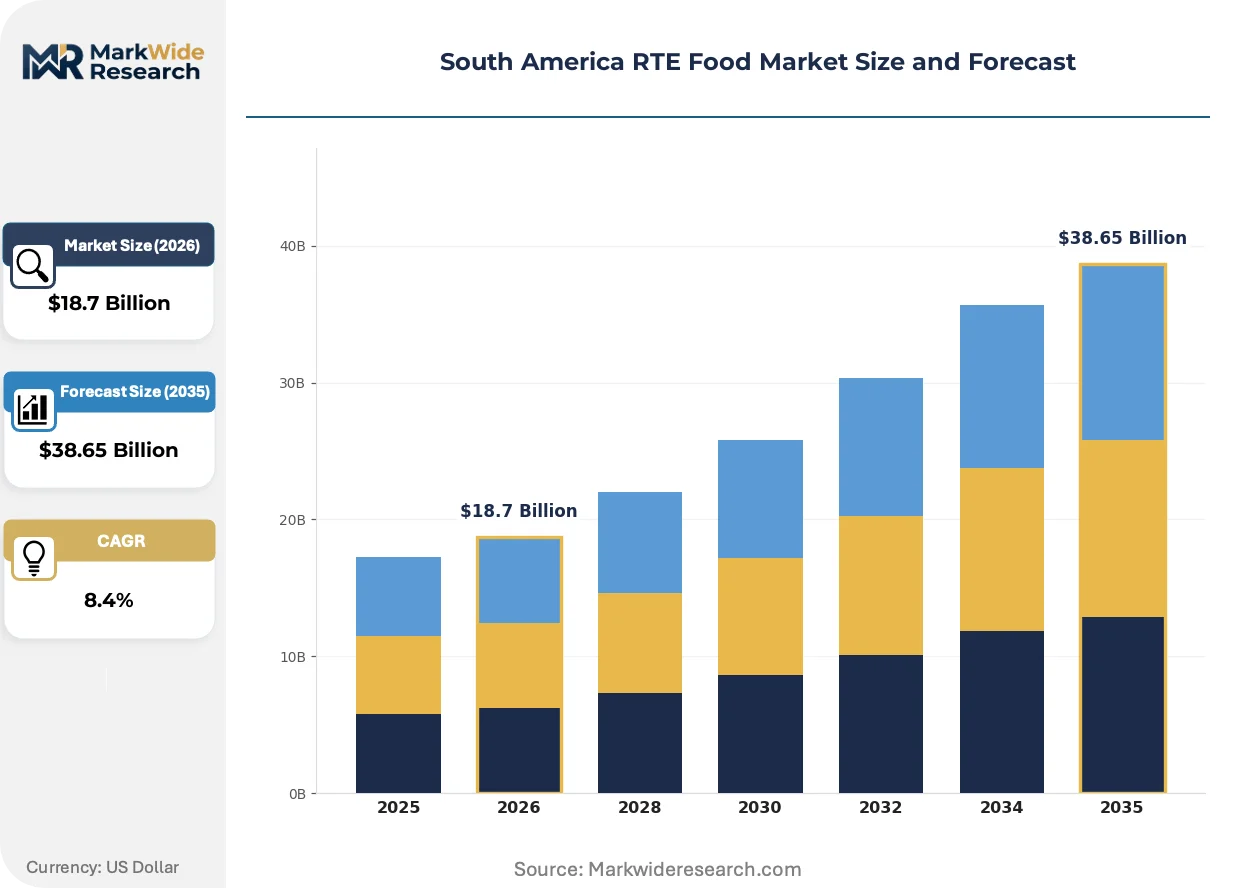
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Chilled Meals, Canned Foods, Snack Foods Packaging Type: Flexible Packaging, Rigid Packaging, Glass Bottles, Food Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Foodservice Customer Type: Millennials, Families, Working Professionals, Health-Conscious Consumers |
| Companies Covered | Nestlé Brasil Ltda, JBS, BRF, McCain Foods, Grupo Bimbo, Unilever, Arcor, Marfrig, Kraft Heinz Company, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America RTE Food Market Evolving Landscape
Refrigeration technology and packaging science are compressing the freshness-preservation tradeoff that has historically separated frozen from chilled meal positioning.
High-pressure processing is electrifying the chilled ready-meal segment by delivering pasteurization-level safety without thermal degradation of texture and flavor. Premium retailers in São Paulo's Pinheiros and Jardins districts are expanding HPP SKU counts 40% annually. The technology is compressing the traditional frozen-chilled quality gap and enabling 45-day chilled shelf lives that reshape distribution economics.
Chile's front-of-package warning label law is mandating reformulation across sodium, sugar, and saturated fat thresholds for all packaged foods. Manufacturers serving the Mercosur trade zone must maintain parallel SKU lines or adopt the stricter Chilean standard as their regional baseline. Chilled processed meats and frozen prepared meals face the steepest compliance curves given existing formulation architectures.
Urban working professionals in Buenos Aires and São Paulo are consolidating weekly food purchasing into single hypermarket trips while demanding daily meal variety. This tension is fragmenting the traditional frozen-stockpiling model and elevating subscription-based chilled meal delivery services. Argentine consumers show the strongest channel pivot, with same-day delivery platforms capturing prepared food occasions that supermarkets previously dominated.
South America RTE Food Market Segmentation
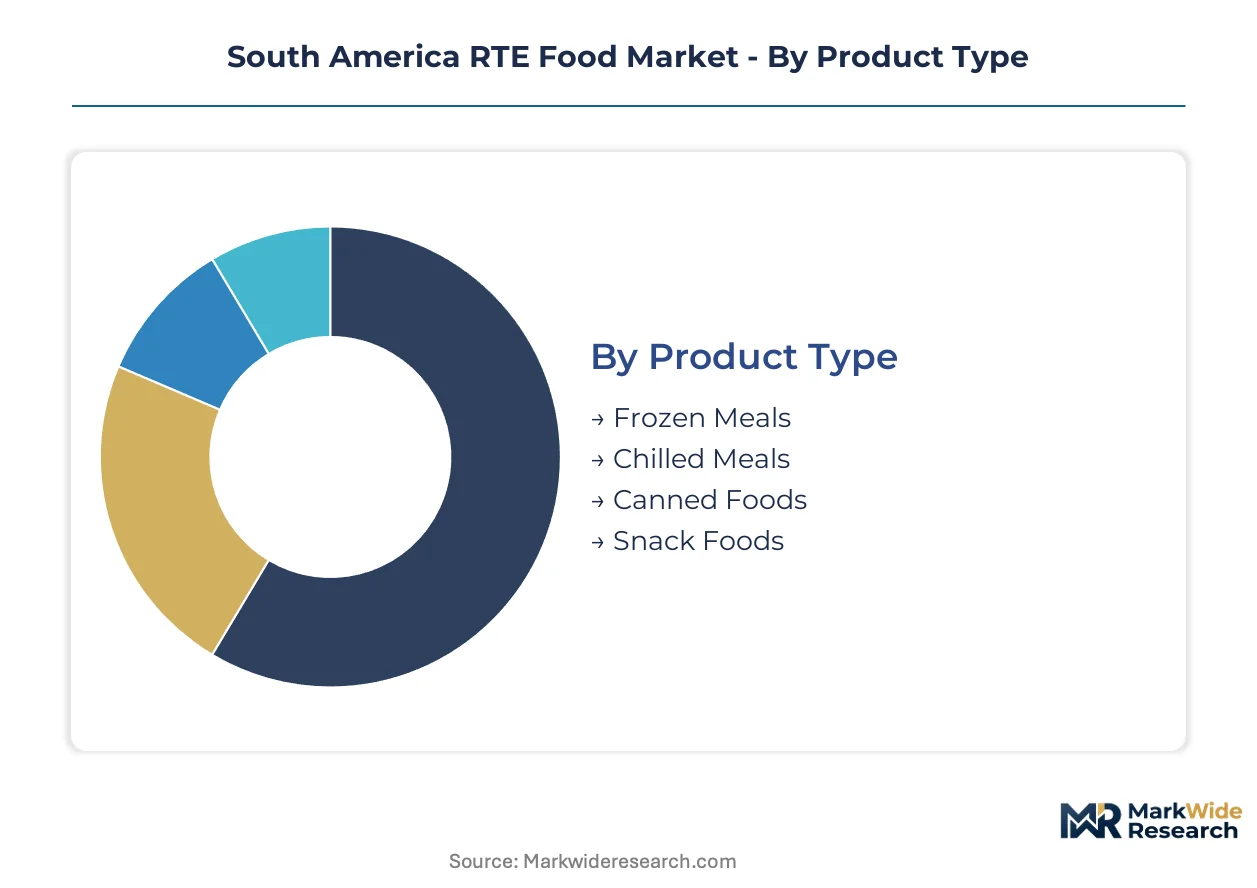
Segmentation in the South America RTE Food Market reveals how temperature tolerance, packaging investment, and channel access dictate purchasing patterns across Brazilian and Argentine consumption environments. Understanding these divides enables processors to align production formats with distinct logistics requirements and freshness expectations.
Product Type:
Buyer differentiation hinges on storage infrastructure access and preparation time tolerance rather than cuisine preference alone.
- Frozen Meals:Thermally stabilized products stored at minus 18 degrees Celsius enable extended distribution radii across Brazil's Campinas-Curitiba corridor and into Argentina's interior provinces. Demand concentrates among families in São Paulo's peripheral districts where weekly hypermarket trips dominate purchasing rhythms.
- Chilled Meals:High-pressure processed or modified-atmosphere packaged products requiring uninterrupted cold chains from plant to retail. Working professionals in Buenos Aires' Palermo and Recoleta neighborhoods drive adoption through same-day delivery platforms prioritizing visible freshness indicators.
- Canned Foods:Retort-sterilized products with ambient distribution tolerance serving Andean markets with underdeveloped refrigeration infrastructure.
- Snack Foods:Shelf-stable formats including processed meats and bakery items targeting convenience store channels and on-premise consumption occasions.
Frozen meals lead volumes today; chilled meals are gaining share fastest.
Packaging Type:
Margin capture varies sharply by material science investment and barrier performance specifications.
- Flexible Packaging:Multilayer coextruded films with oxygen scavenger integration reduce transport weight 15-20 percent versus rigid alternatives while extending shelf stability. Brazilian processors in Curitiba favor this format for chilled meal exports into Mercosur markets.
- Rigid Packaging:Polypropylene and polyethylene trays dominate frozen meal presentation across Carrefour and GPA retail networks, offering stackability and microwave compatibility that flexible formats cannot match.
- Glass Bottles:Premium positioning for sauces and condiments accompanying prepared meals, concentrated in Argentine urban markets with European consumption heritage.
- Food Pouches:Stand-up formats with spout closures for liquid and semi-liquid RTE products, expanding in Chilean retail channels subject to front-of-package warning label compliance requirements.
Flexible packaging commands the steepest margin expansion trajectory; rigid packaging retains volume dominance in frozen categories.
Distribution Channel:
Channel selection reflects urban density, cold-chain maturity, and consumer trip consolidation patterns across metropolitan corridors.
- Supermarkets:GPA and Carrefour networks anchor frozen meal distribution through dedicated freezer aisles and promotional stacking. São Paulo's southeastern industrial corridor supplies these channels via centralized distribution centers with automated temperature monitoring.
- Convenience Stores:AM/PM and similar networks in Brazilian state capitals stock shelf-stable and chilled snack formats for immediate consumption, requiring rapid inventory turnover and limited SKU breadth.
- Online Retail:Same-day delivery platforms capture prepared food occasions previously dominated by supermarkets, with strongest penetration in Buenos Aires where Argentine consumers show the steepest channel pivot.
- Foodservice:Hotels, airlines, and institutional catering procure blast-frozen meal formats in bulk, prioritizing portion consistency and extended holding tolerance over freshness signaling.
Supermarkets anchor current volume; online retail is climbing the fastest.
Customer Type:
Demographic segments separate by health signaling sensitivity, time scarcity intensity, and household composition.
- Millennials:Digital-native purchasers prioritizing subscription-based chilled meal delivery and front-of-package label transparency, concentrated in Santiago and São Paulo's Pinheiros district.
- Families:Multi-person households favoring frozen meal stockpiling and value-oriented SKUs, dominant in Brazil's southeastern industrial corridor suburban developments.
- Working Professionals:Time-constrained buyers in Buenos Aires and São Paulo consolidating weekly purchasing into single trips while demanding daily variety, fragmenting traditional frozen-stockpiling models.
- Health-Conscious Consumers:Ingredient-list scrutinizers driving sodium-reduced and preservative-free reformulation, particularly responsive to ANVISA's updated additive regulations.
Families represent the largest addressable base today; working professionals show the steepest adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Campinas-Curitiba processing corridor anchors South American RTE food production, with cold-chain density and logistics infrastructure concentrating formulation and packaging operations across Brazil's southeastern industrial belt.
Brazil
Working professionals in São Paulo and Curitiba drive chilled meal adoption through same-day delivery platforms prioritizing freshness indicators. ANVISA's updated food additive regulations mandate accelerated sodium reduction timelines and preservative system reformulation across frozen and chilled portfolios. The Campinas cluster houses centralized distribution centers with automated temperature monitoring supplying GPA and Carrefour networks.
Argentina
Urban consumers in Buenos Aires' Palermo and Recoleta neighborhoods fragment traditional frozen-stockpiling models through subscription-based chilled meal services. The national food code imposes labeling and additive restrictions exceeding Mercosur baselines, creating formulation complexity for regional standardization. Processing operations concentrate in Greater Buenos Aires with legacy ERP-cold chain integration challenges constraining secondary market expansion.
Chile
Santiago's dominant supermarket networks prioritize front-of-package warning label compliance, opening preferential retail placement for early reformulators meeting sodium and sugar thresholds. The front-of-package law mandates strict thresholds across packaged foods, forcing parallel SKU maintenance or Chilean-standard adoption as regional baseline. Cold-chain infrastructure supports high-pressure processed chilled meals with extended shelf lives reshaping distribution economics.
Colombia
Bogotá's working households consolidate weekly hypermarket trips while demanding daily meal variety, elevating flexible packaging formats with reduced transport weight. The national food safety authority enforces microbiological standards aligned with broader Andean community protocols. Processing capacity clusters in Cundinamarca with multilayer barrier film adoption lagging Brazilian benchmarks.
Peru
Lima's underpenetrated cold-chain infrastructure presents first-mover advantages for blast-frozen meal formats with ambient distribution tolerance. The national health authority implements technical barriers to trade monitoring as regional integration deepens. Andean city logistics gaps favor retort-sterilized canned formats serving markets with refrigeration deficits.
South America RTE Food Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue chilled freshness positioning and flexible packaging differentiation. The market exhibits tiered concentration with multinational processors controlling frozen meal volumes and domestic specialists capturing chilled segment acceleration. Three archetypes dominate: vertically integrated protein processors leveraging captive supply chains, multinational CPG anchors with localized flavor portfolios, and mid-tier distributors automating cold-chain data handoffs. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure last-mile temperature integrity.
Among Brazil-based processors, JBS, BRF, and Marfrig occupy positions exemplifying the vertically integrated archetype, with protein input control insulating against spot market volatility. Nestlé Brasil Ltda anchors the multinational CPG tier, representing premium frozen meal growth through brand equity and localized formulation. These named entities sit within broader competitive dynamics where cold-chain integration capabilities and regulatory compliance speed determine margin capture.
| Leading Market Players |
|---|
| Nestlé Brasil Ltda |
| JBS |
| BRF |
| McCain Foods |
| Grupo Bimbo |
| Unilever |
| Arcor |
| Marfrig |
| Kraft Heinz Company |
| Others |
Value Network & Pricing Analysis
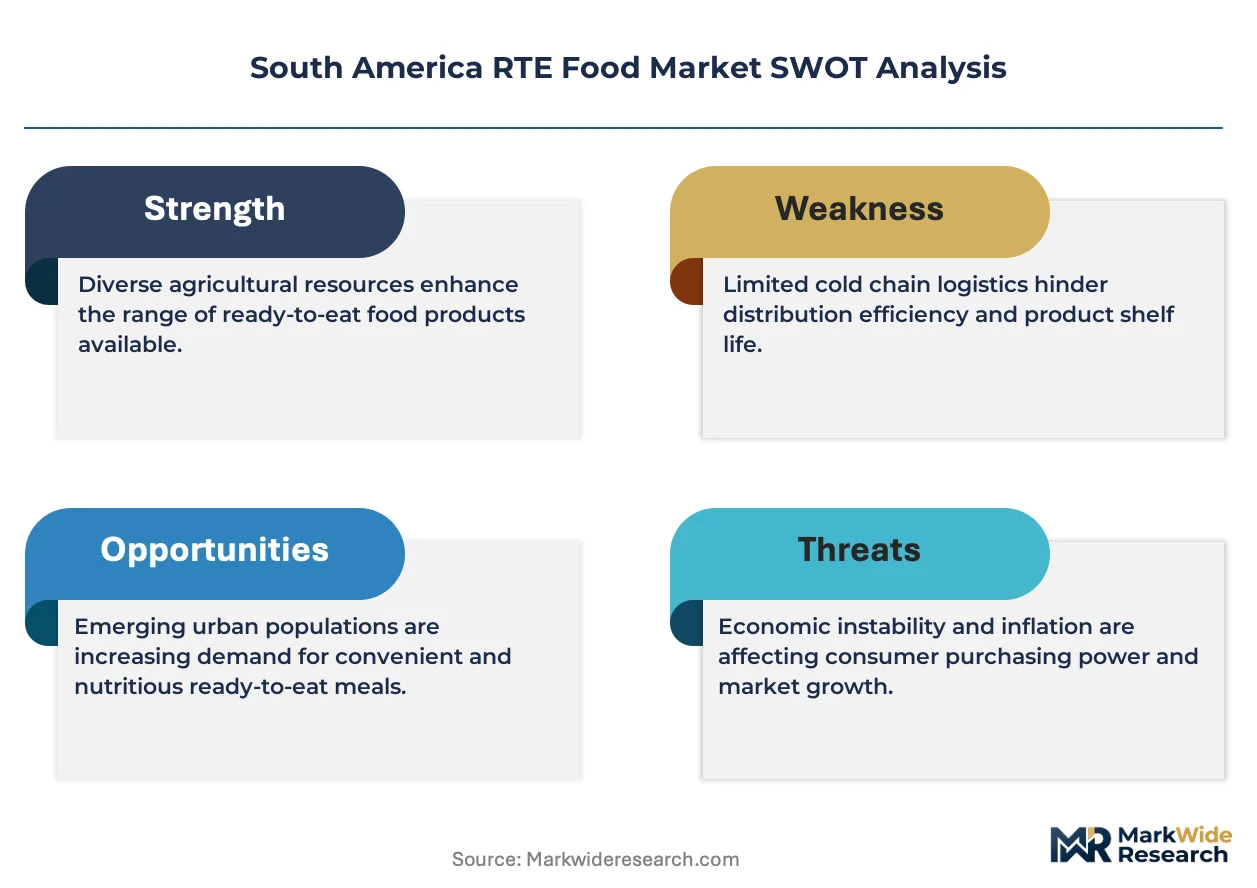
Captive supply chain control by JBS and BRF anchors both procurement stability and pricing power across Brazil's frozen and chilled meal tiers. ANVISA's sodium reduction mandates and feed grain cost swings feed directly into formulation economics and margin compression timelines.
Pricing Analysis
Beef and poultry input cost pass-through dominates pricing architecture across frozen meal portfolios. Three-tier pricing structure across premium, standard, and economy levels separates Nestlé Brasil's branded positioning from private-label alternatives. Cost compression in economy tiers intensifies because of spot market protein volatility and ANVISA compliance investments. Families in São Paulo's peripheral districts show highest price sensitivity; working professionals in Buenos Aires' Palermo district absorb premium chilled meal pricing.
Supply Chain Analysis
Single-source vulnerability sits with Argentine beef processors dependent on Brazilian feed grain imports during drought cycles. Protein inputs draw from Brazil, Argentina, and Paraguay; multilayer barrier films and modified-atmosphere packaging rest on petrochemical supply from São Paulo's southeastern industrial corridor. Tariff exposure across Mercosur technical barriers threatens cross-border SKU standardization. Distribution runs through GPA and Carrefour centralized cold-chain networks with automated temperature monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America RTE Food Market compounds steadily as urban working professionals consolidate purchasing into convenience-driven formats. Chilled meal freshness signaling and regulatory compliance speed separate winners from laggards.
For Market Incumbents: Deploy high-pressure processing capacity expansion to compress the frozen-chilled quality gap and capture 45-day shelf-life economics. Nestlé Brasil and BRF should accelerate ANVISA-compliant reformulation ahead of Argentine national food code divergence. Channel control through same-day delivery platform partnerships defends against subscription-based entrants in Buenos Aires.
For New Entrants and Emerging Players: Capture Ecuador and Peru's underpenetrated Andean corridors with blast-frozen formats tolerant of ambient distribution gaps. Lima's cold-chain infrastructure deficits present the most penetrable white-space for retort-sterilized and frozen meal positioning. Go-to-market through convenience store channels in secondary Brazilian cities bypasses incumbent supermarket slotting dominance.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier distributors lack automated ERP-cold chain integration and real-time temperature handoff capabilities. The five-to-ten year viability window favors processors with backward integration into protein supply and flexible packaging barrier film capabilities. Watch HPP equipment utilization rates as the inflection signal for chilled segment margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Capacity Expansion | HPP installation in São Paulo and Curitiba extends chilled meal shelf life to 45 days, reshaping distribution economics. |
| ANVISA-Compliant Reformulation Acceleration | Sodium and preservative system redesign ahead of enforcement timelines secures retail placement in GPA networks. |
| Flexible Packaging Barrier Film Adoption | Multilayer coextrusion with oxygen scavenger integration reduces transport weight 15-20 percent versus rigid alternatives. |
| Same-Day Delivery Platform Partnership | Direct integration with Buenos Aires delivery services captures prepared food occasions from traditional supermarket channels. |
| Andean Market Entry with Blast-Frozen Formats | Ambient distribution tolerance addresses cold-chain gaps in Lima and Quito convenience store networks. |
Research Methodology
Direct dialogue with RTE food plant managers, ANVISA regulatory affairs leads, GPA category buyers, and cold-chain logistics operators grounded qualitative insights in operational reality. Secondary validation drew from ANVISA additive regulation filings, Mercosur technical barrier notifications, customs trade data for protein inputs, and Nielsen retail audit data across Brazilian supermarket networks. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates.
Segment-level value outputs across the analysis window reflect modeled interactions between temperature format, packaging investment, and channel access patterns. The framework incorporated product type segmentation, distribution channel dynamics, and customer archetype differentiation to derive CAGRs. Forecast inputs included ANVISA reformulation timeline assumptions and high-pressure processing adoption curves in São Paulo's premium retail corridors.
Feed grain price shocks, ANVISA enforcement acceleration, and Mercosur regulatory divergence are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about cold-chain infrastructure buildout and consumer freshness preference evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
Dehydrated Food Market
Processed and Frozen Foods
Scandinavia Frozen Food Market
Processed and Frozen Foods
Frozen Mushroom Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Europe Dehydrated Food Market
Processed and Frozen Foods
North America Frozen Food Market
Processed and Frozen Foods
Frozen Desserts Market
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Chilled Meal Kits Market