
 Frozen Processed Meat Market | 2026-2036
Frozen Processed Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Processed Meat Market Analysis
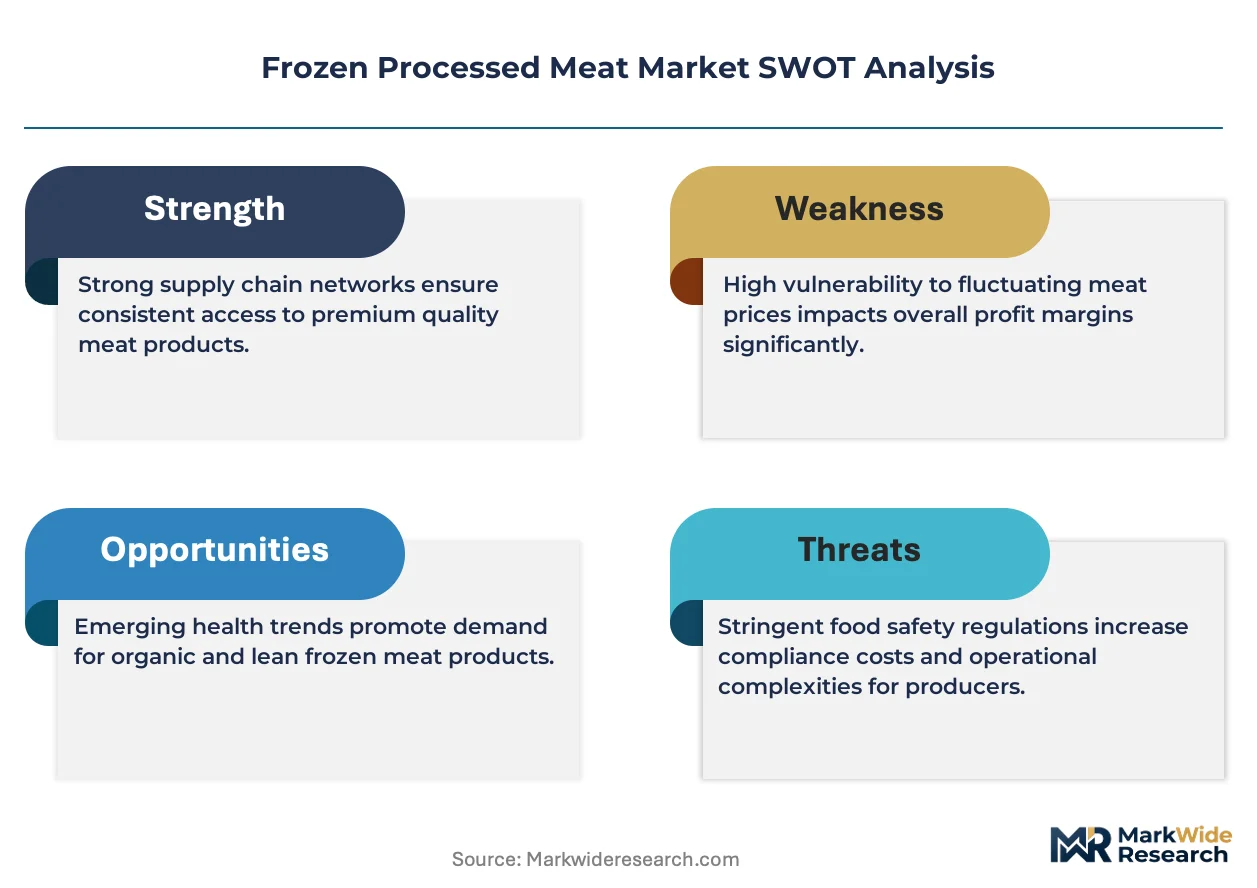
Asset-light leasing models for industrial blast freezers is narrowing the capital barrier for mid-scale processors entering frozen processed meat production. Tyson Foods leverages captive livestock supply networks to sustain margin stability across volatile feed cycles. JBS S.A. anchors South American production gravity with integrated slaughter-to-port logistics. Hormel Foods differentiates through branded retail positioning in North American supermarket channels.
Frozen processed meat comprises animal proteins that undergo slaughter, cutting, curing, smoking, or forming before rapid reduction to temperatures below minus eighteen degrees Celsius for preservation and distribution. The category serves foodservice operators and retail consumers requiring extended shelf life without continuous refrigeration infrastructure. Frozen nuggets and frozen burgers lead volume throughput in hypermarkets, where bulk packaging and promotional stacking drive turnover velocity. Vacuum-sealed formats command premium shelf-space allocations in specialty stores, reflecting consumer prioritization of oxidation control and portion flexibility. Online retail channels for frozen sausages and frozen meatballs are expanding fastest, though last-mile cold-chain reliability remains the binding operational constraint.
The USDA's Food Safety and Inspection Service enforces pathogen reduction performance standards that shape plant-level HACCP design and microbial testing cadence across US production facilities. The EU's EFSA evaluates nitrosamine risk in cured meat additives, directly influencing formulation choices for frozen meatballs and frozen sausages exported to European markets. China's SAMR implements GB standards for frozen food labeling and temperature integrity that condition market access for imported processed meat products. Stakeholders must monitor how tightening contaminant thresholds and carbon-accounting requirements for cold-chain logistics reshape cost structures and sourcing geography decisions.
Market Dynamics
Cold-chain logistics density is reshaping competitive positioning in frozen processed meat, as processors with captive port-to-plant networks capture margin from feed volatility while asset-light entrants lease blast freezer capacity to bypass capital barriers.
Growth Catalysts
- EU Farm to Fork Strategy:Tightening nitrite limits in cured processed meats are accelerating clean-label formulation R&D, opening premium positioning for compliant exporters.
- Quick-service restaurant expansion:Southeast Asian QSR chains are scaling freezer-to-grill workflows, pulling volume demand for frozen nuggets and formed patties.
- São Paulo cold-chain clustering:Brazil's logistics density in this state enables just-in-time foodservice delivery, concentrating processor investment gravity.
Market Restraints
- Feed cost volatility:Grain and protein meal price swings transmit directly to livestock input costs, compressing processor margins without captive supply networks.
- Last-mile cold-chain fragility:Online retail expansion for frozen sausages and meatballs faces temperature integrity failures in emerging market logistics.
- EFSA nitrosamine scrutiny:The EU regulator's additive risk assessments create formulation friction for cured meat exports to European markets.
Strategic Opportunities
- Vacuum-sealed premium formats:Oxidation-control packaging commands specialty retail shelf-space allocations, capturing consumer prioritization of portion flexibility.
- Carbon-accounting cold-chain incentives:EU Green Deal logistics requirements are reshaping sourcing geography decisions for low-emission transport routes.
- Industrial blast freezer leasing:Asset-light models narrow capital barriers for mid-scale processors entering frozen processed meat production.
Industry Challenges
- HACCP design complexity:USDA FSIS pathogen reduction standards demand plant-level microbial testing cadence upgrades that strain technical staffing.
- GB standards compliance:China's SAMR frozen food labeling and temperature integrity rules condition market access timelines for imported products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Processed Meat Market |
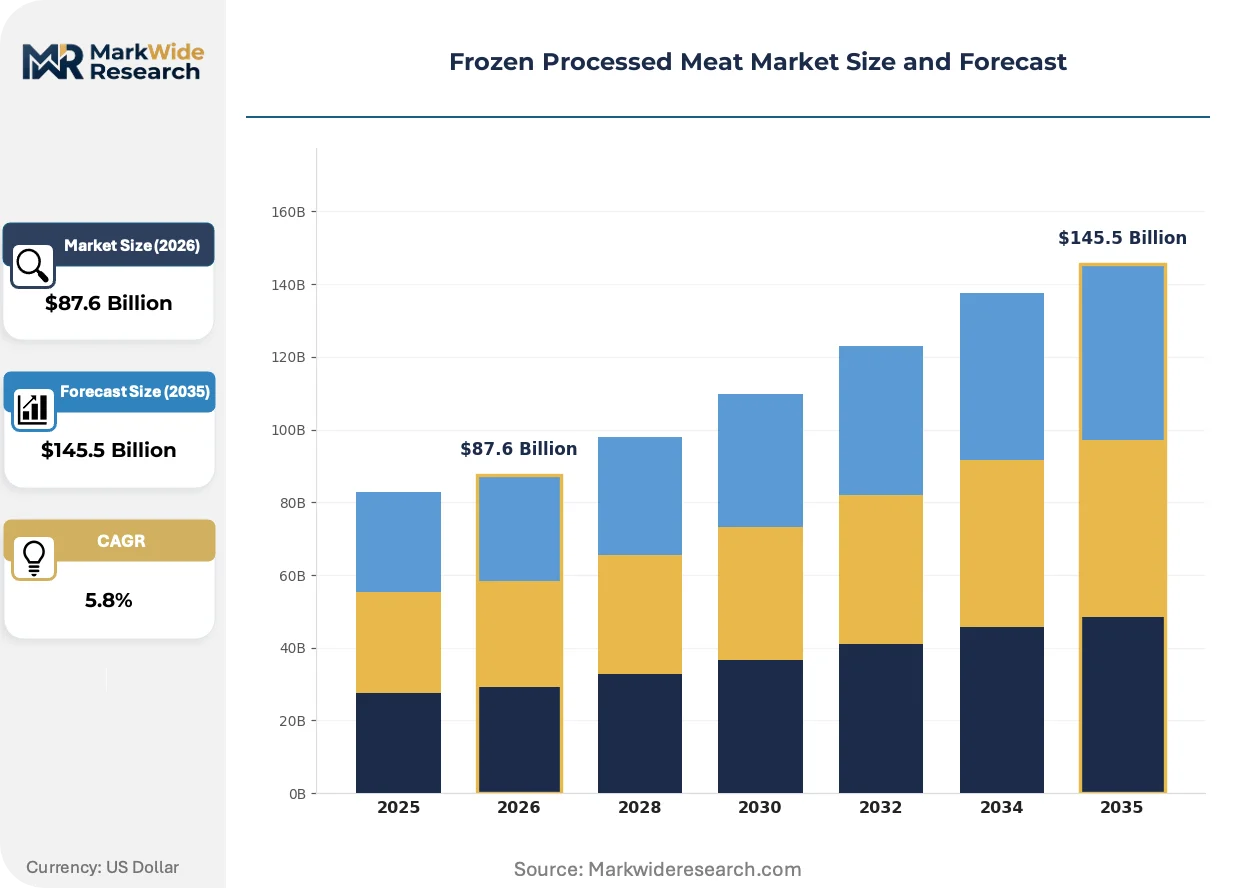
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $145.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Sausages, Frozen Burgers, Frozen Nuggets, Frozen Meatballs Distribution Channel: Supermarkets, Hypermarkets, Online Retail, Specialty Stores End User: Households, Restaurants, Cafeterias, Foodservice Packaging Type: Vacuum-Sealed, Tray Packs, Resealable Bags, Frozen Boxes |
| Companies Covered | JBS S.A., Tyson Foods, Inc., Cargill, Inc., WH Group Limited, BRF S.A., Marfrig Global Foods S.A., Hormel Foods Corporation, Conagra Brands Inc., Smithfield Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Processed Meat Market Emerging Trajectories
Automation and regulatory precision are compressing production cycles while reshaping formulation chemistry and distribution channel economics across frozen processed meat value chains.
High-pressure processing technology is migrating from niche premium applications to mainstream formed meat operations. Mid-scale processors in North American foodservice supply are adopting HPP lines at accelerating pace. This migration from thermal pasteurization is enabling clean-label shelf-life extension without nitrite dependence, compressing the competitive window for conventional curing methods.
REACH chemical restrictions and EU F-Gas Regulation are phasing synthetic refrigerants in industrial freezing equipment. European processors face retrofit obligations for blast freezer infrastructure. Frozen meatball and sausage exporters to EU markets are prioritizing ammonia and CO2 cascade systems to maintain market access compliance.
Foodservice procurement is consolidating toward direct processor relationships, bypassing traditional wholesale intermediaries. Large QSR chains in Southeast Asia are negotiating volume contracts with integrated slaughter-to-port operators. This pattern concentrates most visibly in Brazil's São Paulo corridor, where cold-chain reliability supports just-in-time delivery commitments.
Frozen Processed Meat Market Segmentation
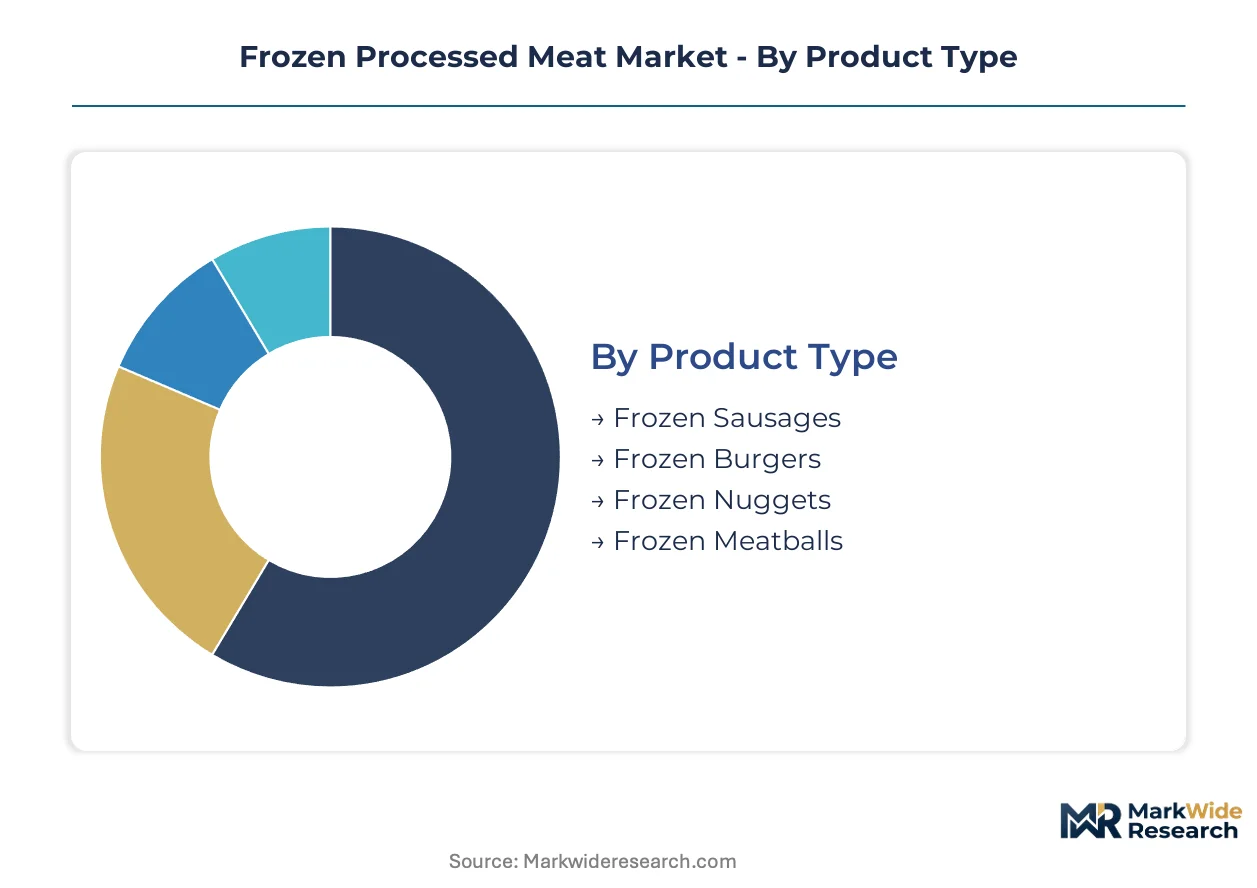
Frozen processed meat segmentation reveals distinct velocity profiles across product formats and channel structures. Cycle time differentials between retail and foodservice distribution shape inventory strategies and margin capture across the value chain.
Product Type:
Turnover velocity varies sharply across formed meat categories, with formed patties moving fastest through QSR procurement pipelines while specialty formats linger in cold storage awaiting premium retail placement.
- Frozen Burgers:Ground and formed beef patties dominate foodservice procurement volumes. Southeast Asian QSR chains in Thailand and Vietnam pull frozen burger shipments through São Paulo's integrated slaughter-to-port corridor to meet freezer-to-grill workflow requirements.
- Frozen Nuggets:Battered and breaded poultry pieces serve institutional cafeterias and family dining channels. Brazil's cold-chain density supports just-in-time delivery commitments to quick-service operators scaling regional footprints.
- Frozen Sausages:Cured and emulsified pork products face EU EFSA nitrosamine scrutiny that constrains formulation options for European-bound exports.
- Frozen Meatballs:Spherical formed beef-pork blends concentrate in retail bulk formats where promotional stacking drives hypermarket velocity.
Frozen burgers anchor the volume base while frozen nuggets gain share at the steepest rate.
Distribution Channel:
Cost tier stratification separates capital-intensive cold-chain infrastructure from asset-light digital intermediaries, with each tier demanding distinct processor capabilities.
- Hypermarkets:Bulk packaging and promotional stacking configurations dominate frozen nugget and meatball throughput. Cold-chain reliability in Brazil's São Paulo state enables just-in-time replenishment cycles for high-velocity SKUs.
- Online Retail:Direct-to-door frozen sausage and meatball shipments face last-mile temperature integrity failures in emerging market logistics networks. SAMR GB standards compliance adds labeling complexity for China-bound imports.
- Supermarkets:Mid-tier frozen burger assortments balance promotional frequency against everyday pricing discipline.
- Specialty Stores:Vacuum-sealed premium formats command shelf-space allocations reflecting oxidation-control prioritization.
Hypermarkets capture the volume base while online retail expands most quickly despite operational constraints.
End User:
Customer type segmentation maps directly to order frequency and specification stringency, with institutional buyers imposing stricter HACCP documentation than household purchasers.
- Restaurants:Quick-service operators negotiate direct processor relationships bypassing wholesale intermediaries. Southeast Asian QSR procurement consolidation favors integrated slaughter-to-port operators with captive logistics networks.
- Foodservice:Contract feeding and institutional procurement demands extended shelf-life specifications that favor high-pressure processing technology adoption over conventional nitrite curing.
- Households:Retail consumers prioritize portion flexibility and resealable convenience in frozen meatball and sausage selections.
- Cafeterias:School and workplace feeding programs emphasize cost-controlled bulk formats with standardized portion yields.
Restaurants anchor the volume base while foodservice climbs the fastest as procurement consolidation accelerates.
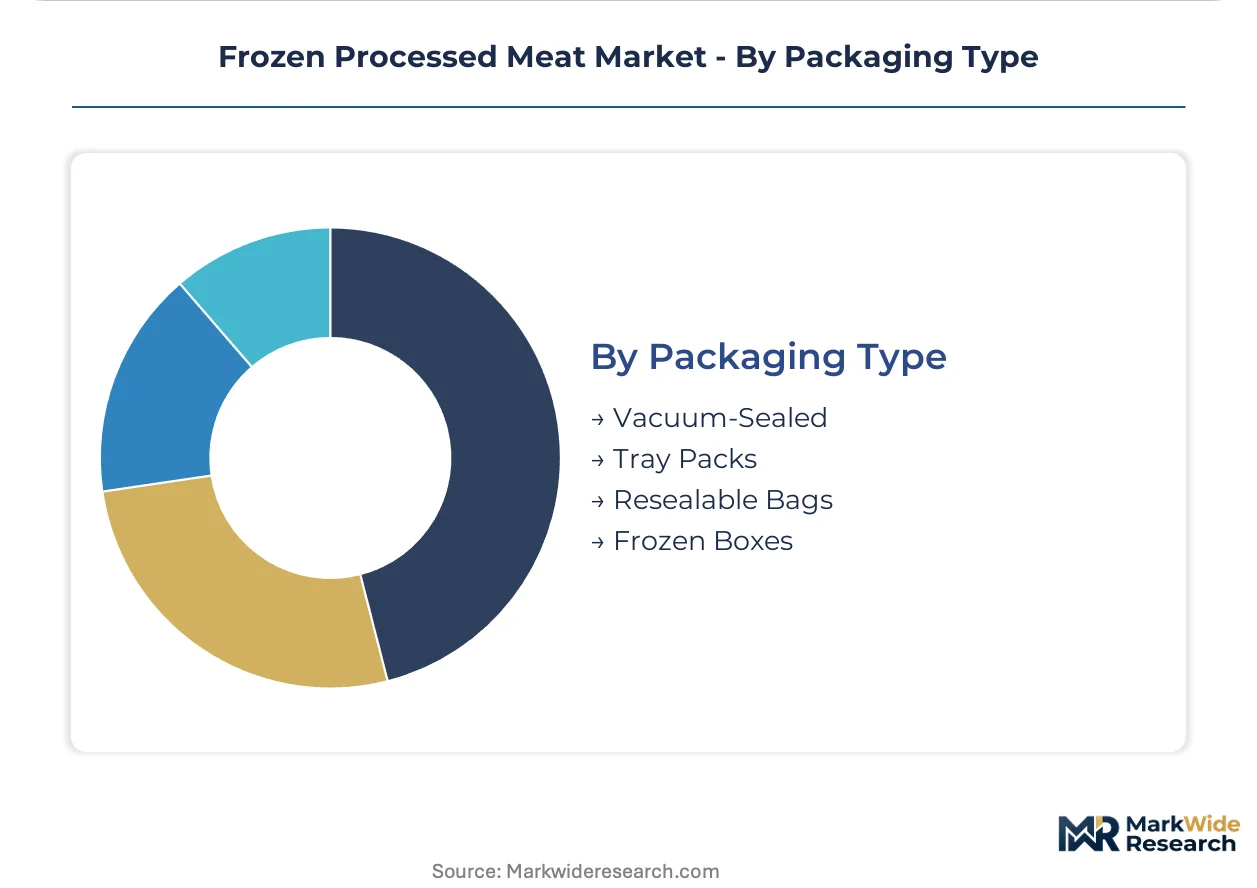
Packaging Type:
Margin structure correlates with barrier technology investment, with oxidation-control formats capturing premium positioning against commodity frozen boxes.
- Vacuum-Sealed:Oxygen-exclusion barrier films extend shelf life without preservative dependence. Specialty retailers in Germany and France allocate disproportionate shelf space to vacuum-sealed frozen sausages meeting EU Farm to Fork clean-label expectations.
- Resealable Bags:Zip-closure polyethylene structures serve household demand for portion flexibility across multi-serve frozen meatball and nugget formats.
- Tray Packs:Modified-atmosphere rigid containers balance visibility against cold-storage cube efficiency.
- Frozen Boxes:Corrugated secondary packaging dominates bulk foodservice shipments where transport efficiency outweighs retail presentation requirements.
Vacuum-sealed formats anchor the premium tier while resealable bags gain household penetration fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Farm to Fork Strategy nitrite restrictions and Brazil's integrated slaughter-to-port logistics are redrawing trade corridors for frozen processed meat exporters. Cold-chain density in São Paulo and regulatory stringency in Brussels now determine market access more than raw production capacity.
Brazil
São Paulo state's cold-chain clustering enables just-in-time delivery to Southeast Asian QSR chains scaling freezer-to-grill workflows. ANVISA's sanitary certifications condition export eligibility for frozen nugget and patty shipments to Mercosur partners. The integrated slaughter-to-port corridor from Mato Grosso through Santos anchors South American production gravity.
United States
USDA FSIS pathogen reduction standards demand plant-level HACCP upgrades that favor large-scale processors with technical staffing depth. The Inflation Reduction Act's clean energy incentives are reshaping refrigeration equipment procurement for blast freezer retrofits. Midwestern packing plants in Iowa and Nebraska leverage captive livestock networks to buffer feed cost volatility.
Germany
EFSA nitrosamine scrutiny constrains formulation options for cured frozen sausages bound for EU retail channels. REACH chemical restrictions and F-Gas Regulation phase synthetic refrigerants in industrial freezing equipment, forcing ammonia cascade system adoption. Bavarian processors supply vacuum-sealed premium formats to French and Benelux specialty retailers.
China
SAMR GB standards for frozen food labeling and temperature integrity condition market access timelines for imported processed meat products. Dual carbon goals are accelerating cold-chain logistics decarbonization investments in Yangtze River Delta distribution hubs. Shanghai's port infrastructure handles bulk frozen meatball imports for foodservice redistribution.
Thailand
Quick-service restaurant procurement consolidation pulls frozen burger and nugget volumes through Bangkok's expanding cold-storage terminal capacity. The country's national food and drug regulator enforces import documentation requirements that favor established supplier relationships. Eastern Economic Corridor logistics parks support freezer-to-grill workflow scaling for regional QSR chains.
Frozen Processed Meat Market Vendor Landscape
Channel-controlling players compete with product-specialist players for positioning across frozen processed meat value chains. The market structure concentrates around integrated slaughter-to-port operators with captive logistics networks, while mid-scale processors lease blast freezer capacity to bypass capital barriers. Three archetypes dominate: vertically integrated livestock-to-retail conglomerates, asset-light specialty format innovators, and foodservice-direct contract suppliers. Competitive moves center on backward integration into livestock supply and carbon-accounting cold-chain certification for EU market access.
Among Brazilian-origin integrated processors, JBS S.A. and Marfrig Global Foods S.A. exemplify the slaughter-to-port archetype with South American production gravity. Tyson Foods, Inc. occupies a position representing North American channel control through retail and foodservice distribution depth. WH Group Limited anchors the Asia-Pacific vector with Chinese corporate structure and processed meat portfolio breadth.
| Leading Market Players |
|---|
| JBS S.A. |
| Tyson Foods, Inc. |
| Cargill, Inc. |
| WH Group Limited |
| BRF S.A. |
| Marfrig Global Foods S.A. |
| Hormel Foods Corporation |
| Conagra Brands Inc. |
| Smithfield Foods, Inc. |
| Others |
Supply Flow & Price Mechanics
Brazil's integrated slaughter-to-port corridor from Mato Grosso through Santos concentrates livestock supply control, anchoring margin pools in foodservice contract pricing and captive logistics premiums rather than commodity spot markets.
Pricing Analysis
Certification level creates the primary spread across frozen processed meat tiers, with EU EFSA nitrosamine-compliant formulations commanding substantial premiums over conventional cured alternatives. Three-tier pricing structure across premium vacuum-sealed formats, standard hypermarket bulk SKUs, and economy foodservice boxes reflects cold-chain reliability grades and HACCP documentation depth. Pricing pressure stems from feed cost volatility transmitting directly to processor margins, particularly for operators without captive livestock networks. Quick-service restaurant procurement teams exhibit highest price sensitivity due to volume contract negotiations, while specialty retail channels absorb premiums for oxidation-control packaging.
Supply Chain Analysis
Contract manufacturing concentration sits with integrated processors like JBS S.A. and Tyson Foods that operate captive blast freezer capacity across Brazil, the United States, and Germany. Raw material dependencies center on corn and soybean meal for livestock feed, natural gas for industrial freezing equipment, and ammonia or CO2 cascade refrigerants for EU-compliant cold chains. Supply chain risk manifests in single-source vulnerability for specialized curing additives facing REACH chemical restrictions. Distribution runs through direct processor-to-QSR relationships bypassing wholesale intermediaries, particularly visible in Southeast Asian freezer-to-grill workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of HACCP-certified technical staffing and blast freezer infrastructure with carbon-accounting compliance creates structural bottlenecks that favor incumbents with existing certification depth over asset-light entrants.
For Market Incumbents: Pre-empt clean-label formulation shifts by accelerating high-pressure processing line adoption before EU Farm to Fork nitrite limits tighten further. Capture margin stability through backward integration into captive livestock supply networks that buffer feed cost volatility. Defend foodservice contract positions by certifying cold-chain carbon intensity for EU Green Deal procurement requirements.
For New Entrants and Emerging Players: Southeast Asian online retail channels for frozen sausages and meatballs present underpenetrated white space where last-mile temperature integrity failures have stalled incumbent expansion. Lease industrial blast freezer capacity to bypass capital barriers while building SAMR GB standards compliance capability for China market access. Target direct-to-door subscription models for vacuum-sealed premium formats in German and French specialty retail corridors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale processors lacking integrated slaughter-to-port logistics but holding HACCP certification and regional foodservice relationships. Long-term viability hinges on cold-chain decarbonization investment timing and clean-label R&D pipeline depth. Monitor EU EFSA additive risk assessments and USDA FSIS pathogen standard revisions as inflection indicators for formulation compliance costs.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Line Adoption | Enables nitrite-free shelf-life extension meeting EU Farm to Fork clean-label expectations. |
| Captive Livestock Network Expansion | Buffers margin compression from corn and soybean meal price volatility in feed markets. |
| Carbon-Accounting Cold-Chain Certification | Secures EU Green Deal procurement eligibility for low-emission transport route sourcing. |
| Direct QSR Contract Negotiation | Bypasses wholesale intermediaries in Southeast Asian freezer-to-grill workflow scaling. |
| SAMR GB Standards Compliance Investment | Accelerates China market access timelines for frozen meatball and sausage imports. |
Methodological Framework
A standing panel of plant-level HACCP managers, quick-service restaurant procurement directors, cold-chain logistics operators, and regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from USDA FSIS enforcement reports, EFSA scientific opinions, SAMR GB standard filings, and ANVISA sanitary certification databases. Bottom-up volume modeling triangulated against top-down macroeconomic anchors across the analysis window.
Scenario-bracketing framed projections across product type, distribution channel, packaging technology, and end-user segmentation dimensions. CAGRs derived from trend-line extrapolation adjusted for regulatory inflection points and cold-chain infrastructure buildout curves. Feed cost volatility indices and EU refrigerant phase-out schedules informed sensitivity ranges.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by asset-light leasing models or accelerated EU nitrite restrictions would shift outcomes. Quarterly review of EFSA additive risk assessments, USDA pathogen reduction standard revisions, and São Paulo cold-chain terminal utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Dehydrated Food Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Taiyaki Ice Cream Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
Freeze Dried Vegetables Market