
 Middle East and Africa Frozen Food Market | 2026-2036
Middle East and Africa Frozen Food Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Frozen Food Market Foresight
Hypermarket and supermarket distribution across the Middle East and Africa is tilting toward private-label and bulk frozen portfolios as modern retail formats displace traditional wet markets. Al Kabeer Group leverages its vertically integrated poultry and red meat processing to dominate freezer space in Saudi Arabian retail chains. Sunbulah Group anchors its position through deep distribution into Gulf Cooperation Council food-service accounts, while Americana Group competes via brand recognition in the quick-service restaurant channel.
The Middle East and Africa frozen food category encompasses raw, partially prepared, and fully cooked foodstuffs preserved at temperatures below minus eighteen degrees Celsius to arrest microbial activity and maintain nutritional integrity, with blast freezing and individual quick freezing representing the dominant industrial processes for texture retention. Frozen meats and frozen seafood occupy the largest margin pools due to protein premiumization and import dependency across Gulf states, while frozen vegetables sustain the fastest volume trajectory as health-conscious retail customers and food-service operators expand plant-forward menu engineering. Vacuum pack and modified-atmosphere packaging formats are gaining share against conventional bags as shelf-life extension becomes a procurement priority for wholesale and online retail channels.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology enforce halal certification and cold-chain integrity standards that shape import eligibility and domestic production compliance across the region. South Africa's National Regulator for Compulsory Specifications mandates frozen product labeling and temperature logging that raise operational barriers for informal traders and unlicensed importers. Stakeholders must monitor evolving Gulf standardization frameworks and local content requirements as governments balance food security ambitions with regulatory sovereignty over imported frozen goods.
Market Dynamics
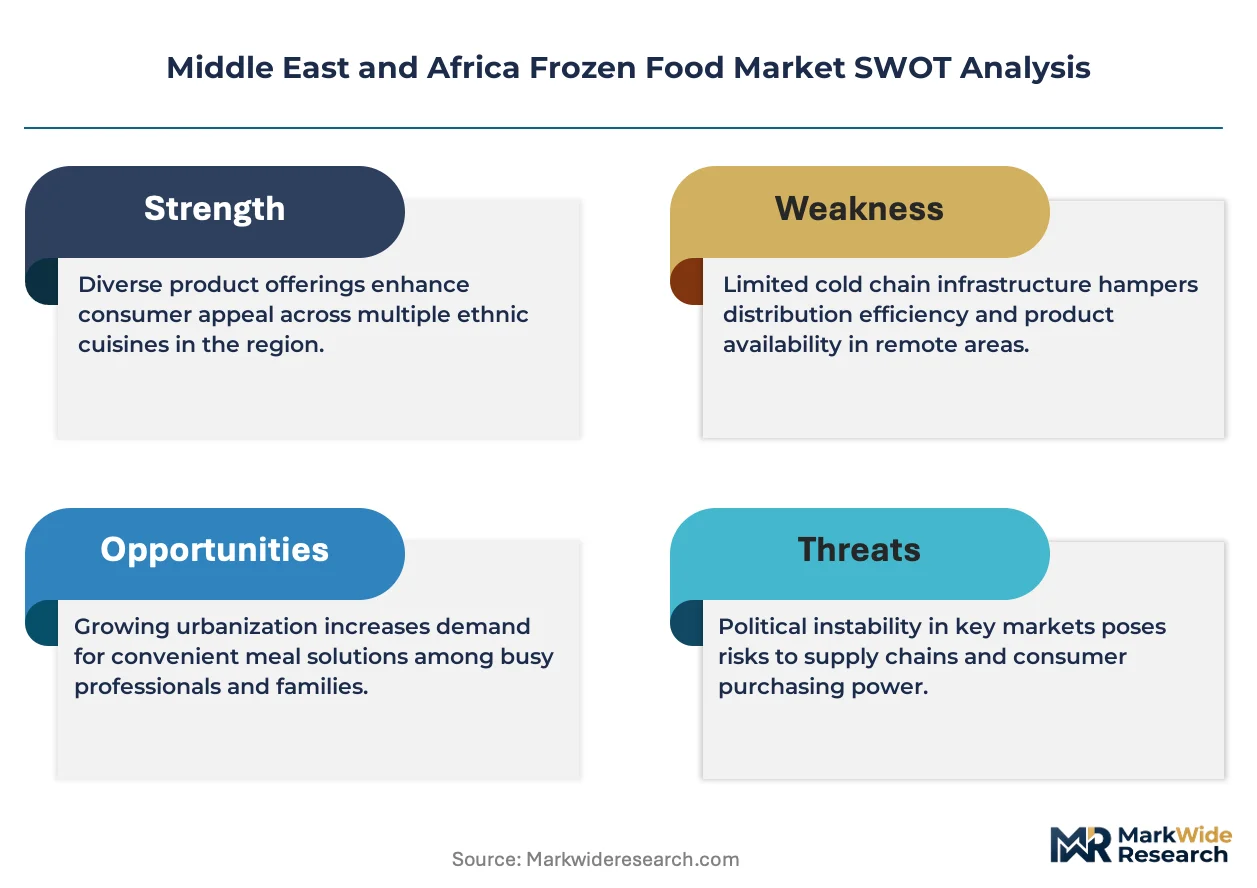
Cold-chain infrastructure expansion across the Gulf Cooperation Council is compressing delivery windows for temperature-sensitive frozen proteins, forcing processors to relocate blast-freezing capacity closer to port terminals and retail distribution hubs.
Growth Catalysts
- SFDA Halal Certification Mandates:Saudi Food and Drug Authority enforcement of end-to-end halal traceability for imported frozen meats is consolidating procurement toward certified suppliers with integrated slaughter-to-freezer documentation.
- Quick-Service Restaurant Chains:Gulf Cooperation Council fast-food operators are standardizing frozen ingredient specifications across franchise networks, creating volume commitments that justify dedicated production lines.
- Blast Freezing at Port:Jeddah Islamic Port and King Abdulaziz Port investments in on-dock freezing facilities are reducing post-harvest degradation for Red Sea seafood landing.
Market Restraints
- Diesel-Powered Refrigeration Costs:Transport operators across the Emirates and Saudi Arabia face fuel price volatility that erodes margins on long-haul frozen distribution to interior cities.
- Import Concentration Risk:Over 70 percent of frozen poultry entering United Arab Emirates originates from Brazilian processing complexes, exposing buyers to single-source supply interruptions.
- Modified-Atmosphere Packaging Limitations:Current barrier film technologies degrade under Gulf summer temperatures above 45 degrees Celsius, limiting shelf-life claims for retail frozen vegetables.
Strategic Opportunities
- Kenya and Ethiopia Cold-Chain Gaps:Underpenetrated East African markets present first-mover advantages for frozen seafood distributors establishing last-mile freezer capacity in Nairobi and Addis Ababa.
- Emirates Authority for Standardization and Metrology Labeling Reforms:Pending digital traceability mandates will favor suppliers with blockchain-enabled temperature logging systems.
- E-Commerce Dark Stores:Saudi Arabian grocery platforms are deploying dedicated frozen fulfillment centers in Riyadh's northern industrial zone, opening direct-to-consumer channels bypassing traditional retail slotting fees.
Industry Challenges
- Halal Slaughter Certification Talent:Qualified Islamic slaughter inspectors with veterinary credentials remain scarce across North African processing facilities, delaying plant approvals.
- Legacy ERP Integration:South African cold-store operators struggle to connect temperature-monitoring IoT sensors with existing warehouse management systems, creating data silos that complicate Emirates Authority for Standardization and Metrology compliance audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Frozen Food Market |
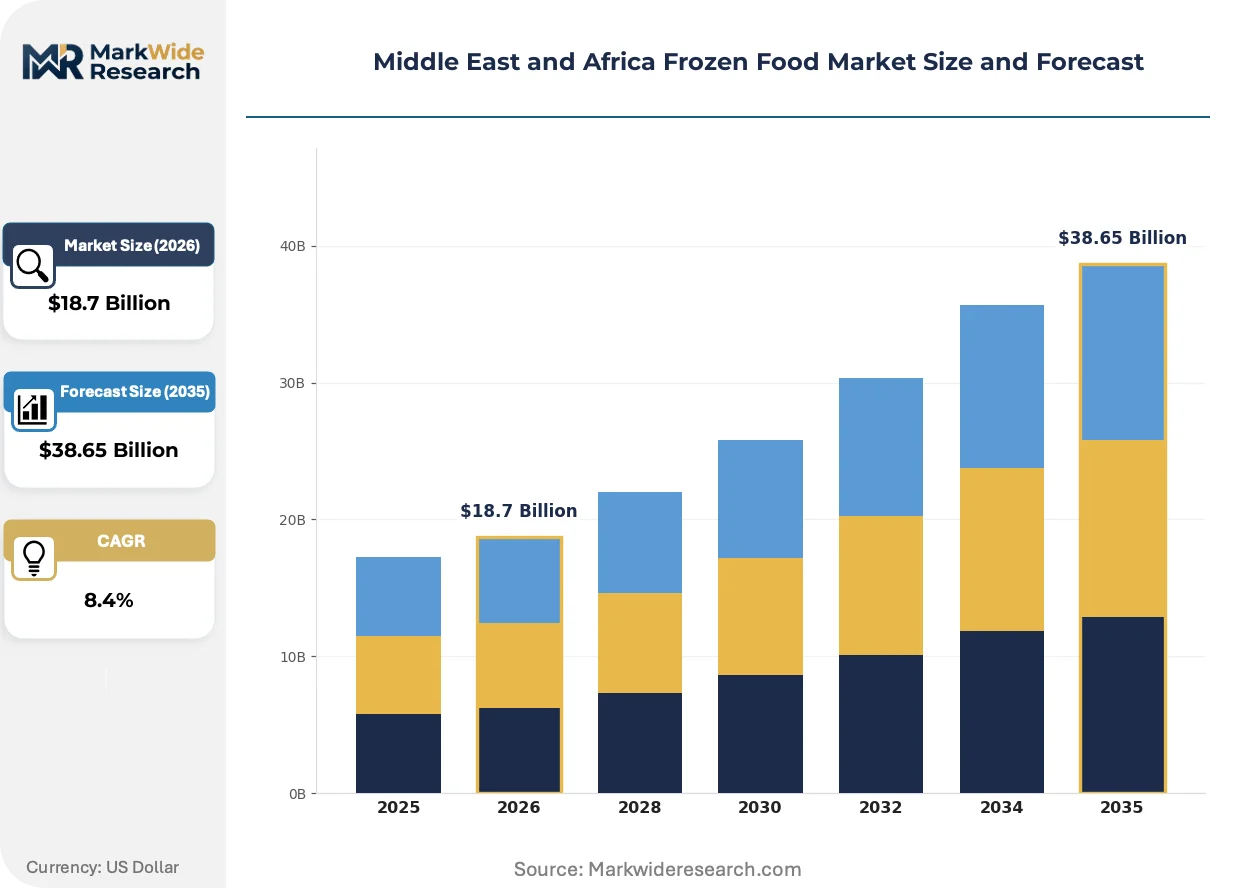
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Vegetables, Frozen Fruits, Frozen Meats, Frozen Seafood End User: Retail Customers, HoReCa, Industrial, Food Service Packaging Type: Vacuum Pack, Bags, Boxes, Containers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | Nestlé S.A., General Mills Inc., Al Kabeer Group, Sunbulah Group, McCain Foods Ltd., Kellanova, Al Islami Foods, Americana Group, Almarai Co., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Frozen Food Market Shifts & Advancements
Freezing technology convergence with packaging science is compressing product development cycles for premium frozen categories, while regulatory digitization and channel fragmentation are redrawing competitive boundaries across the Middle East and Africa.
Individual quick freezing combined with cryogenic tunnel technology is rendering obsolete traditional blast-freezing methods for delicate seafood textures. Saudi Arabian shrimp processors operating out of Jazan are adopting liquid nitrogen immersion systems to eliminate ice crystal formation. This upgrade is rendering obsolete older mechanical freezing equipment that required 45-minute residence times and degraded fillet integrity.
Emirates Authority for Standardization and Metrology's 2024 cold-chain integrity protocols now mandate continuous temperature logging for all frozen imports entering Dubai and Abu Dhabi ports. The regulation forces reefer container operators to retrofit satellite-enabled monitoring hardware before discharge clearance. Frozen red meat shipments from Australia and New Zealand face the strictest enforcement, with customs holding non-compliant containers for secondary inspection averaging 72 hours.
Food-service procurement teams across the Gulf Cooperation Council are consolidating supplier relationships around integrated frozen-protein vendors offering menu development support. Large hospitality groups in Doha and Manama now specify frozen ingredient suppliers who provide recipe calibration and staff training as bundled services. This bundling is most visible in Qatar's luxury hotel sector, where procurement directors prioritize single-source accountability over lowest-unit-cost bidding.
Middle East and Africa Frozen Food Market Segmentation
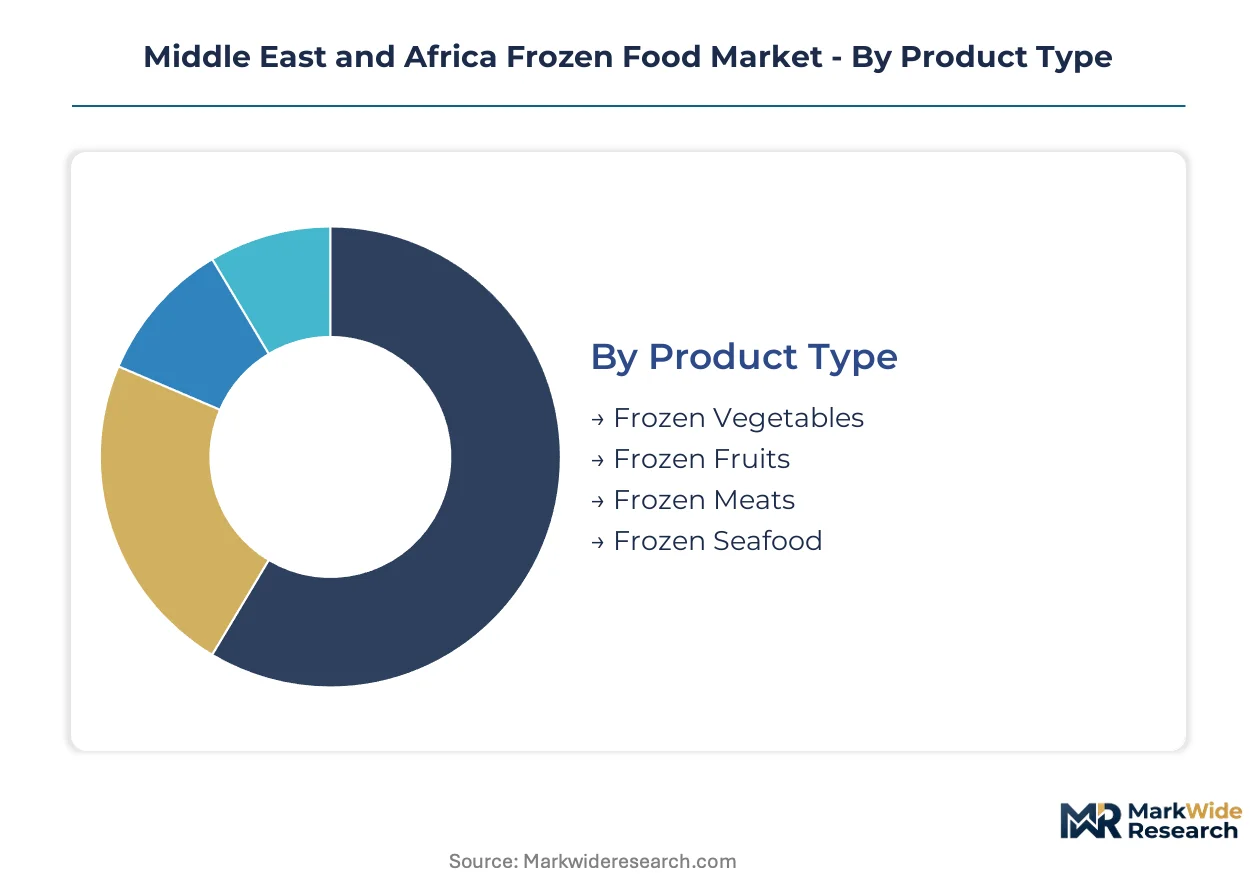
Segmentation in the Middle East and Africa frozen food market reveals how protein import dependency, halal certification requirements, and cold-chain infrastructure gaps reshape competitive priorities across product categories and channel structures.
Product Type:
Mature categories dominate freezer space in Saudi Arabian and Emirati retail, while emerging segments accelerate as health positioning and convenience drive portfolio expansion.
- Frozen Meats:Beef, lamb, and poultry cuts preserved through blast freezing or individual quick freezing to maintain protein structure. Demand concentrates in Saudi Arabia's Riyadh-Jeddah corridor, where quick-service restaurant chains expand procurement of standardized frozen portions to secure halal supply consistency.
- Frozen Seafood:Fish fillets, shrimp, and cephalopods processed via cryogenic tunnel technology at Jeddah Islamic Port and King Abdulaziz Port facilities. Gulf Cooperation Council hospitality groups in Doha and Manama drive volume through menu engineering that substitutes frozen for fresh amid Red Sea landing constraints.
- Frozen Vegetables:Blanching and individual quick freezing preserve micronutrient density in peas, spinach, and mixed medleys. South African retail modernization and plant-forward menu trends in Dubai hotels expand adoption.
- Frozen Fruits:Berries, mango chunks, and tropical varieties frozen at peak ripeness for smoothie manufacturing and bakery applications. Nairobi and Addis Ababa food-service distributors build last-mile freezer capacity to reach underpenetrated East African markets.
Frozen meats handle the majority of throughput; frozen vegetables is the fastest mover on share.
End User:
Volume concentration tilts toward institutional buyers with cold-chain compliance capabilities, while fragmented retail and industrial segments present divergent margin profiles.
- HoReCa:Hotels, restaurants, and catering operations requiring consistent portion control and halal traceability documentation. Procurement directors in Qatar's luxury hotel sector prioritize single-source suppliers offering bundled recipe calibration and staff training services.
- Food Service:Contract catering, institutional cafeterias, and quick-service restaurant chains standardizing frozen ingredient specifications across franchise networks. Gulf Cooperation Council operators create volume commitments justifying dedicated production lines at Al Kabeer Group and Sunbulah Group facilities.
- Retail Customers:Individual households purchasing through hypermarkets and supermarkets as modern formats displace traditional wet markets. Private-label expansion accelerates in Saudi Arabian retail chains.
- Industrial:Food manufacturers incorporating frozen inputs into processed products such as ready meals, bakery fillings, and confectionery. South African Department of Health traceability protocols tighten compliance requirements for imported frozen meat derivatives.
HoReCa captures the highest margin pool; Food Service is expanding most quickly as franchise standardization deepens.
Packaging Type:
Barrier technology investments separate premium shelf-life claims from commodity formats vulnerable to Gulf summer temperature extremes.
- Vacuum Pack:Oxygen-exclusion systems extending frozen protein storage duration while preventing freezer burn. Emirates Authority for Standardization and Metrology cold-chain integrity protocols favor suppliers with continuous temperature logging compatible with vacuum-sealed bulk formats.
- Modified-Atmosphere Packaging:Controlled gas mixtures slowing oxidative degradation in retail frozen vegetables. Current barrier film limitations above 45 degrees Celsius restrict shelf-life claims during Emirates summer distribution.
- Bags:Conventional polyethylene formats for commodity frozen vegetables and fruits. Cost-sensitive procurement in South African informal trade sustains volume despite inferior protection.
- Boxes:Rigid corrugated and plastic containers for bulk food-service shipments. King Abdulaziz Port on-dock freezing facilities standardize box dimensions for automated handling.
- Containers:Reusable and single-use rigid formats for industrial-scale frozen meat and seafood transfers. Brazilian poultry export concentration into United Arab Emirates relies on containerized reefer integrity.
Vacuum pack commands premium positioning; modified-atmosphere packaging faces steepest expansion trajectory pending film technology advances.
Distribution Channel:
Channel fragmentation accelerates as e-commerce dark stores and wholesale consolidation reshape traditional supermarket dominance.
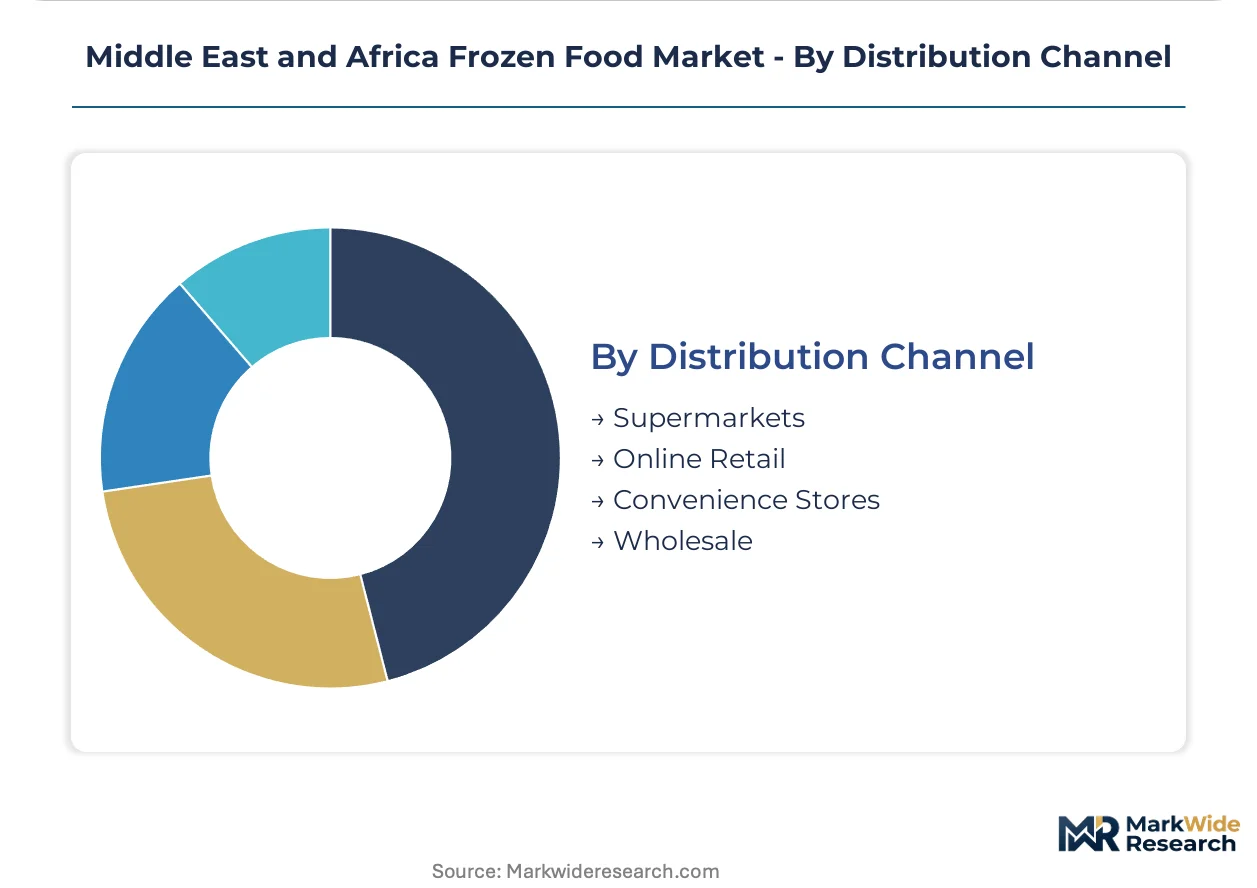
- Supermarkets:Hypermarket and supermarket networks across the Gulf Cooperation Council displacing traditional wet markets with private-label and bulk frozen portfolios. Al Kabeer Group leverages vertically integrated processing to secure freezer space in Saudi Arabian retail chains.
- Wholesale:Cash-and-carry and dedicated food-service distributors supplying restaurants, hotels, and catering operations. Sunbulah Group anchors market position through deep penetration of Gulf Cooperation Council wholesale accounts.
- Online Retail:Grocery platforms deploying dedicated frozen fulfillment infrastructure. Saudi Arabian operators establish dark stores in Riyadh's northern industrial zone to bypass traditional retail slotting fees.
- Convenience Stores:Small-format urban retail with limited freezer capacity targeting impulse and emergency replenishment. Diesel-powered refrigeration cost volatility erodes margin on long-haul distribution to interior Emirates and Saudi cities.
Supermarkets retain volume leadership; online retail is gaining share fastest through direct-to-consumer infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA halal certification mandates and Emirates Authority for Standardization and Metrology cold-chain protocols anchor regulatory frameworks across the Gulf Cooperation Council, while South Africa's National Regulator for Compulsory Specifications shapes compliance requirements in sub-Saharan markets.
Saudi Arabia
Quick-service restaurant chains and retail modernization in the Riyadh-Jeddah corridor drive frozen protein procurement volumes. SFDA enforcement of end-to-end halal traceability consolidates procurement toward certified suppliers with integrated slaughter-to-freezer documentation. King Abdulaziz Port investments in on-dock freezing facilities reduce post-harvest degradation for Red Sea seafood landing.
United Arab Emirates
Hospitality groups in Dubai and Abu Dhabi expand frozen seafood adoption through menu engineering that substitutes frozen for fresh amid supply constraints. Emirates Authority for Standardization and Metrology's 2024 cold-chain integrity protocols mandate continuous temperature logging for all frozen imports entering Dubai and Abu Dhabi ports. Jebel Ali port infrastructure supports Brazilian poultry import concentration exceeding seventy percent of national frozen poultry supply.
South Africa
Retail modernization and plant-forward menu trends accelerate frozen vegetable adoption in urban centers. The National Regulator for Compulsory Specifications mandates frozen product labeling and temperature logging that raise operational barriers for informal traders and unlicensed importers. Cape Town and Johannesburg cold-store operators struggle to connect temperature-monitoring IoT sensors with existing warehouse management systems.
Qatar
Luxury hotel procurement directors prioritize single-source frozen protein suppliers offering bundled recipe calibration and staff training services. Gulf standardization frameworks and local content requirements govern import eligibility for hospitality sector procurement. Doha-based food-service operators consolidate supplier relationships around integrated frozen-protein vendors.
Kenya
Underpenetrated East African markets present first-mover advantages for frozen seafood distributors establishing last-mile freezer capacity. General food safety protocols from the national public health authority shape import compliance for frozen meat derivatives. Nairobi food-service distributors build cold-chain infrastructure to reach previously unserved segments.
Middle East and Africa Frozen Food Market Competitive Landscape
Vertically integrated processors and brand-led multinationals split the market between supply-security and recognition-driven procurement. The competitive structure tilts toward consolidation in Gulf Cooperation Council states where halal certification barriers favor established players with integrated documentation systems. Three archetypes dominate: poultry and red meat processors with captive slaughter capacity, diversified food-service distributors with deep wholesale penetration, and multinational brand houses leveraging quick-service restaurant channel relationships. Capacity relocation toward port terminals and strategic partnerships with e-commerce dark store operators represent the dominant competitive moves.
Within the vertically integrated tier, Al Kabeer Group leverages its poultry and red meat processing dominance to secure freezer space in Saudi Arabian retail chains. Sunbulah Group anchors its market position through deep distribution into Gulf Cooperation Council food-service accounts. Americana Group occupies a position competing via brand recognition in the quick-service restaurant channel. These three exemplify how certification compliance and channel-specific bundling separate sustainable market presence from commodity trading.
| Leading Market Players |
|---|
| Nestlé S.A. |
| General Mills Inc. |
| Al Kabeer Group |
| Sunbulah Group |
| McCain Foods Ltd. |
| Kellanova |
| Al Islami Foods |
| Americana Group |
| Almarai Co. |
| Others |
Supply & Pricing Matrix
Blast-freezing capacity underutilization at Jeddah Islamic Port and King Abdulaziz Port is compressing spot pricing for Red Sea seafood processors while elevating contract premiums for integrated suppliers with guaranteed offtake agreements. This utilization divergence rewards backward-integrated players with captive cold-chain assets and pressures toll-freezing operators into margin-eroding spot competition.
Pricing Analysis
Saudi Arabian retail chains command fifteen to twenty percent discounts versus Dubai hospitality procurement for identical frozen poultry SKUs, reflecting volume concentration and slotting-fee leverage. Three-tier pricing structure across premium halal-certified, standard commercial-grade, and economy private-label tiers segments buyer willingness-to-pay. Pricing pressure stems from diesel-powered refrigeration cost volatility eroding transport margins on long-haul distribution to Riyadh and interior Emirates cities. Quick-service restaurant chains exhibit lowest price sensitivity due to franchise-standardization lock-in, while South African informal traders face acute cost pressure from National Regulator for Compulsory Specifications compliance investments.
Supply Chain Analysis
SFDA halal certification mandates and Emirates Authority for Standardization and Metrology cold-chain integrity protocols restrict eligible supplier pools for frozen meat imports entering Saudi Arabia and United Arab Emirates. Geographic supply concentration centers on Brazilian poultry complexes, Australian and New Zealand red meat processors, and Red Sea seafood landing facilities at Jeddah Islamic Port. Raw material dependencies include corn and soybean feed inputs for poultry, marine diesel for reefer transport, and barrier film polymers for modified-atmosphere packaging. Single-source vulnerability from Brazilian poultry concentration exceeding seventy percent of UAE frozen poultry supply creates disruption exposure. Distribution runs through hypermarket retail chains, wholesale food-service distributors, and emerging e-commerce dark stores in Riyadh's northern industrial zone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with halal certification documentation and cold-chain compliance investments creating switching costs that lock out unqualified competitors.
For Market Incumbents: Build certification moats by deepening SFDA and Emirates Authority for Standardization and Metrology documentation capabilities beyond baseline compliance. Invest in captive blast-freezing capacity relocation toward Jeddah Islamic Port and King Abdulaziz Port terminals to compress delivery windows. Defend against e-commerce dark store disintermediation by securing exclusive supply agreements with Saudi Arabian grocery platforms establishing frozen fulfillment infrastructure. For New Entrants and Emerging Players: East African cold-chain gaps in Nairobi and Addis Ababa offer first-mover positioning before established Gulf distributors extend last-mile freezer capacity. Target Kenya's underpenetrated frozen seafood segment through partnerships with local food-service distributors building cold-chain infrastructure. Enter via white-label supply to quick-service restaurant chains seeking second-source diversification from Brazilian poultry concentration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cryogenic tunnel freezing technology and blockchain-enabled temperature logging systems required for Emirates Authority for Standardization and Metrology compliance. Five-to-ten-year viability favors processors with integrated slaughter-to-freezer halal documentation and port-proximate capacity. Acquisition targets should demonstrate captive cold-chain assets and established Gulf Cooperation Council wholesale relationships. Monitor Brazilian real exchange rate volatility as inflection signal for import cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Port-Proximate Freezing Capacity | King Abdulaziz Port on-dock investments reduce post-harvest degradation for Red Sea seafood landing. |
| Blockchain Temperature Logging | Emirates Authority for Standardization and Metrology digital traceability mandates favor compliant suppliers. |
| Halal Certification Integration | SFDA end-to-end traceability requirements consolidate procurement toward certified slaughter-to-freezer suppliers. |
| E-Commerce Dark Store Partnerships | Saudi Arabian grocery platforms bypass traditional retail slotting fees through dedicated frozen fulfillment. |
| East African Last-Mile Expansion | Nairobi and Addis Ababa cold-chain gaps present first-mover advantages for frozen seafood distributors. |
Research Methodology
A spread of perspectives from quick-service restaurant procurement directors, cold-store operations managers, halal certification auditors, and hypermarket category buyers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation from SFDA regulatory filings, Emirates Authority for Standardization and Metrology protocol documents, South African National Regulator for Compulsory Specifications guidelines, and customs trade data for frozen protein flows. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Demand-supply balance dynamics across the analysis window anchored the forecast framework, with segmentation by product type, end user, packaging technology, and distribution channel informing volume allocations. Modeled dimensions included frozen meats, seafood, vegetables, and fruits; HoReCa, food service, retail, and industrial buyers; vacuum pack, modified-atmosphere, and conventional formats; and supermarket, wholesale, online retail, and convenience channels. CAGRs derived from trend extrapolation adjusted for regulatory inflection points and infrastructure investment cycles. Key inputs comprised cold-chain capacity expansion timelines and halal certification compliance rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Brazilian poultry exporters or Gulf-based integrated processors would shift outcomes. Forecasts reflect assumptions about SFDA enforcement intensity, diesel price trajectories, and barrier film technology advancement. Material shifts in Emirates Authority for Standardization and Metrology digital traceability mandates or Red Sea shipping route disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Frozen Processed Meat Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Freeze Dried Fruits Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Frozen Yogurt Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Freeze Dried Mangos Market
Processed and Frozen Foods
Chilled Soup Market