
 Europe Freeze-Dried Products Market | 2026-2036
Europe Freeze-Dried Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Freeze-Dried Products Market Foresight
Single-serve pouch bundling is shifting how European buyers evaluate freeze-dried products, replacing bulk-format loyalty with modular portion configurations. Nestlé SA leverages its retail channel control to anchor bundled breakfast sets across multiple European markets. European Freeze Dry competes through specialized contract manufacturing for pharmaceutical and military ration clients. Katadyn Group dominates outdoor and emergency preparedness segments with compact, long-shelf-life configurations.
Freeze-dried products are dehydrated materials preserved through sublimation under vacuum at temperatures typically below −40°C, yielding porous structures that rehydrate rapidly while retaining original flavor, color, and bioactive compounds. The primary commercial purpose spans extended shelf-life food supply, pharmaceutical active ingredient stability, and lightweight nutrition formats. Fruits and coffee occupy mature, high-volume positions with thin margin pools, while pharmaceutical applications sustain premium pricing through sterility and cGMP compliance requirements. Meat and pet-focused segments are recording faster growth trajectories as humanization trends in pet nutrition and protein-forward convenience foods expand addressable demand.
EMA stability guidelines, EU Green Deal energy-efficiency mandates, and REACH chemical safety protocols collectively shape product formulation, equipment investment, and facility certification across European freeze-dried production. EFSA novel food assessments add regulatory gatekeeping for innovative freeze-dried ingredient introductions, particularly in functional food positioning. Stakeholders must monitor evolving F-Gas phase-down schedules and carbon border adjustment mechanisms to calibrate capital deployment and sourcing geography decisions.
Market Dynamics
The EU Green Deal's energy-efficiency mandates are compressing operating margins for legacy lyophilization equipment while accelerating capital rotation toward vacuum systems with lower carbon footprints. Food processors and pharmaceutical contract manufacturers face simultaneous pressure from F-Gas phase-down schedules and EMA stability requirements.
Growth Catalysts
- EU Green Deal compliance deadlines:The regulation forces equipment replacement cycles, creating demand for next-generation vacuum pumps and heat recovery systems that reduce facility energy intensity.
- Pet nutrition humanization:Premium pet food brands across Germany and France are incorporating freeze-dried protein toppers, expanding addressable volume beyond traditional human consumption channels.
- Ready meal format proliferation:Single-serve pouch configurations for camping and emergency preparedness are pulling capacity expansion in contract manufacturing facilities.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings in Germany directly compress lyophilization economics, as sublimation cycles demand sustained thermal input.
- Equipment supply concentration:Vacuum system fabrication concentrates among German and Swiss specialists, creating lead time vulnerability for facility expansion timelines.
- Spray-dried alternatives:Lower-cost dehydration methods capture commodity fruit and vegetable volume where rapid rehydration is not specification-critical.
Strategic Opportunities
- Poland and Romania processing clusters:These markets offer labor cost arbitrage and proximity to Black Sea grain corridors for inbound agricultural raw material sourcing.
- Pharmaceutical aseptic filling convergence:Integrating freeze-dried active ingredients with pre-filled syringe lines creates captive demand from biologics manufacturers.
- CSRD disclosure requirements:The mandate rewards processors with verified carbon accounting, creating premium positioning for facilities with renewable energy sourcing.
Industry Challenges
- Cryogenic engineering talent scarcity:Qualified technicians for vacuum system maintenance and process optimization are concentrated in Germany and Switzerland, constraining facility scaling elsewhere.
- cGMP certification timelines:EMA facility inspections for pharmaceutical-grade production create 18-24 month qualification windows that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Freeze-Dried Products Market |
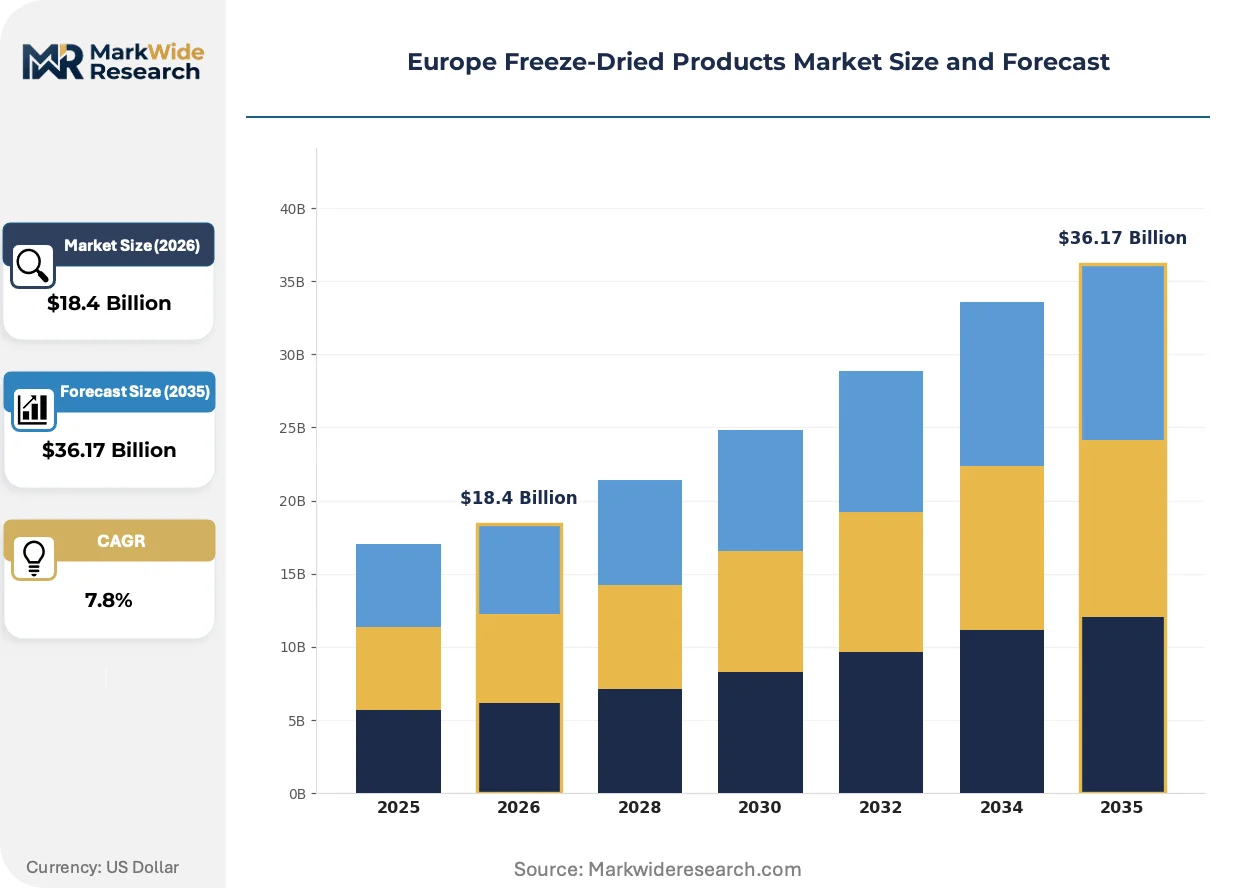
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $36.17 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Meat, Coffee Application: Food & Beverage, Pharmaceuticals, Pets, Cosmetics Distribution Channel: Retail, Online, Wholesale, Direct Sales End User: Consumers, Restaurants, Health Institutions, Manufacturers |
| Companies Covered | Katadyn Group, LYO FOOD Sp. z o.o., Nestlé SA, Unilever Group, The Hain Celestial Group, Kerry Group Plc, Mondelez International, Harmony House Foods, European Freeze Dry, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Freeze-Dried Products Market Shifts & Advancements
Equipment efficiency and process automation are converging to reshape competitive economics across European freeze-dried production. Regulatory carbon accounting and buyer procurement sophistication are accelerating differentiation between legacy and next-generation facilities.
Radio frequency-assisted lyophilization is overtaking conventional conductive heating in pharmaceutical applications. Contract manufacturers serving sterile injectables are adopting the technology to compress cycle times by 30-40%. The shift is overtaking traditional batch economics and enabling continuous processing configurations that reduce facility footprint requirements.
F-Gas Regulation phase-down schedules are forcing refrigerant transitions in industrial cooling systems. Processors must retrofit or replace vacuum pump cold traps that rely on banned hydrofluorocarbon working fluids. German and Dutch facilities face the most compressed compliance timelines, with pharmaceutical-grade installations prioritizing ammonia or CO2 cascade systems despite higher capital requirements.
Direct supplier relationships are displacing traditional ingredient broker networks for freeze-dried fruit and vegetable procurement. Large ready-meal manufacturers in France and the United Kingdom are establishing multi-year offtake agreements with Polish and Spanish processors. The pattern concentrates volume with vertically integrated suppliers capable of lot-level traceability documentation for EFSA novel food submissions.
Europe Freeze-Dried Products Market Segmentation
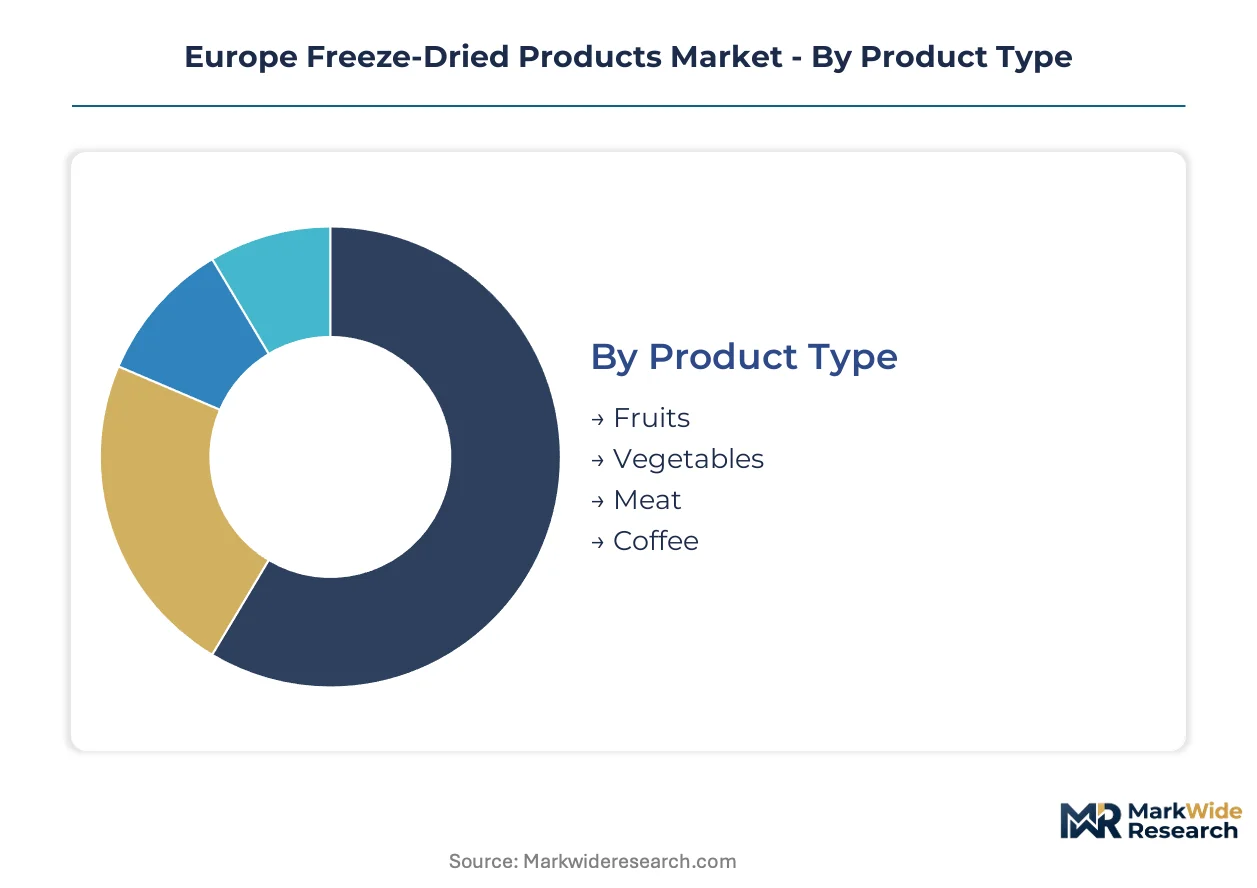
Freeze-dried product segmentation in Europe reflects divergent margin structures and regulatory exposure across food-grade and pharmaceutical-grade specifications. Procurement patterns vary sharply by end-use, with pharmaceutical buyers demanding cGMP lot documentation while retail channels prioritize shelf-life stability and rehydration speed.
Product Type:
Moisture content targets and sublimation cycle parameters define competitive positioning within each product category.
- Fruits:Strawberries, raspberries, and apples dominate volume, with porosity specifications enabling rapid rehydration for breakfast cereal and snack applications. German and Polish processors hold concentrated capacity for berry varieties sourced from Baltic states.
- Vegetables:Peas, corn, and potato segments serve ready-meal manufacturers seeking lightweight ingredients with 12-24 month ambient stability. French soup and sauce producers anchor demand for leek and onion variants.
- Meat:Chicken and beef strips target camping and military ration formats where protein density per gram drives purchasing decisions. Capacity expansion is visible in Romanian and Spanish facilities serving contract manufacturers.
- Coffee:Arabica and robusta freeze-dried extracts occupy mature positions in instant beverage supply chains. Nestlé and JDE Peet's procurement contracts lock in multi-year offtake from German and Swiss processing sites.
Mature deployment sits with Coffee. Newer deployment is concentrated in Meat.
Application:
Regulatory compliance intensity separates pharmaceutical demand from food-grade procurement patterns.
- Food & Beverage:Ready meals, breakfast cereals, and functional nutrition bars absorb the majority of European freeze-dried fruit and vegetable output. EFSA novel food assessments gate innovative ingredient introductions.
- Pharmaceuticals:Sterile injectables and biologics stability applications command premium pricing through EMA cGMP compliance requirements. Radio frequency-assisted lyophilization is compressing cycle times for parenteral antibiotics and vaccines.
- Pets:Protein toppers and complete diets for dogs and cats are climbing the fastest as humanization trends reshape pet nutrition purchasing. German and French premium brands drive formulation innovation.
- Cosmetics:Active botanical extracts for skincare serums utilize freeze-drying to preserve polyphenol integrity. Swiss and French cosmetic manufacturers source specialized contract processing.
Established volume concentrates in Food & Beverage. Steepest expansion trajectory belongs to Pets.
Distribution Channel:
Channel selection determines margin capture and traceability documentation requirements.
- Retail:Supermarket and specialty store placements require consumer-facing packaging with multilingual labeling under EU food information regulations. Nestlé SA leverages retail channel control for bundled breakfast sets.
- Online:Direct-to-consumer platforms enable subscription models for emergency preparedness and outdoor recreation segments. Katadyn Group dominates compact, long-shelf-life configurations through e-commerce specialization.
- Wholesale:Ingredient brokers and foodservice distributors handle bulk formats for industrial buyers. Direct supplier relationships are displacing traditional networks as large manufacturers seek lot-level traceability.
- Direct Sales:Contract manufacturing agreements link processors to pharmaceutical and military clients. European Freeze Dry competes through specialized relationships requiring sterile facility certification.
Volume leadership rests with Retail. Channel shift momentum favors Online.
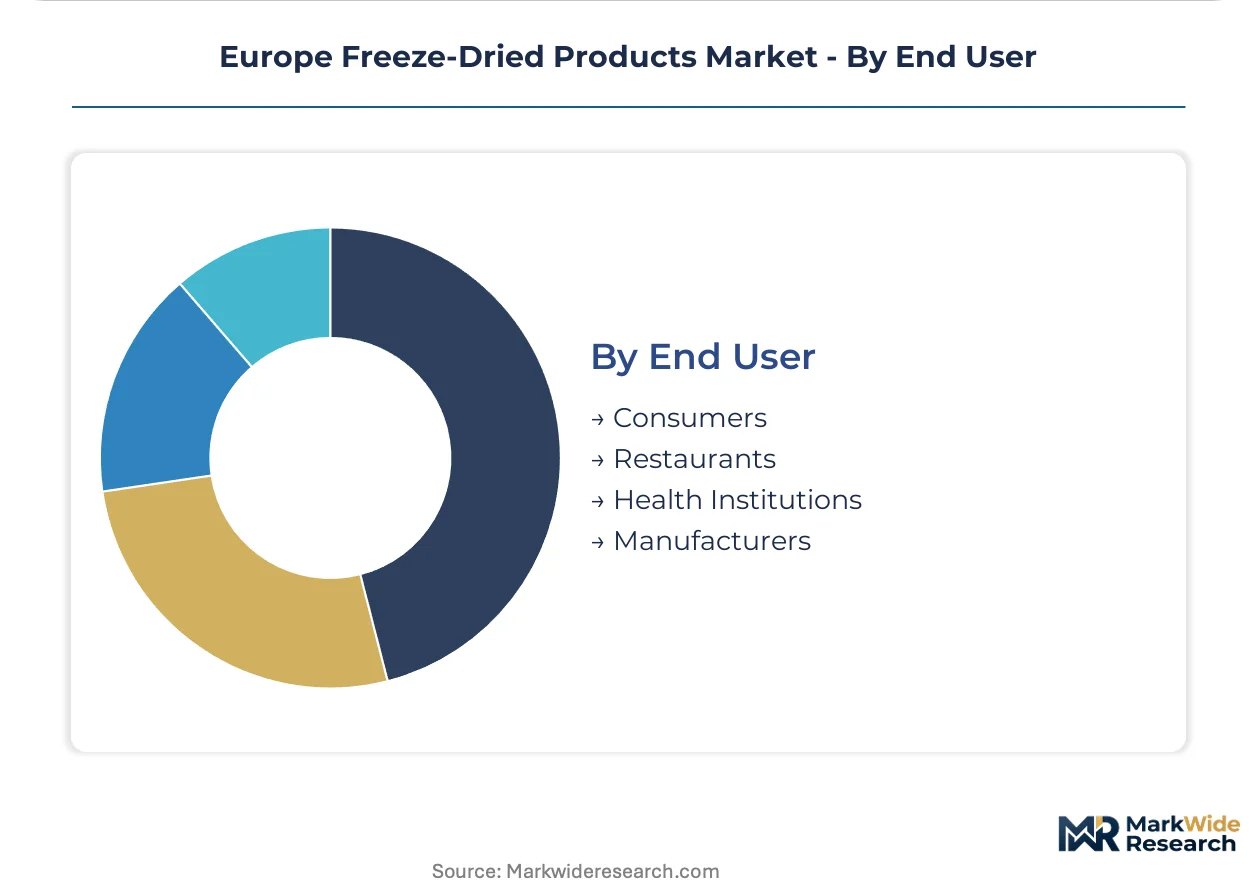
End User:
Procurement sophistication and specification stringency vary sharply across buyer categories.
- Consumers:Individual purchasers prioritize convenience, rehydration speed, and single-serve portability for camping and emergency stockpiling. Pouch bundling formats are replacing bulk loyalty.
- Restaurants:Fine dining and fast-casual operators utilize freeze-dried garnishes and flavor concentrates for consistency and extended holding. French and Italian establishments drive premium herb and spice demand.
- Health Institutions:Hospital and long-term care facilities require therapeutic nutrition formats with documented stability profiles. EMA and national health regulator oversight shapes supplier qualification.
- Manufacturers:Food, pharmaceutical, and cosmetic producers constitute the largest volume buyers, specifying moisture content, particle size, and microbial limits. Multi-year offtake agreements with Polish and Spanish processors are concentrating supply relationships.
Contracted volume concentrates with Manufacturers. Discretionary growth is visible among Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Katowice Special Economic Zone in Poland attracts freeze-dried processors with tax incentives and proximity to Baltic agricultural supply chains. This zone anchors a broader regional pattern where energy costs, regulatory compliance timelines, and raw material access determine facility placement decisions across Europe.
Germany
Pharmaceutical contract manufacturing and large-scale food processing clusters drive freeze-dried capacity concentration in Germany. The F-Gas Regulation forces refrigerant transitions in vacuum pump cold traps, compressing compliance timelines for facilities in Bavaria and Baden-Württemberg. Stuttgart-area equipment fabricators supply specialized vacuum systems to domestic and export markets.
Poland
Polish processors capture labor cost arbitrage and Black Sea grain corridor proximity for inbound agricultural sourcing. EU Green Deal energy-efficiency mandates accelerate capital rotation toward heat recovery systems in facilities near Warsaw and Kraków. The Katowice Special Economic Zone anchors contract manufacturing expansion for German and French food brands.
France
Premium pet nutrition brands and ready-meal manufacturers anchor freeze-dried ingredient demand in France. EFSA novel food assessments gate innovative ingredient introductions for functional food positioning. Lyon and Paris basin processing clusters serve domestic retail channels and export markets.
Spain
Fruit and vegetable processors in Valencia and Murcia supply freeze-dried ingredients to French and UK manufacturers. Direct supplier relationships displace traditional broker networks as large buyers seek lot-level traceability documentation. Spanish facilities leverage extended growing seasons for raw material cost advantages.
Switzerland
Pharmaceutical-grade lyophilization for sterile injectables concentrates in Swiss facilities serving biologics manufacturers. Swissmedic oversight and EMA stability guidelines enforce stringent cGMP certification requirements. Basel-area clusters integrate freeze-dried active ingredients with aseptic filling operations.
Europe Freeze-Dried Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across European freeze-dried production. Tiered market structure separates pharmaceutical-grade contract manufacturers from commodity food-grade processors. Three archetypes dominate: multinational CPG anchors controlling retail channel access, specialized contract manufacturers serving sterile pharmaceutical requirements, and outdoor recreation specialists leveraging compact format expertise. Competitive moves concentrate on direct supplier relationship formation and equipment efficiency investments.
Among diversified CPG anchors, Nestlé SA and Unilever Group exemplify scale-driven retail channel control through bundled breakfast and ready-meal configurations. Katadyn Group occupies a position within the outdoor recreation specialist tier. European Freeze Dry represents the contract manufacturing archetype serving pharmaceutical and military ration clients. Kerry Group Plc sits within the ingredient supplier tier.
| Leading Market Players |
|---|
| Katadyn Group |
| LYO FOOD Sp. z o.o. |
| Nestlé SA |
| Unilever Group |
| The Hain Celestial Group |
| Kerry Group Plc |
| Mondelez International |
| Harmony House Foods |
| European Freeze Dry |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade cGMP certification against commodity food-grade specifications bifurcates pricing power and procurement structures across European freeze-dried production. Contract manufacturers serving EMA-regulated sterile injectables command 3-4x premiums over fruit and vegetable processors, while energy-intensive vacuum system operations concentrate margin pressure in German and Polish facilities facing EU Green Deal compliance deadlines.
Pricing Analysis
Expedited lead-time premiums for pharmaceutical contract manufacturing separate pricing tiers from spot-market commodity transactions. Contract-based long-term offtake agreements dominate food-grade procurement, with volume scale and EFSA novel food certification status driving price differentiation between Polish processors and German specialists. Cost compression in energy-intensive sublimation cycles is intensifying because natural gas price volatility in Germany directly feeds facility operating economics. Ready-meal manufacturers exhibit highest price sensitivity, while biologics producers prioritize sterility assurance over unit cost.
Supply Chain Analysis
Direct-to-manufacturer channels displace traditional ingredient broker networks as large food brands seek lot-level traceability documentation. Raw material sourcing draws from Baltic states for berry varieties, Black Sea corridors for grain inputs, and extended-season Spanish growing regions for vegetable feedstocks. Single-source vulnerability concentrates in German and Swiss vacuum system fabrication, where specialized cryogenic engineering talent scarcity constrains equipment delivery timelines. Distribution runs through contract manufacturing agreements for pharmaceutical clients and bundled retail configurations for consumer-facing brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as EU Green Deal energy-efficiency mandates force capital-intensive equipment replacement cycles that weaker balance sheets cannot absorb. Facility closures and distressed asset sales will concentrate capacity with players possessing renewable energy sourcing and verified carbon accounting under CSRD disclosure requirements.
For Market Incumbents: Anticipate refrigerant transition deadlines under F-Gas Regulation by retrofitting vacuum pump cold traps to ammonia or CO2 cascade systems before compliance windows compress. Secure captive supply of Baltic berry and Black Sea grain inputs through backward integration into Polish agricultural procurement networks. Prioritize heat recovery system investments that reduce facility energy intensity and qualify for premium positioning under buyer ESG screening protocols.
For New Entrants and Emerging Players: Premium pet nutrition brands in Germany and France represent underserved buyer archetypes seeking freeze-dried protein toppers with humanization-grade positioning. Contract manufacturing capacity for military ration and emergency preparedness formats offers penetrable white-space with lower cGMP certification barriers than pharmaceutical entry. Launch through direct-to-consumer online subscription models targeting outdoor recreation segments with compact, long-shelf-life pouch configurations.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified CPG anchors seeking freeze-dried ingredient capabilities and retail channel control. Long-term viability hinges on facilities with renewable energy sourcing and verified carbon accounting that satisfy CSRD disclosure mandates. Monitor F-Gas Regulation phase-down enforcement intensity as inflection indicator for distressed asset availability and consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Equipment Efficiency Retrofit | Ammonia and CO2 cascade vacuum systems reduce energy intensity for EU Green Deal compliance. |
| Direct Supplier Relationship Formation | Multi-year offtake agreements with Polish processors secure Baltic berry supply for EFSA submissions. |
| Pet Nutrition Format Expansion | Freeze-dried protein toppers capture humanization premiums in German and French premium brands. |
| Radio Frequency Lyophilization Adoption | Contract manufacturers compress cycle times by 30-40% for parenteral antibiotics and vaccines. |
| CSRD-Aligned Carbon Accounting | Verified renewable energy sourcing creates procurement preference under buyer ESG screening protocols. |
Research Methodology
Independent corroboration across EMA facility inspection records, EU Green Deal implementation timelines, and F-Gas Regulation phase-down schedules underwrites the qualitative findings in this study. Primary interviews with freeze-dried processing plant managers, pharmaceutical contract manufacturing executives, and retail category buyers combined with secondary validation from EFSA novel food assessment databases, customs trade data for freeze-dried ingredient flows, and SEC filings of diversified CPG anchors. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates across the analysis window.
Comparable-period anchoring to historical lyophilization equipment deployment cycles and energy cost trajectories shaped the forecast framework. Segmentation dimensions modeled include product type, application, distribution channel, and end-user procurement sophistication across the projection horizon. CAGRs were derived from facility expansion announcements, contract manufacturing capacity utilization patterns, and buyer procurement intention surveys. Industry-specific inputs encompass F-Gas Regulation compliance cost estimates and EMA cGMP certification timeline distributions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to natural gas price volatility, refrigerant technology transition costs, and EFSA novel food assessment backlog durations. Forecasts reflect documented assumptions regarding equipment replacement cycle timing and buyer ESG screening adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Europe Dehydrated Food Market
Processed and Frozen Foods
Middle East and Africa Ice Cream Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Dehydrated Food Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Commercial Walk in Freezer Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market