
 Frozen Bread Market | 2026-2036
Frozen Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Bread Market Foresight
The EU Green Deal is repositioning ingredient sourcing and clean-label requirements across the frozen bread sector, compelling manufacturers to reformulate recipes and validate supply chain transparency. Grupo Bimbo leverages its vertically integrated grain procurement network to secure consistent flour quality across multiple continents. ARYZTA AG anchors its competitive stance through specialized par-baked and fully baked frozen portfolios tailored to food service scale. Lantmännen Unibake dominates Nordic and Baltic markets with rye-based and whole-grain frozen lines that align with regional dietary preferences.
Frozen bread denotes dough or partially/fully baked bread products preserved at sub-zero temperatures to arrest staling and extend shelf life, typically requiring blast freezing to minus 18 degrees Celsius or below to maintain crumb structure and volatile aromatic compounds. Its primary commercial purpose centers on enabling food service operators and retailers to deliver fresh-baked texture with minimal on-site labor and waste. Whole wheat and multigrain varieties are capturing margin pools as health-positioned offerings command premium placement in quick service restaurants and specialty stores. Vacuum sealed packs represent the fastest-growing packaging format as brands compete on extended shelf stability and reduced freezer burn incidence.
FDA standards govern frozen dough microbiological safety and labeling in the United States, while EFSA and EU Green Deal frameworks shape additive restrictions and carbon accounting expectations across European production. REACH compliance further constrains packaging material chemistry for plastic bags and clamshell containers sold into EU member states. Stakeholders must monitor how dual carbon goals in China and evolving FDA enforcement on fermented frozen products will reshape export eligibility and capital allocation for cross-border manufacturing footprints.
Market Dynamics
The EU Green Deal is forcing frozen bread manufacturers to reconfigure ingredient sourcing and carbon accounting systems, compressing margins for non-compliant suppliers while rewarding early adopters of regenerative grain procurement.
Growth Catalysts
- Quick service restaurant expansion:Fast-food chains in Germany and France are scaling par-baked frozen programs to reduce on-site labor costs and standardize product quality across franchise networks.
- EU Green Deal compliance incentives:Manufacturers sourcing regenerative wheat and validating supply chain transparency gain preferential placement in EU public procurement tenders and retail shelf negotiations.
- Vacuum sealing technology:Advanced barrier films and modified atmosphere packaging are extending frozen bread shelf life while reducing freezer burn incidence in long-haul distribution.
Market Restraints
- Energy cost volatility:Blast freezing to minus 18 degrees Celsius requires substantial electricity input, exposing margins to European natural gas price swings and grid instability.
- Flour supply concentration:Premium wheat milling capacity clusters in specific Black Sea and North American regions, creating geographic vulnerability to climate shocks and export restrictions.
- Clean-label formulation limits:EFSA additive restrictions under evolving EU frameworks constrain dough conditioners and preservatives that historically enabled extended frozen storage.
Strategic Opportunities
- Nordic rye-based specialization:Underpenetrated whole-grain and heritage rye segments in Sweden, Norway, and Finland offer premium positioning for regional taste preferences.
- Direct-to-foodservice platforms:Digital ordering portals connecting artisan frozen bakeries with independent restaurants bypass traditional wholesale distribution markups.
- Dual carbon goal alignment in China:SAMR carbon accounting requirements for imported frozen foods create first-mover advantage for EU manufacturers with verified low-carbon production.
Industry Challenges
- Refrigerated logistics talent scarcity:Cold chain engineering and blast freezing operations require specialized technicians that bakeries struggle to recruit and retain.
- REACH compliance timelines:ECHA substance restrictions on packaging adhesives and coatings force reformulation cycles that delay new product launches by 12-18 months.
- Legacy equipment integration:Automated dough portioning and freezing lines must interface with existing bakery management software, creating data interoperability friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Bread Market |
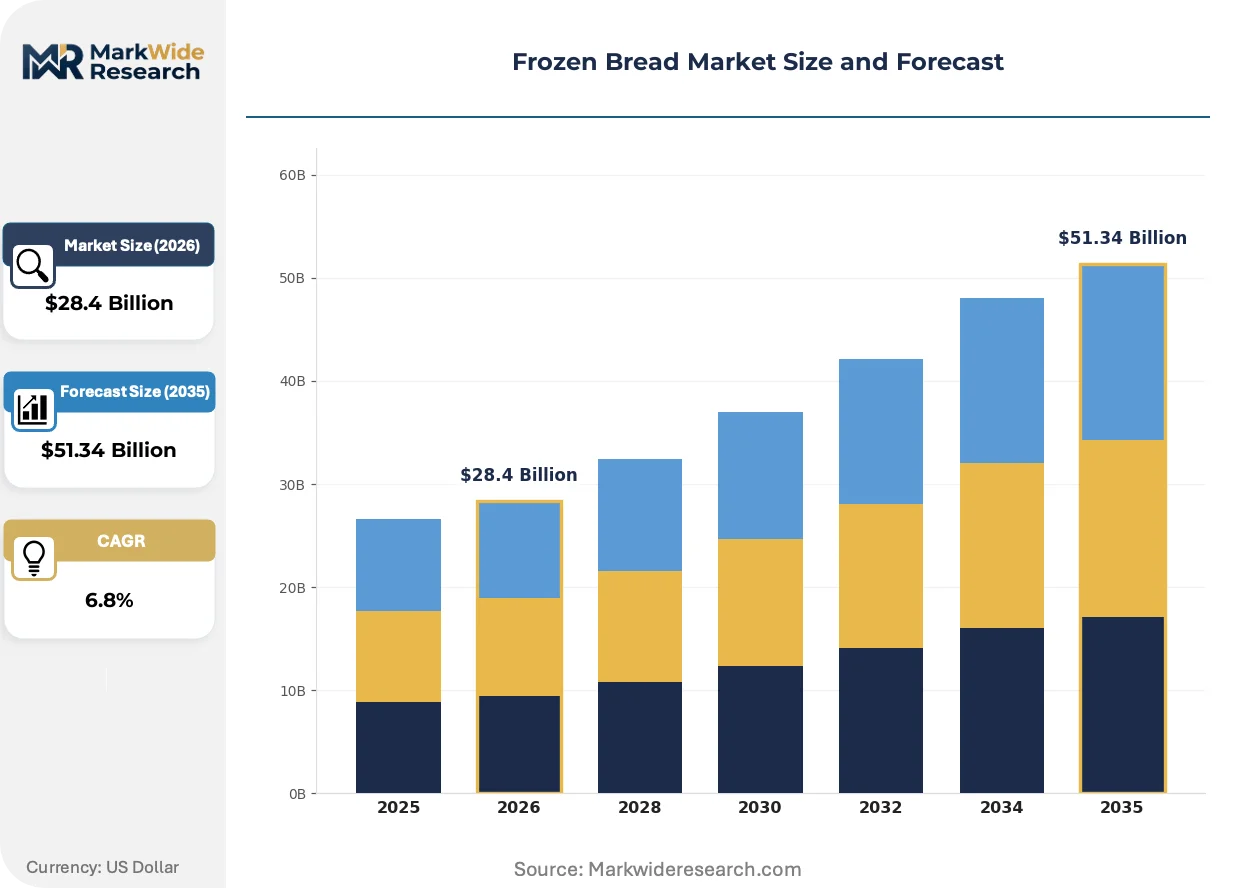
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Bread, Whole Wheat Bread, Multigrain Bread, Sourdough Bread, Rye Bread Application: Bakeries, Food Service Providers, Convenience Stores, Caterers, Quick Service Restaurants Packaging Type: Plastic Bags, Clamshell Containers, Vacuum Sealed Packs, Paper Wraps, Foil Wraps Customer Type: Households, Retailers, Food Distributors, Institutional Buyers, Specialty Stores |
| Companies Covered | Grupo Bimbo, ARYZTA AG, Lantmännen Unibake, Vandemoortele, Europastry, General Mills, Conagra Brands, Associated British Foods, Flowers Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Bread Market Shifts & Advancements
Active freeze-drying and controlled atmosphere technologies are compressing the traditional trade-off between shelf stability and sensory quality, enabling new product architectures previously excluded from frozen formats.
High-pressure processing is absorbing residual microbial loads in frozen dough without thermal degradation of aromatic volatile compounds. Artisan bakeries in Italy and Spain are adopting this post-freezing treatment to extend distribution radius while maintaining crust texture. The technology is absorbing market share from traditional chemical preservative approaches.
REACH substance restrictions are compelling packaging suppliers to eliminate specific phthalates and bisphenol derivatives from frozen bread bags and clamshells. German retailers are demanding full material disclosure certificates ahead of 2027 enforcement deadlines. Premium private-label lines are absorbing compliance costs faster than economy tiers.
Foodservice operators are consolidating frozen bread suppliers to reduce vendor management overhead, favoring par-baked specialists with multi-SKU portfolios over single-product bakeries. Hospital and institutional cafeterias in France and Belgium are shifting procurement to approved vendor lists with mandatory carbon disclosure. This concentration is visible most acutely in quick service restaurant supply agreements.
Frozen Bread Market Segmentation
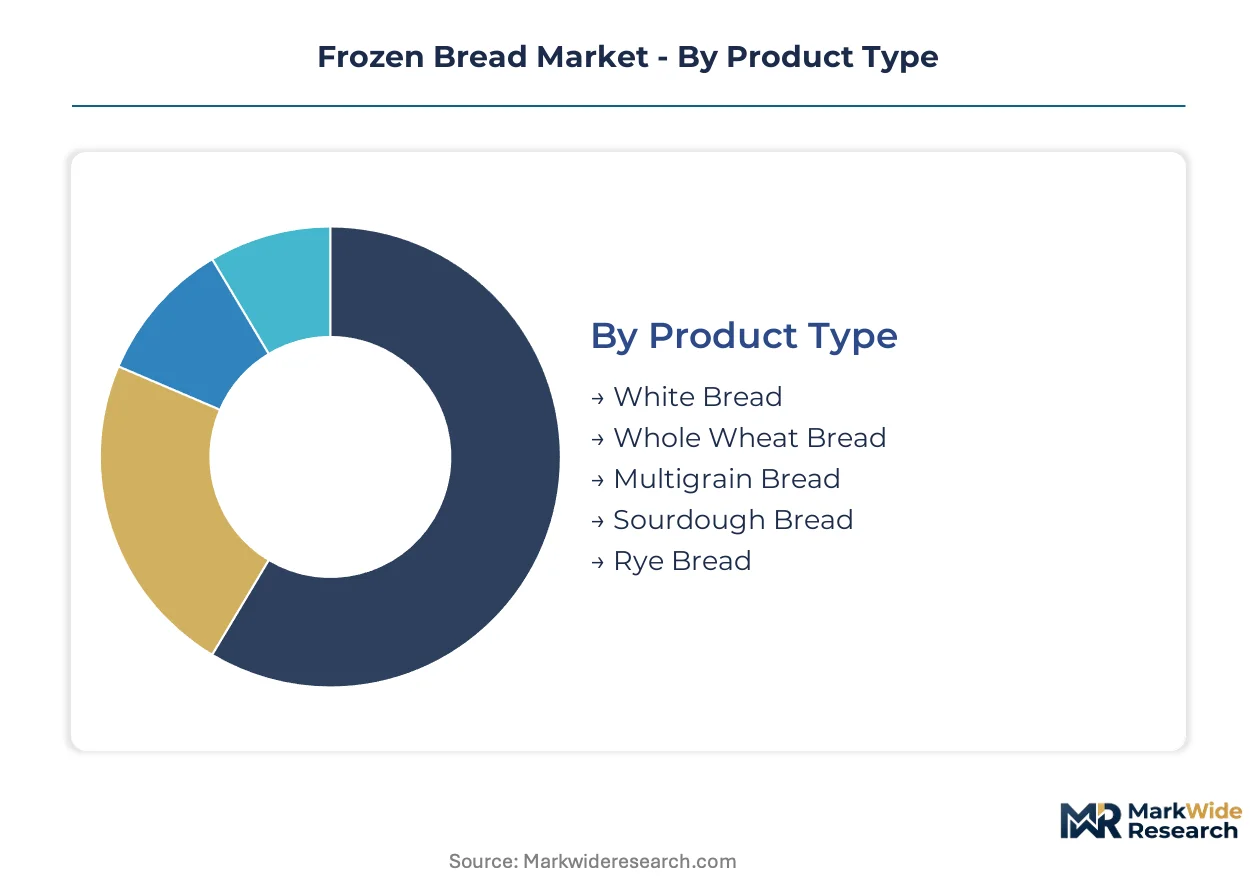
Frozen bread segmentation reveals how purchasing logic splits between health-positioned varieties commanding premium placement and operational formats optimizing foodservice throughput. Manufacturers configure production lines around these divergent margin profiles rather than treating frozen bread as a commoditized category.
Product Type:
Health credentials drive the primary purchase decision, with buyers weighing nutritional density against sensory expectations and price tolerance.
- White Bread:Standard refined-flour formulations maintain the largest production volume across industrial bakeries. Demand concentrates in quick service restaurants seeking neutral flavor profiles that accommodate diverse sandwich builds without alienating mainstream consumers.
- Whole Wheat Bread:Stone-ground and roller-milled whole grain varieties capture expanding placement in German retail chains and French institutional procurement where EU Green Deal carbon accounting rewards regenerative wheat sourcing. Premium positioning offsets higher ingredient costs.
- Multigrain Bread:Seed-inclusion and multi-flour blends address the clean-label segment with visible ingredient differentiation.
- Sourdough Bread:Long-fermentation frozen dough delivers artisan positioning to foodservice operators lacking on-site fermentation capacity.
- Rye Bread:Dense, low-moisture formulations dominate Nordic markets with heritage grain specifications.
White bread leads on scale; whole wheat bread leads on momentum.
Application:
Operational complexity determines vendor selection, with buyers prioritizing SKU consolidation and thaw-to-serve reliability over unit price.
- Quick Service Restaurants:Par-baked frozen programs standardize quality across franchise networks while eliminating on-site mixing and proofing labor. Chains in Germany and France are scaling these programs fastest as wage pressures intensify.
- Bakeries:Artisan and industrial bakeries source frozen dough to extend operating hours without night-shift baking, particularly in Spain and Italy where energy costs have compressed margins on traditional production schedules.
- Food Service Providers:Contract caterers and institutional suppliers value portion-controlled frozen formats for inventory predictability.
- Convenience Stores:In-store bakery programs rely on frozen bake-off products for fresh aroma without skilled labor.
- Caterers:Event-focused operators source frozen bread for volume flexibility and waste reduction.
Quick service restaurants anchor volume demand; bakeries show the steepest expansion trajectory as energy economics shift.
Packaging Type:
Shelf stability requirements and retail display constraints shape material selection, with regulatory deadlines forcing accelerated format transitions.
- Vacuum Sealed Packs:Multi-layer barrier films with modified atmosphere technology extend frozen storage life while eliminating freezer burn. German retailers are mandating these formats for premium private-label lines ahead of tightened ECHA substance restrictions.
- Plastic Bags:Polyethylene and polypropylene formats remain the cost baseline for economy-tier distribution despite REACH compliance pressures on adhesive layers.
- Clamshell Containers:Rigid PET and rPET structures protect artisan product integrity in specialty retail.
- Paper Wraps:Grease-resistant kraft formats serve sustainability-positioned brands in Scandinavian markets.
- Foil Wraps:Aluminum laminate structures dominate foodservice bulk packaging for thermal protection.
Plastic bags retain volume dominance; vacuum sealed packs are gaining share fastest on shelf-life extension.
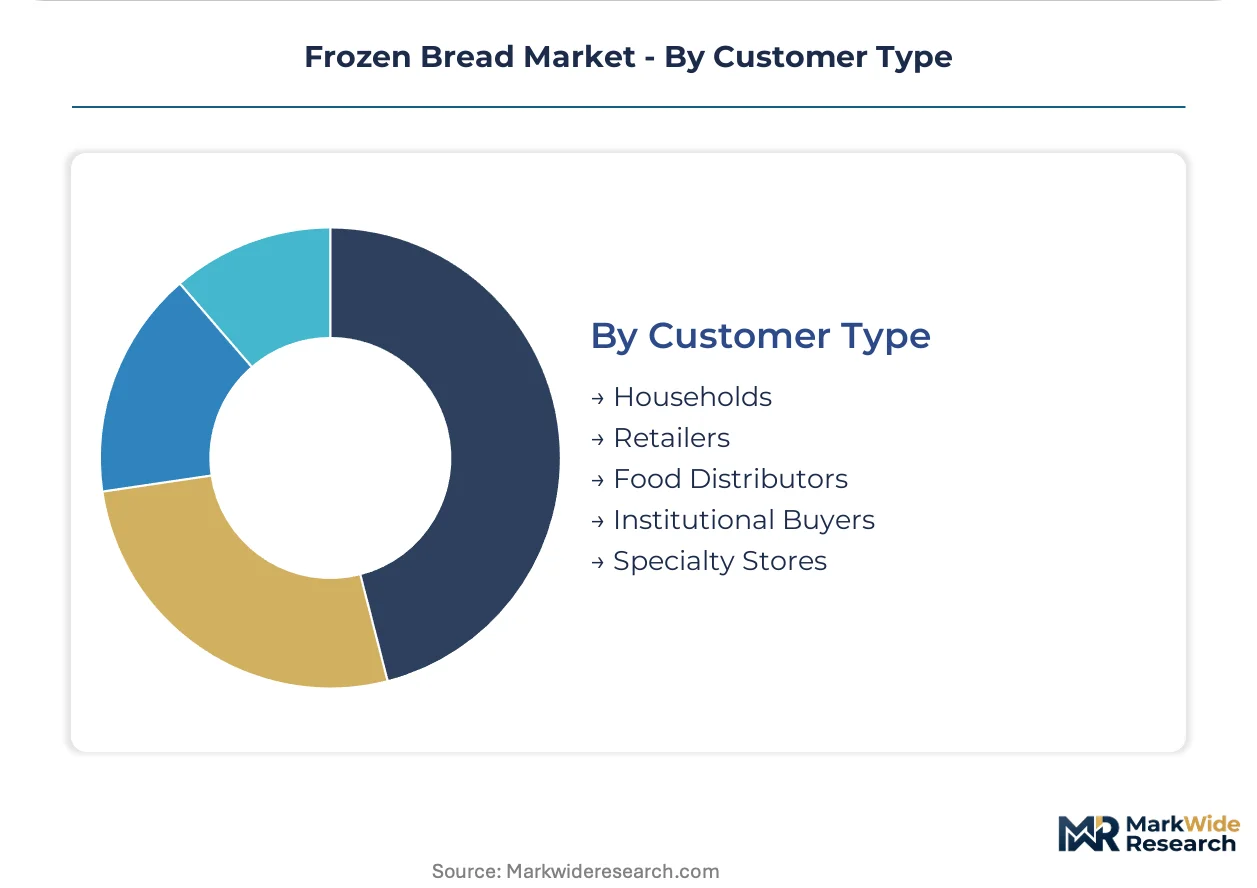
Customer Type:
Procurement scale and technical sophistication create distinct service requirements that vendors address through specialized logistics and credit terms.
- Food Distributors:Broadline and specialty distributors consolidate frozen bread into multi-temperature consolidated loads, requiring blast freezing continuity through last-mile handoffs. Their procurement power concentrates supplier relationships around ARYZTA AG and Lantmännen Unibake for portfolio breadth.
- Retailers:Supermarket and hypermarket chains negotiate direct relationships for private-label frozen bread, with EFSA additive restrictions and EU Green Deal carbon disclosure becoming mandatory tender criteria in France and Belgium.
- Households:Consumer-packaged frozen bread purchases concentrate in Nordic markets with smaller household sizes and limited daily bakery access.
- Institutional Buyers:Hospital and school cafeteria procurement shifts toward approved vendor lists with mandatory sustainability certification.
- Specialty Stores:Organic and gourmet retailers source heritage grain and artisan frozen lines for differentiation.
Food distributors command the largest order values; retailers are expanding their frozen bread assortment fastest on private-label investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bakery technician concentrations in Germany, France, and Italy anchor European frozen bread production capacity, while cold-chain engineering talent clusters in Chicago and Shanghai support North American and Asian distribution scale.
Germany
Quick service restaurant chains in Bavaria and North Rhine-Westphalia are scaling par-baked frozen programs to offset wage inflation in on-site baking labor. The EU Green Deal mandates regenerative wheat sourcing disclosure for public procurement tenders starting 2026. Industrial bakeries around Munich and Hamburg are retrofitting blast freezing lines to meet ECHA substance restrictions on packaging adhesives.
France
Artisan bakeries in Île-de-France are adopting frozen sourdough dough to extend operating hours without night-shift energy costs. EFSA additive restrictions under evolving EU frameworks constrain traditional dough conditioners. Lyon and Auvergne-Rhône-Alpes host specialized par-baked producers supplying hospital and institutional cafeterias with mandatory carbon disclosure requirements.
United States
Foodservice distributors in the Midwest and Southeast are consolidating frozen bread suppliers to reduce vendor management overhead. FDA standards govern frozen dough microbiological safety and labeling, with enforcement intensifying on fermented frozen products. Chicago anchors national cold-chain logistics networks connecting regional bakery clusters to quick service restaurant chains.
Italy
Artisan bakeries in Lombardy and Emilia-Romagna deploy high-pressure processing to extend distribution radius without thermal degradation of aromatic compounds. REACH compliance timelines for packaging materials force 12-18 month reformulation cycles. Milan hosts digital ordering platforms connecting frozen artisan producers directly with independent restaurants.
China
Quick service restaurant expansion in Shanghai and Beijing is absorbing imported frozen bread volumes as SAMR carbon accounting requirements reshape import eligibility. Dual carbon goals mandate verified low-carbon production documentation for EU manufacturers. Yangtze River Delta cold-chain infrastructure is expanding to handle blast-frozen bakery products at scale.
Frozen Bread Market Competitive Landscape
Capital-heavy producers with captive milling and freezing infrastructure compete with asset-light brand licensors and regional bakery networks that outsource manufacturing to third-party cold-chain facilities. The market exhibits tiered concentration: multinational frozen bakery conglomerates with continental scale, national champions anchored in specific grain-growing regions, and specialized par-baked suppliers focused on foodservice channels. Strategic moves center on backward integration into regenerative grain procurement and geographic expansion through co-manufacturing partnerships rather than greenfield capacity builds.
Within the multinational conglomerate tier, Grupo Bimbo and ARYZTA AG exemplify divergent sourcing strategies—one leveraging vertically integrated grain networks across multiple continents, the other anchoring competitive stance through specialized par-baked and fully baked frozen portfolios. Lantmännen Unibake occupies a position as a regional champion with Nordic and Baltic market dominance in rye-based and whole-grain lines. These three represent the archetype spectrum: global scale with upstream control, foodservice specialization with portfolio breadth, and regional taste alignment with heritage grain focus.
| Leading Market Players |
|---|
| Grupo Bimbo |
| ARYZTA AG |
| Lantmännen Unibake |
| Vandemoortele |
| Europastry |
| General Mills |
| Conagra Brands |
| Associated British Foods |
| Flowers Foods |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon accounting mandates gate access to both qualified regenerative wheat supply and premium-tier pricing placement in public procurement channels across Germany and France. Manufacturers lacking verified low-carbon production documentation face exclusion from institutional tenders while absorbing higher compliance costs without corresponding price recovery.
Pricing Analysis
Bundled logistics-and-product contracts separate from unbundled commodity spot purchases. Three-tier pricing structure across premium, standard, and economy levels stratifies by EU Green Deal certification grade and regenerative sourcing validation. Price differentiation centers on carbon disclosure documentation and blast freezing energy efficiency ratings. Pricing pressure stems from natural gas cost volatility in European blast freezing operations, with quick service restaurant chains exhibiting highest price sensitivity and institutional buyers with mandated sustainability procurement showing lowest.
Supply Chain Analysis
Domestic-content requirements under France's public procurement codes and Germany's federal catering contracts are reshaping sourcing toward verified regional grain cooperatives. Supply concentrates in Germany, France, and Poland for par-baked production capacity, with premium wheat milling capacity drawing from Black Sea and North American regions. Raw material dependencies include high-protein wheat, specialized yeast cultures, and multi-layer barrier films. Single-source vulnerability concentrates in natural gas-dependent blast freezing infrastructure. Distribution runs through foodservice broadline distributors and direct-to-retail frozen bakery platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen bread has matured into a late-cycle quality story where whole wheat and multigrain varieties command placement premiums as quick service restaurants and institutional buyers shift procurement specifications toward regenerative sourcing credentials.
For Market Incumbents: Deepen backward integration into regenerative grain procurement networks to secure flour supply continuity against Black Sea climate volatility. Expand par-baked freezing capacity in Bavaria and North Rhine-Westphalia to capture quick service restaurant consolidation demand. Prioritize ECHA-compliant packaging adhesive reformulation ahead of enforcement deadlines to avoid 12-18 month launch delays. For New Entrants and Emerging Players: High-pressure processing technology offers a wedge for artisan frozen dough specialists to extend distribution radius without thermal degradation. Target Nordic rye-based heritage grain segments in Sweden, Norway, and Finland where regional taste preferences create defendable positioning. Deploy digital ordering portals connecting directly with independent restaurants to bypass traditional wholesale distribution markups. For Investors and Strategic Acquirers: Roll-up economics work for regional par-baked specialists because foodservice operator consolidation favors multi-SKU portfolios over single-product bakeries. Over a 5-10 year horizon, acquisition targets should demonstrate captive regenerative wheat sourcing or verified low-carbon production documentation. Watch SAMR carbon accounting enforcement intensity in China as the signal for EU manufacturer export eligibility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Grain Procurement Integration | Secures flour supply continuity against Black Sea climate shocks and EU Green Deal compliance requirements. |
| Par-Baked Freezing Capacity Expansion | Captures quick service restaurant consolidation demand in Germany and France as wage pressures intensify. |
| ECHA-Compliant Packaging Reformulation | Avoids 12-18 month product launch delays ahead of 2027 substance restriction enforcement deadlines. |
| High-Pressure Processing Technology Adoption | Enables artisan bakeries to extend distribution radius without thermal degradation of aromatic compounds. |
| Direct-to-Foodservice Digital Platform Launch | Bypasses traditional wholesale distribution markups connecting frozen artisan producers with independent restaurants. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with bakery operations directors, quick service restaurant procurement leads, frozen food distribution channel managers, and EFSA regulatory affairs specialists with secondary validation. Secondary sources included EU customs trade data, ECHA substance restriction filings, SEC 10-K disclosures from listed frozen bakery conglomerates, and quick service restaurant supply agreement tender documents. Bottom-up production capacity modeling and top-down demand segmentation triangulated volume estimates.
Historical reference periods anchored the forecast window to pre-pandemic baseline volumes and post-energy-crisis recovery trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including product type, application channel, packaging format, and customer procurement scale. CAGRs derived from regression analysis against macroeconomic indicators and industry-specific inputs including wheat futures price volatility and natural gas cost indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement intensity and SAMR carbon accounting rule finalization in China. Forecasts reflect documented assumptions regarding regenerative wheat adoption rates and blast freezing energy efficiency improvements. A small set of triggers—ECHA packaging adhesive deadline compliance rates and quick service restaurant par-baked program rollout velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market
Processed and Frozen Foods
Europe Dehydrated Food Market
Processed and Frozen Foods
Germany Frozen Snack Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
Chilled Soup Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
Frozen Snacks Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
Frozen Soup Market
Processed and Frozen Foods
North America Dehydrated Food Market