
 Asia-Pacific Ceramic Tiles Market | 2026-2036
Asia-Pacific Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ceramic Tiles Market Outlook
Vietnam's northern provinces is tilting the regional supply map as new kiln complexes come online near Hai Phong. Dongpeng Holdings leverages its Guangdong base to dominate high-throughput porcelain production for export markets. SCG Ceramics anchors Thai domestic demand through vertically integrated distribution reaching provincial construction hubs. Somany Ceramics competes across India's tier-two cities with specialized vitrified tile portfolios tailored to middle-income housing.
Ceramic tiles are sintered clay-based surfacing materials, typically composed of kaolin, feldspar, and silica, fired at temperatures between 1,000°C and 1,400°C to achieve hardness, water resistance, and dimensional stability; they serve as primary flooring and wall cladding solutions in residential, commercial, and infrastructure applications. Porcelain tiles command the steepest margin pools due to density requirements and technical performance specifications that limit producer entry. Glazed tiles sustain volume leadership across Southeast Asian residential channels where cost sensitivity outweighs durability premiums. Vitrified tiles represent the fastest-growing structural category as Indian and Vietnamese developers specify full-body tiles for high-traffic commercial spaces.
China's SAMR enforces GB standards on radon emission and dimensional tolerance that filter subscale producers from export eligibility. India's BIS certification mandate for ceramic floor and wall tiles, administered through the Quality Control Order, redirects procurement toward domestic manufacturers in Morbi and Thangadh. Thailand's industrial estate authorities coordinate with METI-aligned technical protocols for Japanese-funded construction projects. Stakeholders must monitor how diverging national standards across ASEAN, China, and India fragment certification costs and determine which production bases can serve multiple jurisdictions without redundant testing regimes.
Market Dynamics
India's BIS certification mandate and China's SAMR enforcement of GB standards are compressing export eligibility for subscale producers while concentrating procurement toward certified manufacturing belts in Morbi, Thangadh, and Guangdong.
Growth Catalysts
- Urban residential construction:Southeast Asian housing stock expansion absorbs rising porcelain and vitrified tile volumes, particularly in Vietnamese provincial cities and Indonesian secondary metros.
- GB standards enforcement:China's SAMR radon emission and dimensional tolerance requirements filter non-compliant producers from cross-border supply chains.
- Vitrified tile specification:Commercial developers across India and Vietnam specify full-body tiles for high-traffic infrastructure, displacing glazed alternatives in airports, hospitals, and retail complexes.
Market Restraints
- Natural gas cost volatility:Kiln operations in Morbi and Thangadh face margin compression from fluctuating LNG import prices tied to spot market exposure.
- Kaolin supply concentration:Premium clay deposits in Guangxi and Rajasthan concentrate upstream input control among regional mining consortia.
- Thick-tile technical limitation:Full-body vitrified production above 12mm thickness faces firing uniformity constraints that restrict large-format commercial applications.
Strategic Opportunities
- Vietnam's northern corridor:Hai Phong-adjacent kiln complexes offer tariff-advantaged export positioning into ASEAN markets and Japanese-funded construction.
- Digital specification platforms:Architect and contractor procurement through BIM-integrated material libraries reduces sampling logistics and accelerates project timelines.
- PLI scheme alignment:India's production-linked incentive framework for advanced ceramics rewards capital expenditure in automated glazing and sorting lines.
Industry Challenges
- Kiln automation expertise:Morbi and Thangadh manufacturers compete for limited process engineers capable of programming roller-hearth temperature profiling systems.
- BIS certification timelines:Quality Control Order testing queues extend 14-18 weeks, delaying export readiness for new product lines.
- Legacy distributor integration:Tier-two city stockists resist inventory management system adoption, fragmenting demand visibility for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ceramic Tiles Market |
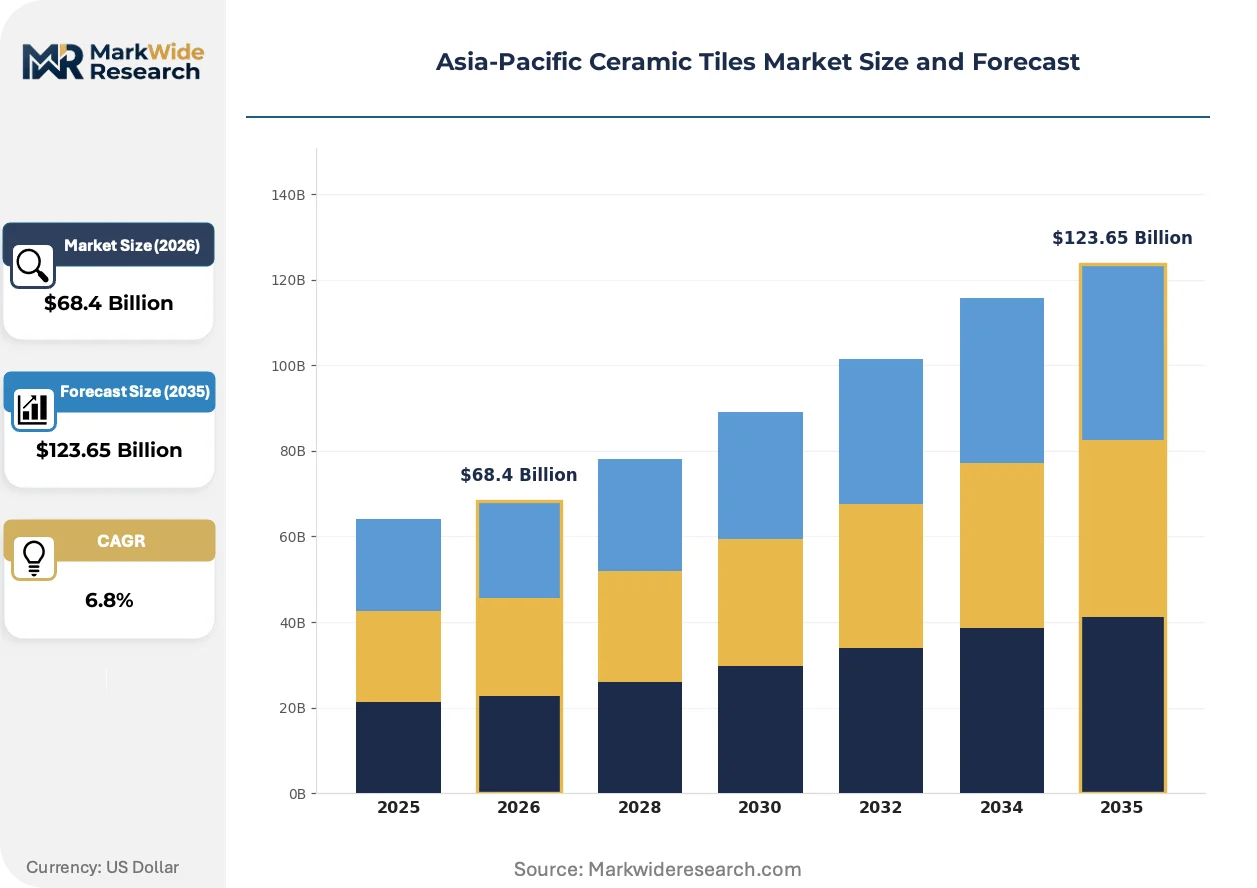
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Porcelain Tiles, Vitrified Tiles, Unglazed Tiles End Use: Residential Applications, Commercial Spaces, Industrial Use, Outdoor Settings Installation Type: Flooring, Wall-mounted, Countertops, Backsplashes Distribution Channel: Online Retail, Specialty Stores, Home Improvement Centers, Direct Sales |
| Companies Covered | Kajaria Ceramics, SCG Ceramics, RAK Ceramics, Mohawk Industries, Atlas Concorde, Somany Ceramics, Dongpeng Holdings, China Ceramics Co. Ltd, Foshan Hanse Industrial Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ceramic Tiles Market Strategic Shifts
Digital inkjet decoration and thin-tile body technologies are compressing firing cycles and expanding format flexibility across Asia-Pacific production bases. These shifts intersect with tightening emissions protocols and evolving procurement behaviors.
Thin large-format porcelain slabs are migrating from niche facade cladding into mainstream residential flooring as Indian and Vietnamese developers specify 3-6mm bodies for high-rise weight reduction. Specifiers in Bangkok and Jakarta accelerate adoption for renovation projects where structural load limits constrain traditional tile weight. The technology is migrating from premium commercial segments toward mid-market housing through localized Guangdong equipment licensing.
India's BIS Quality Control Order for ceramic floor and wall tiles redirects public procurement toward domestic certified manufacturers, excluding unregistered imports from Bangladesh and unbranded Chinese supply. State-level housing boards in Maharashtra and Karnataka now embed BIS marks as mandatory tender qualifications. Morbi-based exporters absorb compliance costs through in-house laboratory investment while smaller Thangadh units face consolidation pressure.
Direct manufacturer-contractor relationships are displacing traditional multi-tier distribution in Vietnam's commercial construction channel. Dong Nai and Binh Duong project developers source full-container loads through digital tender platforms, bypassing provincial stockists. This pattern concentrates most visibly in Japanese-funded industrial estate construction where METI-aligned technical protocols favor documented supply chain transparency over distributor relationships.
Asia-Pacific Ceramic Tiles Market Segmentation
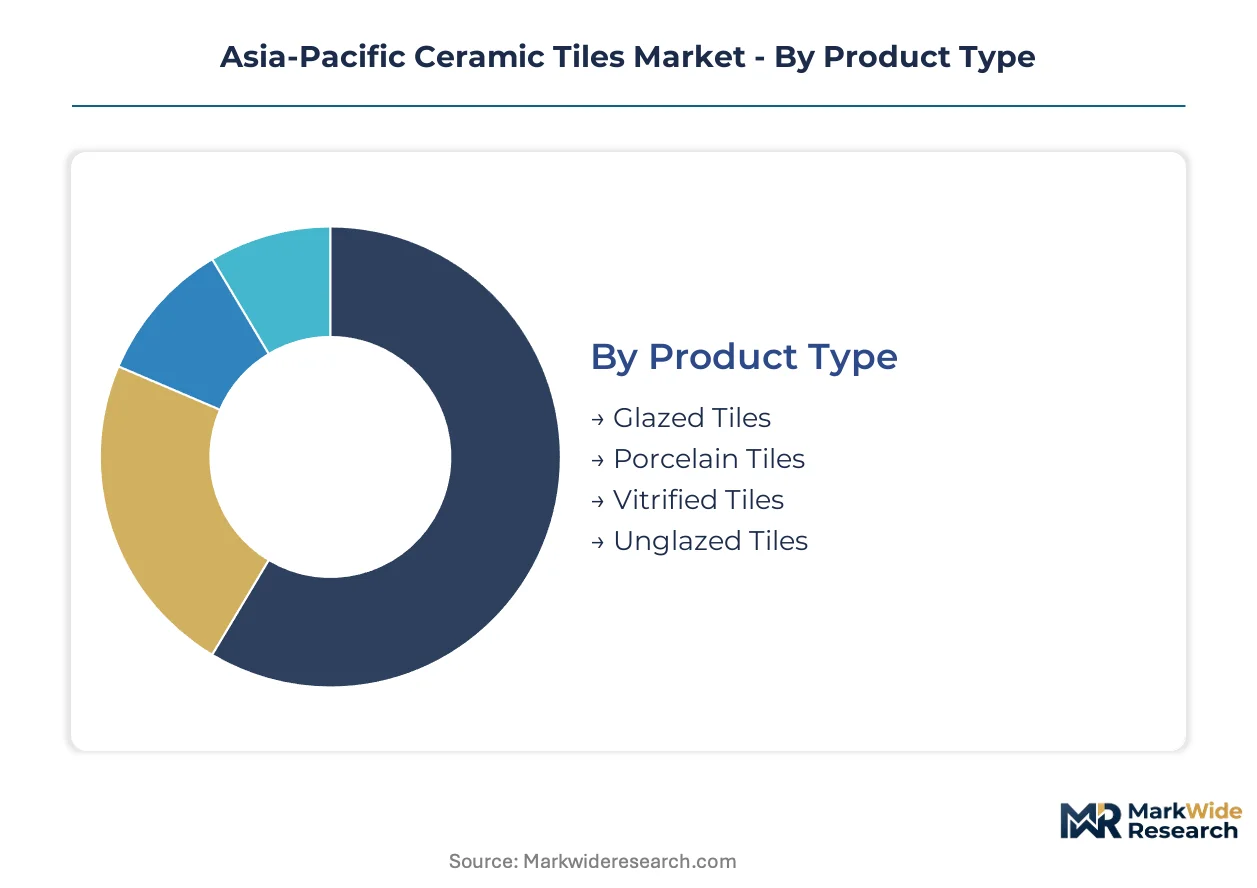
Ceramic tile segmentation across the Asia-Pacific region reflects divergent cost sensitivities, technical specifications, and procurement channel preferences. Manufacturers configure production lines around product density, end-use durability requirements, and distribution reach rather than pursuing uniform positioning.
Product Type:
Mature glazed formats coexist with emerging full-body technologies across Southeast Asian and Indian production bases.
- Glazed Tiles:Surface-coated clay bodies fired at moderate temperatures dominate residential replacement cycles in Indonesian and Philippine provincial markets. Cost positioning below porcelain alternatives sustains volume throughput despite inferior abrasion resistance in high-traffic commercial environments.
- Porcelain Tiles:Dense, low-porosity ceramics fired above 1,200°C command specification preference in Vietnamese high-rise residential and Thai hospitality projects. Technical performance thresholds for water absorption and breaking strength limit viable producer entry to Guangdong and select Morbi lines with roller-hearth kiln automation.
- Vitrified Tiles:Full-body homogeneous ceramics with silica-glass matrices penetrate Indian commercial infrastructure—airports, hospitals, retail complexes—where surface wear uniformity outweighs first-cost premiums.
- Unglazed Tiles:Natural clay surfaces without protective coatings serve industrial and outdoor drainage applications across Australia's mining corridor and New Zealand agricultural processing facilities.
Glazed tiles retain volume leadership; vitrified tiles hold the steepest expansion curve.
End Use:
Application-driven specification splits procurement between cost-optimized housing stock and performance-weighted commercial infrastructure.
- Residential Applications:Floor and wall surfacing in multi-unit housing across Vietnam's Dong Nai-Binh Duong corridor and India's tier-two cities absorbs standardized 600x600mm formats. Developer procurement through direct manufacturer tender platforms is displacing traditional distributor networks.
- Commercial Spaces:Retail complexes, hospitality venues, and healthcare facilities in Bangkok and Jakarta specify large-format porcelain and vitrified bodies for durability under sustained foot traffic. Japanese-funded industrial estate construction applies METI-aligned technical protocols favoring documented supply chain transparency.
- Industrial Use:Chemical-resistant quarry tiles and heavy-duty pressed ceramics line food processing plants and pharmaceutical cleanrooms across Australia's manufacturing belt.
- Outdoor Settings:Frost-resistant pavers and anti-slip textured surfaces serve municipal plaza and transportation infrastructure projects in South Korea's provincial cities and Japan's earthquake-reconstruction zones.
Residential applications anchor procurement volumes; commercial spaces drive margin expansion through specification premiums.
Installation Type:
Structural load constraints and surface area economics determine format selection across vertical and horizontal applications.
- Flooring:Primary load-bearing surfaces in residential and commercial buildings specify 8-12mm thickness for structural integrity. Thin large-format porcelain slabs at 3-6mm are penetrating high-rise renovation segments in Bangkok and Jakarta where weight reduction overrides traditional thickness preferences.
- Wall-mounted:Vertical cladding applications favor lighter, larger formats with reduced structural anchoring requirements. Digital inkjet decoration enables marble and wood-grain aesthetic replication at thicknesses below flooring specifications.
- Countertops:Kitchen and vanity surfaces in premium Indian housing specify full-body vitrified or engineered stone composites for stain resistance and thermal shock tolerance.
- Backsplashes:Decorative wall segments in residential kitchens and food service facilities utilize mosaic and subway formats with glazed protective surfaces.
Flooring commands the dominant share of installed square footage; wall-mounted applications are expanding most quickly through large-format thin-body adoption.
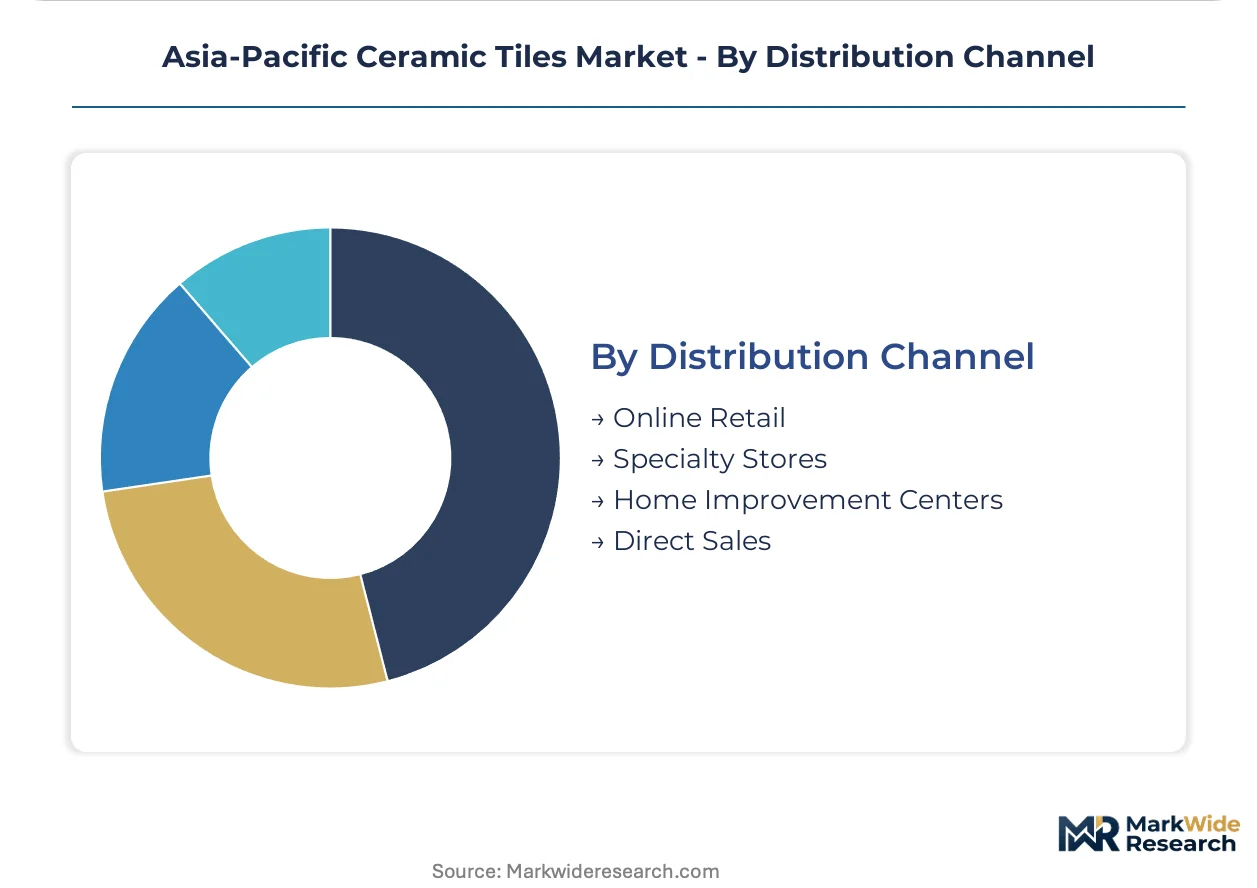
Distribution Channel:
Channel configuration reflects project scale, buyer technical sophistication, and inventory carrying cost tolerance across fragmented regional markets.
- Online Retail:Digital platforms aggregate small-lot residential procurement in Australia's dispersed population centers and Indian metro satellite cities. Sample logistics and freight damage rates constrain category penetration for fragile ceramic formats.
- Specialty Stores:Independent tile retailers with in-house design consultation dominate premium residential renovation in Japan's urban prefectures and South Korea's Seoul-Incheon corridor. Showroom inventory depth determines competitive positioning.
- Home Improvement Centers:Big-box retailers with private-label sourcing capture standardized replacement demand in Australia's Bunnings-dominated market and Thailand's HomePro network.
- Direct Sales:Manufacturer-contractor relationships bypass distribution tiers in Vietnamese commercial construction and Indian public housing tenders. Container-load procurement through digital tender platforms concentrates in Japanese-funded industrial estate development.
Specialty stores retain margin leadership; direct sales channels are gaining share fastest through project-scale procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong's kiln clusters and Gujarat's Morbi-Thangadh belt concentrate fired ceramic capacity across the Asia-Pacific region. SAMR's GB standards and India's BIS Quality Control Order filter cross-border supply eligibility. Vietnam's northern corridor and Indonesia's secondary metros absorb rising porcelain and vitrified volumes.
China
Guangdong province anchors high-throughput porcelain production for export markets. SAMR enforces GB standards on radon emission and dimensional tolerance that exclude subscale producers from cross-border eligibility. Foshan and Zhengzhou kiln complexes invest in roller-hearth automation to maintain specification access.
India
Tier-two city housing stock expansion drives vitrified tile absorption in Maharashtra and Karnataka. BIS certification mandates under the Quality Control Order redirect public procurement toward domestic manufacturers. Morbi and Thangadh clusters face consolidation pressure as compliance costs favor integrated laboratory investment.
Vietnam
Provincial city construction across Dong Nai and Binh Duong corridors specifies large-format porcelain for high-rise residential. Japanese-funded industrial estate projects apply METI-aligned technical protocols favoring documented supply chain transparency. Hai Phong-adjacent kiln complexes offer tariff-advantaged export positioning into ASEAN markets.
Thailand
Hospitality and retail infrastructure in Bangkok anchors premium porcelain specification. Industrial estate authorities coordinate technical protocols for Japanese-funded construction projects. SCG Ceramics leverages vertically integrated distribution reaching provincial construction hubs outside the capital corridor.
Indonesia
Secondary metro housing development in Surabaya and Bandung absorbs standardized glazed tile volumes. Cost-sensitive residential channels prioritize surface-coated clay bodies over porcelain alternatives. Local distributors face displacement pressure as direct manufacturer-contractor relationships consolidate procurement.
Asia-Pacific Ceramic Tiles Market Competitive Environment
Vertically integrated conglomerates and specialized regional fabricators split the market along export capability and domestic distribution reach. Chinese producers with Guangdong bases dominate high-throughput roller-hearth capacity for cross-border supply. Indian manufacturers in Gujarat compete through BIS-certified product lines tailored to public housing tender requirements. Vietnamese emerging players leverage Hai Phong logistics corridors for ASEAN market access. Capacity expansion and certification compliance represent the dominant competitive moves across production bases.
Among India-based fabricators, Kajaria Ceramics and Somany Ceramics occupy positions within the certified domestic supply tier serving state housing board procurement. SCG Ceramics anchors Thai market presence through distribution integration reaching provincial construction hubs. Dongpeng Holdings exemplifies the scale-driven export archetype with Guangdong-based kiln capacity targeting specification-grade porcelain demand across Southeast Asian markets.
| Leading Market Players |
|---|
| Kajaria Ceramics |
| SCG Ceramics |
| RAK Ceramics |
| Mohawk Industries |
| Atlas Concorde |
| Somany Ceramics |
| Dongpeng Holdings |
| China Ceramics Co. Ltd |
| Foshan Hanse Industrial Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Natural gas cost volatility across Gujarat's Morbi-Thangadh belt compresses margin spreads between BIS-certified premium tiers and unbranded economy supply, forcing kiln operators to reconfigure procurement around spot LNG hedging and captive coal-gasification trials that reshape upstream fuel sourcing geography.
Pricing Analysis
India's BIS Quality Control Order dictates the pricing tier structure across domestic ceramic tile procurement. Three-tier pricing separates certified premium porcelain from standard glazed formats and unregistered economy imports. Price differentiation rests on certification grade and roller-hearth automation level. Cost compression in economy tiers is intensifying because Bangladeshi and unbranded Chinese supply faces exclusion from state housing tenders. Public sector buyers demonstrate lowest price sensitivity; provincial retail channels exhibit highest.
Supply Chain Analysis
Guangdong's Foshan-Zhengzhou kiln complexes and Gujarat's Morbi-Thangadh belt hold dominant fired ceramic capacity. Geographic supply concentrates in China, India, and Vietnam's emerging Hai Phong corridor. Raw material dependencies draw from Guangxi kaolin deposits, Rajasthan feldspar consortia, and imported LNG feedstock. Single-source vulnerability runs through concentrated premium clay mining rights. Distribution runs through vertically integrated manufacturer networks and direct contractor platforms in commercial construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through BIS certification and SAMR GB standards creates durable defensive moats. Switching costs for certified supply chains lock in specification-grade procurement relationships.
For Market Incumbents: Entrench certification advantages through in-house laboratory investment that compresses BIS testing timelines from 18 weeks toward 10-week turnaround. Acquire distressed Thangadh assets to consolidate roller-hearth automation expertise before emerging Vietnamese kiln complexes reach scale. Threat vector: Hai Phong-adjacent producers leveraging tariff-advantaged ASEAN export positioning. For New Entrants and Emerging Players: Vietnam's northern provinces offer underpenetrated white space for METI-aligned supply to Japanese-funded industrial estate construction. Target direct manufacturer-contractor procurement platforms in Dong Nai-Binh Duong corridors where distributor displacement accelerates. Go-to-market angle: documented supply chain transparency protocols that bypass legacy stockist networks. For Investors and Strategic Acquirers: India's BIS enforcement milestone reshapes the acquisition landscape toward certified domestic manufacturers with integrated laboratory infrastructure. Long-term viability favors Morbi-based fabricators with state housing board tender access and automated glazing line capital already deployed. Acquisition target archetype: BIS-certified mid-cap producers facing liquidity pressure from compliance cost absorption. Signal to watch: BIS testing queue lengths as indicator of certification bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kaolin Mining | Captive Rajasthan and Guangxi clay supply secures input cost stability against mining consortium pricing power. |
| Roller-Hearth Kiln Automation Deployment | Temperature profiling precision unlocks GB standard compliance and large-format vitrified tile specification access. |
| In-House BIS Laboratory Investment | Accelerated Quality Control Order testing cycles compress export readiness timelines for new product launches. |
| Direct Contractor Platform Development | Bypasses fragmented tier-two distributor networks in Vietnamese commercial construction procurement. |
| Hai Phong Logistics Corridor Expansion | Tariff-advantaged ASEAN export positioning displaces Guangdong supply in Japanese-funded regional projects. |
Study Parameters
A standing panel of kiln operations managers, state housing board procurement officers, ceramic tile distributors, and BIS certification laboratory directors provided ongoing calibration across the analysis window. Primary interviews with Morbi and Thangadh manufacturing executives combined with secondary validation from Indian customs export records, Gujarat industrial estate authority filings, and SAMR GB standard enforcement bulletins. Bottom-up production capacity surveys triangulated against top-down construction sector absorption estimates.
Scenario-bracketing around natural gas price volatility and BIS certification timeline variations anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product density tier, end-use application, installation format, and distribution channel structure. CAGRs derived from production capacity expansion schedules correlated with provincial housing stock completion data and commercial infrastructure project pipelines.
Practitioners should monitor BIS testing queue lengths, spot LNG price movements, and Hai Phong kiln complex commissioning schedules for early signals of supply chain reconfiguration. Quarterly review of state housing tender award patterns and METI-aligned project specifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Ceramic Coating Market
Ceramics
Global Alumina Market
Ceramics
Pottery Ceramics Market
Ceramics
Global Alumina Trihydrate Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Boiler Refractory Material Market
Ceramics
Fire Clay Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Yttria-Stabilized Zirconia (YSZ) Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Wollastonite Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
Ceramic Substrate Market
Ceramics
Europe Aluminum Oxide Market