
 Allulose Market | 2026-2036
Allulose Market Size, Share, and Industry Trends Forecast 2026-2036
Allulose Market Analysis
China is reconfiguring supply dynamics through expanding enzymatic conversion capacity for rare sugars. CJ CheilJedang leverages proprietary biocatalytic platforms to sustain cost leadership in liquid allulose production. Tate & Lyle anchors Western supply security through integrated corn-based feedstock operations in North America. Matsutani Chemical Industry dominates crystalline powder grades through decades of specialty sweetener expertise.
Allulose is a rare monosaccharide, epimer of fructose at the C-3 position, yielding 0.2–0.4 kcal/g versus sucrose's 4 kcal/g while delivering comparable bulk and Maillard browning functionality. Commercial production relies on enzymatic epimerization of fructose using D-psicose 3-epimerase, followed by chromatographic separation to achieve food-grade purity exceeding 99.5%. Powder formulations lead volume due to shelf stability and ease of blending in dry mixes, though liquid syrups capture margin pools in beverage manufacturing where dissolution speed matters. Confectionery applications represent the fastest-growing segment as chocolate and gummy producers reformulate for sugar claims.
The FDA's GRAS notification pathway and nutrition labeling exemption for allulose have accelerated formulation trials across US food manufacturers. EFSA's ongoing novel food assessment in Europe shapes market access timelines for entrants targeting EU27 expansion. Stakeholders must monitor regulatory divergence between jurisdictions, as approval status directly determines addressable market scope and investment prioritization for capacity allocation.
Market Dynamics
Enzymatic epimerization economics now govern competitive positioning as manufacturers scale D-psicose 3-epimerase platforms to compress unit costs below crystalline sucrose parity. Chromatographic separation bottlenecks determine which producers capture margin in beverage-grade liquid syrups versus powder formulations.
Growth Catalysts
- FDA Nutrition Labeling Exemption:The 2019 decision excluding allulose from total and added sugars declarations removed formulation cost penalties for US beverage manufacturers targeting clean-label positioning.
- Maillard Reactivity:Allulose browns identically to sucrose during thermal processing, enabling confectionery producers to reformulate chocolate and baked goods without altering surface chemistry or flavor profiles.
- China:Expanding enzymatic conversion capacity for rare sugars is reconfiguring feedstock sourcing patterns and pressuring legacy corn-based supply chains.
Market Restraints
- Fructose Feedstock Volatility:Corn syrup price swings directly compress margins for North American producers lacking backward integration into starch processing.
- Supply Concentration:Three biocatalytic platform holders control liquid-grade output, creating single-source vulnerability for beverage formulators requiring tanker-scale delivery.
- EFSA Novel Food Assessment:Pending European Union approval timelines block EU27 market access, forcing capacity allocation toward already-saturated US demand pools.
Strategic Opportunities
- Sports Nutrition:Ready-to-drink protein beverages represent underpenetrated white space where rapid-dissolution liquid allulose displaces erythritol-blend sweetness systems.
- Japan:METI's functional foods framework permits FOSHU claims for rare sugars, creating regulatory arbitrage for early entrants versus slower-moving EU27 competitors.
- Direct-to-Consumer Powder:E-commerce channels enable specialty crystalline grades to bypass conventional foodservice distribution, capturing premium pricing from keto and diabetic consumer segments.
Industry Challenges
- Biocatalytic Engineering Talent:Shortage of enzymatic process chemists constrains scale-up velocity for second-generation epimerase variants with improved thermal stability.
- Food-Grade Chromatography Certification:Validating resin-based separation systems to 99.5% purity standards extends facility commissioning timelines by 18-24 months.
- Legacy Sweetener Integration:Reformulation teams must recalibrate water activity and humectancy when replacing sucrose in existing production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allulose Market |
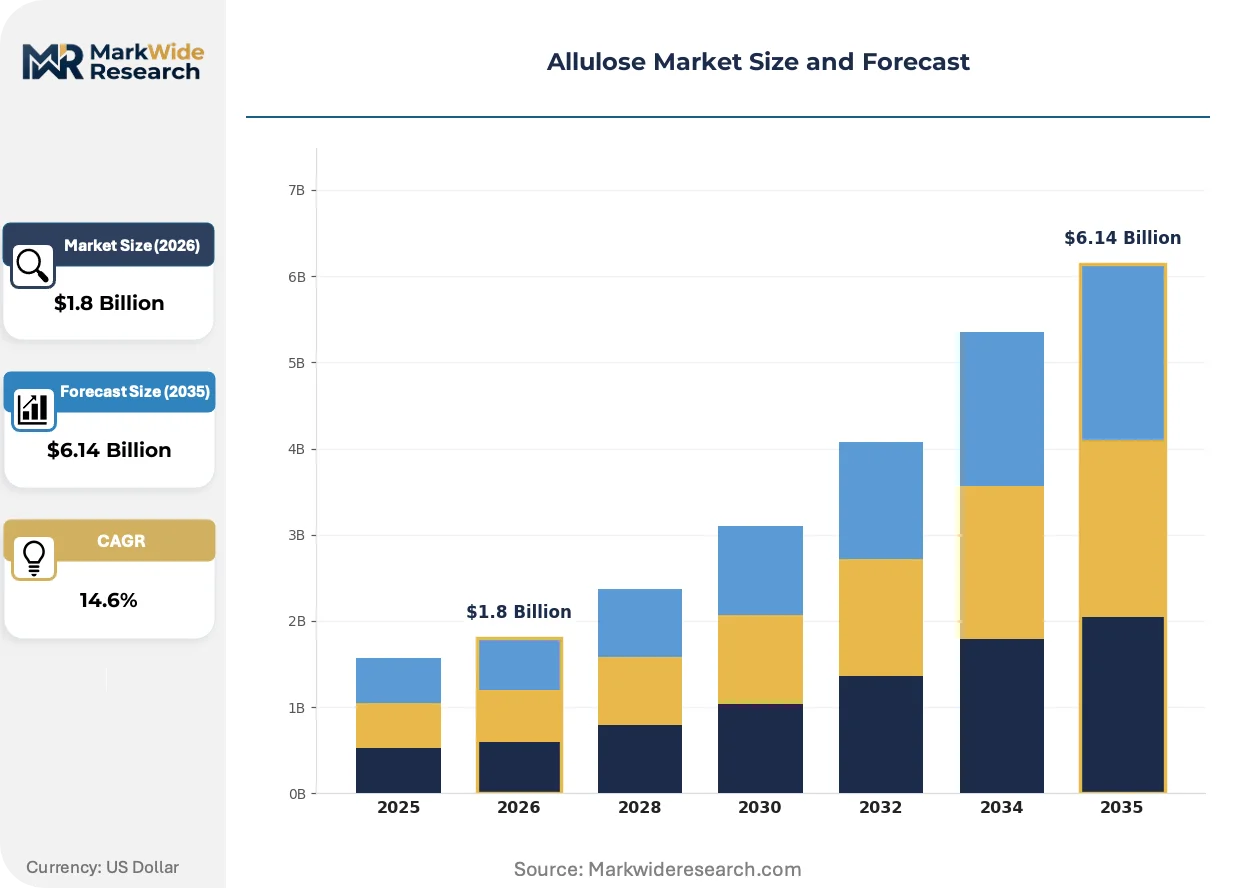
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Tablets, Syrup Application: Beverages, Bakery Products, Dairy Products, Confectionery End User: Food Manufacturers, Nutraceutical Companies, Dietary Supplement Providers, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Tate & Lyle, CJ CheilJedang, Matsutani Chemical Industry, Ingredion, Samyang Corporation, Bonumose, Anderson Advanced Ingredients, Apura Ingredients, Heartland Food Products Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allulose Market Emerging Trajectories
Biocatalytic process intensification and regulatory arbitrage strategies now separate margin leaders from commodity aspartame replacers. Formulation science advances are compressing the performance gap between rare sugars and bulk caloric sweeteners.
Continuous-flow enzymatic reactors are hybridizing batch epimerization economics with pharmaceutical-grade process control. Beverage manufacturers in the United States adopt these systems at pilot scale to reduce solvent use and chromatography load. The technology is hybridizing capital efficiency expectations, pressuring incumbent producers to retrofit semi-batch infrastructure or surrender cost leadership.
EFSA's ongoing novel food assessment for allulose is reshaping European market entry sequencing. Manufacturers delay EU27 capacity commitments pending positive safety opinions, redirecting investment toward Japan's established FOSHU pathway and South Korea's MFDS fast-track. Confectionery exporters targeting dual US-EU labeling now maintain parallel formulation specifications, increasing SKU complexity.
Clean-label procurement mandates from North American retail chains are compressing acceptable sweetener ingredient lists to single-word declarations. Private-label beverage brands at Kroger and Target now specify allulose ahead of stevia blends to avoid "natural flavor" qualifiers. This specification shift concentrates volume with producers achieving GRAS self-affirmation without FDA notification delays.
Allulose Market Segmentation
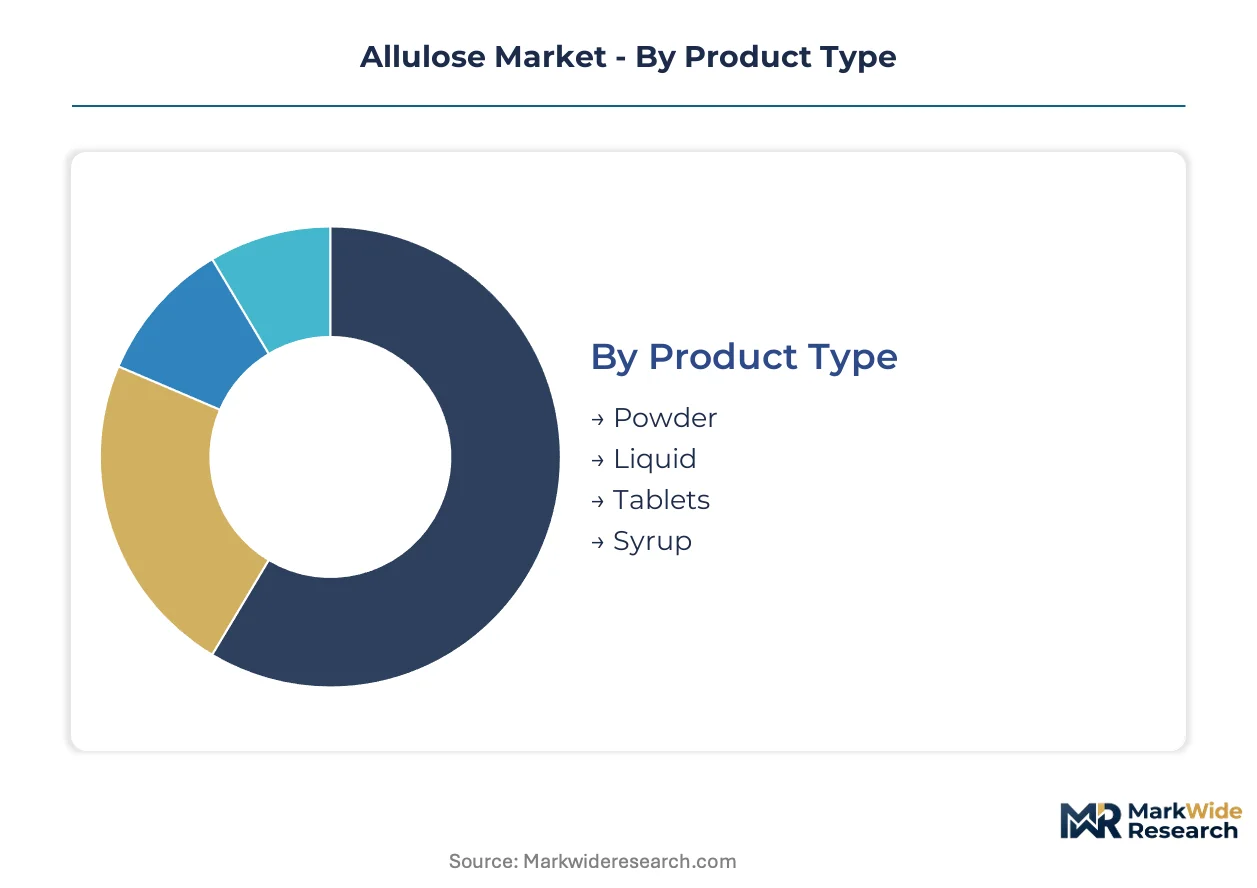
Formulation requirements vary sharply across allulose grades, driving divergent technical specifications and procurement behaviors. Segmentation reveals how crystalline stability, dissolution kinetics, and regulatory compliance reshape supplier selection criteria.
Product Type:
After-sales service intensity concentrates in liquid grades where tanker-scale logistics and shelf-life monitoring demand dedicated technical account management.
- Powder:Crystalline formulations exceeding 99.5% purity deliver shelf-stable sweetness with minimal hygroscopicity. Demand clusters in dry-mix manufacturers across the United States seeking GRAS-compliant sugar replacement for keto baking blends. FDA nutrition labeling exemption amplifies procurement velocity.
- Liquid:Aqueous solutions with rapid dissolution profiles target beverage formulators requiring seamless integration into carbonated and sports drink lines. Chromatographic separation bottlenecks constrain supply, forcing buyers into long-term offtake agreements with enzymatic platform operators.
- Tablets:Compressed formats serve portable sweetening applications with precise dosing convenience.
- Syrup:Viscous preparations bridge functionality gaps in confectionery glazing and sauce applications.
By volume, Powder leads. By growth pace, Liquid is ahead.
Application:
Cost tier stratification separates premium confectionery reformulations from commodity beverage sweetening.
- Beverages:Carbonated soft drinks and ready-to-drink protein formulations absorb tanker-scale liquid allulose deliveries. Clean-label procurement mandates from Kroger and Target private-label programs accelerate specification shifts away from stevia blends.
- Confectionery:Chocolate and gummy producers leverage Maillard reactivity identical to sucrose for surface browning without flavor profile alteration. Reformulation teams recalibrate water activity and humectancy when displacing caloric sweeteners.
- Bakery Products:Bread and pastry manufacturers exploit bulk functionality in yeast-raised applications.
- Dairy Products:Yogurt and ice cream formulators utilize freezing point depression characteristics.
By revenue concentration, Beverages dominates. By reformulation intensity, Confectionery is expanding most quickly.
End User:
Customer type determines specification rigor, from pharmaceutical-grade documentation for nutraceuticals to cost-optimized procurement for foodservice.
- Food Manufacturers:CPG giants integrate allulose across multi-SKU portfolios requiring consistent supply security and backward-integrated corn feedstock traceability. Tate & Lyle anchors Western supply through North American starch operations.
- Nutraceutical Companies:Sports nutrition and functional food developers specify rapid-dissolution liquid grades for protein beverage applications. METI's FOSHU framework in Japan creates regulatory arbitrage for rare sugar positioning.
- Dietary Supplement Providers:Capsule and tablet producers demand excipient-compatible crystalline grades.
- Restaurants:Foodservice operators pursue bulk syrup formats for menu reformulation flexibility.
By procurement scale, Food Manufacturers leads. By margin capture, Nutraceutical Companies shows steepest expansion trajectory.
Distribution Channel:
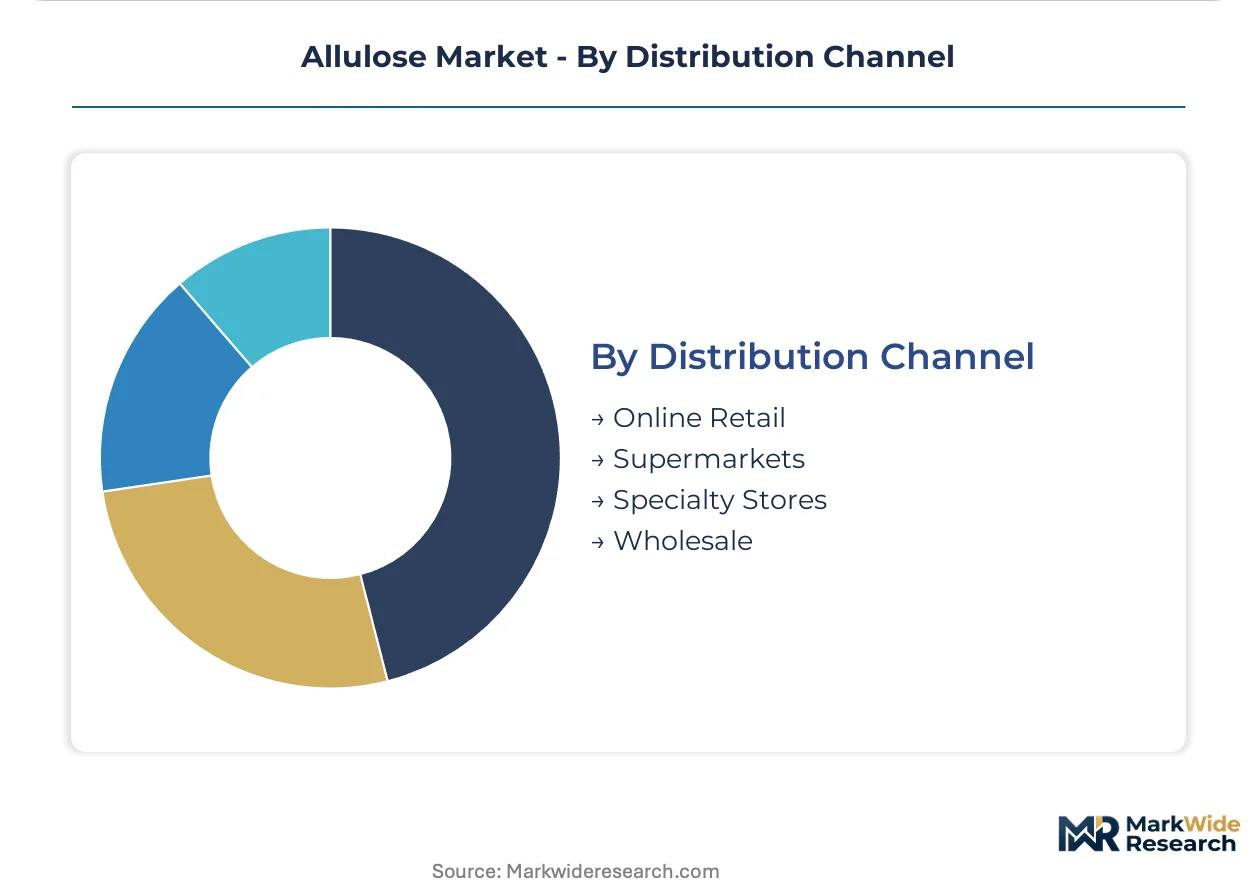
Supply concentration in enzymatic platform holders shapes channel access, with direct relationships displacing traditional wholesale for volume buyers.
- Wholesale:Tanker-scale liquid allulose moves through distributor networks serving beverage manufacturers requiring just-in-time delivery coordination. Three biocatalytic platform holders control liquid-grade output, creating single-source vulnerability.
- Online Retail:E-commerce channels enable specialty crystalline grades to bypass conventional foodservice distribution. Keto and diabetic consumer segments drive premium pricing for direct-to-consumer powder formats.
- Supermarkets:Mass retail placement supports private-label sweetener blends.
- Specialty Stores:Health food and natural product retailers curate premium-positioned rare sugar offerings.
By throughput volume, Wholesale leads. By pricing power, Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach handles specialized liquid sweetener tanker traffic that underwrites California's position as the primary US entry point for Asian allulose shipments. This infrastructure anchors North American distribution networks for enzymatically converted rare sugars.
United States
GRAS self-affirmation pathways and FDA nutrition labeling exemptions accelerate formulation trials across beverage manufacturers. The 2019 FDA decision excluding allulose from added sugars declarations removed cost penalties for clean-label positioning. Chicago and Minneapolis house reformulation labs where CPG giants recalibrate water activity in chocolate and baked goods applications.
China
Expanding enzymatic conversion capacity for rare sugars is pressuring legacy corn-based supply chains. MIIT's biotechnology industrial policy prioritizes biocatalytic platforms for food-grade carbohydrate production. Zhejiang and Jiangsu provinces host fermentation clusters where D-psicose 3-epimerase scale-up operations concentrate.
Japan
METI's FOSHU framework permits rare sugar functional claims, creating regulatory arbitrage for early entrants versus EU27 competitors. The Ministry of Health, Labour and Welfare maintains streamlined novel food assessments for established enzymatic processes. Osaka and Nagoya anchor confectionery reformulation demand where Maillard-reactive allulose displaces sucrose in premium chocolate production.
South Korea
MFDS fast-track pathways for enzymatically produced rare sugars accelerate market access relative to EFSA timelines. The Ministry of Food and Drug Safety recognizes biocatalytic allulose as a prior-sanctioned substance under existing sweetener regulations. Seoul-Incheon corridor houses sports nutrition formulators specifying rapid-dissolution liquid grades for protein beverage applications.
Germany
EFSA's pending novel food assessment blocks immediate market access, forcing German confectionery exporters toward dual US-Asia formulation specifications. The Federal Office of Consumer Protection and Food Safety coordinates with EMA on enzymatic process safety evaluations. Hamburg and Frankfurt maintain R&D facilities monitoring regulatory divergence for future EU27 capacity allocation decisions.
Allulose Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in enzymatic catalyst supply and chromatographic resin fabrication. The vendor base organizes around three biocatalytic platform holders controlling liquid-grade output, with crystalline powder specialists occupying adjacent margin pools. Two strategic archetypes dominate: backward-integrated corn processors securing feedstock traceability, and enzymatic technology licensors monetizing D-psicose 3-epimerase patents. Competitive moves concentrate on capacity expansion in China and strategic partnerships for tanker-scale logistics.
Among Asia-Pacific biocatalytic specialists, CJ CheilJedang and Matsutani Chemical Industry exemplify divergent positioning strategies. Tate & Lyle anchors Western supply security through North American starch operations. These three entities represent distinct archetypes: Korean enzymatic platform licensing, Japanese crystalline specialty expertise, and Anglo-American integrated feedstock processing. Their collective footprint determines tanker-scale availability for beverage manufacturers and powder-grade access for dry-mix formulators.
| Leading Market Players |
|---|
| Tate & Lyle |
| CJ CheilJedang |
| Matsutani Chemical Industry |
| Ingredion |
| Samyang Corporation |
| Bonumose |
| Anderson Advanced Ingredients |
| Apura Ingredients |
| Heartland Food Products Group |
| Others |
Supply Flow & Price Mechanics
Zhejiang and Jiangsu fermentation clusters anchor global enzymatic capacity, translating biocatalytic scale into downstream pricing leverage for liquid-grade allulose. Their D-psicose 3-epimerase output concentration enables tanker-scale producers to command premium terms from beverage formulators lacking alternative supply sources.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade purity levels separates chromatographic certification investments from commodity sweetener positioning. Price differentiation hinges on enzymatic conversion efficiency and FDA GRAS documentation completeness, with certification-lacking entrants facing margin compression from established platform licensors. Pricing pressure stems from CJ CheilJedang's capacity expansion in rare sugar biocatalysis, forcing legacy corn-based processors to absorb feedstock volatility without cost leadership. Powder-grade buyers at keto-focused e-commerce channels show lowest price sensitivity; carbonated beverage procurement teams at Kroger and Target private-label programs drive hardest volume negotiations.
Supply Chain Analysis
Contract manufacturing concentrates among Tate & Lyle's North American starch operations, CJ CheilJedang's Korean enzymatic platforms, and Matsutani Chemical Industry's Japanese crystallization facilities. Geographic supply concentration centers on China, South Korea, and the United States, with Zhejiang fermentation clusters and Chicago-area reformulation labs forming interdependent nodes. Raw material dependencies draw from corn syrup fructose feedstock, D-psicose 3-epimerase biocatalyst supply, and food-grade chromatography resin fabrication. Single-source vulnerability pervades liquid-grade output where three platform holders control tanker-scale availability. Distribution runs through direct technical account relationships for beverage manufacturers, bypassing traditional wholesale for volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against next-generation rare sugars and precision fermentation-derived sweeteners that threaten allulose's clean-label positioning. The imperative is securing biocatalytic cost leadership before alternative platforms achieve parity.
For Market Incumbents: Pre-empt emerging precision fermentation threats by deepening captive enzymatic capacity in Zhejiang or securing exclusive D-psicose 3-epimerase variant licensing. Lock in long-term fructose feedstock contracts to neutralize corn price volatility that erodes margin against integrated starch processors. Prioritize FDA GRAS self-affirmation completion to accelerate specification wins at Kroger and Target procurement desks.
For New Entrants and Emerging Players: Pursue regulatory arbitrage through Japan's METI FOSHU pathway or South Korea's MFDS fast-track, bypassing EFSA novel food delays that stall EU27 competitors. Target sports nutrition white space where rapid-dissolution liquid allulose displaces erythritol-stevia blends in ready-to-drink protein beverages. Lead with direct-to-consumer crystalline powder positioning via Amazon and specialty health platforms to capture keto segment premium before incumbent brand extension.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biocatalytic platform licensors with patent-protected epimerase variants over commodity corn processors lacking enzymatic differentiation. Long-term viability hinges on continuous-flow reactor adoption compressing unit costs below sucrose parity. Acquisition target archetype: enzymatic technology specialists with thermal-stable D-psicose 3-epimerase IP and existing GRAS documentation. Signal to watch: EFSA novel food opinion publication triggering EU27 capacity commitment waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Enzymatic Reactor Deployment | Reduces solvent use and chromatography load for pharmaceutical-grade process control adoption. |
| Backward Integration into Corn Starch Processing | Secures fructose feedstock traceability against syrup price volatility compressing North American margins. |
| FOSHU Regulatory Pathway Entry | Unlocks functional food claims in Japan ahead of slower EU27 novel food approval timelines. |
| Direct-to-Consumer Powder Channel Launch | Bypasses foodservice distribution to capture premium pricing from diabetic and keto consumer segments. |
| Long-Term Liquid Grade Offtake Agreements | Resolves single-source vulnerability for beverage formulators requiring tanker-scale delivery security. |
Methodological Framework
Desk research of enzymatic process patents, FDA GRAS notification filings, and EFSA novel food assessment precedents preceded structured interviews with beverage formulation chemists, confectionery R&D directors, and sweetener procurement managers at North American retail chains. Primary fieldwork captured tanker-scale logistics requirements, chromatographic separation commissioning timelines, and biocatalytic engineering talent constraints. Secondary validation drew from customs trade data, corn futures pricing archives, and MIIT biotechnology industrial policy documents. Bottom-up capacity modeling triangulated against top-down demand projections from clean-label procurement mandate tracking.
Assumption sets held enzymatic conversion efficiency improvements and regulatory approval timelines as variable inputs while fixing corn feedstock cost baselines and GRAS documentation requirements as structural constraints across the analysis window. Segmentation modeling incorporated product type crystallinity, application Maillard reactivity requirements, end-user specification rigor, and distribution channel access tiers. CAGRs derived from installed capacity expansion curves weighted by regional regulatory velocity differentials. Forecast inputs included D-psicose 3-epimerase platform licensing rates and chromatography resin certification bottlenecks.
Macroeconomic conditions sit as an overlay; deviation in corn commodity prices, freight rate indices, or biotechnology sector capital availability would shift the trajectory. Forecasts reflect documented assumptions about EFSA timeline progression and Chinese fermentation cluster buildout schedules. Cross-checking against FOSHU claim approval databases and MFDS prior-sanctioned substance registers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Australia Allulose Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
China Food Sweetener Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
United States Food Sweetener Market
Sweeteners
China Allulose Market
Sweeteners
Sweet Modulator Market
Sweeteners
Global Brown Sugar Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Saccharin Market
Sweeteners
Granulated Sugar Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
Natural Sweetener Blends Market
Sweeteners
Natural Sweeteners Market