
 Food Sweetener Market | 2026-2036
Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Food Sweetener Market Intelligence
The EU Green Deal's Farm to Fork strategy is restructuring procurement priorities across European food manufacturing. Cargill Incorporated leverages its vertically integrated stevia supply chain to secure cost positions in natural extract production. Tate & Lyle PLC specializes in reformulation partnerships that replace bulk sugar with soluble fibers and allulose blends. Südzucker AG anchors beet sugar supply across Central Europe while navigating gradual volume erosion in conventional sucrose.
Food sweeteners comprise caloric and non-caloric substances added to confer sweetness, spanning sucrose derived from beet or cane processing, high-intensity compounds such as aspartame and sucralose synthesized through chemical modification, and plant-derived glycosides extracted via aqueous steeping and crystallization. Their primary commercial purpose centers on flavor modulation, shelf-life extension through humectancy, and bulk functional properties in baked and frozen matrices. Natural sweeteners command accelerating volume growth as beverage and dairy applications shift label claims toward plant-derived and non-GMO positioning, while artificial sweeteners retain cost advantages in mass-market carbonated drinks where price sensitivity constrains formulation budgets. Sugar alcohols occupy a narrower but expanding niche in confectionery and nutraceuticals, delivering reduced glycemic impact alongside cooling sensory profiles that differentiate premium positioning.
The FDA governs high-intensity sweetener safety through food additive petitions and GRAS notifications, while EFSA enforces purity specifications and acceptable daily intake thresholds across European member states. BIS in India mandates labeling disclosures for artificial sweetener content that shape consumer perception and manufacturer formulation choices. Stakeholders must monitor evolving regulatory classifications for novel sweeteners and caloric reduction claims, as divergence between FDA GRAS pathways and EFSA novel food assessments creates compliance complexity for multinational product portfolios.
Market Dynamics
Beverage manufacturers are accelerating reformulation toward reduced-calorie portfolios under pressure from FDA Nutrition Facts label mandates and WHO sugar reduction guidelines, restructuring procurement priorities across North American and European food manufacturing.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:The European Commission's sustainability framework is mandating procurement shifts toward plant-derived ingredients, forcing manufacturers to substitute conventional sucrose with stevia and monk fruit glycosides in clean-label product lines.
- Clean-Label Positioning in Dairy:Yogurt and flavored milk producers are replacing artificial sweeteners with natural extracts to capture premium shelf space, driving volume expansion in aqueous extraction and crystallization capacity for plant-derived glycosides.
- WHO Sugar Reduction Guidelines:The World Health Organization's recommended intake thresholds are pressuring national health ministries to implement beverage taxes and front-of-pack labeling, accelerating high-intensity sweetener substitution in carbonated and still drinks.
Market Restraints
- Stevia Leaf Supply Concentration:Cultivation clusters in China's Guangxi and Yunnan provinces create geographic concentration risk, with weather volatility and labor cost inflation transmitting directly to natural sweetener input pricing.
- EFSA Novel Food Assessment Complexity:The European Food Safety Authority's prolonged purity verification and acceptable daily intake threshold-setting processes delay market entry for emerging glycoside variants, compressing first-mover advantages.
- Allulose Production Cost Structure:Enzymatic conversion of fructose to this rare sugar requires specialized biocatalysis infrastructure, constraining supply scalability relative to conventional high-intensity alternatives and limiting mass-market penetration.
Strategic Opportunities
- India BIS Labeling Disclosure Requirements:India's Bureau of Indian Standards mandates prominent artificial sweetener content declarations, creating competitive white space for natural extract positioning in a market with rising diabetes prevalence and health-conscious urban consumers.
- Confectionery Sugar Alcohol Expansion:Erythritol and xylitol formulations are penetrating premium chocolate and hard candy segments, leveraging cooling sensory profiles and reduced glycemic impact to differentiate functional positioning.
- Soluble Fiber-Sweetener Convergence:Reformulation partnerships combining allulose with resistant dextrin and inulin are enabling dual claims of sugar reduction and prebiotic benefit, opening functional food applications in sports nutrition and senior nutrition.
Industry Challenges
- GRAS Notification Timeline Compression:FDA food additive petition pathways for novel high-intensity compounds require extensive toxicological dossiers, with review cycles extending 18-24 months and consuming significant regulatory affairs bandwidth.
- Extraction Technology Talent Scarcity:Aqueous steeping and crystallization process engineering expertise for stevia and monk fruit concentrates in short supply, constraining capacity expansion at natural extract specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Sweetener Market |
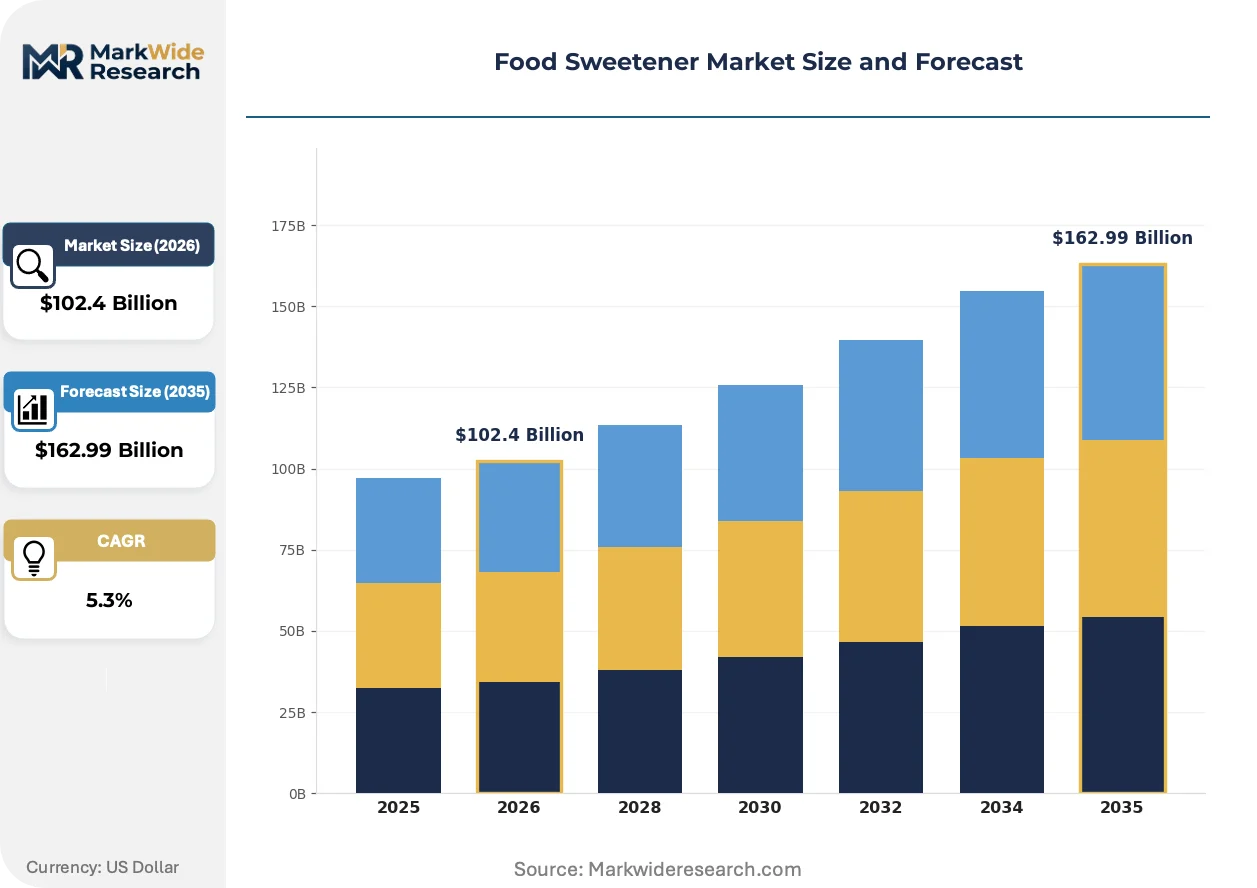
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $162.99 Billion |
| CAGR (2026 – 2036) | 5.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sugar, Artificial Sweeteners, Natural Sweeteners, Sugar Alcohols Application: Beverages, Bakery, Dairy, Confectionery Form: Liquid, Powder, Granulated, Crystal End User: Retail, Food Service, Food Manufacturers, Nutraceuticals |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Ajinomoto Co. Inc., DuPont de Nemours Inc., Südzucker AG, Tereos, Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Sweetener Market Strategic Shifts & Innovations
Reformulation science is converging with biotechnology and regulatory compliance systems to reshape how sweetness is engineered, delivered, and labeled across packaged food and beverage categories.
Biocatalytic production platforms for rare sugars are integrating into commercial manufacturing infrastructure. Allulose and tagatose output from enzymatic fructose conversion is scaling through partnerships between ingredient suppliers and synthetic biology firms. Beverage and bakery applications are absorbing this supply expansion as formulators seek bulk functional properties without caloric load. The technology is integrating crystallization and drying processes that previously required separate sucrose handling equipment, compressing capital requirements for plant retrofit.
Front-of-pack labeling mandates are tightening across multiple jurisdictions. The FDA's updated Nutrition Facts panel emphasizes added sugars disclosure, while France's Nutri-Score algorithm penalizes excessive sweetness intensity regardless of caloric content. Manufacturers reformulating for A or B ratings are prioritizing glycoside blends over artificial alternatives. European dairy and dessert segments are responding fastest, with clean-label claims now standard in private-label development briefs.
Direct procurement from extract processors is displacing traditional distributor relationships in North American natural and organic channels. Large beverage brands are establishing captive supply agreements with stevia cultivators and extraction facilities, bypassing ingredient trading houses. This consolidation of sourcing relationships concentrates volume with vertically integrated suppliers capable of certifying non-GMO and organic chain of custody. The shift is most visible in United States sports drink and enhanced water categories, where label transparency commands price premiums.
Food Sweetener Market Segmentation
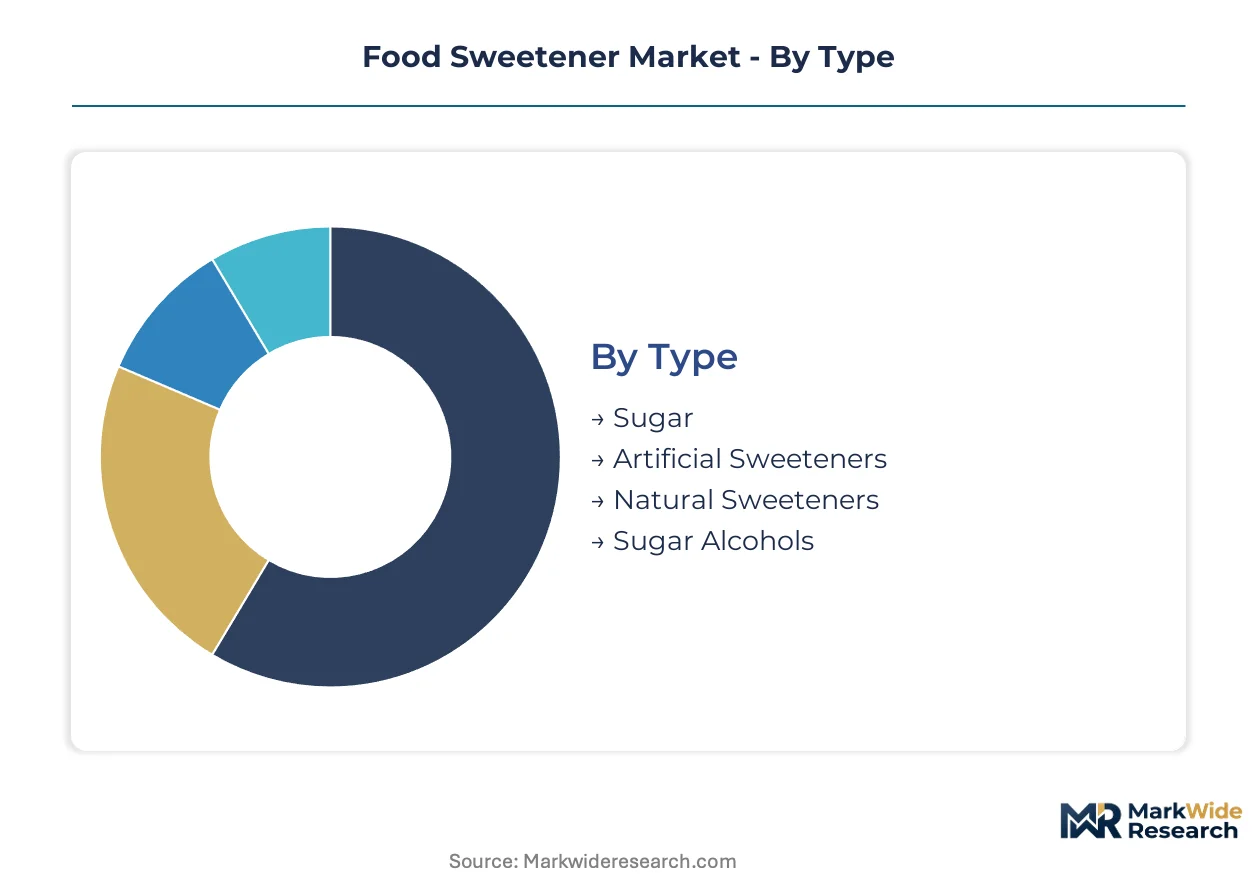
Sweetener procurement strategies diverge sharply across formulation requirements, with beverage manufacturers prioritizing high-intensity solubility while bakery operations demand bulk functional properties. The segmentation framework reveals how technical specifications and end-use constraints reshape supplier selection and ingredient sourcing priorities across the value chain.
Type:
Technical specifications around caloric density, glycemic impact, and label positioning determine procurement hierarchies across food manufacturing segments.
- Sugar:Conventional sucrose from beet and cane processing delivers bulk sweetness and humectancy for baked and frozen matrices. European dairy and dessert manufacturers are gradually reducing dependence as EFSA sugar reduction guidelines tighten formulation constraints.
- Artificial Sweeteners:Chemically synthesized high-intensity compounds including aspartame and sucralose provide cost-efficient sweetness at ppm concentrations. Mass-market carbonated beverage producers in the United States retain these inputs where price sensitivity dominates procurement decisions.
- Natural Sweeteners:Plant-derived stevia and monk fruit glycosides extracted via aqueous steeping command accelerating volume growth as clean-label positioning penetrates premium retail channels.
- Sugar Alcohols:Erythritol and xylitol deliver reduced glycemic impact alongside cooling sensory profiles that differentiate functional confectionery positioning in nutraceutical applications.
Sugar leads on scale; natural sweeteners lead on momentum.
Application:
Formulation complexity and thermal stability requirements create distinct procurement patterns across food processing categories.
- Beverages:Liquid solubility and flavor masking dominate technical specifications, with high-intensity sweeteners enabling calorie reduction without volume loss in carbonated and still drinks.
- Bakery:Maillard reaction participation and moisture retention properties constrain substitution options, with bulk sweeteners retaining functional necessity despite sugar reduction pressures.
- Dairy:Fermentation compatibility and clean-label positioning are restructuring procurement toward natural glycosides in yogurt and flavored milk segments.
- Confectionery:Crystallization control and cooling effects from sugar alcohols are penetrating premium chocolate and hard candy formulations.
Beverage applications anchor volume demand; dairy applications are expanding most quickly.
Form:
Processing equipment compatibility and handling efficiency shape manufacturing preferences across production scales.
- Liquid:Pre-dissolved concentrates streamline batch consistency in high-volume beverage operations and reduce dust exposure during handling.
- Powder:Fine particle distribution enables rapid dissolution and precise dosing in dry blend applications across bakery and confectionery mixing lines.
- Granulated:Free-flowing properties support automated dispensing systems in large-scale food manufacturing facilities with pneumatic transfer infrastructure.
- Crystal:Defined particle geometry provides controlled dissolution kinetics and visual appeal in premium tabletop and beverage applications.
Powder form dominates manufacturing throughput; liquid form is gaining share fastest in beverage reformulation.
End User:
Volume scale and specification stringency create tiered procurement relationships across the demand spectrum.
- Food Manufacturers:Large-scale reformulation partnerships with ingredient suppliers enable customized glycoside blends and soluble fiber co-formulations for sugar reduction claims.
- Food Service:Dispensing convenience and cost control dominate purchasing decisions, with portion-packaged tabletop sweeteners and bulk liquid concentrates serving distinct operational needs.
- Retail:Consumer-facing packaging emphasizes organic certification and non-GMO verification, with natural extract tabletop products commanding shelf space premiums.
- Nutraceuticals:Functional positioning around glycemic management and dental health drives sugar alcohol incorporation in supplement and medical food formulations.
Food manufacturers lead on procurement volume; nutraceuticals demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers specializing in aqueous extraction and crystallization concentrate in China's Guangxi and Yunnan provinces, where stevia cultivation clusters anchor natural glycoside supply chains for beverage reformulation worldwide.
United States
Beverage manufacturers in Atlanta and Purchase are accelerating zero-sugar portfolio expansion. FDA Nutrition Facts label mandates pressure reformulation timelines. Chicago and Minneapolis house ingredient R&D facilities where allulose-soluble fiber blends are scaling for sports nutrition applications.
China
Stevia leaf processing capacity concentrates in Guilin and Nanning extraction facilities. SAMR food additive standards govern glycoside purity thresholds. Guangdong province beverage bottlers are integrating direct procurement relationships with Yunnan cultivators, bypassing traditional trading networks.
Germany
Südzucker AG anchors beet sugar processing across Saxony-Anhalt and Bavaria. EU Green Deal Farm to Fork procurement mandates accelerate plant-derived sweetener substitution. Mannheim and Hamburg host reformulation technical centers where allulose blends are penetrating dairy applications.
India
Urban diabetes prevalence drives natural extract demand in Mumbai and Delhi beverage markets. BIS labeling disclosure requirements for artificial sweeteners create competitive positioning space for stevia and monk fruit. Gujarat and Maharashtra process engineering clusters are expanding aqueous extraction capacity for domestic glycoside supply.
Brazil
Cane sugar processors in São Paulo and Minas Gerais navigate gradual volume erosion as beverage reformulation accelerates. ANVISA food additive regulations shape import pathways for high-intensity alternatives. Campinas technical centers are piloting enzymatic rare sugar conversion for regional bakery and confectionery applications.
Food Sweetener Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the sweetener value chain, with integrated agricultural processors maintaining cost positions against specialty ingredient formulators. The market structures around three tiers: commodity sucrose refiners with captive beet and cane supply, natural extract specialists with backward integration into cultivation, and biotechnology-enabled rare sugar producers with enzymatic conversion platforms. Strategic moves concentrate on captive supply agreements with beverage brands and reformulation partnership models that embed technical service into ingredient supply contracts.
Within the integrated agricultural processor tier, Cargill Incorporated and Südzucker AG exemplify archetypes spanning American and European supply bases. Tate & Lyle PLC occupies a position among specialty ingredient formulators emphasizing reformulation science partnerships. These three anchors demonstrate how geographic cultivation control, enzymatic biotechnology capabilities, and technical service integration respectively define competitive positioning in a market restructuring toward clean-label and reduced-calorie portfolios.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Ajinomoto Co. Inc. |
| DuPont de Nemours Inc. |
| Südzucker AG |
| Tereos |
| Roquette Frères |
| Others |
Cost & Logistics Intelligence
Process engineers with aqueous extraction expertise in China's Guangxi and Yunnan provinces command wage premiums that compress margins for natural glycoside processors, widening spreads between premium certified-organic stevia and standard-grade artificial alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic stevia extracts from conventional natural glycosides from mass-market artificial sweeteners. Price differentiation hinges on organic certification status and volume procurement scale. Cost compression in standard-grade natural extracts is intensifying because Chinese labor inflation transmits directly to Yunnan cultivation clusters. Mass-market carbonated beverage producers exhibit highest price sensitivity, while premium dairy and sports nutrition brands absorb organic premiums for clean-label positioning.
Supply Chain Analysis
Non-GMO and organic certification gating restricts supplier pools to vertically integrated processors capable of documenting chain of custody from Guangxi and Yunnan cultivators through extraction facilities. Raw material dependencies center on stevia leaf supply, fructose feedstock for enzymatic allulose conversion, and beet sugar from Central European processing. Single-source vulnerability concentrates in China's natural extract clusters where weather volatility disrupts leaf supply. Distribution runs through direct procurement agreements between beverage brands and extraction specialists, displacing traditional ingredient trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food sweetener market functions as a regulatory compounder where FDA Nutrition Facts label mandates and WHO sugar reduction guidelines continuously restructure procurement priorities across beverage and dairy manufacturing.
For Market Incumbents: Deepen backward integration into Yunnan and Guangxi cultivation clusters to secure non-GMO stevia supply against Chinese labor cost inflation. Expand aqueous extraction capacity in India to exploit BIS labeling disclosure requirements that disadvantage artificial sweetener competitors. Defend margin position by embedding reformulation technical services into long-term supply contracts with North American beverage brands. For New Entrants and Emerging Players: India's BIS labeling disclosure requirements open a window for natural extract positioning among Mumbai and Delhi beverage manufacturers serving diabetes-prevalent urban consumers. Target confectionery sugar alcohol applications where erythritol and xylitol cooling profiles differentiate premium chocolate and hard candy segments. Establish enzymatic rare sugar pilot facilities in Brazil to leverage ANVISA regulatory pathways for regional bakery and confectionery market entry. For Investors and Strategic Acquirers: Beverage conglomerates are the most active acquirer in this space, seeking captive glycoside supply to secure clean-label reformulation pipelines. Natural extract specialists with demonstrated organic certification and direct cultivator relationships represent priority acquisition targets over commodity sucrose refiners. Monitor EFSA novel food assessment timelines as inflection indicators for emerging glycoside variant commercialization windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Cargill's Yunnan stevia supply chain control secures cost positions against Chinese labor inflation. |
| Reformulation Partnership Models | Tate & Lyle's technical service embedding enables sugar reduction claims in European dairy applications. |
| Enzymatic Rare Sugar Scale-Up | Allulose biocatalysis infrastructure partnerships compress capital requirements for beverage plant retrofit. |
| Direct Procurement Agreements | Atlanta beverage brands bypass trading houses to certify non-GMO chain of custody with extract processors. |
| Clean-Label Certification Investment | Organic and non-GMO verification unlocks premium shelf space in United States sports nutrition channels. |
Research Approach
Direct dialogue with extraction facility process engineers, beverage reformulation scientists, procurement directors at dairy manufacturers, and regulatory affairs specialists at FDA and EFSA grounded qualitative insights. Secondary validation drew from SAMR food additive standards filings, BIS labeling disclosure mandates, EU Green Deal Farm to Fork strategy documents, and SEC 10-K disclosures from publicly traded ingredient suppliers. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Segmented outputs spanning sweetener type, application category, physical form, and end-user tier generated discrete demand trajectories throughout the forecast period. CAGRs derived from elasticity modeling against WHO sugar reduction guideline implementation timelines and FDA Nutrition Facts label compliance deadlines. Industry-specific inputs included stevia leaf yield volatility indices and enzymatic conversion efficiency benchmarks for rare sugar production.
Revisions become necessary when EFSA novel food assessment timelines compress or expand, SAMR tightens glycoside purity thresholds, or Chinese labor cost inflation accelerates beyond historical patterns. Forecasts reflect documented assumptions about regulatory implementation schedules and cultivation yield stability. A model refresh is warranted upon material change in FDA GRAS notification processing speed or EU Green Deal procurement mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
India Cane Sugar Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
Sanding Sugar Market
Sweeteners
Stevia Market
Sweeteners
Polyphenol Sweetener Market
Sweeteners
Sugar Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
China Food Sweetener Market
Sweeteners
D Psicose Market
Sweeteners
Maltitol Market
Sweeteners
China Saccharin Market
Sweeteners
Xylitol Market
Sweeteners
Coconut Sugar Market
Sweeteners
Global Starch Sweetener Market