
 Sucrose Esters Market | 2026-2036
Sucrose Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Sucrose Esters Market Analysis
Premium pharmaceutical-grade sucrose esters is decoupling from commodity food-grade supply chains on purity specifications and batch documentation requirements. Evonik Industries leverages its alkoxylation backbone to sustain high-margin positions in medical-grade emulsifiers. Croda International anchors its portfolio with RSPO-certified feedstock sourcing, while Mitsubishi Chemical dominates Asian supply through captive sorbitol and fatty acid integration.
Sucrose esters are non-ionic surfactants synthesized by transesterification of sucrose with fatty acid methyl esters, typically yielding HLB values between 1 and 16 for applications spanning emulsification to conditioning. Their primary commercial purpose centers on replacing petrochemical surfactants in formulations where mildness and biodegradability carry regulatory or brand weight. Powder and liquid forms command divergent margin structures, with powder grades capturing premium positions in pharmaceutical lyophilization while liquid concentrates penetrate high-volume food processing. The food and beverage application segment retains volume leadership, though personal care formulation is expanding fastest on clean-label positioning and silicone-free claims.
FDA food additive regulations and EU REACH registration requirements shape product migration pathways, with EFSA novel food opinions creating additional gates for new ester variants in European markets. Japan's MHLW and METI enforce pharmaceutical excipient standards that exclude lower-purity grades from injectable applications. Stakeholders must monitor divergence between regional bio-based content mandates and the actual certified sustainable palm oil availability that underlies cost-competitive production.
Market Dynamics
Clean-label mandates across food and personal care sectors are forcing formulators to abandon petrochemical surfactants, redirecting procurement budgets toward bio-based emulsifiers with certified supply chains and documented batch purity.
Growth Catalysts
- EU REACH compliance deadlines:Registration requirements for existing chemical substances are accelerating substitution of synthetic surfactants in European cosmetic and pharmaceutical formulations.
- Water-based emulsion demand:Personal care manufacturers are prioritizing high-HLB sucrose esters for silicone-free moisturizers and sunscreens.
- Southeast Asia food processing expansion:Indonesia and Vietnam are building new processed-food capacity that specifies bio-based emulsifiers for export-market access.
Market Restraints
- Feedstock concentration:Certified sustainable palm oil availability constrains cost-competitive production for RSPO-certified grades.
- Pharmaceutical purity thresholds:Japan's MHLW excipient standards exclude lower-purity grades from injectable applications, fragmenting supply chains.
- Enzymatic process yield limits:Lipase-catalyzed transesterification remains below chemical route efficiency, capping volume scalability.
Strategic Opportunities
- Pharmaceutical lyophilization:Powder-grade sucrose esters for protein stabilization represent an underpenetrated segment with documentation premiums.
- US bio-preferred procurement:Federal purchasing mandates under USDA BioPreferred are opening institutional foodservice channels.
- Cell-culture media:Sucrose esters as shear-protective agents in bioreactors are displacing poloxamers in contract manufacturing.
Industry Challenges
- Analytical chemist scarcity:Batch documentation for pharmaceutical grades requires specialized HPLC and mass spec capabilities that outpace talent supply.
- Multi-site certification complexity:Simultaneous audits for RSPO, ISO 22000, and EXCiPACT across manufacturing networks extend qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sucrose Esters Market |
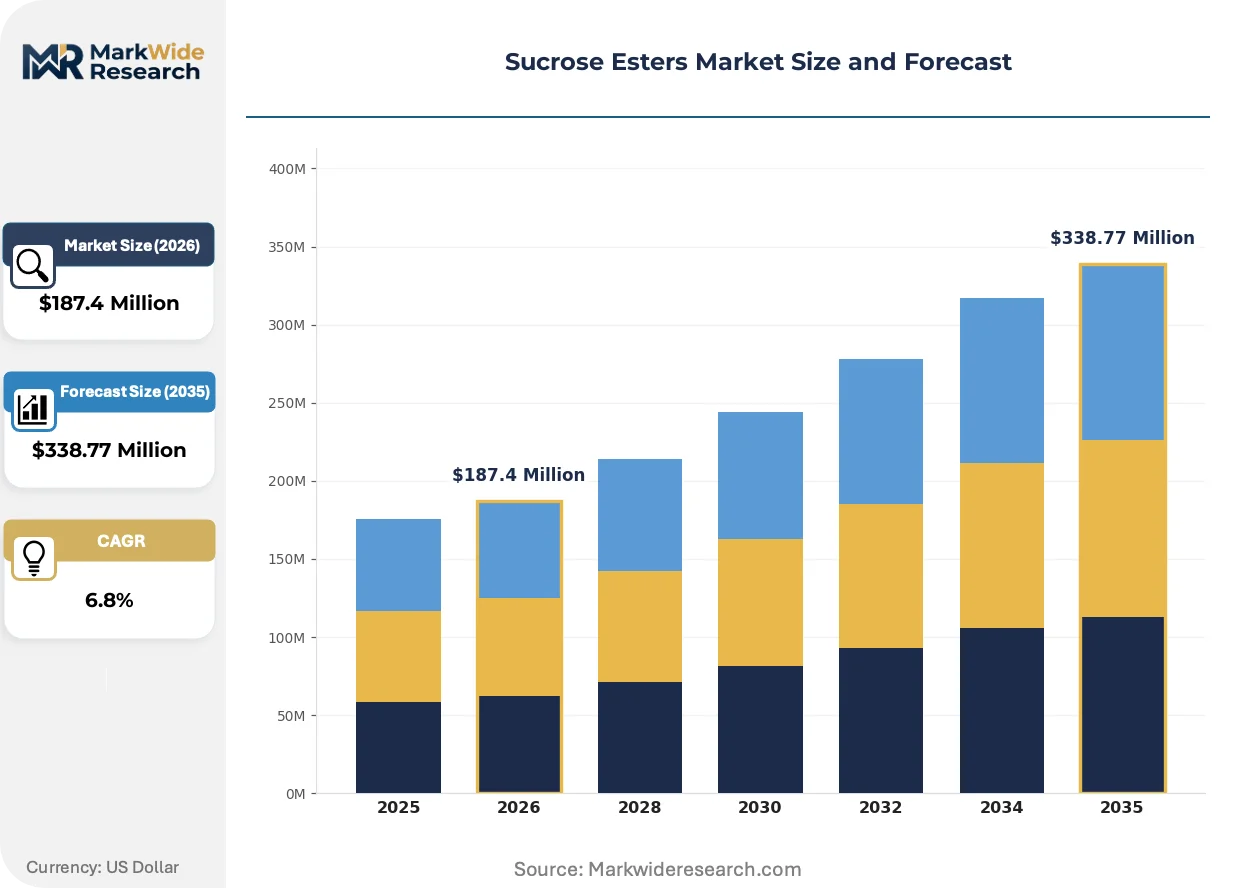
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granulated, Flakes Application: Food & Beverage, Personal Care, Pharmaceuticals, Industrial End User: Manufacturers, Retailers, Wholesalers, Distributors Formulation: Emulsifiers, Stabilizers, Thickening Agents, Flavoring Agents |
| Companies Covered | Evonik Industries, BASF, Croda International, P&G Chemicals, Sisterna, Mitsubishi Chemical, Dai-Ichi Kogyo Seiyaku, Stearinerie Dubois, Alfa Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sucrose Esters Market Emerging Trajectories
Enzymatic synthesis routes and advanced purification systems are reshaping competitive economics, while regulatory divergence between jurisdictions is fragmenting product specifications and forcing regional formulation strategies.
Enzymatic transesterification using immobilized lipases is expanding into commercial-scale production of high-purity sucrose esters for pharmaceutical applications. Contract manufacturers in Germany and Switzerland are adopting these biocatalytic systems to reduce solvent residues and thermal degradation. This technology is expanding into previously inaccessible medical-grade segments by enabling single-isomer specificity that chemical routes cannot match.
EFSA novel food opinions are creating additional regulatory gates for new sucrose ester variants in European markets. Food innovators must now submit comprehensive toxicology packages before launching modified HLB grades, extending development cycles. Bakery and confectionery segments are responding by reformulating with existing approved esters rather than pursuing novel variants.
Direct procurement from certified sustainable feedstock sources is compressing traditional distributor channels in North American and European markets. Large personal care formulators are establishing long-term offtake agreements with RSPO-certified producers, bypassing regional chemical distributors. This pattern is most visible in German and French cosmetic clusters where supply chain transparency carries brand weight.
Sucrose Esters Market Segmentation
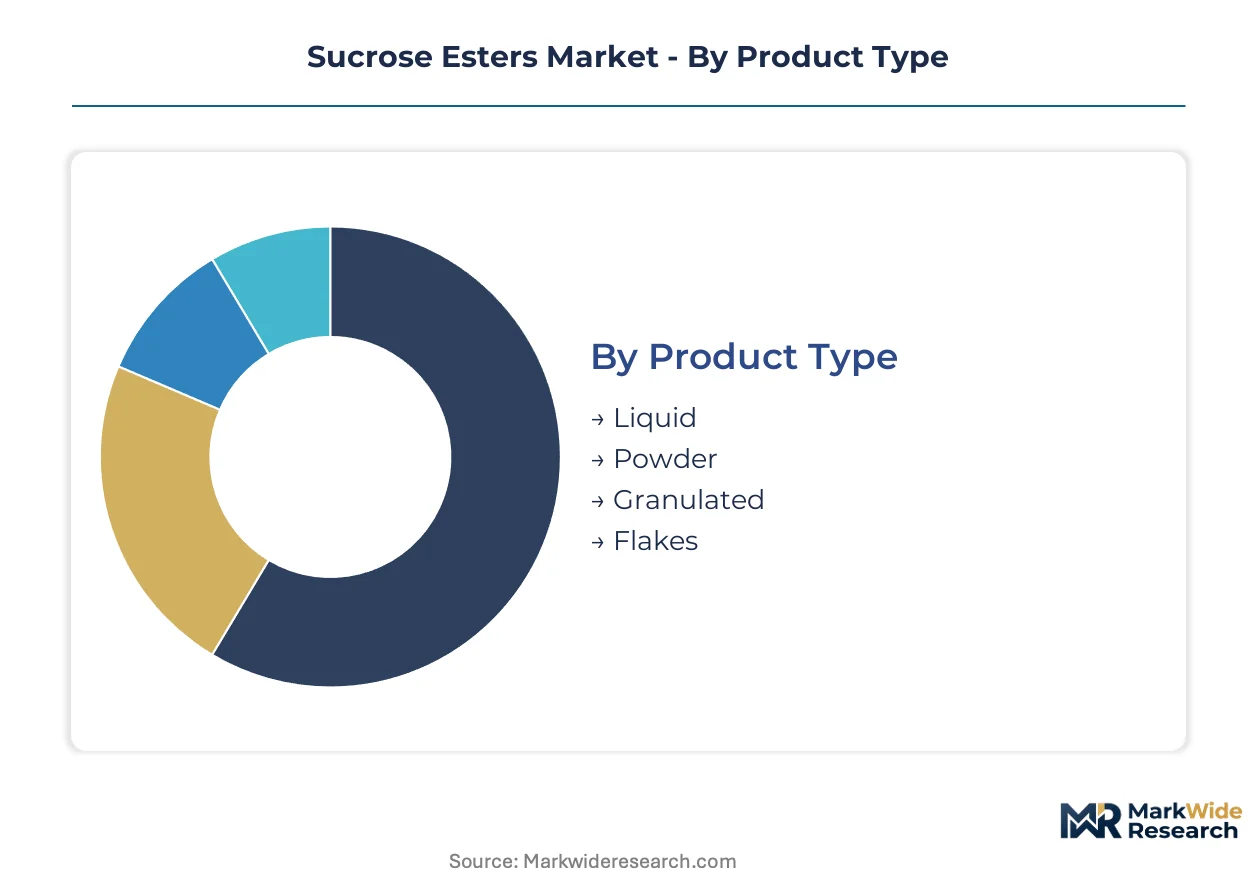
Sucrose esters fragment across four distinct classification axes that reshape procurement economics. Physical form determines logistics cost and storage stability. Application end-use governs purity thresholds and certification requirements.
Product Type:
Liquid concentrates dominate tonnage shipments while powder grades command documentation premiums in regulated channels.
- Liquid:Aqueous concentrates with 25-75% active content serve high-volume food processing where metered dosing and thermal stability matter. Indonesian and Vietnamese processed-food plants specify liquid grades for continuous emulsion lines. This segment anchors volume economics through tanker-scale procurement.
- Powder:Spray-dried or lyophilized grades with sub-5% moisture content target pharmaceutical lyophilization and protein stabilization. Japan's MHLW excipient standards restrict powder grades to documented batch purity, creating supply chain bifurcation. Documentation premiums separate pharmaceutical from food-grade powder streams.
- Granulated:Free-flowing agglomerates with controlled particle size distribution improve handling in bakery and confectionery dry mixes.
- Flakes:Compressed crystalline forms with defined melting profiles serve specialty chocolate and fat-based confectionery applications.
Today's leader: Liquid. Tomorrow's challenger: Powder.
Application:
Clean-label mandates are reallocating procurement budgets across end-use segments with divergent regulatory exposure.
- Food & Beverage:Emulsification in bakery, confectionery, dairy alternatives, and processed foods constitutes the foundational volume base. EFSA novel food opinions gate new ester variants, forcing reformulation with existing approved grades rather than innovation.
- Personal Care:Silicone-free moisturizers and sunscreens specify high-HLB sucrose esters for water-based emulsions. EU REACH compliance deadlines accelerate substitution of synthetic surfactants in German and French cosmetic clusters. This segment climbs the fastest on clean-label positioning.
- Pharmaceuticals:Injectable emulsions and protein stabilization require EXCiPACT certification and batch HPLC documentation.
- Industrial:Agrochemical dispersions and textile auxiliaries utilize lower-purity grades with relaxed specification tolerance.
Food & Beverage holds volume dominance. Personal Care drives margin expansion.
End User:
Channel structure is compressing as large formulators bypass distributors for direct RSPO-certified feedstock offtake.
- Manufacturers:Integrated food, cosmetic, and pharmaceutical producers with in-house formulation capabilities represent the primary demand concentration.
- Retailers:Private-label grocery and pharmacy chains sourcing finished emulsifier blends for contract manufacturing.
- Wholesalers:Regional chemical distributors serving mid-tier formulators without direct producer relationships.
- Distributors:Specialty ingredient distributors with technical service capabilities for small-batch pharmaceutical and cosmetic accounts.
Direct manufacturer relationships expand. Traditional distributor influence contracts.
Formulation:
Functional role determines HLB specification and competitive substitution dynamics.
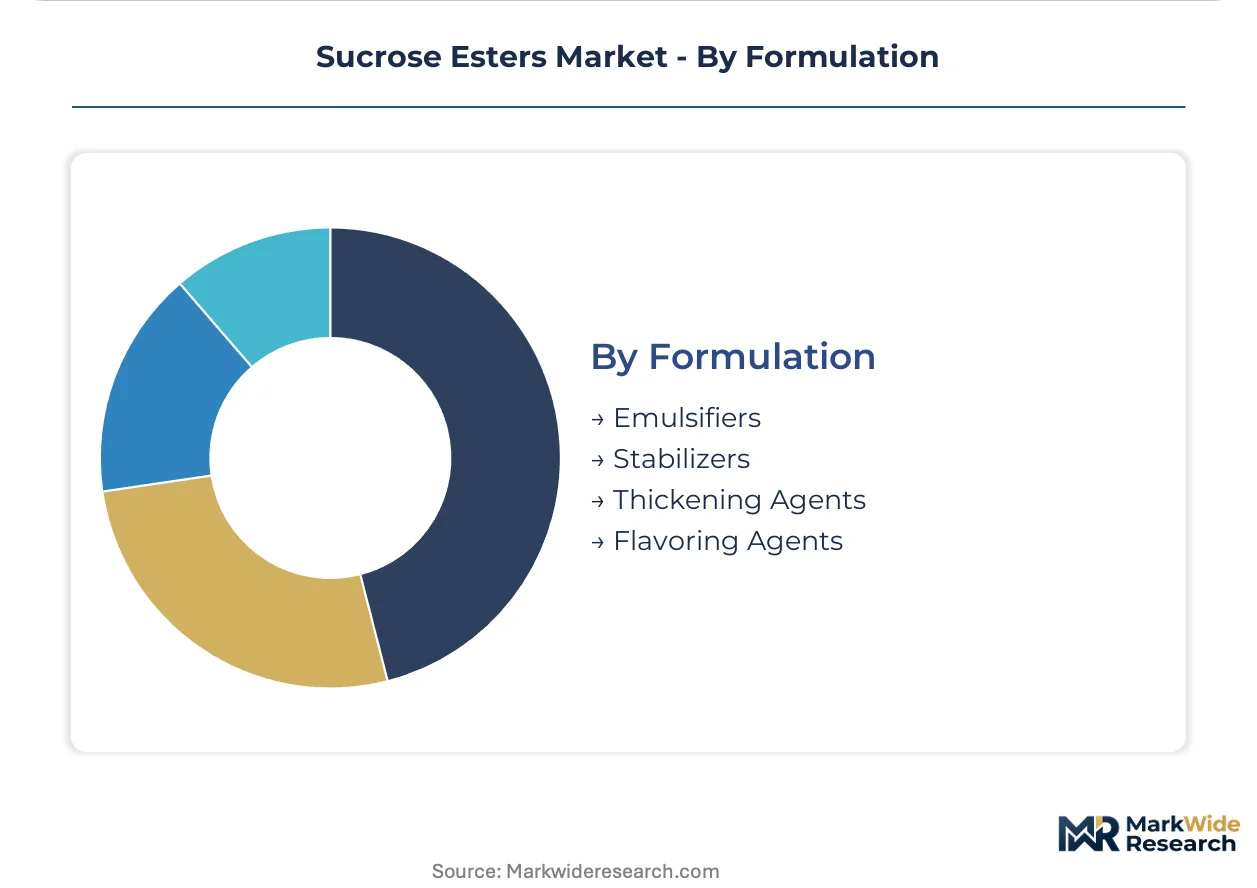
- Emulsifiers:Oil-in-water and water-in-oil stabilization across HLB 1-16 range, with high-HLB grades penetrating personal care fastest.
- Stabilizers:Freeze-thaw protection and viscosity maintenance in frozen desserts and aerated confections.
- Thickening Agents:Viscosity building in low-fat and reduced-calorie formulations where fat replacement is required.
- Flavoring Agents:Taste modulation and bitterness masking in pharmaceutical and nutraceutical applications.
Emulsification retains functional dominance. Stabilization gains share in frozen food innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists cluster in Germany's Rhine-Ruhr corridor and Japan's Kanto region, anchoring pharmaceutical-grade production networks. These talent concentrations shape regional supply capabilities and certification standards.
Germany
Personal care formulators in the Rhine-Ruhr corridor drive high-HLB sucrose ester procurement for silicone-free emulsions. ECHA REACH registration deadlines accelerate substitution of petrochemical surfactants in cosmetic formulations. Cologne's cosmetic ingredient cluster concentrates EXCiPACT-certified production for pharmaceutical export markets.
United States
USDA BioPreferred federal procurement mandates open institutional foodservice channels for bio-based emulsifiers. FDA food additive regulations govern bakery and confectionery applications with strict documentation requirements. New Jersey's pharmaceutical corridor demands batch HPLC documentation for injectable-grade sucrose esters.
Japan
MHLW pharmaceutical excipient standards exclude lower-purity grades from injectable applications, fragmenting supply chains. METI enforces industrial chemical reporting that shapes surfactant substitution patterns. Osaka's specialty chemical district concentrates medical-grade lyophilization applications with premium documentation requirements.
Indonesia
Processed-food capacity expansion specifies bio-based emulsifiers for export-market access to EU and US buyers. National food safety regulations align with CODEX standards for emulsifier usage levels. Java's industrial corridor builds continuous emulsion lines specifying liquid sucrose ester concentrates for cost efficiency.
Vietnam
Confectionery and dairy alternative processors adopt RSPO-certified emulsifiers for clean-label export positioning. Ministry of Health circulars govern food additive safety assessments with evolving purity standards. Ho Chi Minh City's food processing zone concentrates new plant construction specifying certified sustainable feedstock sourcing.
Sucrose Esters Market Vendor Landscape
Top-tier vendors anchor pharmaceutical and personal care segments, while regional specialists serve high-volume food processing markets. The vendor base stratifies across certification tiers rather than geographic boundaries. Three archetypes dominate: integrated chemical conglomerates with alkoxylation backbones, RSPO-certified specialty surfactant houses, and Asian producers with captive fatty acid integration. Competitive moves concentrate on direct offtake agreements with certified feedstock sources and multi-site qualification for pharmaceutical documentation standards.
Within the integrated chemical tier, Evonik Industries and BASF occupy positions defined by alkoxylation technology platforms and pharmaceutical-grade documentation capabilities. Croda International exemplifies the sustainability-certified archetype through RSPO feedstock sourcing commitments. Mitsubishi Chemical anchors the Asian supply structure through captive integration into sorbitol and fatty acid precursors. These three company profiles illustrate how competitive positioning fragments across certification standards, geographic supply chain control, and end-use purity requirements rather than converging on unified scale advantages.
| Leading Market Players |
|---|
| Evonik Industries |
| BASF |
| Croda International |
| P&G Chemicals |
| Sisterna |
| Mitsubishi Chemical |
| Dai-Ichi Kogyo Seiyaku |
| Stearinerie Dubois |
| Alfa Chemicals |
| Others |
Supply Flow & Price Mechanics
Large personal care formulators with direct RSPO-certified offtake agreements command volume-based contract pricing that compresses margins for distributor-dependent mid-tier competitors. This buyer concentration forces three-tier pricing stratification across pharmaceutical documentation grades, food-grade certifications, and industrial specifications.
Pricing Analysis
Pharmaceutical-grade sucrose esters bundle HPLC batch documentation and EXCiPACT certification into per-kilogram premiums, while food-grade liquid concentrates trade on unbundled spot pricing indexed to palm oil futures. Price differentiation hinges on purity thresholds and RSPO chain-of-custody certification, with documentation premiums widening as analytical chemist scarcity intensifies. Cost compression in food-grade segments reflects Indonesian and Vietnamese processor procurement scale, though margins are tightening due to certified sustainable palm oil availability constraints. Small-batch pharmaceutical buyers exhibit lowest price sensitivity; high-volume food processors drive hardest bargain leverage.
Supply Chain Analysis
Dual-sourcing mandates from EU and Japanese pharmaceutical buyers require simultaneous qualification of German and Southeast Asian producers, fragmenting procurement pools. Supply concentrates in Malaysia, Indonesia, and Germany, with Malaysian and Indonesian producers controlling RSPO-certified feedstock streams and German manufacturers anchoring pharmaceutical-grade documentation capabilities. Raw material dependencies rest on crude palm oil, fatty acid methyl esters, and sucrose from sugar beet or cane processing. Single-source vulnerability runs through RSPO-certified plantation capacity, where sustainability audit backlogs delay new supplier qualification. Distribution runs through direct manufacturer relationships for tier-one formulators, with regional distributors serving mid-tier accounts lacking technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: pharmaceutical-grade production commands documentation premiums in Germany and Japan, while feedstock-integrated Southeast Asian producers capture cost advantages in food-grade volumes. The spread between these pricing regimes rewards multi-site qualification strategies.
For Market Incumbents: Deploy backward integration into RSPO-certified palm oil sourcing to defend margin position against emerging Asian producers with captive fatty acid capabilities. Incumbents must simultaneously expand EXCiPACT-certified capacity in Germany's Rhine-Ruhr corridor to meet Japan's MHLW pharmaceutical excipient standards, locking out lower-purity competitors from injectable applications.
For New Entrants and Emerging Players: Begin with enzymatic synthesis technology for pharmaceutical lyophilization powder grades, where documentation premiums and analytical chemist scarcity create defendable positioning. The most penetrable white space sits in cell-culture media applications for bioreactor shear protection, displacing poloxamers through direct technical selling to contract manufacturers.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with alkoxylation backbones are the most active acquirer in this space, seeking pharmaceutical-grade documentation capabilities to complement existing surfactant portfolios. Acquisition targets should display RSPO certification, multi-site audit readiness, and established relationships with personal care formulators in French and German cosmetic clusters. Watch for inflection when EFSA novel food opinion backlogs force bakery and confectionery reformulation toward existing approved ester grades, consolidating demand around qualified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into RSPO-Certified Feedstock | Captive palm oil sourcing secures cost-competitive production for EU REACH-compliant grades. |
| EXCiPACT Multi-Site Certification | Dual qualification in Germany and Japan unlocks pharmaceutical lyophilization documentation premiums. |
| Enzymatic Synthesis Scale-Up | Immobilized lipase systems reduce solvent residues for MHLW injectable-grade standards. |
| Direct Offtake Agreements with Formulators | Bypassing distributors captures margin from clean-label procurement in French cosmetic clusters. |
| Cell-Culture Media Technical Partnerships | Bioreactor shear-protection positioning displaces poloxamers in contract manufacturing relationships. |
Methodological Framework
Direct dialogue with plant managers at sucrose ester production facilities, procurement leads at personal care and food processing OEMs, RSPO certification auditors, and pharmaceutical formulation chemists grounded the qualitative foundation. Secondary validation drew from EFSA novel food opinion databases, ECHA REACH registration filings, Japanese MHLW pharmaceutical excipient standards, and trade flow data for palm oil derivatives. Bottom-up capacity estimates and top-down demand segmentation were triangulated against producer revenue disclosures.
Segmented outputs across physical form, application end-use, HLB functional specification, and regional regulatory cluster were generated across the projection horizon. CAGRs were derived from elasticity-adjusted demand modeling incorporating clean-label substitution rates and pharmaceutical-grade purity threshold evolution. Forecast inputs included RSPO-certified plantation expansion timelines and enzymatic process yield improvement curves.
Several conditions sit outside the modeled scope, including abrupt EFSA regulatory reversals, palm oil price volatility spikes, and pharmaceutical excipient standard harmonization between Japan and other jurisdictions. Deviation in certified sustainable palm oil availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
South Korea Allulose Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
North America Stevia Market
Sweeteners
Europe Stevia Market
Sweeteners
Global Cane Molasses Market
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Europe Starch Sweetener Market
Sweeteners
France Food Sweetener Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
Sugar Polyols Market
Sweeteners
Rice Syrup Market
Sweeteners
Allulose Market
Sweeteners
Agave Syrup Market
Sweeteners
Africa Stevia Market
Sweeteners
Agave Nectar Market