
 United Kingdom Food Sweetener Market | 2026-2036
United Kingdom Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Food Sweetener Market Analytics
Stevia extract is consolidating its position against artificial alternatives in British food manufacturing. Tate & Lyle PLC leverages its decades of formulation expertise to sustain supply relationships with major beverage brands. Cargill Incorporated anchors its UK operations through integrated stevia sourcing and processing capabilities. Südzucker AG competes aggressively in the bulk sucrose segment while navigating price pressures from natural sweetener substitution.
Food sweeteners encompass caloric and non-caloric substances added to food and beverage products to impart sweetness, typically measured by sucrose equivalence and stability under thermal processing conditions. These ingredients serve primarily to enhance palatability, manage energy content, and preserve functional properties in processed foods across industrial and consumer applications. Sucrose retains dominant volume share in bakery products and confectionery despite gradual displacement, while stevia records the fastest expansion across beverages and dairy items as manufacturers reformulate for reduced-sugar positioning. The HoReCa distribution channel presents concentrated margin pools as food service operators seek consistent sweetness profiles at scale.
The UK's sugar tax levy and Food Standards Agency guidelines actively shape reformulation timelines and ingredient disclosure requirements for domestic manufacturers. BSI standards and EU-originated REACH compliance obligations govern purity thresholds and labeling protocols for imported sweetener raw materials. Stakeholders must monitor evolving clean-label certification demands and traceability mandates to secure shelf placement with British retail buyers.
Market Dynamics
The UK's Soft Drinks Industry Levy continues compressing sucrose volumes across British beverage manufacturing, redirecting procurement budgets toward stevia and monk fruit extracts as formulators race to maintain sweetness intensity without triggering tax thresholds.
Growth Catalysts
- Soft Drinks Industry Levy:The tiered sugar tax penalizes beverages exceeding 5g sugar per 100ml, compelling Coca-Cola Europacific Partners and Britvic to accelerate reformulation timelines toward high-purity stevia glycosides.
- Clean-label certification demand:British Retail Consortium standards now require ingredient traceability to farm level, advantaging vertically integrated stevia processors with captive Paraguayan and Chinese cultivation contracts.
- Plant-based dairy expansion:Oat and almond milk producers across Greater Manchester and Yorkshire are substituting sucrose with erythritol-stevia blends to achieve neutral flavor profiles without added calories.
Market Restraints
- Stevia leaf supply concentration:Over 70% of global raw stevia extraction capacity sits with Chinese processors in Fujian and Shandong provinces, exposing British formulators to yuan-denominated input volatility and geopolitical freight disruptions.
- Bitterness masking costs:Reb-A and Reb-M steviol glycosides require expensive taste-modulator adjuncts or enzymatic bioconversion to suppress licorice aftertaste, eroding unit economics versus aspartame in cost-sensitive applications.
- REACH compliance burden:ECHA registration requirements for novel sweetener molecules impose 18-24 month approval timelines and six-figure dossier preparation costs, freezing innovation pipelines for mid-scale British ingredient houses.
Strategic Opportunities
- Scottish and Welsh food manufacturing corridors:Devolved administration economic development funds in Glasgow and Cardiff are subsidizing clean-label ingredient manufacturing facilities, creating localized supply alternatives to England-centric distribution.
- Precision fermentation-derived sweeteners:Amyris-style biomanufacturing of rare steviol glycosides via engineered yeast strains promises 40% cost reduction versus agronomic extraction, with pilot facilities emerging in Cambridge and Oxford science parks.
- NHS procurement reform:National Health Service hospital catering contracts now mandate reduced-sugar specifications for patient meals and retail concessions, opening institutional volume channels previously dominated by sucrose suppliers.
Industry Challenges
- Enzymology talent scarcity:British universities produce insufficient biocatalysis PhDs to staff the bioconversion R&D labs that stevia processors require for next-generation glycoside production, forcing reliance on Danish and Dutch technical consultants.
- Legacy ERP integration:Food Standards Agency traceability mandates require lot-level ingredient tracking from farm to finished goods, but many Midlands-based contract manufacturers operate on 1990s-era MRP systems incapable of automated genealogy capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Food Sweetener Market |
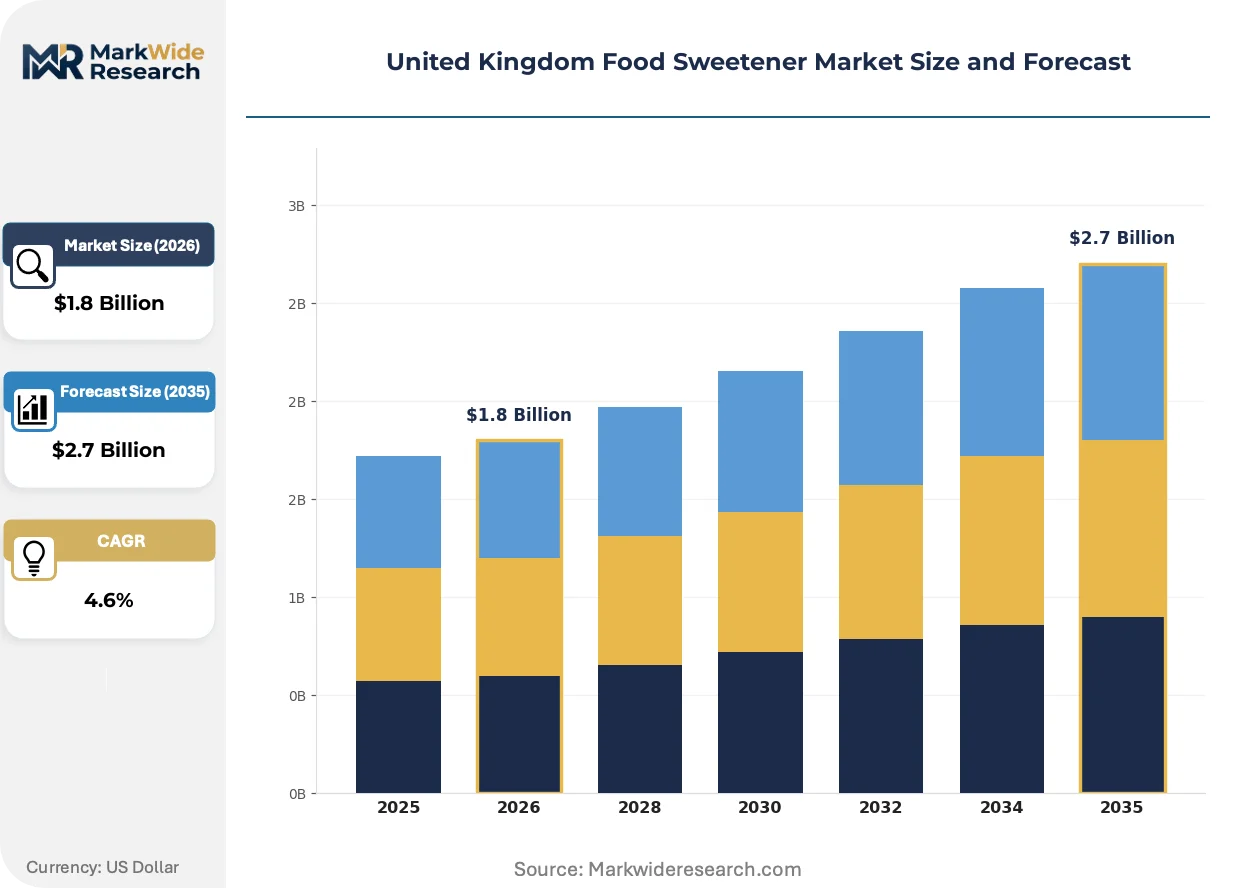
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose, Glucose Syrup, High Fructose Corn Syrup, Stevia Application: Beverages, Bakery Products, Dairy Items, Confectionery Distribution Channel: Supermarkets, Convenience Stores, Online Retail, HoReCa End User: Households, Food Manufacturers, Restaurants, Cafés |
| Companies Covered | Tate & Lyle PLC, Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, DuPont, Tereos S.A., PureCircle Limited, GLG Life Tech Corporation, Südzucker AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Food Sweetener Market Evolving Landscape
Bioconversion technologies and enzymatic processing are compressing the cost curve for rare steviol glycosides, while regulatory disclosure requirements and procurement digitization reshape how British formulators source and specify sweetener inputs.
Enzymatic glycosylation platforms are unifying the production of Reb-M and Reb-D steviol glycosides from lower-grade leaf extracts. Tate & Lyle and Cargill are deploying these systems at commercial scale across their British manufacturing assets. This convergence is collapsing the historical price premium between commodity Reb-A and premium glycosides, forcing pure-play stevia extractors to defend margin through proprietary cultivar development.
Food Standards Agency guidance on novel food notifications is tightening the evidentiary threshold for fermentation-derived sweeteners entering the UK market. The regulator now requires 90-day toxicology studies and full metabolite characterization that agronomic extracts bypass through grandfathered approval. Small molecule biomanufacturers in Oxford and Cambridge are responding by front-loading regulatory dossier costs into Series B fundraising rounds rather than amortizing across commercial launch.
Retail buyer consolidation is compressing supplier negotiation cycles across British grocery. Tesco, Sainsbury's, and Asda now coordinate joint sweetener specification reviews through their collective buying alliance, replacing the fragmented procurement that previously allowed ingredient houses to price-discriminate by account. This concentration is most visible in private-label beverage manufacturing, where reformulation decisions for 2,000-plus SKUs now route through centralized technical panels in Hertfordshire and Leeds rather than individual category managers.
United Kingdom Food Sweetener Market Segmentation
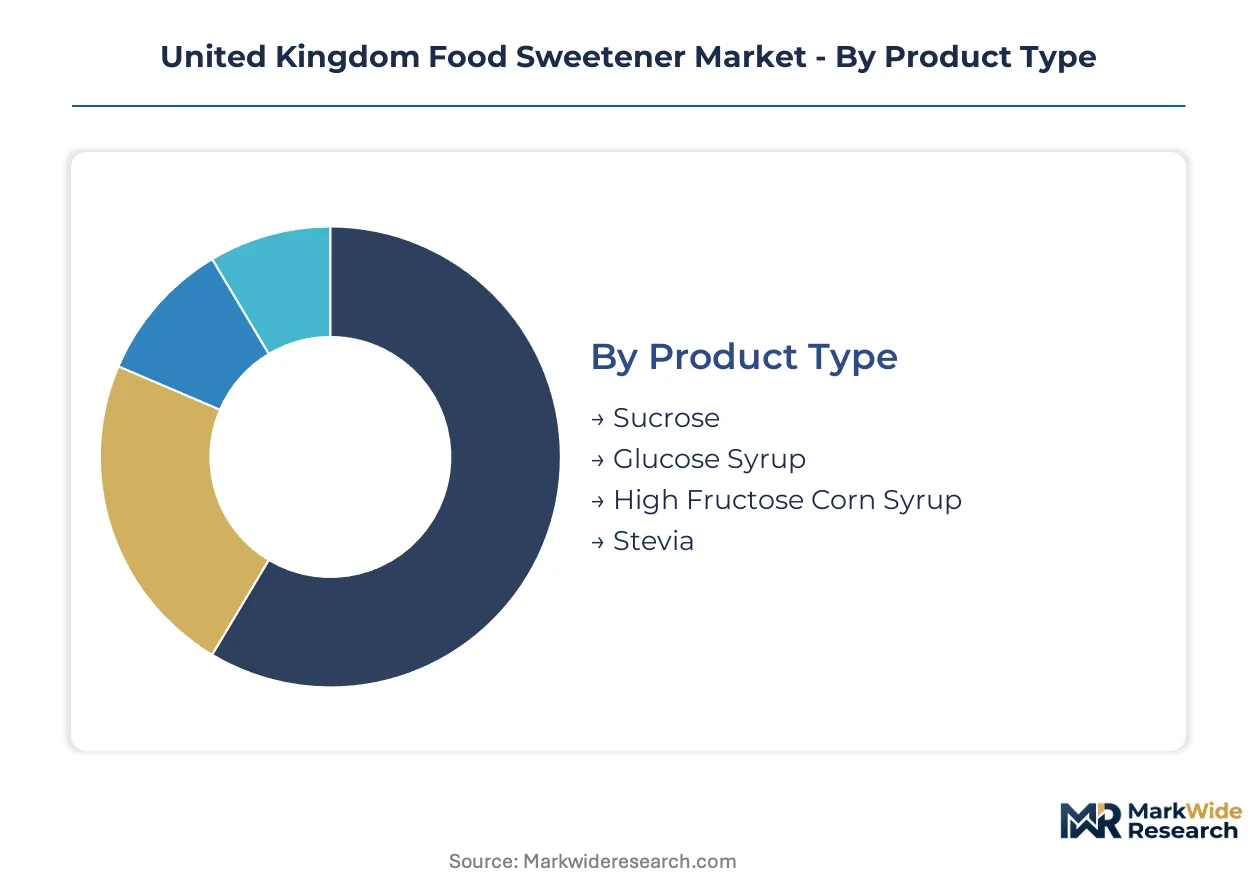
United Kingdom food sweetener procurement splits sharply between commodity bulk purchasing and premium clean-label specifications. Manufacturers navigating the Soft Drinks Industry Levy must match segment-specific sweetness intensity targets against reformulation cost constraints.
Product Type:
Volume dominance concentrates in caloric sweeteners, while premium positioning accelerates in stevia glycosides as beverage formulators chase tax threshold compliance.
- Sucrose:Crystalline cane and beet sugar retains dominant tonnage across British food manufacturing. Bakery and confectionery operations in England's Midlands corridor source this through Tate & Lyle and British Sugar supply contracts, though the sugar tax is compressing beverage applications.
- Stevia:High-purity Reb-A and Reb-M glycosides command premium positioning against artificial alternatives. Coca-Cola Europacific Partners and Britvic procurement teams specify these extracts for reduced-calorie reformulations targeting sub-5g sugar thresholds.
- Glucose Syrup:Enzymatically hydrolyzed starch syrup provides bulk sweetness and humectancy in baked goods manufacturing.
- High Fructose Corn Syrup:Isoglucose holds limited penetration in UK formulations due to sugar beet supply abundance and consumer perception challenges.
Mature deployment sits with sucrose. Newer deployment is concentrated in stevia glycosides.
Application:
End-use differentiation tracks reformulation urgency, with taxed beverage categories forcing fastest ingredient substitution timelines.
- Beverages:Carbonated soft drinks, juices, and flavored waters face immediate sugar reduction mandates under the Soft Drinks Industry Levy. High-purity stevia extracts and erythritol blends are displacing sucrose fastest here as formulators race to maintain sweetness intensity without triggering tax thresholds.
- Bakery Products:Cakes, biscuits, and pastries retain sucrose dominance due to Maillard reaction requirements and structural functionality. Yorkshire and Greater Manchester manufacturing clusters source bulk sweeteners through established distributor networks with limited clean-label substitution pressure.
- Dairy Items:Yogurt and flavored milk producers balance sugar reduction claims against fermentation compatibility.
- Confectionery:Chocolate and sugar confectionery manufacturers face partial exemption from beverage-focused tax structures.
Reformulation pressure peaks in beverages. Functional stability requirements protect incumbent sweeteners in bakery.
Distribution Channel:
Channel selection determines margin capture, with institutional procurement consolidating specifications while retail fragments across format tiers.
- HoReCa:Hotels, restaurants, and catering operations purchase sweeteners through wholesale food service distributors with standardized sweetness profiles. Bid pricing concentrates volume with Brakes and Bidfood supply contracts across Greater London and Birmingham service clusters.
- Supermarkets:Tesco, Sainsbury's, and Asda coordinate joint sweetener specification reviews through their buying alliance, centralizing procurement decisions for private-label beverage and bakery SKUs.
- Convenience Stores:Symbol group retailers and independent convenience operators source through wholesale cash-and-carry networks.
- Online Retail:Amazon and Ocado channels capture specialty and organic sweetener demand from health-conscious households.
Consolidated procurement sits with HoReCa. Fragmented purchasing persists in online retail.
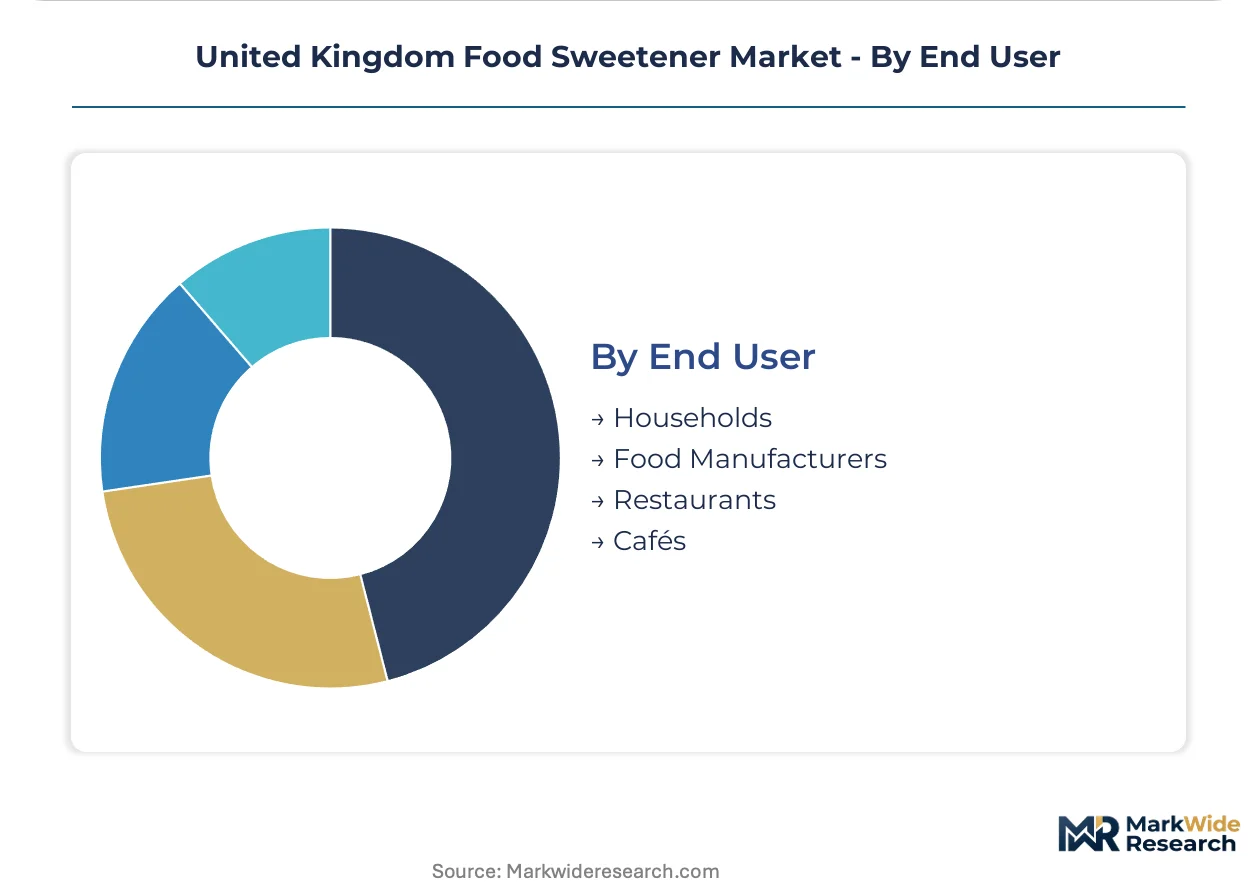
End User:
User category shapes specification complexity, with industrial formulators driving technical innovation while food service prioritizes cost consistency.
- Food Manufacturers:Industrial-scale beverage, bakery, and dairy producers employ food technologists to optimize stevia-sucrose blends for cost-targeted sweetness delivery. These teams navigate Food Standards Agency disclosure requirements while managing enzymatic bioconversion sourcing from Cargill and Tate & Lyle technical service divisions.
- Households:Consumer retail purchases split between commodity sugar and premium stevia tabletop sweeteners.
- Restaurants:Independent and chain restaurant operators specify bulk sweeteners through food service distributors with limited formulation flexibility.
- Cafés:Coffee shop chains and independents source standard sucrose and artificial sachet alternatives.
Technical specification leadership sits with food manufacturers. Volume growth concentrates in household premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for food sweeteners across the United Kingdom concentrates in England's manufacturing corridors, with Scotland and Wales emerging as alternative production hubs under devolved economic development programs.
Greater London and the Southeast
Beverage formulators in Greater London face the strictest Soft Drinks Industry Levy compliance deadlines. The Food Standards Agency maintains its headquarters here, accelerating enforcement timelines for novel sweetener notifications. Thames Valley logistics clusters handle inbound stevia extract shipments from Chinese processors.
West Midlands
Bakery and confectionery manufacturers in Birmingham and Coventry retain sucrose-dominant supply contracts with British Sugar. The region's legacy food processing infrastructure resists rapid clean-label conversion. Wolverhampton distribution hubs serve as consolidation points for glucose syrup deliveries to industrial bakeries.
Greater Manchester and Yorkshire
Plant-based dairy producers across Manchester and Leeds are substituting erythritol-stevia blends for sucrose in oat and almond milk formulations. The British Retail Consortium coordinates joint procurement specifications from offices in Leeds. Sheffield-based contract manufacturers struggle with Food Standards Agency traceability mandates on aging MRP systems.
Scotland
Scottish Enterprise development funds in Glasgow subsidize clean-label ingredient manufacturing facilities. Whisky distillers in Speyside and Islay maintain traditional sucrose and caramel specifications for flavoring. Edinburgh food technology startups pilot precision fermentation-derived sweeteners with university research partnerships.
Wales
The Welsh Government's economic development programs in Cardiff target reduced-sugar food manufacturing investment. South Wales valleys host limited legacy sweetener processing capacity. Swansea University biocatalysis research feeds into regional stevia bioconversion R&D initiatives.
United Kingdom Food Sweetener Market Competitive Landscape
Capacity expansion dominates the current landscape as established processors retrofit existing assets for stevia glycoside production. The market structure tilts toward consolidated supply relationships between multinational ingredient houses and British beverage manufacturers. Three archetypes define competitive positioning: legacy sugar processors defending bulk sucrose volumes, integrated stevia extractors with captive cultivation contracts, and fermentation technology specialists pursuing biomanufacturing routes. M&A activity and strategic partnerships represent the dominant competitive moves, with processors acquiring taste-modulation technology capabilities and biotechnology firms licensing enzymatic bioconversion platforms.
Within the integrated processor tier, Tate & Lyle PLC and Cargill Incorporated exemplify supply relationship anchoring through formulation expertise and captive sourcing capabilities. Südzucker AG occupies a position representing legacy European sugar processing concentration, while PureCircle Limited sits within the stevia-specialist archetype despite ownership integration into larger ingredient houses. Archer Daniels Midland Company and Ingredion Incorporated represent North American-based diversified carbohydrate processors with British distribution presence. These six entities collectively illustrate how competitive positioning stratifies across vertical integration depth, geographic origin, and portfolio breadth in UK sweetener procurement.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| DuPont |
| Tereos S.A. |
| PureCircle Limited |
| GLG Life Tech Corporation |
| Südzucker AG |
| Others |
Value Network & Pricing Analysis
Joint procurement specifications from Tesco, Sainsbury's, and Asda compress supplier negotiation cycles and force stevia extractors to absorb taste-modulator costs or lose shelf placement, tightening margins across British formulation houses while elevating premium positioning for vertically integrated processors with captive Paraguayan cultivation.
Pricing Analysis
Volume dominance in commodity sucrose trades at thin margins through long-term offtake contracts with British Sugar, while premium stevia glycosides capture wider spreads through purity-tier differentiation and Food Standards Agency disclosure compliance. Price compression runs through standard-grade Reb-A as Chinese processors flood spot markets, though Reb-M and Reb-D maintain resilience via enzymatic bioconversion cost barriers. Industrial beverage manufacturers exhibit acute price sensitivity, whereas NHS institutional procurement tolerates premium positioning for reduced-sugar mandates.
Supply Chain Analysis
Regional distribution centers at Wolverhampton and Thames Valley operate hub-and-spoke patterns consolidating inbound stevia leaf extracts from China, Paraguay, and Kenya before final-mile delivery to Midlands beverage plants. Raw material dependencies center on Fujian and Shandong province extraction capacity, British Sugar beet processing, and enzymatic catalyst supply from Danish biotech specialists. Single-source vulnerability concentrates in yuan-denominated leaf procurement, exposing formulators to geopolitical freight disruptions. Distribution runs through Brakes and Bidfood food service networks for HoReCa channels, with direct manufacturer-to-retailer contracting dominating supermarket private-label flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stevia leaf supply concentration in Chinese provinces props pricing power for integrated processors, constraining margin recovery for British formulators lacking backward cultivation control.
For Market Incumbents: Anticipate continued price erosion in commodity Reb-A by accelerating enzymatic glycosylation deployment at British manufacturing assets to collapse premium glycoside cost curves. Secure captive supply through Paraguayan cultivation partnerships or precision fermentation licensing from Cambridge and Oxford biotech clusters to defend margin against pure-play Chinese extractors. For New Entrants and Emerging Players: The Soft Drinks Industry Levy in the United Kingdom opens a window for fermentation-derived sweetener specialists to bypass agronomic supply constraints through engineered yeast biomanufacturing. Target NHS hospital catering procurement with reduced-sugar specifications and precision fermentation cost advantages, positioning against legacy sucrose suppliers through institutional volume channels. For Investors and Strategic Acquirers: The window for entry favors biotechnology firms with enzymatic bioconversion platforms and regulatory dossier capabilities, as ECHA registration timelines freeze mid-scale innovation pipelines. Monitor Food Standards Agency novel food notification approval velocity as the inflection indicator for fermentation-derived sweetener commercialization feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioconversion Scale-Up | Tate & Lyle and Cargill deployment collapses Reb-M price premiums versus commodity Reb-A extracts. |
| Precision Fermentation Facility Buildout | Cambridge and Oxford science park pilots promise 40% cost reduction versus Chinese leaf extraction. |
| Captive Cultivation Contracting | Paraguayan and Chinese farm-level traceability secures British Retail Consortium clean-label certification. |
| Regulatory Dossier Front-Loading | Series B fundraising integration addresses ECHA 18-24 month approval timelines for novel molecules. |
| NHS Procurement Channel Penetration | Hospital catering mandates open institutional volume previously locked by sucrose incumbents. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with food technologists at beverage manufacturers, procurement leads at Tesco and Sainsbury's, enzymatic bioconversion specialists at Tate & Lyle, and regulatory affairs managers navigating Food Standards Agency novel food notifications. British Soft Drinks Association consumption statistics, HMRC import records, ECHA registration databases, and British Retail Consortium certification directories provided validation layers, with bottom-up volume modeling triangulated against top-down category spend estimates.
Granularity-level modeling operated at product type, application, and distribution channel dimensions, with additional segmentation by purity grade for stevia glycosides and tax-status compliance for beverage formulations. CAGRs derived from regression analysis of historical levy-driven substitution patterns projected across the analysis window, incorporating Soft Drinks Industry Levy threshold adjustments and NHS procurement reform timelines as scenario inputs.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation-derived sweeteners would alter the outlook if ECHA accelerates novel food approval timelines or if Chinese leaf processors achieve enzymatic glycosylation cost parity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
China Food Sweetener Market
Sweeteners
North America Stevia Market
Sweeteners
Food Sweetener Market
Sweeteners
White Sugar Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
D-Mannose Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Spain Food Sweetener Market
Sweeteners
Corn Syrup Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Cassava Syrup Market
Sweeteners
Fermented Sweeteners Market
Sweeteners
Oligofructose Market