
 Milk Fat Fractions Market | 2026-2036
Milk Fat Fractions Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Fat Fractions Market Analysis
New Zealand is fragmenting its traditional bulk butter export model into higher-margin fractionation streams, with Fonterra Co-operative Group Limited leveraging its cooperative structure to sustain captive milk supply across seasonally variable production. Groupe Lactalis anchors European fractionation capacity through multi-site dairy processing networks in France and Italy. Arla Foods amba competes on cooperative-owned supply security, while Saputo Inc. extends North American reach through integrated cheese and whey-fat recovery operations.
Milk fat fractions are lipid concentrates obtained by thermal or solvent-free crystallization of butterfat, yielding distinct melting profiles ranging from low-melting olein to high-melting stearin fractions for targeted functional applications in food formulation. The process typically separates triglyceride classes at 20-40°C controlled cooling regimes, producing fractions with slip points between 15°C and 45°C for confectionery coating, bakery shortening, and dairy recombination. Butter and cream fractions dominate current volume throughput, though powder and semi-solid forms are gaining traction among food manufacturers seeking extended shelf stability and precise dosing in automated production lines. Bakery and confectionery applications command premium positioning due to strict tempering requirements and cocoa butter compatibility standards.
FDA standards for dairy identity and labeling, coupled with EFSA novel food assessments for enzymatically modified fat fractions, shape product approval timelines and cross-border formulation compliance. BIS certification requirements in India and China's NMPA dairy import safety protocols further segment market access by regulatory jurisdiction. Stakeholders must monitor evolving fractionation technology patents and regional clean-label enforcement intensity to calibrate capacity deployment and product portfolio prioritization.
Market Dynamics
The EU F-Gas Regulation is forcing dairy processors to abandon conventional solvent-based fractionation in favor of thermal crystallization systems, compressing capital deployment timelines and reshaping supplier qualification criteria across European manufacturing networks.
Growth Catalysts
- Clean-label confectionery reformulation:Premium chocolate manufacturers in Germany and Switzerland are substituting hydrogenated palm oils with high-melting stearin fractions to meet retailer clean-label mandates.
- EFSA novel food pathways:Enzymatically modified milk fat fractions are gaining regulatory clearance for functional food applications, opening formulation possibilities in sports nutrition and infant formula.
- Seasonal supply arbitrage:New Zealand's cooperative processing structure enables year-round fractionation despite hemispheric milk production seasonality, stabilizing olein supply for Asian bakery chains.
Market Restraints
- Butterfat input volatility:Global butter prices fluctuate with pasture conditions and grain costs, compressing fractionation margins when cream feedstock spikes.
- Fractionation capacity concentration:Industrial-scale dry fractionation plants cluster in France, Italy, and Germany, creating supply vulnerability during energy price shocks or maintenance cycles.
- Plant lipid substitution:Cocoa butter equivalents from shea and illipe fractions compete on cost for confectionery coating applications where tempering precision is secondary.
Strategic Opportunities
- Indian bakery modernization:BIS certification for milk fat fractions in industrial shortening creates first-mover advantage as domestic biscuit and pastry manufacturers automate production lines.
- Carbon accounting integration:EU Green Deal sustainability reporting requirements favor fractionation over hydrogenation, rewarding processors with verified low-carbon thermal crystallization processes.
- Precision fermentation convergence:Blending traditional fractionated lipids with microbially-derived triglycerides enables custom melting profiles for personalized nutrition applications.
Industry Challenges
- Fractionation technologist scarcity:Operating controlled-crystallization plants requires specialized expertise in triglyceride polymorphism that outpaces vocational training pipeline output.
- Cross-border formulation compliance:FDA dairy identity standards conflict with EFSA novel food classifications, forcing dual-track product development for transatlantic brands.
- Patent landscape navigation:Dense intellectual property around solvent-free separation methods creates licensing friction for equipment upgrades and process modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Fat Fractions Market |
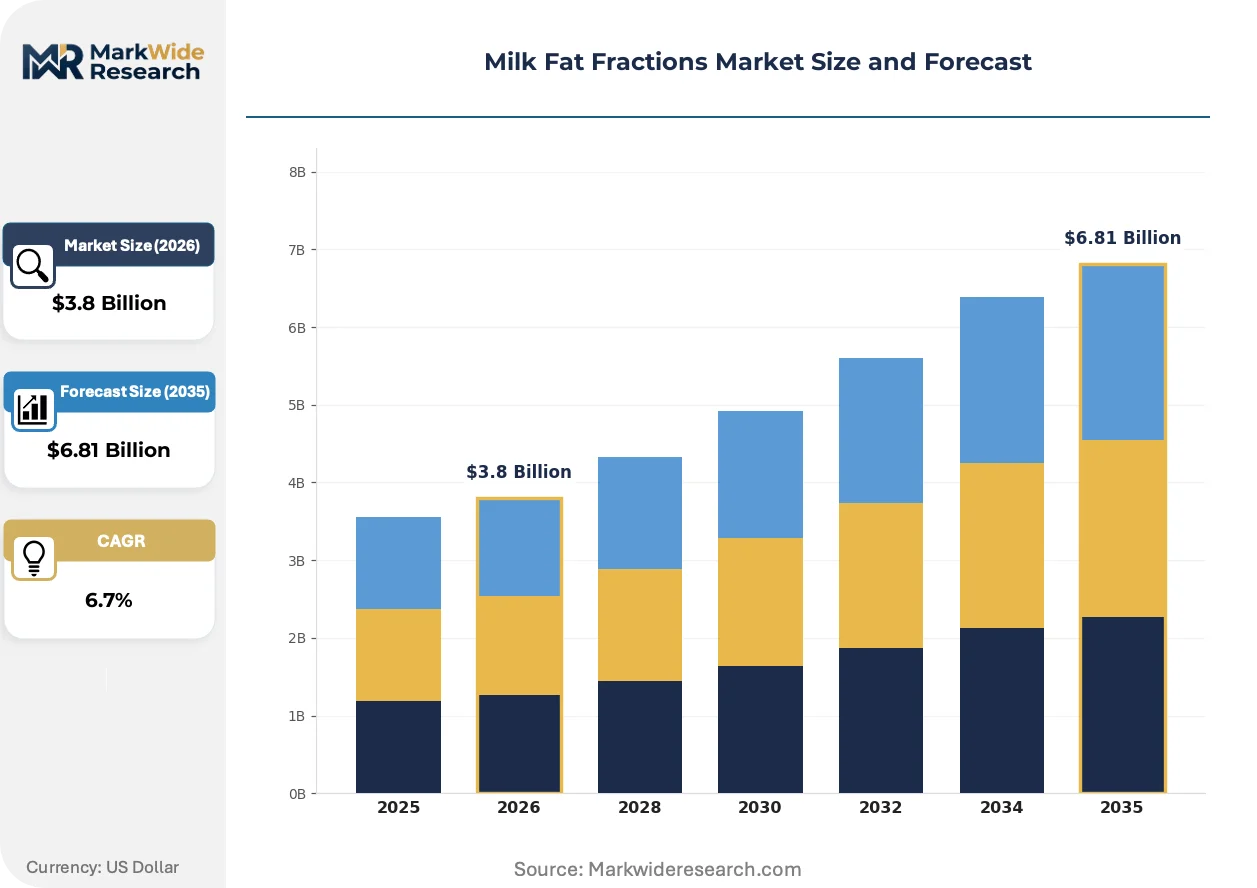
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Ghee, Cream, Cheese Application: Dairy Products, Confectionery, Bakery, Food Processing End User: Food Manufacturers, Retailers, HoReCa, Households Form: Liquid, Powder, Semi-Solid, Solid |
| Companies Covered | Koninklijke FrieslandCampina N.V., Land O'Lakes, Inc., Dairy Farmers of America, Inc., Glanbia plc, Arla Foods amba, Fonterra Co-operative Group Limited, Saputo Inc., Uelzena Milchwerke eGmbH, Groupe Lactalis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Fat Fractions Market Emerging Trajectories
Fractionation technology is pivoting toward energy-efficient thermal crystallization while regulatory pressure on hydrogenated oils accelerates clean-label lipid sourcing. These shifts are compressing traditional supply relationships and rewarding processors with integrated sustainability verification.
Supercritical carbon dioxide fractionation is rendering obsolete conventional multi-stage dry crystallization for high-value stearin production. Specialty chocolate manufacturers in Belgium and Switzerland are piloting these systems to achieve precise 42°C slip-point fractions with reduced thermal degradation. The technology is rendering obsolete legacy solvent-based separation, eliminating residual solvent testing requirements and shortening regulatory approval timelines for premium confectionery launches.
The EU F-Gas Regulation mandates phase-down of hydrofluorocarbon-based refrigeration in dairy processing facilities, forcing retrofit of fractionation plant cooling systems. Industrial processors in France and Italy face accelerated capital expenditure schedules to comply with 2027 benchmarks for equipment replacement. Bakery shortening suppliers dependent on German fractionation capacity are auditing supplier refrigeration compliance to secure continuity certifications for retail private-label contracts.
Confectionery procurement teams are consolidating supplier relationships around fractionation specialists with integrated carbon accounting and mass-balance certification. Long-tail distributors of commodity butter oils are losing shelf space to processors offering lot-traceable stearin and olein fractions with embedded lifecycle data. This concentration is most visible in German and Swiss manufacturing clusters where retailer sustainability scorecards determine ingredient list approval.
Milk Fat Fractions Market Segmentation
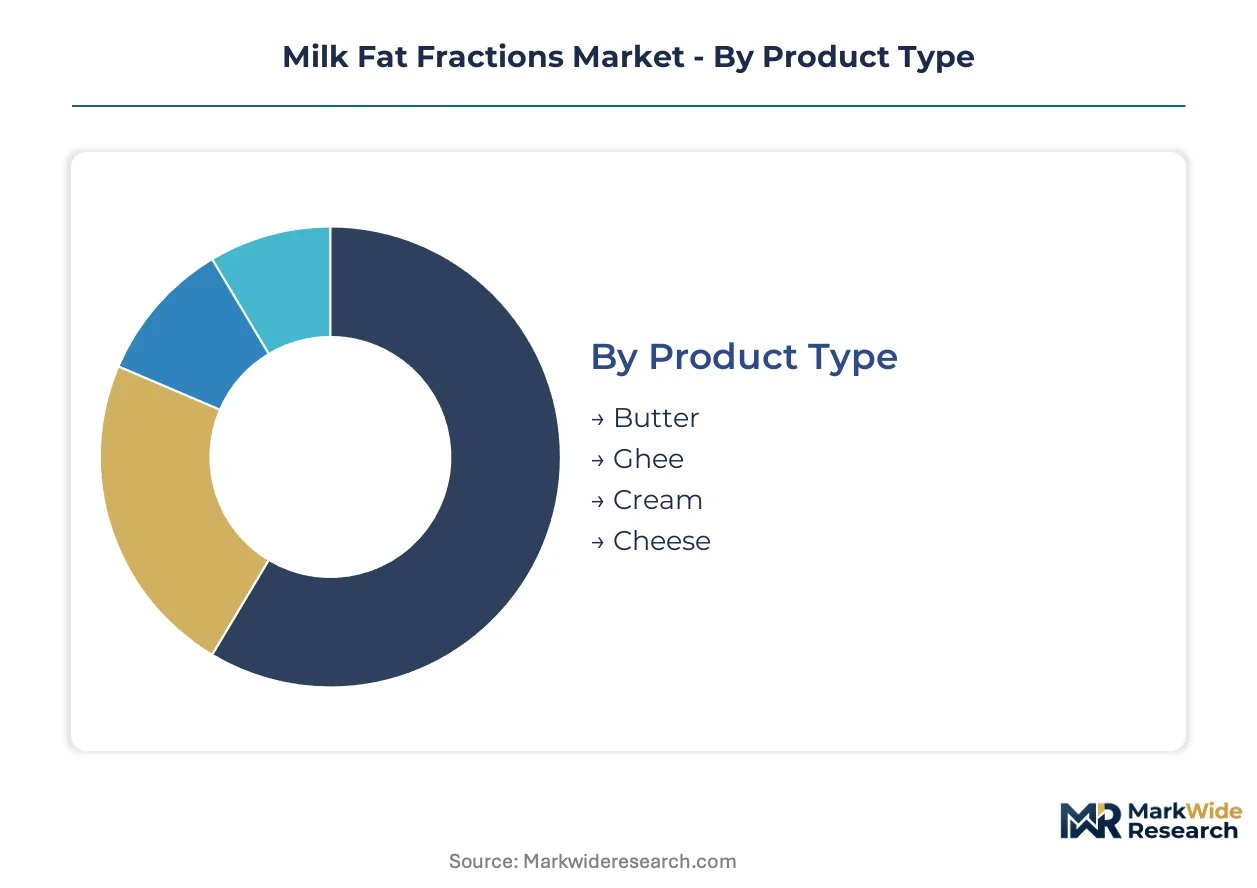
Milk fat fractions derive commercial value from precise melting-point engineering, making product-type selection and application targeting decisive for margin capture. Form and end-user channel choices determine capital intensity and regulatory compliance burdens across manufacturing footprints.
Product Type:
Cost tier stratification separates commodity bulk streams from premium fractionation outputs requiring controlled crystallization infrastructure.
- Butter:Anhydrous milk fat fractions from butter yield olein and stearin streams with slip points spanning 15°C to 45°C. German confectionery coaters specify high-melting stearin fractions from butter to replace hydrogenated oils under retailer clean-label mandates.
- Cream:Fresh cream fractionation produces low-melting olein fractions prized for bakery shortening applications. French industrial bakers concentrate procurement on cream-derived olein for laminated dough production requiring plastic fat functionality across temperature fluctuations.
- Ghee:Clarified butter fractions from South Asian processing traditions offer distinct flavor profiles for ethnic food manufacturing.
- Cheese:Whey fat recovery from cheese operations generates secondary fractionation feedstock for recombined dairy products.
Butter holds installed capacity. Cream is rotating up the share rankings.
Application:
Application focus determines formulation complexity, with confectionery and bakery segments commanding premium positioning due to strict tempering requirements.
- Confectionery:High-melting stearin fractions with precise 42°C slip points enable cocoa butter compatibility in chocolate coating applications. Swiss and Belgian manufacturers pilot supercritical carbon dioxide fractionation to achieve reduced thermal degradation in premium stearin production.
- Bakery:Olein fractions provide plastic shortening functionality for laminated dough and puff pastry. Industrial bakery chains across India automate production lines using fractionated shortening with extended shelf stability.
- Dairy Products:Recombined milk and infant formula applications use standardized fat fractions for nutritional consistency.
- Food Processing:General food manufacturing incorporates milk fat fractions as clean-label alternatives to hydrogenated oils.
Confectionery commands premium pricing. Bakery is climbing the fastest on volume throughput.
End User:
Customer type shapes order scale and specification stringency, with food manufacturers driving standardization and retailers enforcing sustainability verification.
- Food Manufacturers:Industrial-scale buyers specify lot-traceable fractions with embedded carbon accounting for private-label contract compliance. German and Swiss manufacturing clusters consolidate procurement around processors offering mass-balance certification.
- Retailers:Supermarket chains mandate clean-label ingredient lists and lifecycle data for shelf placement. Sustainability scorecards in Central Europe determine approved supplier lists for milk fat fraction sourcing.
- HoReCa:Hotel, restaurant, and catering channels purchase bulk fractions for in-house bakery and confectionery operations.
- Households:Consumer-packaged formats target home baking enthusiasts with convenient dosing and extended storage stability.
Food Manufacturers hold installed capacity. Retailers is rotating up the share rankings.
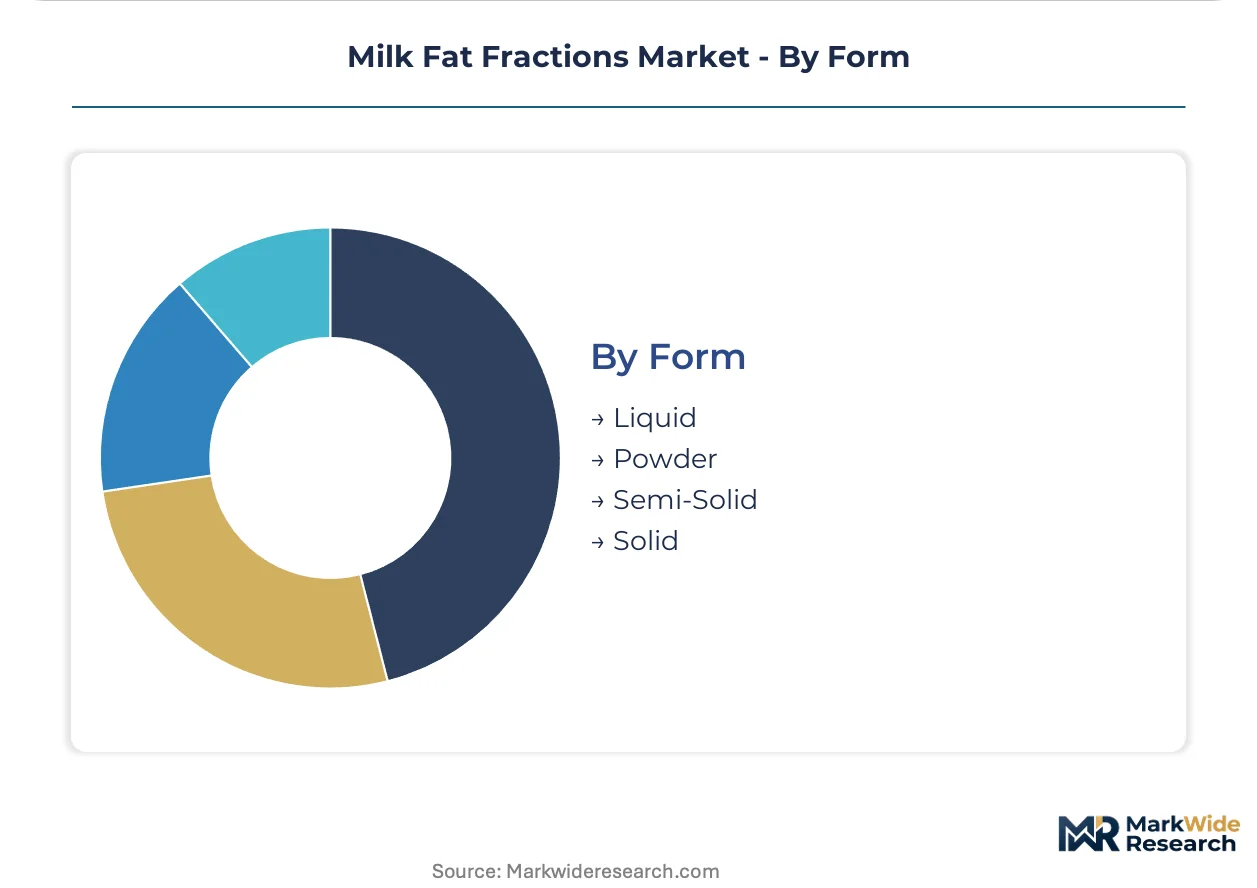
Form:
Physical state selection balances handling efficiency against functional performance, with automated production lines favoring precise dosing formats.
- Powder:Spray-dried milk fat fractions enable precise dosing in automated confectionery and bakery lines. Extended shelf stability reduces cold-chain dependency for Asian bakery chains sourcing from New Zealand fractionation facilities.
- Semi-Solid:Plastic fat fractions provide tempering control for chocolate coating applications requiring specific crystallization behavior.
- Liquid:Low-melting olein fractions ship in bulk tankers for industrial dairy recombination.
- Solid:High-melting stearin blocks serve traditional confectionery tempering operations.
Powder holds installed capacity. Semi-Solid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Switzerland consume milk fat fractions predominantly for premium confectionery coating, while India and China deploy them for industrial bakery shortening—revealing a stark split between clean-label chocolate reformulation and cost-driven food processing modernization.
Germany
Specialized fractionation facilities in Lower Saxony and Bavaria supply high-melting stearin streams to Swiss and Belgian chocolate manufacturers replacing hydrogenated palm oils. The EU F-Gas Regulation forces accelerated cooling system retrofits by 2027, compressing capital deployment timelines for processors in the Münsterland dairy cluster. Cologne-based procurement teams now audit supplier refrigeration compliance before awarding private-label contracts.
Switzerland
Premium chocolate manufacturers in the Lake Geneva region pilot supercritical carbon dioxide fractionation to achieve precise 42°C slip-point stearin with reduced thermal degradation. Swissmedic oversight of novel food applications shapes approval pathways for enzymatically modified fractions entering sports nutrition formulations. The Zürich manufacturing corridor concentrates demand for lot-traceable fractions with embedded lifecycle carbon data.
India
Industrial biscuit and pastry manufacturers in Maharashtra and Gujarat automate production lines using spray-dried milk fat fractions with extended shelf stability. BIS certification requirements for dairy ingredients create compliance gateways that favor processors with verified thermal crystallization capabilities. The Pune-Ahmedabad industrial belt drives volume uptake as domestic bakery chains expand refrigerated distribution networks.
China
Recombined dairy product manufacturers in the Yangtze River Delta source standardized olein fractions for infant formula consistency. NMPA dairy import safety protocols segment market access by requiring extensive documentation for enzymatically modified lipid ingredients. Shanghai-based food manufacturers increasingly specify powder-form fractions to reduce cold-chain dependency in automated dosing systems.
New Zealand
Cooperative processing structures enable year-round fractionation despite hemispheric milk production seasonality, stabilizing olein supply for Asian bakery chains. Fonterra's captive milk supply across variable pasture conditions sustains continuous thermal crystallization operations. The Canterbury Plains dairy cluster anchors export-oriented capacity serving refrigerated logistics corridors into Southeast Asia.
Milk Fat Fractions Market Vendor Landscape
Capability concentration sits with specialized fractionation technologists; scale advantage sits with integrated dairy cooperatives with captive milk supply. The market structures around three tiers: cooperative-owned processors with backward integration into raw milk, independent fractionation specialists with patented crystallization expertise, and diversified dairy conglomerates leveraging cheese and whey-fat recovery streams. Dominant competitive moves include capacity expansion in low-carbon thermal crystallization and strategic partnerships with confectionery manufacturers seeking clean-label certification.
Among cooperative-structured processors, Fonterra Co-operative Group Limited and Arla Foods amba exemplify the captive-supply archetype, securing milk feedstock across seasonally variable production. Groupe Lactalis occupies a position within the multi-site European network tier, anchoring fractionation capacity across France and Italy. These three represent distinct strategic postures: hemispheric supply arbitrage, cooperative-owned security, and continental manufacturing density.
| Leading Market Players |
|---|
| Koninklijke FrieslandCampina N.V. |
| Land O'Lakes, Inc. |
| Dairy Farmers of America, Inc. |
| Glanbia plc |
| Arla Foods amba |
| Fonterra Co-operative Group Limited |
| Saputo Inc. |
| Uelzena Milchwerke eGmbH |
| Groupe Lactalis |
| Others |
Supply Flow & Price Mechanics
Undercapacity in German thermal crystallization facilities is compressing supplier pricing power while accelerating long-term offtake negotiations with Swiss and Belgian confectionery manufacturers seeking supply security.
Pricing Analysis
Long-term offtake contracts dominate premium stearin procurement, with spot markets handling residual olein volumes from seasonal production peaks. Price differentiation rests on carbon certification tier and volume scale, with mass-balance verified fractions commanding substantial premia over conventional thermal crystallization outputs. Pricing pressure stems from butterfat feedstock volatility, which squeezes margins when pasture conditions spike cream costs. Industrial food manufacturers exhibit highest price sensitivity, while premium chocolate houses prioritize specification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from Swiss confectionery buyers are financing capacity expansions across French and Italian fractionation networks, tightening supplier liquidity interdependence. Geographic supply concentrates in France, Italy, and Germany, with New Zealand serving as the Southern Hemisphere anchor. Raw material dependencies center on anhydrous milk fat, fresh cream, and whey fat recovery streams from cheese operations. Single-source vulnerability runs through German high-melting stearin capacity, where maintenance cycles disrupt coating supply chains. Distribution runs through integrated dairy cooperatives with captive tanker fleets and cold-chain partnerships into Asian bakery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation is disrupting competitive positioning by forcing capital-intensive cooling retrofits, creating a window for processors with low-carbon thermal crystallization capabilities to capture shelf space from legacy solvent-based operators.
For Market Incumbents: Build regulatory compliance moats by accelerating thermal crystallization capacity in Lower Saxony and Bavaria ahead of the 2027 equipment replacement benchmarks. Secure backward integration into cooperative milk supply to buffer butterfat volatility, while patenting solvent-free separation modifications to lock out licensing competitors. The threat of enzymatically modified fraction entrants from precision fermentation platforms demands defensive patent filings around melting-point engineering. For New Entrants and Emerging Players: Build out BIS-certified production capacity in Maharashtra and Gujarat to capture Indian biscuit and pastry automation demand before incumbent dairy cooperatives establish local fractionation footholds. Target spray-dried powder formats for Asian bakery chains seeking cold-chain reduction, leveraging New Zealand's seasonal supply arbitrage as a feedstock bridge. A technical sales partnership with industrial bakery equipment manufacturers offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical carbon dioxide fractionation equipment, favoring early positioning before 2027 compliance deadlines compress available vendor capacity. Five-to-ten year viability favors processors with integrated carbon accounting and mass-balance certification infrastructure already deployed. Acquisition targets should display patented crystallization expertise and established retailer sustainability scorecard relationships. The signal to watch is German private-label contract migration toward lot-traceable suppliers with embedded lifecycle data.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Carbon Thermal Crystallization Capacity Expansion | EU F-Gas Regulation compliance secures German and Italian manufacturing network continuity certifications. |
| Supercritical Carbon Dioxide Fractionation Pilot | Swiss and Belgian chocolate manufacturers achieve precise 42°C slip points with reduced thermal degradation. |
| BIS Certification Pathway Investment | Indian biscuit and pastry automation creates first-mover advantage in Maharashtra and Gujarat industrial belts. |
| Mass-Balance Certification Integration | German retailer sustainability scorecards determine approved supplier lists for private-label contract awards. |
| Precision Fermentation Blending Partnership | Custom melting profiles for personalized nutrition applications merge traditional lipids with microbial triglycerides. |
Methodological Framework
Desk research of customs trade databases, dairy cooperative annual disclosures, and EFSA novel food assessment records preceded structured interviews with thermal crystallization plant managers, confectionery procurement directors, and bakery chain supply planners. Secondary validation drew from EU F-Gas Regulation implementation tracking, BIS certification registries, and NMPA dairy import safety protocol documentation. Bottom-up capacity modeling triangulated against top-down demand aggregation across confectionery, bakery, and recombined dairy applications.
Assumptions held fixed include regulatory enforcement intensity of clean-label mandates and the pace of Indian bakery automation adoption, while variables included butterfat price volatility bands and supercritical carbon dioxide technology diffusion rates across the analysis window. Segmentation dimensions encompassed product type, application, end-user channel, and physical form, with CAGRs derived from installed capacity utilization trends and premium substitution elasticities. Forecast inputs integrated pasture condition indices and grain cost correlations affecting cream feedstock availability.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation lipid platforms or accelerated Indian dairy modernization would shift outcomes. Macroeconomic deviation in commodity dairy markets, regulatory acceleration of novel food pathways, or breakthroughs in enzymatic modification efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America A2 Milk Market
Dairy Products
United Kingdom Casein and Caseinates Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Fermented Milk Products Market
Dairy Products
Natural Cheese Market
Dairy Products
Yogurt Drink Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
Condensed Whey Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
White Cheese Market
Dairy Products
Middle East Dairy Market
Dairy Products
Global Specialty Cheese Market
Dairy Products
China Dairy Market
Dairy Products
Organic Dairy Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
A2 Fresh Milk Market