
 Small Gas Engine Market | 2026-2036
Small Gas Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Small Gas Engine Market Intelligence
Subscription-based maintenance programs for outdoor power equipment is pivoting how manufacturers monetize long-term customer relationships. Briggs & Stratton leverages its dealer network to bundle service contracts with engine purchases. Honda Motor anchors premium positioning through extended warranty programs and certified technician training. STIHL dominates the professional landscaping channel with captive fleet-management software that tracks usage and schedules preventive maintenance.
Small gas engines are single-cylinder or V-twin internal combustion units typically displacing 25cc to 750cc, featuring air-cooled aluminum blocks with overhead valve architectures, and designed to convert hydrocarbon fuel into mechanical rotary power for portable or stationary equipment. The outdoor power equipment application segment leads unit volume, though the commercial landscaping end user generates the highest margin pool per engine due to utilization intensity and replacement frequency. Gasoline remains the dominant fuel type, yet propane configurations are gaining traction in municipalities with clean-air procurement mandates.
The EPA enforces exhaust and evaporative emissions standards under 40 CFR Part 90, while CARB operates a separate certification pathway that de facto sets the baseline for engines sold across multiple US states. OSHA noise-exposure regulations for commercial operators indirectly shape engine design priorities around muffler efficiency and operating decibel thresholds. Stakeholders must monitor state-level preemption battles over local gas-engine bans, as municipal electrification ordinances in California, Colorado, and Washington threaten to fragment addressable demand geography.
Market Dynamics
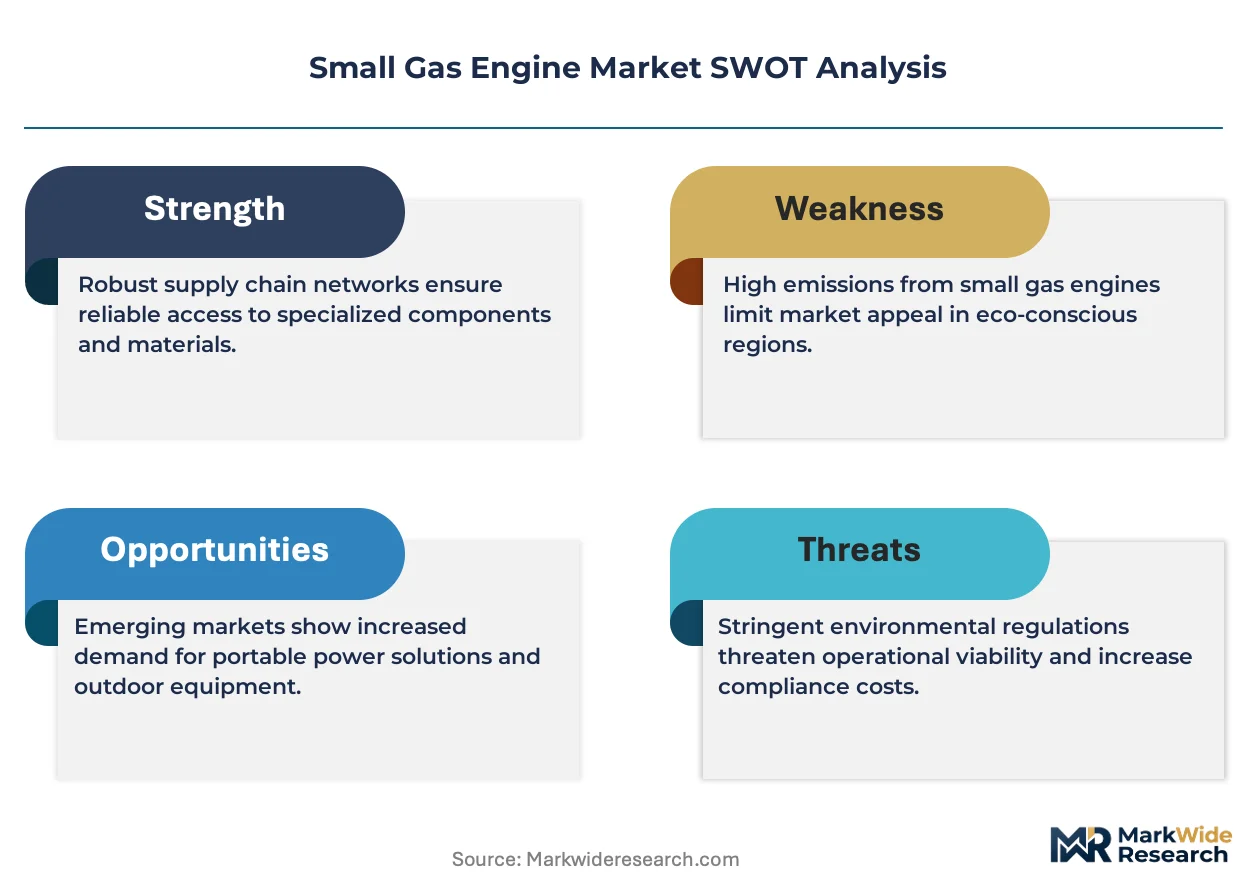
EPA Phase 3 emissions standards and CARB small off-road engine rules are forcing manufacturers to redesign combustion architectures and exhaust after-treatment systems, compressing development timelines while raising certification costs.
Growth Catalysts
- Residential landscaping fleet expansion:Outdoor services demand across Sun Belt states is driving equipment purchases by commercial contractors.
- Propane fuel configurations:Municipal clean-air procurement mandates in California and Colorado are creating alternative-fuel engine demand.
- Subscription maintenance programs:Service contract bundling through dealer networks is extending manufacturer revenue per unit.
Market Restraints
- Aluminum block cost volatility:Raw material price swings for air-cooled engine castings squeeze margin on economy-tier products.
- California regulatory fragmentation:Municipal electrification ordinances in Denver, Seattle, and Sacramento threaten addressable demand geography.
- Battery-electric substitution:Lithium-ion powered alternatives are capturing residential handheld equipment segments below 50cc displacement.
Strategic Opportunities
- Fleet-management software integration:Usage-tracking platforms for professional landscapers are creating recurring revenue streams.
- Extended warranty programs:Certified technician training networks differentiate premium positioning against price competitors.
- Propane infrastructure buildout:Clean-air procurement mandates in Texas and Florida municipalities favor dual-fuel engine configurations.
Industry Challenges
- Emissions certification timelines:EPA 40 CFR Part 90 and CARB parallel pathways create duplicative testing burdens for multi-state engine families.
- Overhead valve architecture redesign:Meeting evaporative emissions standards requires fuel system engineering that extends product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Gas Engine Market |
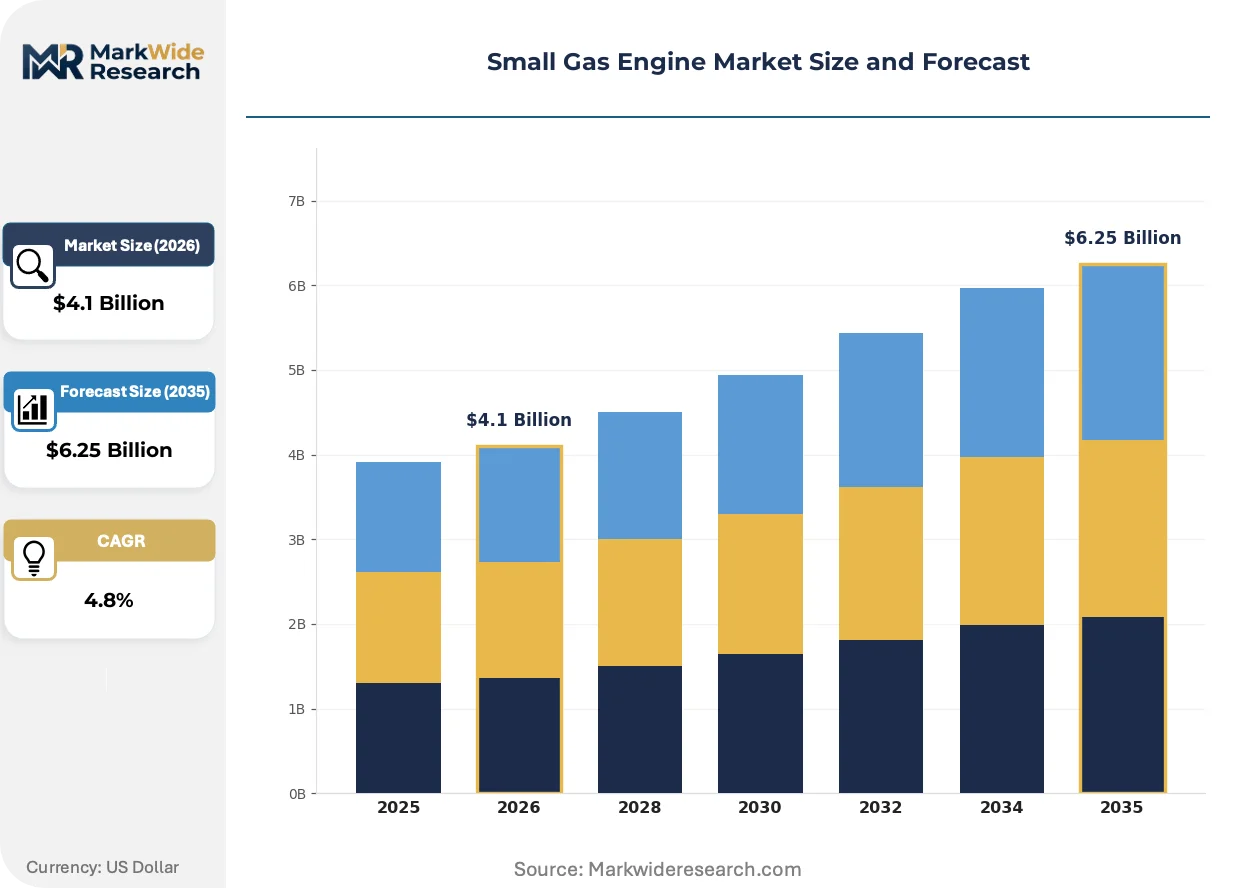
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.25 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lawn Mowers, Chainsaws, Trimmers, Generators End User: Residential, Commercial, Industrial, Agricultural Application: Outdoor Power Equipment, Construction, Landscaping, Irrigation Fuel Type: Gasoline, Propane, Ethanol, Others |
| Companies Covered | Yamaha Motor, Kawasaki Heavy Industries, Briggs & Stratton, STIHL, Kubota, Honda Motor, Generac Holdings, Subaru, Kohler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Gas Engine Market Strategic Shifts & Innovations
Digital connectivity and alternative-fuel architectures are reshaping how engine manufacturers capture lifetime value from commercial users while navigating tightening emissions constraints.
Electronic fuel injection is integrating closed-loop oxygen sensing and catalytic converter monitoring into small-displacement engines previously limited to carbureted designs. Commercial landscaping fleets are adopting these systems fastest due to utilization intensity that justifies upfront cost premiums. This technology is integrating predictive maintenance alerts through telematics modules that compress unplanned downtime for high-hour operators.
OSHA noise-exposure regulations for commercial operators are tightening muffler efficiency requirements and operating decibel thresholds. Engine designers are responding with dual-chamber exhaust architectures and acoustic insulation packages that add unit cost but prevent workplace violation liability. Professional landscaping segments in dense urban corridors face the strictest enforcement and have accelerated equipment replacement cycles.
Preventive maintenance scheduling is migrating from calendar-based to usage-hour triggers through embedded hour meters and cloud-connected fleet dashboards. Dealer service departments are capturing this shift by unbundling maintenance from equipment sales into standalone subscription contracts. Sun Belt states with year-round lawn maintenance show the highest attachment rates for these service programs.
Small Gas Engine Market Segmentation
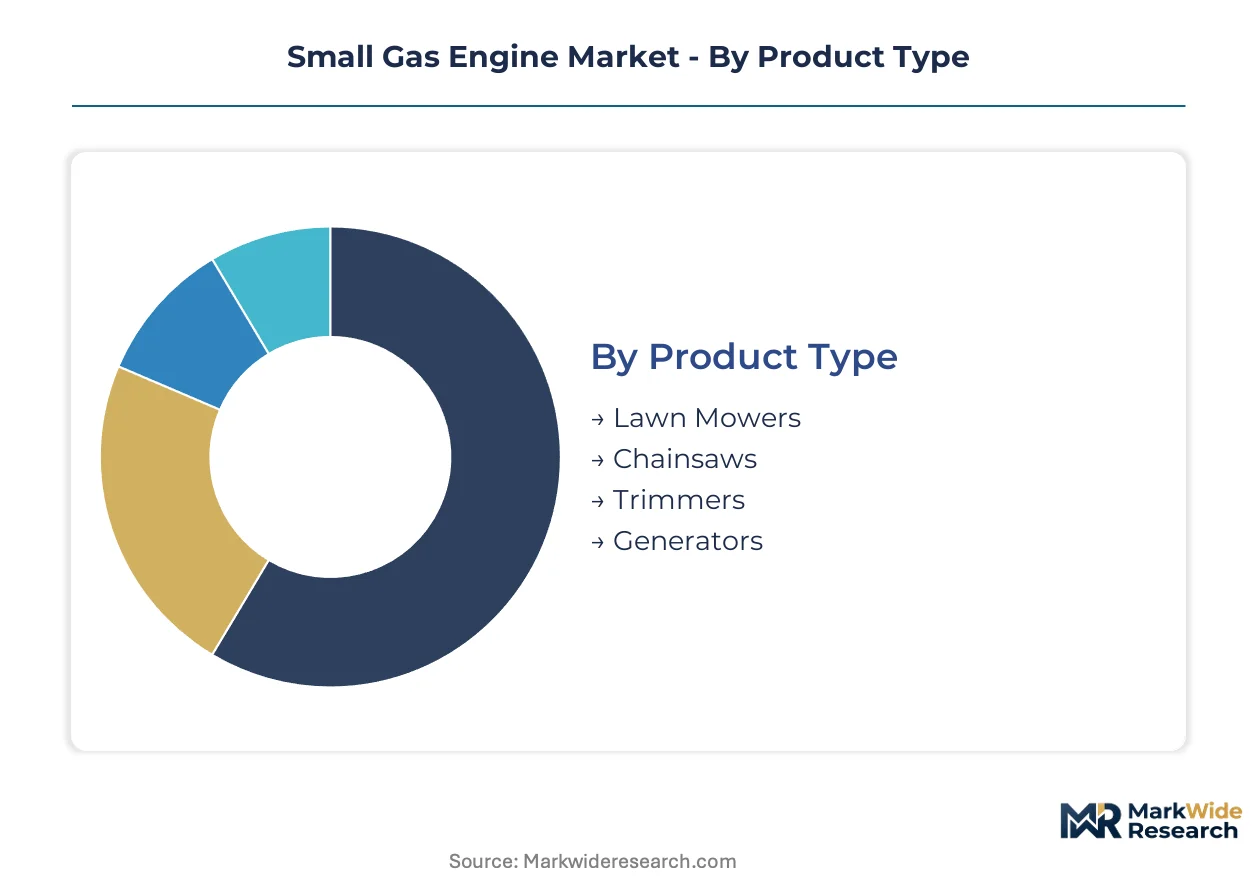
Equipment specification and duty-cycle intensity drive purchase decisions across the small gas engine landscape. End users select displacement ranges and fuel architectures based on runtime requirements, emissions compliance zones, and total cost of ownership over replacement intervals.
Product Type:
Purchase volume correlates with replacement frequency and seasonal utilization patterns in residential versus professional settings.
- Lawn Mowers:Single-cylinder and V-twin configurations displace 150cc to 750cc for walk-behind and riding platforms. Demand concentrates in Sun Belt states with year-round lawn maintenance needs, where commercial contractors replace units every 3-4 seasons due to high-hour operation.
- Chainsaws:Compact 25cc to 60cc two-stroke and four-stroke architectures prioritize power-to-weight ratios for arborist and forestry applications. Professional tree services in the Pacific Northwest and Southeast timber regions drive premium segment attachment rates for anti-vibration and heated-handle configurations.
- Trimmers:Lightweight 25cc to 35cc engines power string and brush-cutting attachments for edge maintenance and vegetation control.
- Generators:Stationary and portable units range from 200cc to 750cc for backup power and jobsite electricity supply.
Volume sits with Lawn Mowers; growth tilts toward Generators.
End User:
Margin structure varies sharply between price-sensitive residential purchasers and utilization-intensive commercial operators.
- Residential:Homeowners purchase primarily through retail channels for seasonal property maintenance with sub-50-hour annual runtime. Battery-electric substitution is capturing handheld segments below 50cc displacement in this tier.
- Commercial:Landscaping contractors and rental fleets generate the highest margin pool per engine due to replacement frequency and extended warranty attachment. OSHA noise-exposure regulations for commercial operators accelerate equipment turnover in dense urban corridors.
- Industrial:Manufacturing facilities and warehouses deploy engines for material handling and portable power generation.
- Agricultural:Farms and ranches utilize engines for irrigation pumps, augers, and specialty harvesting equipment across extended seasonal cycles.
Revenue concentrates with Commercial; expansion is steepest in Agricultural mechanization.
Application:
Emissions jurisdiction and duty-cycle intensity determine fuel system architecture and after-treatment requirements.
- Outdoor Power Equipment:Lawn mowers, chainsaws, trimmers, and blowers constitute the dominant unit volume segment. EPA Phase 3 and CARB small off-road engine rules force electronic fuel injection adoption for evaporative emissions compliance.
- Construction:Portable generators, compactors, and concrete saws demand ruggedized air-cooled blocks with high-torque profiles for intermittent heavy loading.
- Landscaping:Professional grounds maintenance fleets are adopting usage-hour-based maintenance triggers through telematics modules that compress unplanned downtime.
- Irrigation:Agricultural and golf course pumping applications favor propane configurations where municipal clean-air procurement mandates apply.
Unit leadership belongs to Outdoor Power Equipment; the fastest climb occurs in Landscaping fleet digitization.
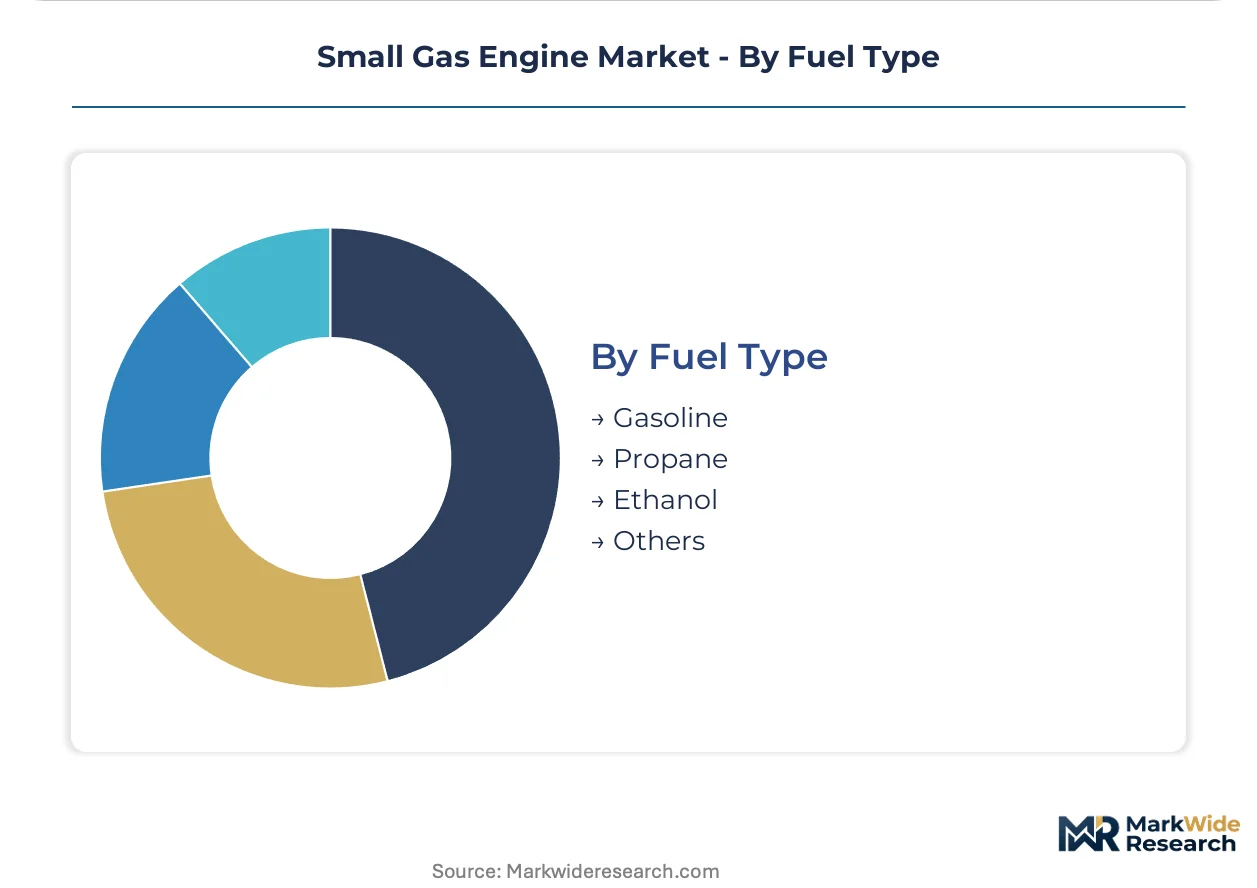
Fuel Type:
Procurement regulations and infrastructure availability shape adoption trajectories across metropolitan and rural geographies.
- Gasoline:Dominates unit volume with established distribution infrastructure and equipment compatibility across all displacement categories. CARB certification requirements drive reformulated gasoline and sealed fuel system designs for evaporative control.
- Propane:Gaining share in municipalities with clean-air procurement mandates in California, Colorado, and Texas. Dual-fuel configurations allow fleet operators to switch between gasoline and propane based on fuel availability and emissions zone requirements.
- Ethanol:E10 and E15 blends require fuel system materials compatibility for seal and gasket longevity in small-displacement architectures.
- Others:Compressed natural gas and hybrid configurations serve niche applications in institutional fleets with captive fueling infrastructure.
Gasoline retains volume dominance; propane gains share fastest in regulated municipal procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in industrial manufacturing clusters across Germany, Japan, China, and the United States, while consumption patterns track landscaping service density and construction activity in North American and European markets.
United States
Commercial landscaping contractors across Florida, Texas, and Arizona are expanding equipment fleets to meet year-round lawn maintenance demand. EPA Phase 3 emissions standards under 40 CFR Part 90 and CARB small off-road engine rules force electronic fuel injection adoption. Sacramento, Denver, and Seattle municipal electrification ordinances threaten to fragment addressable demand in Western states.
Germany
Professional forestry equipment demand in Bavaria and Baden-Württemberg drives premium chainsaw engine procurement. EU Green Deal decarbonization targets and F-Gas Regulation compliance requirements shape clean-air procurement mandates. Stuttgart's industrial machinery cluster hosts precision engine component manufacturing for export across European landscaping markets.
China
Domestic construction equipment demand in Guangdong and Jiangsu provinces sustains generator engine production volumes. MIIT emission standards and GB compliance frameworks for small off-road engines tighten manufacturing specifications. Chongqing's motorcycle and small engine manufacturing corridor supplies cost-competitive units for emerging market export.
Japan
Compact engine demand for precision agricultural equipment in Hokkaido and Tohoku regions supports specialized displacement categories. METI energy efficiency standards and JIS certification requirements enforce quality benchmarks for domestic and export-bound production. The Nagoya industrial belt concentrates precision casting and overhead valve component manufacturing.
Canada
Seasonal landscaping contractors in Ontario and British Columbia drive gasoline engine demand for summer-intensive equipment utilization. Health Canada and PMRA environmental regulations align with US EPA frameworks for cross-border engine certification compatibility. Toronto's equipment distribution hub channels imports for Prairie Provinces agricultural and construction applications.
Small Gas Engine Market Key Industry Players
Capital-heavy producers compete with asset-light designers across foundry-dependent and assembly-focused business models. The market structures around three tiers: integrated engine-equipment manufacturers, standalone powertrain specialists, and regional fabrication shops serving replacement markets. Strategic archetypes include warranty-network differentiators, fleet-software integrators, and commodity displacement competitors. Dominant competitive moves encompass dealer network consolidation and telematics platform development for usage-based service monetization.
Among integrated Japanese manufacturers, Yamaha Motor, Kawasaki Heavy Industries, and Honda Motor occupy positions spanning marine, powersports, and outdoor power equipment verticals. These Tokyo and Hamamatsu-based corporations exemplify the premium-tier archetype through captive distribution and extended warranty infrastructure. Their scale allows parallel compliance with EPA, CARB, and domestic emission frameworks without product line fragmentation.
| Leading Market Players |
|---|
| Yamaha Motor |
| Kawasaki Heavy Industries |
| Briggs & Stratton |
| STIHL |
| Kubota |
| Honda Motor |
| Generac Holdings |
| Subaru |
| Kohler |
| Others |
Cost & Logistics Intelligence
Precision casting specialists in Japan's Nagoya industrial belt command wage premiums that propagate through three-tier pricing spreads across premium, standard, and economy engine tiers. Labor-cost differentials between Japanese precision manufacturers and Chinese foundry operations create pricing-tier spreads that OEMs exploit through geographic sourcing arbitrage.
Pricing Analysis
Margin tightening in economy-tier engines traces to aluminum block cost volatility and compressed certification timelines under EPA 40 CFR Part 90. Three-tier pricing structure across premium, standard, and economy levels stratifies by electronic fuel injection adoption and warranty-network density. Honda Motor and Yamaha Motor anchor premium positioning through certified technician training infrastructure, while price-sensitive residential purchasers drive commoditization pressure below 150cc displacement.
Supply Chain Analysis
Domestic-content mandates in China's MIIT emission compliance frameworks are reshaping sourcing patterns for crankcase castings and overhead valve components. Manufacturing gravity centers on Japan, China, and Germany for precision-machined blocks, with aluminum ingot supply tethered to Australian bauxite and Chinese smelter output. Single-source vulnerability concentrates in Japanese bearing and seal suppliers, while distribution runs through captive dealer networks and independent equipment retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around emissions-compliant electronic fuel injection capacity as EPA Phase 3 certification costs force sub-scale fabricators toward exit. Regulatory compliance burdens favor integrated manufacturers with parallel CARB and EPA testing infrastructure.
For Market Incumbents: Acquire telematics platform capabilities to bundle usage-based maintenance contracts with engine sales. Briggs & Stratton's dealer-network bundling and STIHL's fleet-management software demonstrate defensive moats against battery-electric substitution in commercial landscaping segments. Backward integration into aluminum foundry capacity insulates margin from raw material volatility.
For New Entrants and Emerging Players: Direct-to-contractor digital channels offer lowest-friction entry into propane dual-fuel configurations for California and Colorado municipal procurement. Clean-air mandates in Sun Belt states create white-space demand for alternative-fuel architectures underserved by incumbent gasoline-focused portfolios. Target agricultural irrigation pump applications where propane infrastructure buildout lags behind municipal fleet adoption.
For Investors and Strategic Acquirers: Re-rating potential sits with telematics-integrated engine specialists given subscription revenue attachment rates in commercial landscaping fleets. Five-to-ten-year viability favors manufacturers with captive EFI calibration capabilities and CARB certification infrastructure. Monitor state-level preemption litigation over municipal gas-engine bans as inflection indicator for addressable demand geography.
| Strategic Initiative | Industry Significance |
|---|---|
| Electronic Fuel Injection Platform Standardization | EPA Phase 3 compliance locks in EFI architectures across 25cc-750cc displacement ranges. |
| Fleet-Management Software Integration | STIHL's captive usage-tracking creates recurring revenue attachment in professional landscaping. |
| Propane Dual-Fuel Certification Investment | CARB and Texas clean-air procurement mandates favor dual-fuel engine configurations. |
| Dealer Network Consolidation | Briggs & Stratton's service-contract bundling compresses independent distributor margins. |
| Extended Warranty Infrastructure Buildout | Honda Motor's certified technician training differentiates premium positioning against price competitors. |
Research Approach
Multi-period observation of equipment replacement cycles and emissions certification timelines anchored the trend analysis, supplemented by interviews with commercial landscaping fleet managers, small engine manufacturing engineers, EPA compliance officers, and dealer network operators. Secondary validation drew from EPA 40 CFR Part 90 filings, CARB executive orders, SEC 10-K disclosures from listed engine manufacturers, and customs trade data on aluminum casting imports. Bottom-up unit shipment modeling triangulated against top-down equipment OEM procurement estimates.
Segment-weighting across product type, end user, application, and fuel type dimensions structured volume and value outputs across the analysis window. CAGRs derived from replacement-frequency modeling by utilization intensity tier and seasonal runtime patterns. Forecast inputs incorporated municipal electrification ordinance tracking and propane infrastructure development databases.
Inputs from EPA certification filings and equipment OEM procurement surveys were available through the study window; gaps in real-time fleet telematics utilization data introduce uncertainty bands around subscription revenue attachment rate assumptions. Forecasts reflect documented assumptions regarding regulatory preemption outcomes and battery-electric substitution velocity in handheld segments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Continuous Variable Transmission Market
Powertrain
Car Oil Filter Market
Powertrain
Automotive Drivetrain Market
Powertrain
Torque Converter Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Global Industrial Turbocharger Market
Powertrain
Automotive Coil Spring Market
Powertrain
Automatic Transmission Torque Converter Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Power Assisted Steering Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Automotive Carburetor Market
Powertrain
Automotive Power Modules Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Automotive Driveline Market