
 Gas Engine Market | 2026-2036
Gas Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Engine Market Intelligence
Aftermarket service and digital monitoring contracts are rewriting the competitive positioning of original equipment manufacturers. Wärtsilä Corporation leverages its extensive installed base to secure long-term power plant operational agreements. Caterpillar Inc. differentiates through its global dealer network for parts and service support, while INNIO specializes in high-efficiency engines for cogeneration and biogas applications.
A gas engine is an internal combustion engine that runs on a gaseous fuel, such as natural gas, biogas, or hydrogen blends. These engines often operate on a lean burn principle to maximize efficiency and reduce NOx emissions, with power outputs ranging from kilowatts to over 20 megawatts. Reciprocating engines continue to dominate the market due to their versatility and wide power range. The power generation application segment is expanding rapidly, driven by the need for grid balancing and distributed energy solutions.
Emissions standards set by the US Environmental Protection Agency (EPA) and the European Union's Industrial Emissions Directive dictate engine design and after-treatment requirements. China's 'dual carbon' goals are accelerating the adoption of high-efficiency gas engines over coal for industrial power. Consequently, manufacturers must navigate a complex landscape of regional emissions rules while preparing for future fuel flexibility, including hydrogen blends.
Market Dynamics
The central tension between decarbonization mandates and the critical need for grid reliability is shaping the gas engine market. This dynamic favors flexible, fast-ramping engines for distributed power and balancing intermittent renewables, particularly as they adapt to future hydrogen blends.
Growth Catalysts
- EU Green Deal Implementation:The policy's emphasis on energy efficiency drives investment in high-efficiency combined heat and power (CHP) gas engines, replacing older, less efficient assets in industrial and municipal applications across member states.
- Data Center Expansion:Unrelenting growth in data center construction, especially in the United States, requires highly reliable backup power systems, creating a concentrated demand source for large-scale gas engine generator sets.
- Biogas Utilization Incentives:Government support for waste-to-energy projects in agriculture and wastewater sectors promotes the adoption of specialized engines designed to operate efficiently on biogas and other low-calorific value gaseous fuels.
Market Restraints
- Battery Storage Competition:The rapidly declining cost and performance improvements of Battery Energy Storage Systems (BESS) present a direct substitution threat for gas engines in short-duration grid services and peak shaving applications.
- Methane Slip Regulations:Increasingly stringent limits on unburnt methane emissions, a potent greenhouse gas, necessitate complex after-treatment systems or advanced combustion designs that increase the total cost of engine ownership.
- Natural Gas Price Volatility:Geopolitical events and supply-demand imbalances create significant fluctuations in natural gas prices, impacting the operational cost-effectiveness of gas engines and creating long-term financial uncertainty for project developers.
Strategic Opportunities
- Hydrogen-Ready Engine Development:Engineering engines capable of operating on high-percentage hydrogen blends offers a pathway to future-proof assets, aligning with long-term decarbonization roadmaps in markets like Germany, Japan, and South Korea.
- Grid Balancing Services:The proliferation of intermittent renewable energy sources creates a distinct market for fast-starting gas engines to provide essential ancillary services such as frequency regulation and spinning reserve to maintain grid stability.
- Southeast Asian Industrialization:Rapid industrial growth combined with underdeveloped grid infrastructure in nations like Vietnam and Indonesia presents a substantial opportunity for distributed power generation solutions using natural gas engines.
Industry Challenges
- Navigating Regional Emissions Rules:Manufacturers face significant engineering and compliance costs to design platforms that meet a complex patchwork of disparate standards, from the US EPA's Tier requirements to the EU's Industrial Emissions Directive.
- Supply Chain Resilience:Securing a stable supply of critical components like advanced electronic controls and high-temperature alloys, often sourced from geopolitically sensitive regions, is a persistent operational challenge for engine manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Engine Market |
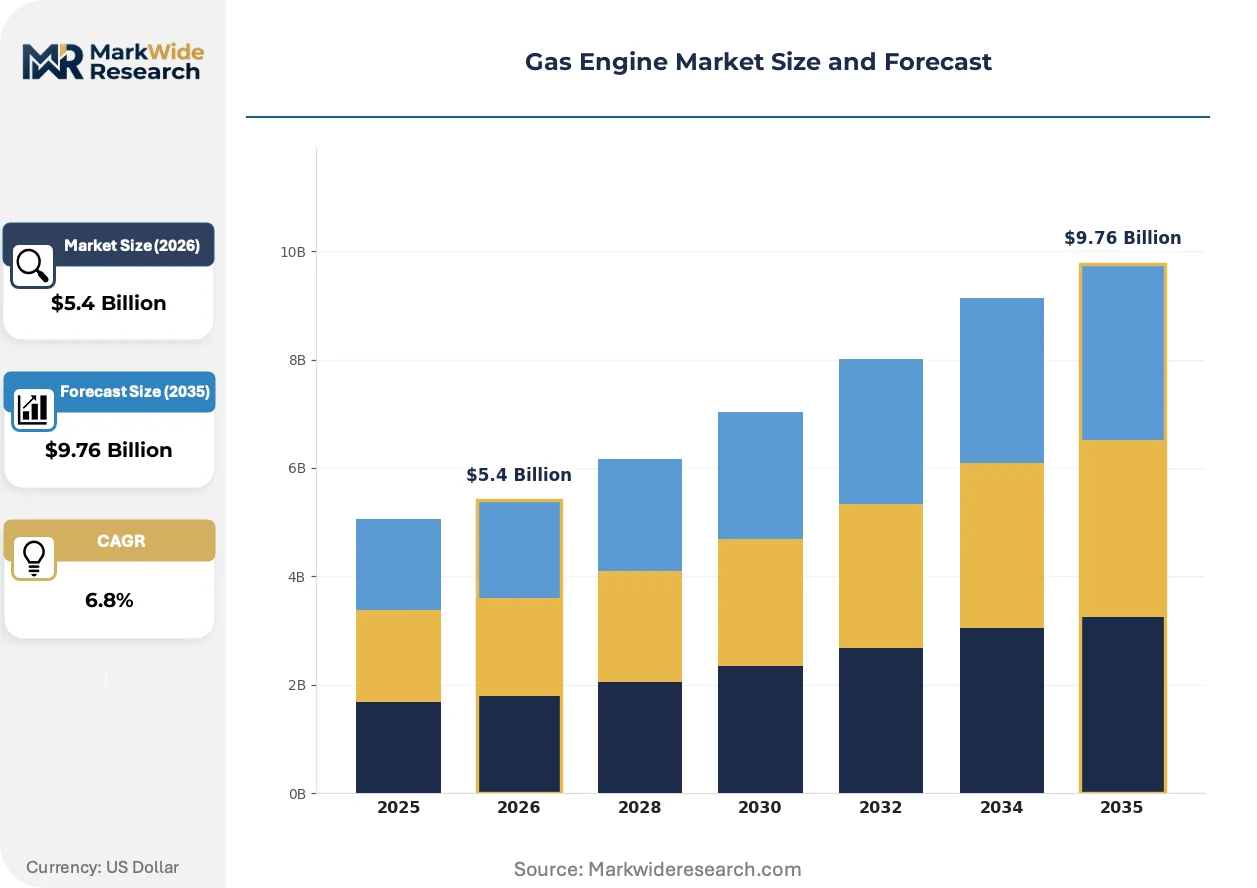
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating Engines, Rotary Engines, Turbine Engines, Dual Fuel Engines Technology: Lean Burn, Spark Ignition, Compression Ignition, Stoichiometric Combustion Application: Power Generation, Agriculture Equipment, Construction Machinery, Marine Propulsion End User: Power Plants, Farming Operations, Building Contractors, Shipping Companies |
| Companies Covered | Wärtsilä Corporation, MTU Friedrichshafen GmbH, Caterpillar Inc., Kawasaki Heavy Industries, Ltd., INNIO, Cummins Inc., MAN Energy Solutions SE, Mitsubishi Heavy Industries, Ltd., General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Engine Market Strategic Shifts & Innovations
Fuel flexibility and digital integration define the market's current trajectory. Engine designs are adapting to accommodate new gaseous fuels like hydrogen blends, while remote monitoring and data analytics are transforming operational service models and enhancing asset performance.
Lean-burn combustion technology optimizes the air-fuel mixture to maximize thermal efficiency while minimizing NOx formation in modern gas engines. Power generation operators and industrial combined heat and power users are adopting these systems to comply with stringent air quality regulations. Consequently, engine design philosophy is migrating from a singular focus on power density to a balanced approach emphasizing efficiency, emissions, and fuel tolerance.
China's 'dual carbon' policy framework is accelerating the replacement of coal-fired boilers with high-efficiency gas engine systems in industrial zones. This national strategy drives investment in distributed energy infrastructure and mandates cleaner power generation sources. The industrial power segment in coastal provinces is most affected, with operators prioritizing engine systems optimized for high-efficiency cogeneration applications.
A shift from outright equipment sales to long-term operational agreements is gaining traction for large power plant projects. This service-based model bundles the engine with comprehensive maintenance and performance guarantees, managed directly by the original equipment manufacturer. The trend is most visible in the multi-megawatt power generation sector, where asset uptime and predictable operational expenditures are critical for project bankability.
Gas Engine Market Segmentation
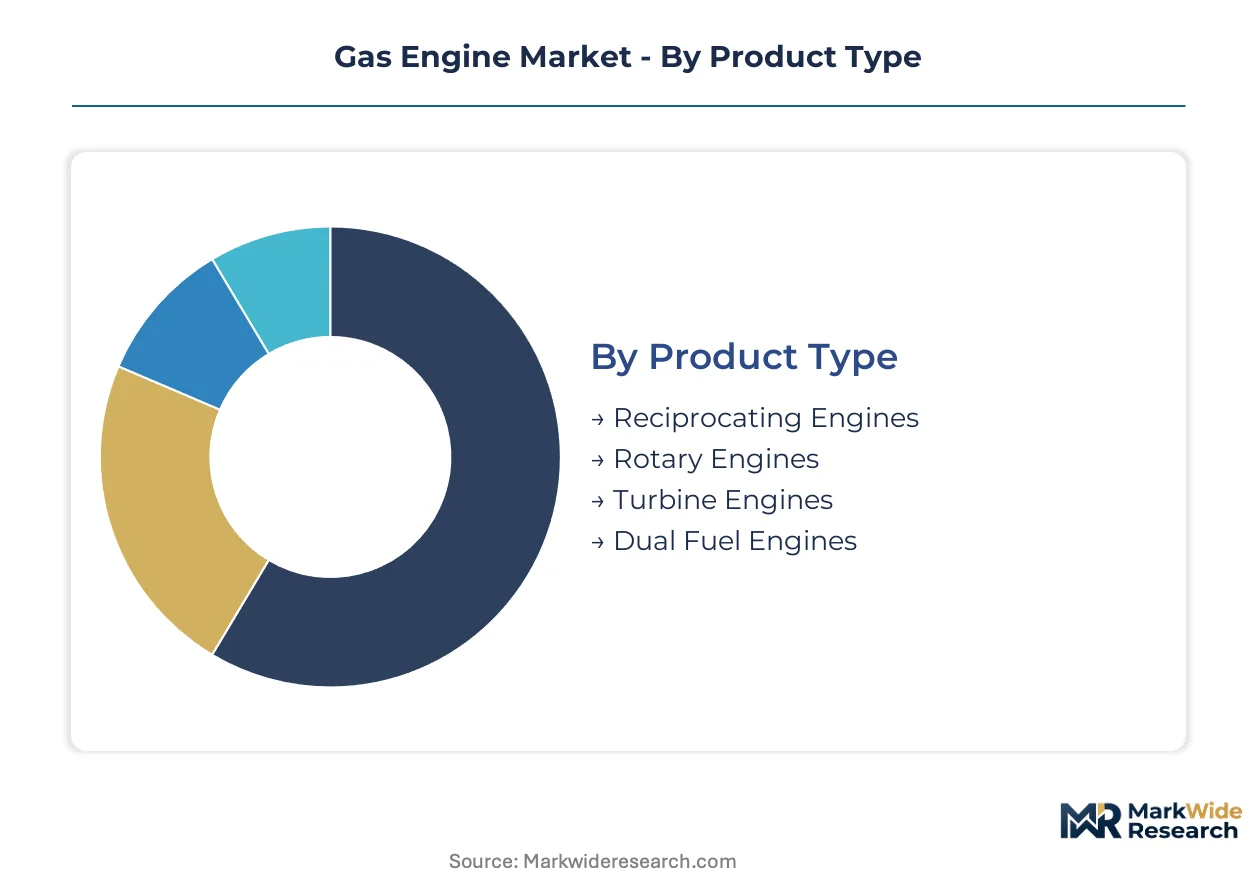
Understanding the Gas Engine Market through detailed segmentation reveals distinct growth vectors and technological preferences across various applications. Each segment possesses unique operational requirements and regulatory pressures influencing design and adoption. This granular view helps identify specific opportunities for product development and market penetration strategies.
Product Type:
The product type segmentation highlights the maturity spectrum of engine designs, from established piston-driven systems to emerging fuel-flexible solutions. Engine manufacturers continually innovate to enhance efficiency and reduce emissions across these diverse configurations.
- Reciprocating Engines:These internal combustion engines utilize pistons to convert gaseous fuel energy into mechanical power, dominating the market due to their proven reliability and broad power range. Demand concentrates in power generation and industrial combined heat and power applications, driven by the need for versatile and scalable energy solutions.
- Dual Fuel Engines:Capable of operating on both gaseous fuels (like natural gas or hydrogen blends) and liquid fuels, these engines offer critical operational flexibility and future-proofing against fuel availability shifts. Grid balancing services and distributed energy projects increasingly demand these adaptable systems to manage intermittent renewable power.
- Rotary Engines:Characterized by a triangular rotor that orbits within a specially shaped housing, these engines offer high power-to-weight ratios for niche applications such as unmanned aerial vehicles.
- Turbine Engines:These continuous combustion engines convert gaseous fuel into rotational energy through a turbine, primarily used in large-scale power generation and certain industrial processes requiring high power output.
Reciprocating Engines retains volume leadership; Dual Fuel Engines holds the steepest expansion curve.
Technology:
Technology segmentation explores the primary combustion methods employed in gas engines, each optimized for different performance characteristics and emission profiles. Efficiency drivers and regulatory mandates heavily influence the adoption of specific combustion technologies.
- Lean Burn:This technology operates with a high air-to-fuel ratio, leading to lower combustion temperatures and significantly reduced nitrogen oxide (NOx) emissions, making it ideal for stringent air quality regions. Combined heat and power (CHP) plants and grid balancing facilities frequently adopt lean burn engines for their high thermal efficiency and environmental compliance.
- Spark Ignition:Utilizing a spark plug to initiate combustion of the air-fuel mixture, this is a widely adopted and reliable technology for natural gas engines across various power outputs. Distributed power generation and industrial applications in the United States rely on spark ignition engines for their robust performance and established operational history.
- Compression Ignition:These engines ignite fuel through the heat generated by compressing air, traditionally associated with diesel but adaptable for gaseous fuels with pilot injection. Heavy-duty applications and certain industrial sectors value their robust construction.
- Stoichiometric Combustion:This method involves a precise air-to-fuel ratio for complete combustion, often paired with three-way catalytic converters to simultaneously reduce NOx, carbon monoxide, and unburnt hydrocarbons. Specific emission regulations in urban areas drive demand for these systems.
Efficiency gains are central to Lean Burn, while Spark Ignition offers broad operational flexibility.
Application:
The application segment delineates the primary uses of gas engines across diverse sectors, reflecting where demand concentrates for specific operational benefits. Demand concentration in each application drives tailored engine design and service offerings.
- Power Generation:This segment encompasses utility-scale power plants, distributed energy resources, and critical backup power systems, providing electricity for grids, industries, and commercial facilities. Data center expansion in the United States and grid stability requirements globally drive substantial demand for reliable power generation solutions.
- Marine Propulsion:Gas engines power a wide range of vessels, from cargo ships and tankers to ferries, increasingly utilizing liquefied natural gas (LNG) and dual-fuel systems to meet international emissions standards. International Maritime Organization (IMO) regulations and the pursuit of lower operational costs are accelerating adoption in global shipping lanes.
- Agriculture Equipment:Gas engines are integrated into various farm machinery, irrigation systems, and on-site power generation units, particularly those fueled by biogas from agricultural waste. Government incentives for waste-to-energy projects in Europe support this application.
- Construction Machinery:Used in heavy equipment like excavators, loaders, and temporary power generators on construction sites, gas engines offer a cleaner alternative to diesel in urban environments. Infrastructure development projects in Southeast Asia require robust and efficient power sources.
The Power Generation segment drives significant market volume, with Marine Propulsion showing considerable expansion due to regulatory shifts.
End User:
This segmentation focuses on the types of organizations and entities that procure and operate gas engines, highlighting their distinct investment drivers and operational priorities. Operational scale and investment drivers shape the preferences of different end-user groups.
- Power Plants:These include utility companies, independent power producers, and industrial facilities operating large-scale electricity generation and combined heat and power (CHP) systems. Grid reliability mandates and the transition to cleaner energy sources are key investment drivers for power plant operators.
- Shipping Companies:Operators of commercial vessels, including container ships, bulk carriers, and cruise lines, invest in gas engines to comply with environmental regulations and optimize fuel costs. The global push for decarbonization in maritime transport shapes their purchasing decisions.
- Farming Operations:Individual farms and agricultural cooperatives utilize gas engines for on-site electricity generation, often leveraging biogas from animal waste, and for powering specialized farm machinery. Government support for sustainable agriculture influences equipment choices.
- Building Contractors:Companies involved in construction and infrastructure development deploy gas engines for temporary power supply, operating heavy machinery, and backup systems for new developments. Project timelines and site-specific power needs dictate equipment selection.
Large-scale energy infrastructure defines demand from Power Plants, while Shipping Companies navigates evolving environmental compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gas Engine Market exhibits distinct consumption patterns across geographies. While some regions prioritize grid reliability with robust backup systems, others focus on decarbonization through high-efficiency combined heat and power. This differential approach shapes regional demand for specific engine types and fuel flexibility solutions.
United States
Unrelenting data center expansion in the United States drives substantial demand for reliable backup power systems. The US Environmental Protection Agency (EPA) sets emissions standards that influence engine design and after-treatment requirements. Concentrated demand for large-scale gas engine generator sets is particularly visible in major tech hubs across California and Virginia.
Germany
The EU Green Deal's emphasis on energy efficiency drives investment in high-efficiency combined heat and power (CHP) gas engines in Germany. German policy supports hydrogen-ready engine development, aligning with long-term decarbonization roadmaps. Industrial and municipal applications in regions like Bavaria and North Rhine-Westphalia are actively replacing older, less efficient assets.
China
China's 'dual carbon' goals accelerate the replacement of coal-fired boilers with high-efficiency gas engine systems for industrial power. This national strategy mandates cleaner power generation sources and distributed energy infrastructure. The industrial power segment in coastal provinces, including Jiangsu and Guangdong, shows significant adoption of optimized cogeneration applications.
India
Rapid industrialization and an underdeveloped grid infrastructure in India present a substantial opportunity for distributed power generation solutions. The Indian government promotes gas-based power generation to meet rising energy demands and reduce reliance on coal. Industrial zones around Mumbai and Chennai are increasingly deploying natural gas engines to ensure stable power supply.
Japan
Japan's focus on energy security and grid stability creates a distinct market for fast-starting gas engines to provide essential ancillary services. The Ministry of Economy, Trade and Industry (METI) supports the development of hydrogen and ammonia co-firing technologies for power generation. Major utility companies in the Tokyo metropolitan area and Kansai region are investing in flexible gas engines for frequency regulation.
Gas Engine Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the Gas Engine Market. The industry features a tiered structure, with established global manufacturers competing alongside specialized regional players and technology-focused innovators. Strategic archetypes include integrated solution providers offering end-to-end power solutions and niche technology innovators focusing on specific fuel types or applications. Dominant competitive moves involve expanding global service networks and accelerating the development of future-proof fuel flexibility, particularly for hydrogen blends.
Within the integrated solution provider archetype, Wärtsilä Corporation and Caterpillar Inc. exemplify global reach and extensive service capabilities. Wärtsilä Corporation, a Finnish-based company, leverages its installed base for long-term operational agreements. Caterpillar Inc., a US-based manufacturer, differentiates through its vast global dealer network for parts and service support. Furthermore, INNIO, an Austrian-based specialist, occupies a position as a high-efficiency engine provider for cogeneration and biogas applications.
| Leading Market Players |
|---|
| Wärtsilä Corporation |
| MTU Friedrichshafen GmbH |
| Caterpillar Inc. |
| Kawasaki Heavy Industries, Ltd. |
| INNIO |
| Cummins Inc. |
| MAN Energy Solutions SE |
| Mitsubishi Heavy Industries, Ltd. |
| General Electric Company |
| Others |
Cost & Logistics Intelligence
Natural gas price volatility, influenced by geopolitical events, determines both pricing tier spreads and the supply chain shape for gas engine components. This volatility directly impacts operational costs for end-users, affecting their willingness to invest in new engine systems.
Pricing Analysis
Long-term operational agreements define the pricing model for large-scale power generation projects. Price differentiation stems from after-sales service bundles and customization levels for specific fuel types. Cost compression in the industrial segment is intensifying due to competition from alternative power solutions. Building contractors typically exhibit the most price-sensitive procurement behavior, while power plant operators prioritize reliability and long-term performance.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the procurement of high-value components within the gas engine market. Geographic supply concentration for critical components like advanced electronic controls and high-temperature alloys centers on Germany, Japan, and China. Single-source vulnerability for specialized castings presents a structural risk for manufacturers. Distribution runs primarily through established global dealer networks and direct sales channels to large power producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gas Engine Market presents a fragmentation opportunity, driven by diverse regional decarbonization mandates creating specialized demand niches.
For Market Incumbents: Entrench core market share by leveraging extensive installed bases to secure long-term service contracts. Invest heavily in hydrogen-ready engine development to future-proof product portfolios against evolving fuel standards. Address the threat from battery storage competition by emphasizing combined heat and power efficiency and grid balancing capabilities. Maintain channel control through robust global dealer networks and aftermarket support.
For New Entrants and Emerging Players: Specialized biogas engines for agricultural waste-to-energy projects represent a penetrable entry point, particularly with government incentives in Europe. Fast-ramping engines for grid balancing services in regions with high renewable penetration offer another white-space target. Focus on localized service partnerships and modular, scalable solutions to meet the needs of underdeveloped grid infrastructure in Southeast Asian industrialization. Offer differentiated after-treatment systems for methane slip reduction.
For Investors and Strategic Acquirers: The EU Green Deal's emphasis on energy efficiency reshapes the acquisition landscape, favoring companies with proven high-efficiency CHP technologies. The market demonstrates significant long-term viability over the next decade, driven by grid reliability needs and decarbonization efforts. Target specialized technology innovators focused on advanced combustion designs or hydrogen blend capabilities. The signal to watch is the pace of hydrogen infrastructure development in key markets like Germany and Japan.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Hydrogen-Ready Engine Development | Future-proofs assets against evolving fuel standards and decarbonization roadmaps. |
| Expand Long-Term Operational Agreements | Secures recurring revenue streams and leverages existing installed base for OEMs. |
| Target Biogas-Fueled Engine Solutions | Addresses waste-to-energy incentives and niche demand in agricultural sectors. |
| Strengthen Global Dealer and Service Networks | Enhances aftermarket support and ensures high asset uptime for end-users. |
| Develop Fast-Ramping Grid Balancing Engines | Captures opportunities from intermittent renewable energy integration and grid stability. |
Research Approach
A standing panel of power plant operators, engine R&D directors, EPC contractors, and maritime fleet managers provided ongoing calibration for market assumptions. This primary input was rigorously combined with secondary validation from sources including US EPA emissions reports, EU Industrial Emissions Directive documents, and national energy agency reports. Bottom-up and top-down triangulation ensured data consistency and comprehensive market sizing.
Scenario-bracketing framed the analytical framework, modeling market dynamics across the projection horizon. Segmentation dimensions included product type, technology, application, end-user, and regional regulatory clusters. Compound annual growth rates were derived from a synthesis of historical trends, regulatory impacts, and future outlooks. Natural gas price forecasts and renewable energy integration rates served as critical industry-specific forecast inputs.
Stress conditions across geopolitical events impacting natural gas supply and accelerated battery storage cost reduction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
High Speed Engine Market
Powertrain
Diesel Engine Management System Market
Powertrain
Racing Clutches Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Automotive Chain Tensioners Market
Powertrain
South America Automotive Market
Powertrain
Engine Cylinder Liners Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Exhaust System Muffler Market
Powertrain
Mexico Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Camless Engine Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Automotive Engine Market