
 Automotive Fan Clutch Market | 2026-2036
Automotive Fan Clutch Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fan Clutch Market Analysis
Aftermarket refurbishment revenue is reshaping margin distribution across the automotive fan clutch value chain. BorgWarner Inc. leverages its integrated thermal systems portfolio to capture recurring service demand from North American heavy-duty fleets. Horton Holding, Inc. anchors its position through viscous clutch specialization and direct OEM supply relationships with major truck manufacturers. Valeo Group competes on electromagnetic actuator technology, extending its reach into European electric vehicle thermal modules.
An automotive fan clutch is a temperature-responsive coupling device that modulates cooling fan engagement relative to engine thermal load, typically employing bimetallic sensors, silicone fluid chambers, or pulse-width-modulated solenoids to achieve engagement differentials. Its primary commercial purpose is to reduce parasitic engine drag, improve fuel efficiency, and prevent thermal damage in internal combustion powertrains operating across variable duty cycles. Electric operating mechanisms are gaining fastest penetration as 48V mild-hybrid architectures proliferate, while viscous designs sustain dominant share in cost-sensitive commercial vehicle segments. OEM end users command the largest volume channel, though aftermarket demand for aluminum-bodied replacement units generates superior per-unit margins due to expedited fulfillment requirements.
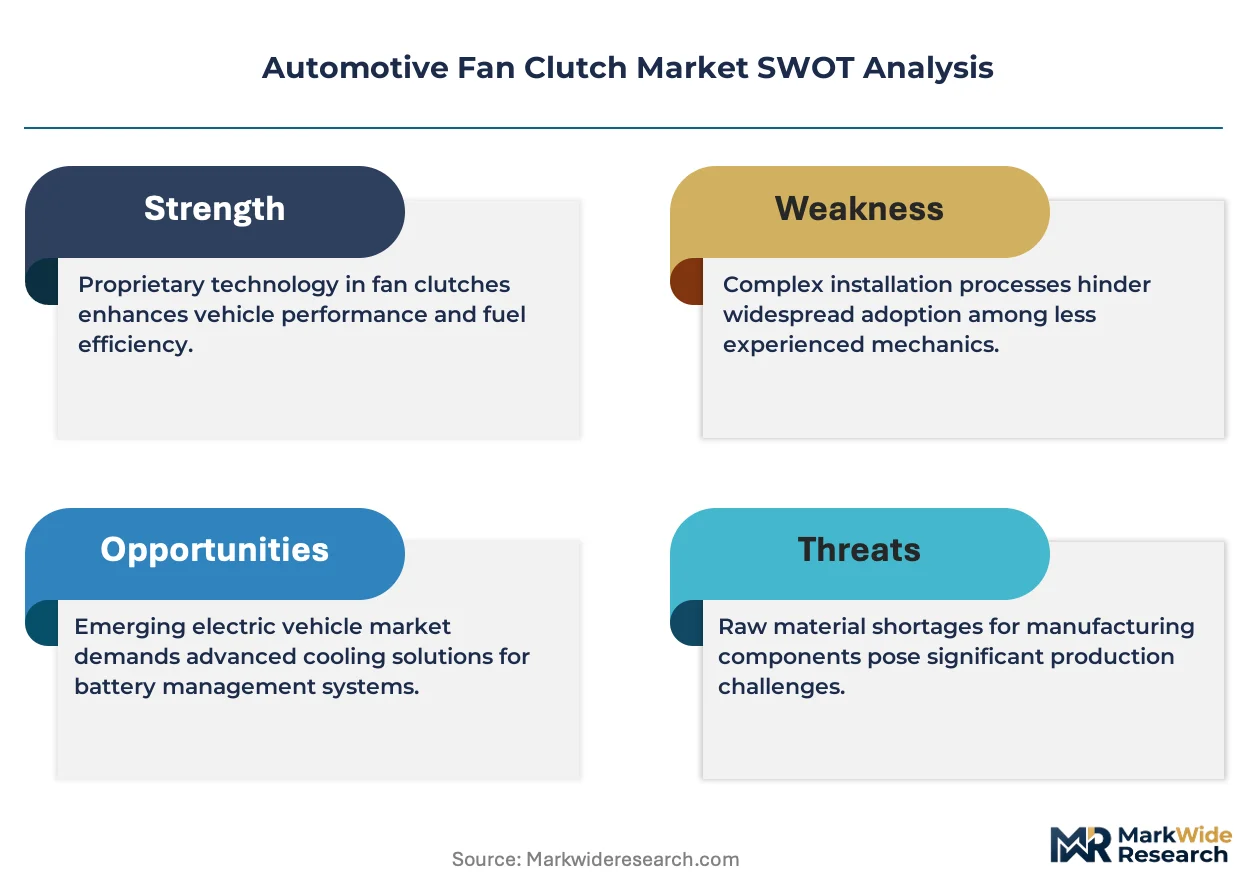
EPA Phase 3 standards and NHTSA fuel economy rules are tightening thermal management specifications for heavy-duty engines, compelling redesigns that favor electronically modulated fan clutches over legacy mechanical designs. ISO 26262 functional safety requirements are additionally shaping electromagnetic clutch validation protocols for integration with engine control modules. Stakeholders must monitor electrification transition velocity in commercial vehicle segments, as battery thermal management architectures may displace conventional engine-driven cooling systems faster than current platform roadmaps assume.
Market Dynamics
Electronically modulated fan clutches are displacing viscous mechanical designs as EPA Phase 3 standards force precision thermal management into heavy-duty engine architectures. This technology transition concentrates procurement leverage with Tier 1 thermal systems integrators capable of delivering pulse-width-modulated solenoid packages validated to ISO 26262 functional safety protocols.
Growth Catalysts
- EPA Phase 3 Standards:NHTSA fuel economy mandates for heavy-duty engines compel OEM redesign cycles that favor electronically controlled fan clutches over legacy bimetallic designs.
- 48V Mild-Hybrid Architectures:Commercial vehicle electrification roadmaps are accelerating demand for electric operating mechanisms capable of seamless integration with belt-starter-generator systems.
- Aftermarket Refurbishment Concentration:United States-based Class 8 truck fleets generate recurring revenue streams from aluminum-bodied replacement units requiring expedited fulfillment.
Market Restraints
- Silicone Fluid Cost Volatility:Viscous clutch manufacturers face margin compression from petrochemical feedstock price swings affecting silicone oil chamber production.
- Electrification Substitution Threat:Battery thermal management architectures in commercial electric vehicles may displace engine-driven cooling systems faster than incumbent platform roadmaps anticipate.
- Supply Concentration in Precision Machining:North American aluminum die-casting capacity constraints limit rapid scaling of electronically actuated clutch housings.
Strategic Opportunities
- European Electric Vehicle Thermal Modules:Electromagnetic actuator technology developed for internal combustion applications transfers directly to battery cooling circuits in EV architectures.
- India Commercial Vehicle Emission Norms:Bharat Stage VI Phase 2 implementation creates first-mover advantage for suppliers offering electronically modulated fan clutches to domestic truck manufacturers.
- Telematics-Enabled Predictive Maintenance:Integration with fleet management platforms allows clutch health monitoring to shift replacement demand from reactive breakdown toward scheduled optimization.
Industry Challenges
- ISO 26262 Validation Timelines:Electromagnetic clutch electromagnetic compatibility certification for engine control module integration extends development cycles by 12-18 months.
- Legacy Mechanical Inventory Stranding:Distributors holding viscous clutch stock face write-down risk as OEM procurement shifts abruptly toward electronic architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fan Clutch Market |
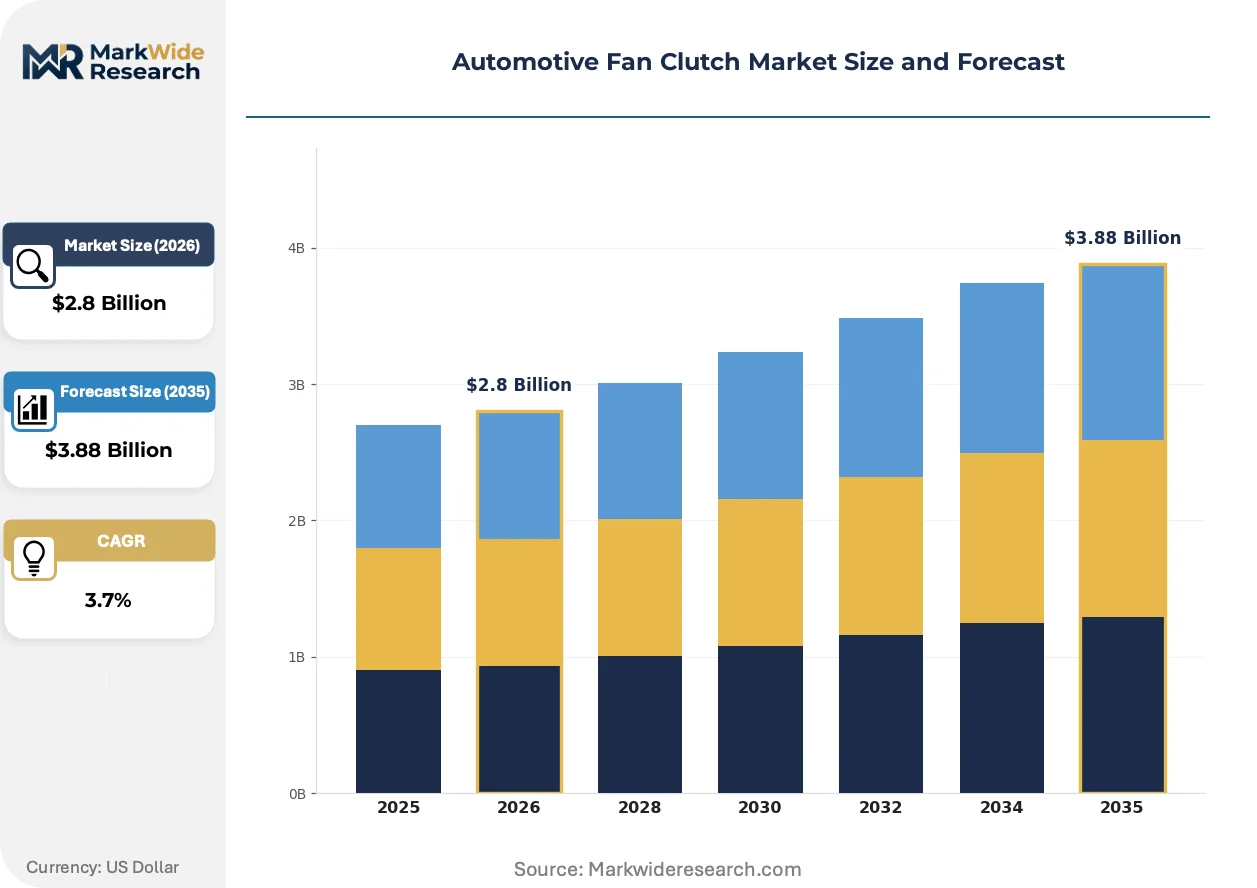
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.88 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Variable Speed, Mechanical, Electric, Pneumatic End User: OEMs, Aftermarket, Commercial Vehicles, Passenger Vehicles Material: Aluminum, Steel, Plastic, Composite Operating Mechanism: Viscous, Electromagnetic, Hydraulic, Belt Driven |
| Companies Covered | BorgWarner Inc., Horton Holding, Inc., Hayden Automotive, Aisin Corporation, Eaton, Mahle GmbH, GMB North America, Inc., Valeo Group, HYTEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fan Clutch Market Emerging Trajectories
Thermal management architectures are fragmenting across powertrain electrification pathways. Fan clutch suppliers must now engineer for three simultaneous transitions: mechanical-to-electronic actuation, engine-driven-to-electric cooling, and fixed-speed-to-variable thermal response.
Silicone fluid viscosity modulation is hybridizing with electronic control interfaces to create semi-active clutch systems. Class 8 truck OEMs in the United States are piloting these hybrid architectures for 2027 model year platforms. The technology is hybridizing cost structures between premium electromagnetic units and commodity viscous designs, compressing mid-tier supplier margins.
EPA Phase 3 greenhouse gas standards and NHTSA fuel economy rules are tightening thermal management specifications for heavy-duty engines. OEM engineering teams must redesign cooling circuits to minimize parasitic drag during low-load operation. Heavy-duty diesel powertrains operating in long-haul freight corridors face the most stringent compliance timelines.
Fleet procurement departments are consolidating supplier relationships around integrated thermal system providers capable of single-source accountability. Direct OEM supply contracts are displacing fragmented multi-vendor arrangements for fan clutch modules. This concentration is most visible among United States-based commercial vehicle fleet operators managing thousand-unit tractor deployments.
Automotive Fan Clutch Market Segmentation
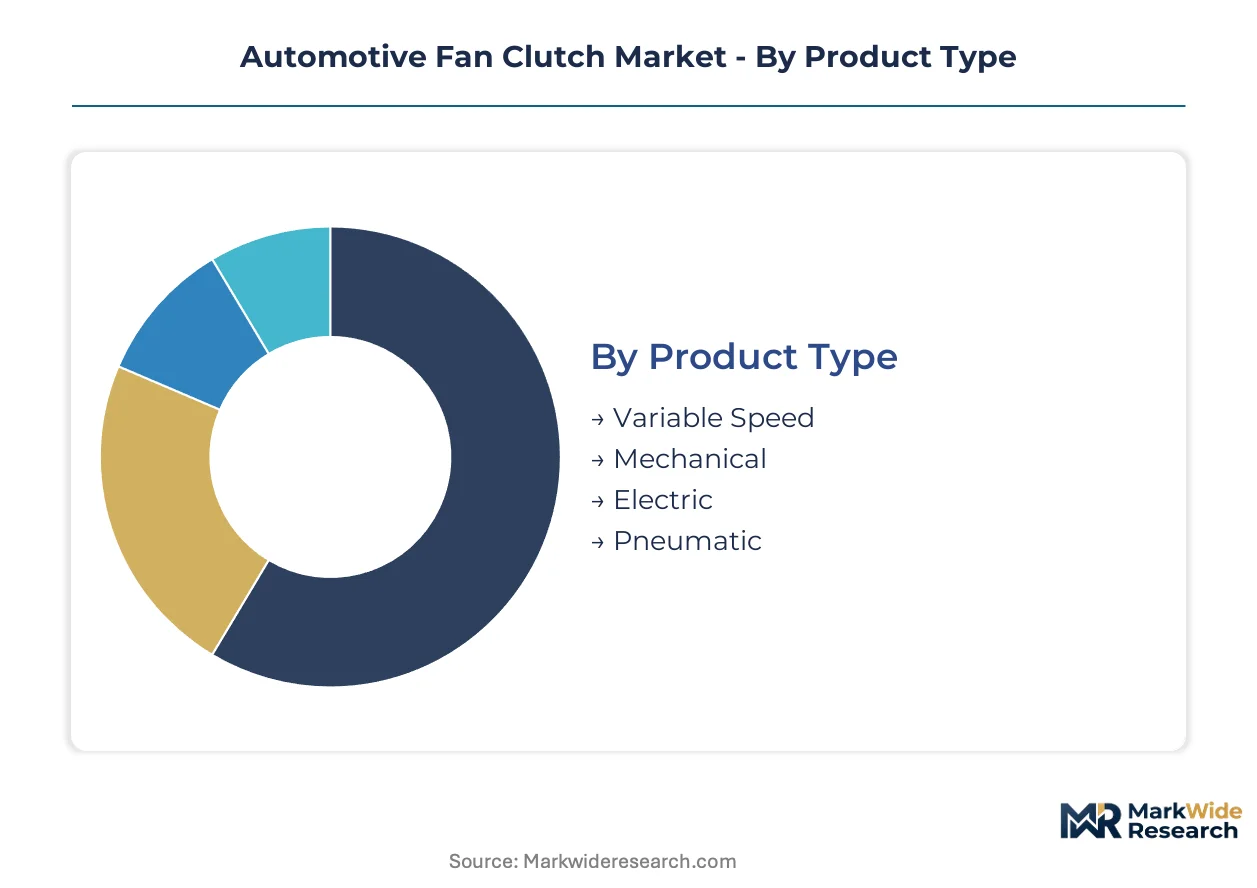
Automotive fan clutch procurement patterns diverge sharply between first-fit OEM contracts and aftermarket refurbishment cycles. Material specifications and actuation technologies determine service intervals, warranty exposure, and margin capture across distinct thermal management architectures.
Product Type:
After-sales service intensity varies dramatically across actuation technologies, with electronic variants demanding specialized diagnostic capabilities while mechanical designs support broader installer bases.
- Variable Speed:Pulse-width-modulated engagement enables continuous thermal load matching rather than binary on-off cycling. United States-based Class 8 fleets specify these units for long-haul corridors where idle reduction delivers measurable fuel savings under EPA Phase 3 compliance windows.
- Mechanical:Bimetallic spring and silicone fluid architectures dominate cost-sensitive commercial vehicle segments with proven durability in high-vibration environments. Indian truck manufacturers under Bharat Stage VI Phase 2 procurement timelines favor these units for their field-service simplicity and minimal electronic integration requirements.
- Electric:Belt-starter-generator compatibility positions these clutches for 48V mild-hybrid architectures proliferating in European commercial vehicle platforms.
- Pneumatic:Compressed air actuation persists in legacy heavy-duty applications where pneumatic infrastructure already exists across vehicle subsystems.
Mechanical designs hold the largest share; momentum sits with variable speed units as precision thermal management becomes a regulatory compliance tool.
End User:
Volume concentration and margin structure invert across the value chain, with OEM contracts delivering scale but aftermarket channels capturing superior per-unit economics through expedited fulfillment premiums.
- OEMs:Direct supply relationships with truck manufacturers concentrate procurement leverage among integrated thermal system providers capable of single-source accountability for complete cooling modules.
- Aftermarket:Aluminum-bodied replacement units generate recurring revenue from United States fleet operators managing thousand-unit tractor deployments, with refurbishment demand cycling every 4-6 years based on duty severity.
- Commercial Vehicles:Heavy-duty diesel powertrains in freight corridors face the most stringent EPA Phase 3 thermal management specifications, forcing redesigns that favor electronically modulated engagement.
- Passenger Vehicles:Light-duty applications increasingly integrate fan clutches into broader thermal management modules as 48V electrification spreads through European and North American passenger car platforms.
OEMs command absolute volume; aftermarket channels are climbing the fastest as fleet telematics enable predictive replacement scheduling.
Material:
Die-casting capacity constraints and thermal conductivity requirements shape sourcing geography, with aluminum availability concentrated in specific manufacturing clusters.
- Aluminum:High thermal conductivity and corrosion resistance make this the default for electronically actuated housings where precision machining tolerances are critical. North American capacity limitations constrain rapid scaling of these components.
- Steel:Lower material costs and superior fatigue resistance sustain demand in mechanical clutch constructions for emerging market commercial vehicles.
- Plastic:Polymer housings penetrate cost-optimized passenger vehicle segments where thermal loads remain moderate.
- Composite:Hybrid material constructions target weight reduction initiatives in electric vehicle thermal modules where every kilogram affects range calculations.
Aluminum dominates value; composites represent the steepest expansion trajectory as battery thermal management architectures proliferate.
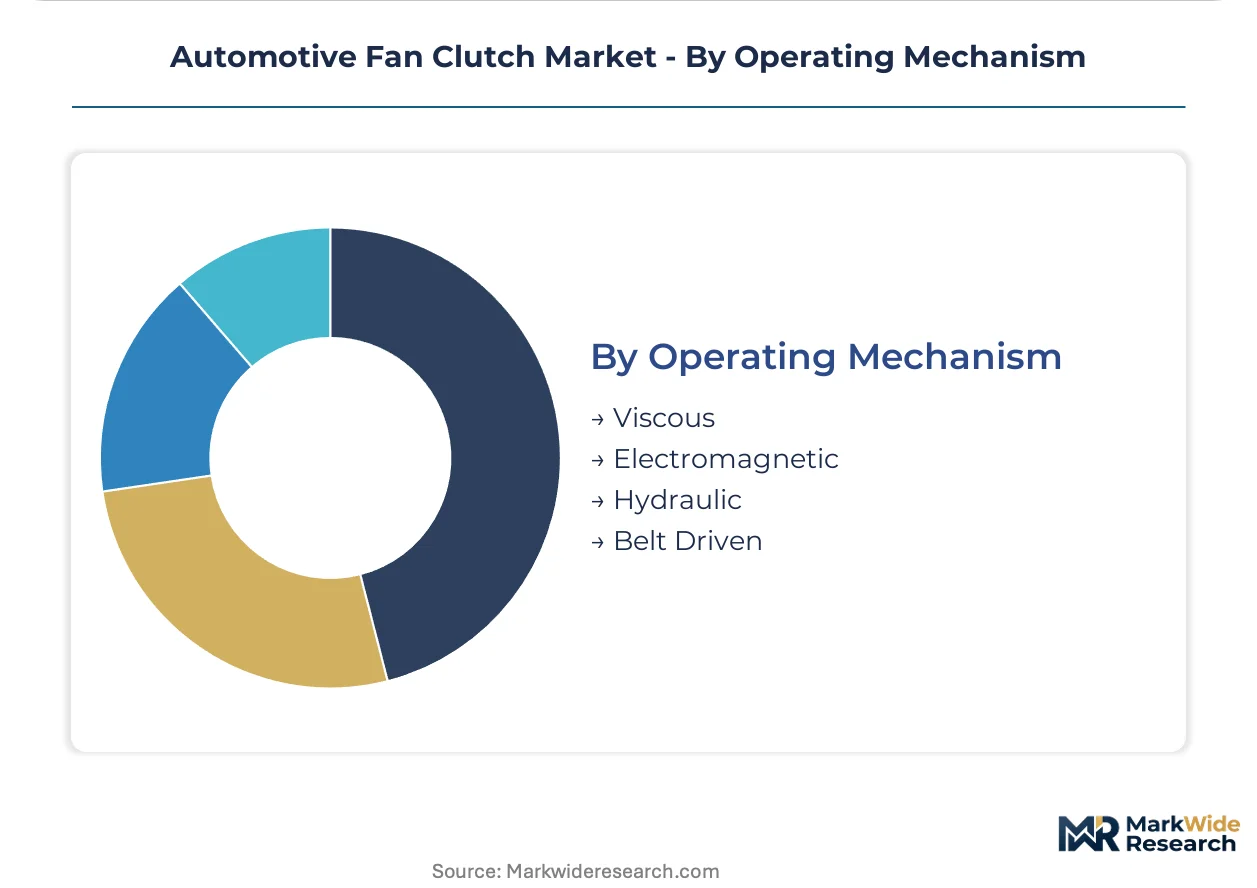
Operating Mechanism:
Validation timelines and functional safety certification requirements create divergent competitive moats across actuation technologies.
- Viscous:Silicone fluid shear coupling provides progressive engagement proportional to temperature differentials, with decades of field validation supporting commodity pricing in high-volume segments. Petrochemical feedstock volatility compresses margins unpredictably.
- Electromagnetic:Solenoid-actuated friction plates deliver instantaneous response for integration with engine control modules under ISO 26262 functional safety protocols. Development cycles extend 12-18 months for electromagnetic compatibility certification.
- Hydraulic:Pressurized fluid circuits persist in specialized off-highway equipment where hydraulic infrastructure is already pervasive.
- Belt Driven:Direct mechanical connection to crankshaft pulleys serves auxiliary cooling requirements in simplified powertrain architectures.
Viscous mechanisms retain volume leadership; electromagnetic systems are gaining share fastest as EPA Phase 3 standards force precision thermal management redesigns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for automotive fan clutches varies sharply by geography. United States fleet operators absorb premium pricing for electronically modulated units driven by regulatory compliance economics, while Indian commercial vehicle buyers prioritize field-service simplicity and minimal upfront cost.
United States
Class 8 truck production and aftermarket refurbishment activity concentrate demand in the Great Lakes and Southeast manufacturing corridors. EPA Phase 3 greenhouse gas standards for heavy-duty engines force OEM redesign cycles toward precision thermal management. Detroit and Columbus anchor supplier engineering operations serving thousand-unit fleet deployments.
Germany
Commercial vehicle electrification roadmaps accelerate demand for 48V mild-hybrid compatible fan clutch architectures. EU Green Deal decarbonization targets tighten thermal efficiency specifications for heavy-duty diesel powertrains. Stuttgart and Munich host integrated thermal system development for European truck manufacturers.
China
Domestic heavy-duty truck production scales drive volume procurement of cost-optimized mechanical fan clutch designs. MIIT fuel consumption standards for commercial vehicles mandate incremental thermal management improvements. Shandong and Hubei provinces concentrate aluminum die-casting capacity for clutch housing production.
India
Bharat Stage VI Phase 2 implementation creates procurement timelines favoring electronically modulated fan clutches for domestic truck manufacturers. The Central Pollution Control Board enforcement tightens emission compliance windows for commercial vehicle fleets. Tamil Nadu and Maharashtra automotive clusters integrate fan clutch sourcing into complete cooling module assemblies.
Mexico
Nearshoring of North American commercial vehicle component manufacturing expands precision machining demand for aluminum clutch housings. NOM-044-SEMARNAT emission standards align heavy-duty engine thermal management with US EPA benchmarks. Nuevo León and Bajío Region industrial parks attract Tier 1 thermal system suppliers serving cross-border OEM contracts.
Automotive Fan Clutch Market Vendor Landscape
Capability concentration sits with electromagnetic actuator specialists validated to ISO 26262 protocols; scale advantage sits with viscous clutch manufacturers serving high-volume mechanical replacement cycles. The market structures around three tiers: integrated thermal system providers, standalone clutch specialists, and regional aftermarket fabricators. Dominant competitive moves include backward integration into precision aluminum die-casting and technology licensing agreements spanning electronic control module integration.
Within the integrated thermal systems tier, BorgWarner Inc. and Valeo Group exemplify archetypes pursuing engine control module integration. Horton Holding, Inc. occupies a position among standalone clutch specialists emphasizing viscous mechanism field validation. Aisin Corporation anchors the precision manufacturing tier with captive aluminum casting operations. Mahle GmbH and Eaton represent diversified automotive suppliers leveraging thermal management portfolio breadth. Hayden Automotive and GMB North America, Inc. sit within aftermarket-focused fabricators serving expedited replacement demand.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Horton Holding, Inc. |
| Hayden Automotive |
| Aisin Corporation |
| Eaton |
| Mahle GmbH |
| GMB North America, Inc. |
| Valeo Group |
| HYTEC |
| Others |
Supply Flow & Price Mechanics
Shandong and Hubei provinces anchor aluminum die-casting capacity for clutch housing production, with their foundry utilization rates directly transmitting into Tier 1 supplier pricing power over North American OEM procurement teams.
Pricing Analysis
Long-term offtake contracts dominate OEM procurement, locking in volume commitments from integrated thermal system providers. Three-tier pricing structure across premium electromagnetic, standard hybrid, and economy mechanical levels reflects ISO 26262 certification tier and after-sales service bundling. Cost compression in viscous clutch segments is intensifying because silicone fluid feedstock volatility erodes margin buffers. Fleet operators managing thousand-unit deployments show lowest price sensitivity, while independent repair shops exhibit acute responsiveness to aluminum replacement unit fluctuations.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for aluminum housing sourcing. Precision machining draws from China, Mexico, and Germany, with petrochemical feedstock for silicone fluid resting on South Korean and Japanese chemical conglomerates. Single-source vulnerability concentrates in electromagnetic actuator solenoid packages validated to functional safety protocols. Distribution runs through captive Tier 1 logistics networks serving OEM assembly plants, with aftermarket channels feeding through regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive fan clutch procurement represents a defensive-moat market where EPA Phase 3 regulatory entrenchment creates multi-year switching costs for OEM platform engineering teams.
For Market Incumbents: Build certification moats by accelerating ISO 26262 validation investments ahead of 2027 model year platform locks. Backward integration into captive aluminum die-casting in Nuevo León insulates against tariff exposure. Electrification substitution threat demands electromagnetic actuator R&D prioritization over legacy viscous inventory accumulation. For New Entrants and Emerging Players: Establish a beachhead in Indian commercial vehicle aftermarket refurbishment under Bharat Stage VI Phase 2 procurement windows. White-space concentrates in telematics-enabled predictive maintenance modules for United States Class 8 fleets. Go-to-market leverage rests on direct OEM supply relationship cultivation with domestic truck manufacturers in Tamil Nadu and Maharashtra clusters. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EPA Phase 3 compliance timelines extend incumbent contract visibility through the projection horizon. Target acquisition archetype: electromagnetic actuator specialists with validated engine control module integration. Monitor battery thermal management architecture adoption velocity in commercial electric vehicle segments as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 Certification Acceleration | Validates electromagnetic clutches for EPA Phase 3 engine control integration. |
| Backward Integration into Aluminum Die-Casting | Captures Nuevo León capacity for tariff-resistant North American OEM supply. |
| Telematics-Enabled Predictive Maintenance | Shifts United States fleet replacement demand from reactive breakdown to scheduled optimization. |
| Electromagnetic Actuator Technology Licensing | Transfers internal combustion clutch expertise into European EV battery cooling modules. |
| Geographic Manufacturing Footprint Expansion | Positions production in Maharashtra to serve Bharat Stage VI Phase 2 domestic truck procurement. |
Methodological Framework
Operator-level perspectives from Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and fleet maintenance directors anchored the qualitative base. Primary fieldwork combined with secondary validation against vehicle production databases, EPA regulatory filings, IHS Markit registration data, and customs trade records. Bottom-up segment sizing and top-down macro triangulation cross-checked volume assumptions across the analysis window.
Scenario-bracketing framed the analytical approach, modeling demand trajectories across variable speed, mechanical, electric, and pneumatic product types by OEM, aftermarket, commercial vehicle, and passenger vehicle end users. CAGRs derived from segment-level growth rate reconciliation with propulsion architecture transition assumptions. Forecast inputs incorporated 48V mild-hybrid adoption curves and EPA Phase 3 compliance timeline rigidity.
Sensitivities concentrate around electrification substitution velocity in commercial vehicle segments and silicone fluid cost volatility. Forecasts reflect documented assumptions on platform redesign cycle timing and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Transmission Oil Filters Market
Powertrain
Automotive Hydraulic Lash Adjuster Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
CNG Powertrain Market
Powertrain
Electrically Powered Hydraulic Steering Market
Powertrain
Torque Limiter Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
Racing Clutches Market
Powertrain
Mexico Electrically Powered Hydraulic Steering Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Continuously Variable Transmission (CVT) Market