
 Automotive Engine Air Filter Market | 2026-2036
Automotive Engine Air Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Air Filter Market Analysis
Mexico is rewriting assembly-line sourcing patterns as automakers expand engine-component manufacturing near Guanajuato and Puebla. MANN+HUMMEL GmbH anchors European engineering standards through its R&D intensity in pleated-media systems. Donaldson Company competes on filtration efficiency ratings for severe-service commercial fleets. K&N Engineering specializes in reusable cotton-gauze designs that target performance aftermarket channels.
An automotive engine air filter is a pleated or woven porous element, typically constructed from cellulose paper, synthetic fiber blends, or oiled cotton gauze, designed to remove abrasive particulate matter from intake air before combustion. Its primary function is protecting cylinder walls, piston rings, and valve seats from silicon-dust erosion that degrades compression ratios and oil integrity. Panel filters dominate OEM fitments due to standardized form factors and low unit cost across passenger-car platforms. Synthetic media technology captures the fastest expansion as turbocharged engines demand higher dust-holding capacity at reduced flow restriction. Activated carbon layers add incremental margin pools in premium cabin-air segments where odor and VOC removal command price premiums.
EPA tailpipe and evaporative-emission rules in the United States tighten permissible particulate loads, forcing filter-efficiency upgrades that cascade into replacement-cycle acceleration. China MIIT enforces GB standards for intake-system integrity that align with dual carbon goals, while EMA in Europe monitors F-Gas Regulation interactions with HVAC-integrated filtration modules. Stakeholders must monitor how regulator convergence on nanoparticle filtration thresholds reshapes material-certification requirements and supplier qualification timelines.
Market Dynamics
Synthetic media filtration is compressing replacement cycles as turbocharged engines demand higher dust-holding capacity at reduced pressure drop, forcing substrate suppliers to recalibrate pleating geometries and resin formulations.
Growth Catalysts
- EPA particulate standards:Commercial fleets in the United States face mandatory filtration-efficiency upgrades that accelerate filter replacement frequency and expand addressable aftermarket volume.
- Turbocharger penetration:Downsized forced-induction powertrains require synthetic media with superior flow characteristics, pulling premium substrate demand across passenger-car and light-truck platforms.
- China MIIT GB standards:Dual carbon alignment mandates intake-system integrity certifications that disqualify low-efficiency imports and favor domestic pleated-media producers.
Market Restraints
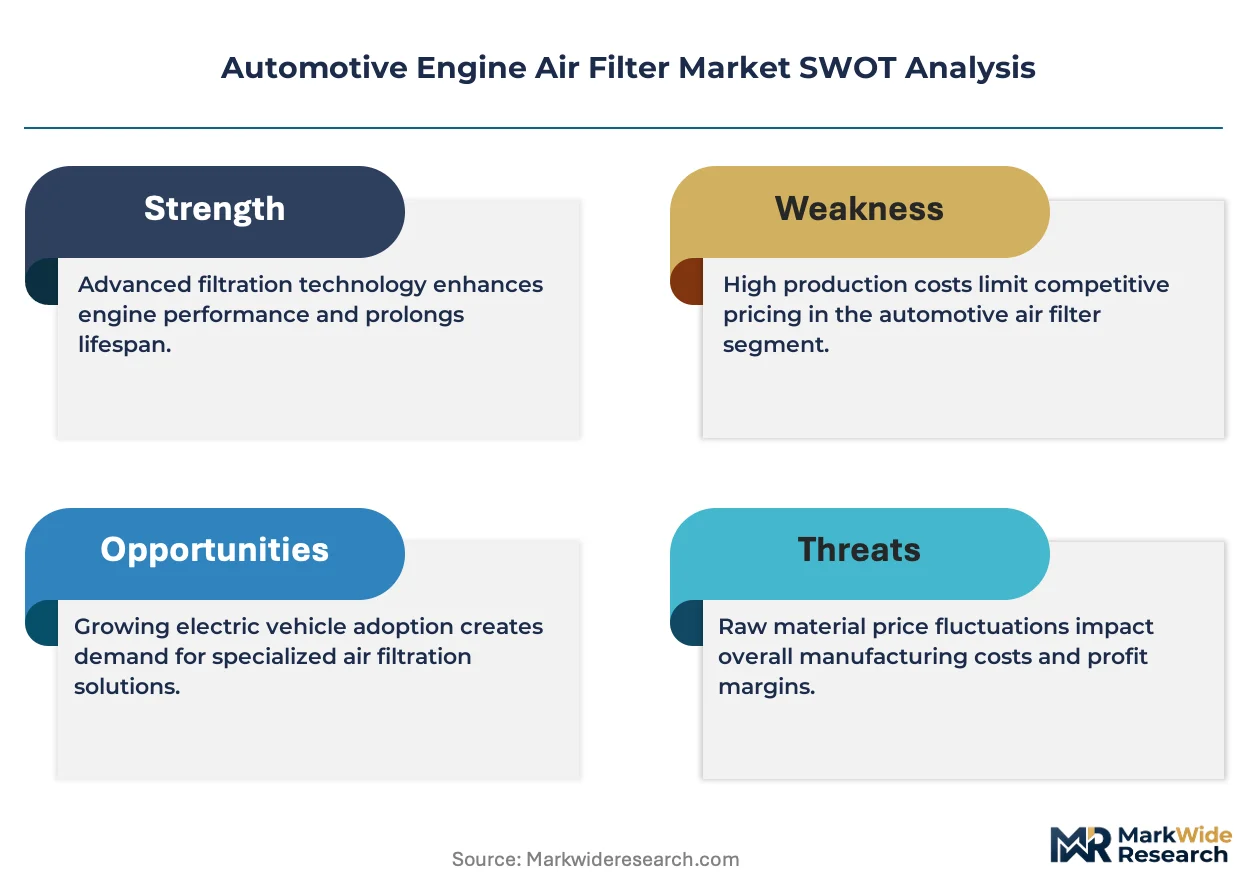
- Cellulose pulp volatility:Raw-material cost swings for paper-based substrates squeeze margin pools for economy-tier suppliers locked into long-term OEM supply contracts.
- Filter-manufacturing concentration:Pleated-media production clusters in Germany and China expose downstream assemblers to single-source geographic risk during logistics disruptions.
- Extended-drain synthetic oils:Longer service intervals in commercial fleets compress traditional 15,000-mile filter replacement rhythms.
Strategic Opportunities
- Reusable cotton-gauze aftermarket:Performance enthusiasts in the United States and Germany pay premium multiples for cleanable designs that eliminate recurring replacement spend.
- Activated carbon layering:Cabin-air odor and VOC removal commands price premiums in premium vehicle segments where OEMs bundle filtration with HVAC modules.
- Mexico assembly expansion:Automaker engine-component manufacturing near Guanajuato and Puebla creates captive demand for regional pleated-media fabrication.
Industry Challenges
- Nanoparticle certification timelines:EMA and EPA convergence on sub-micron filtration thresholds extends supplier qualification periods by 12-18 months.
- Pleating automation capex:High-speed rotary pleaters and thermal-bonding equipment require seven-figure capital commitments that mid-tier suppliers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Air Filter Market |
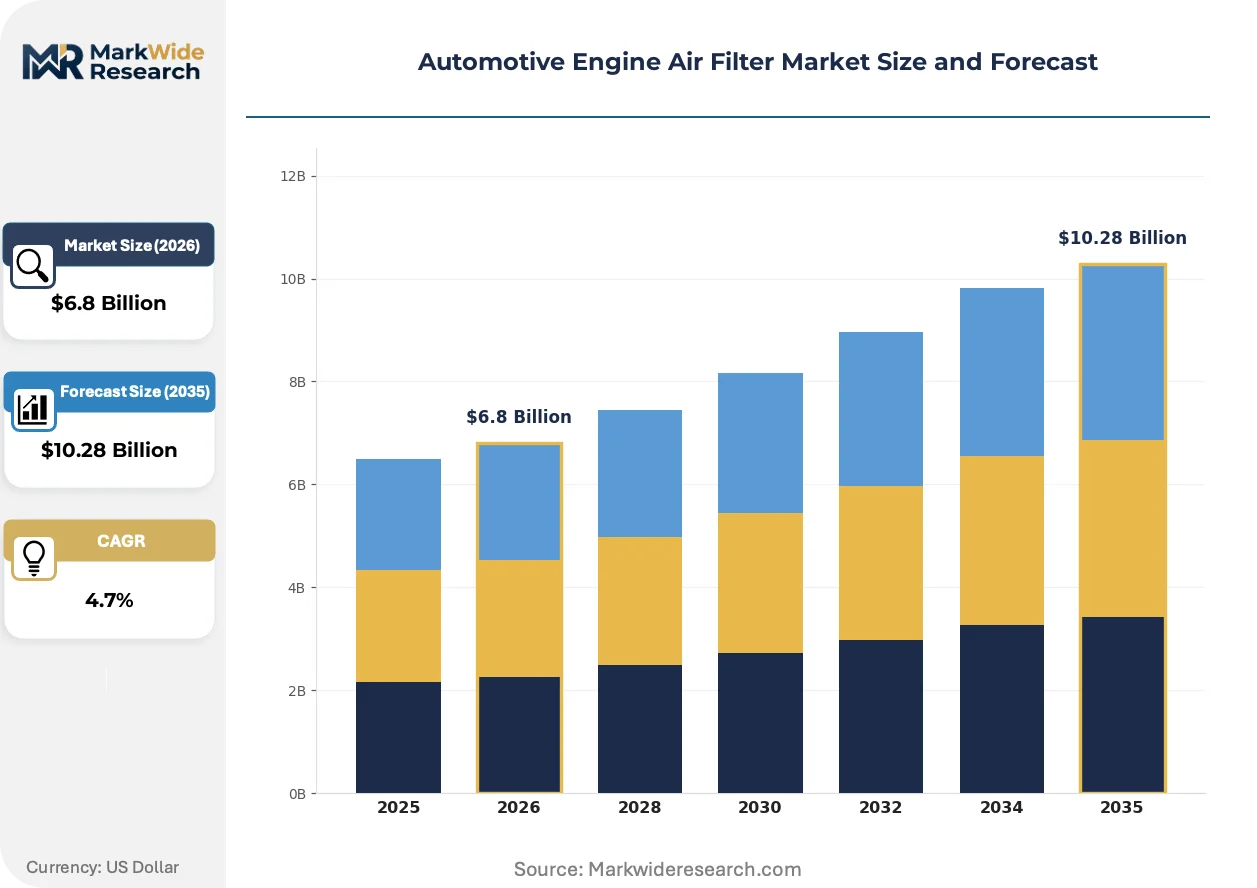
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Filters, Cylinder Filters, Conical Filters, Cabin Filters Technology: Electrostatic, HEPA, Activated Carbon, Synthetic Media End User: OEMs, Aftermarket, Automotive Manufacturers, Part Suppliers Material: Paper, Foam, Cotton, Synthetic Fiber |
| Companies Covered | MAHLE GmbH, WIX Filters, MANN+HUMMEL GmbH, K&N Engineering, Hengst SE, Denso Corporation, Fram Group, Donaldson Company, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Air Filter Market Emerging Trajectories
Filtration engineering is pivoting toward multi-layer synthetic architectures that reconcile particulate capture efficiency with pressure-drop minimization, reshaping material specifications across OEM and aftermarket channels.
Synthetic melt-blown media is migrating from industrial HVAC applications into automotive engine intake systems as turbocharged powertrains proliferate. OEM powertrain engineers specify these substrates for their superior dust-holding capacity at reduced flow restriction. The shift compresses demand for traditional cellulose paper in high-performance segments while elevating resin-formulation expertise as a competitive differentiator.
REACH and F-Gas Regulation interactions in Europe are tightening material-certification requirements for HVAC-integrated filtration modules. Suppliers must document chemical-substance compliance across substrate binders and adhesive layers. Premium German OEMs now require full material-disclosure documentation that disqualifies non-compliant Asian substrate imports.
Fleet procurement teams are consolidating filter suppliers through multi-year total-cost-of-ownership contracts that bundle filtration with predictive maintenance analytics. Severe-service commercial operators in North America favor integrated supply agreements over spot aftermarket purchasing. This concentration rewards suppliers with telematics integration capabilities and compresses margins for catalog distributors.
Automotive Engine Air Filter Market Segmentation
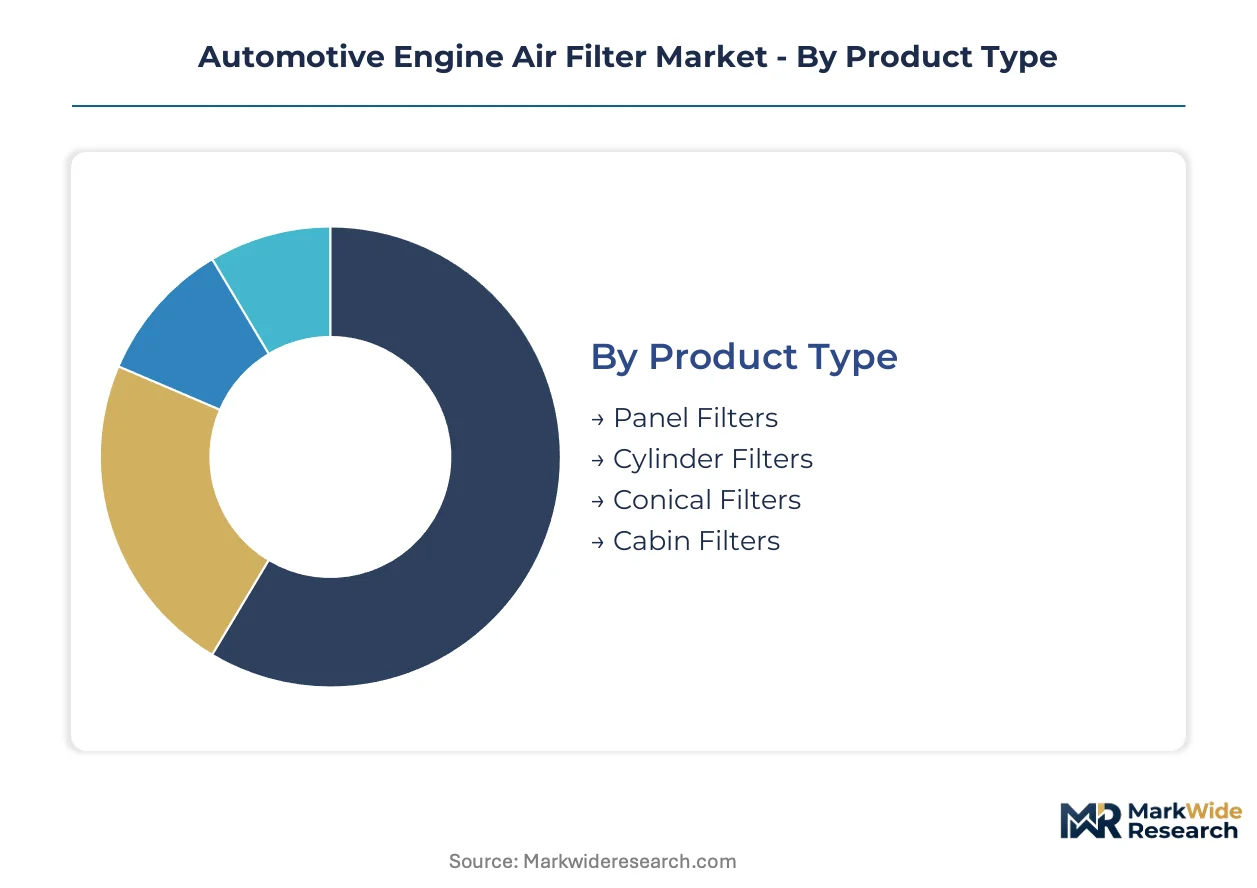
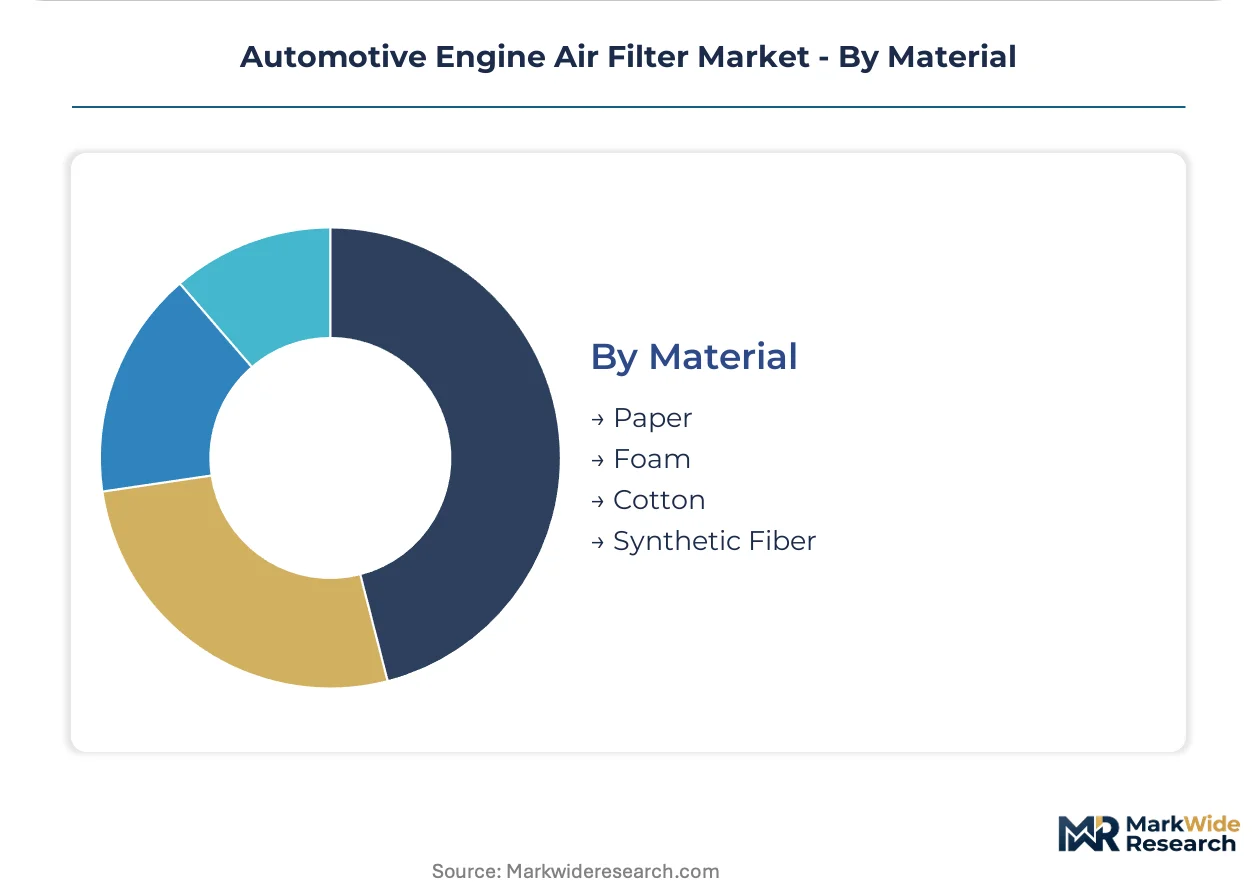
Filter architectures and material substrates fragment the market into distinct procurement channels, each governed by divergent performance specifications and replacement economics. Understanding these segment boundaries clarifies where synthetic media investments outpace cellulose legacy positions.
Product Type:
Form factor selection tracks engine-bay packaging constraints and service-interval economics across passenger and commercial platforms.
- Panel Filters:Rectangular pleated elements dominate OEM fitments due to standardized form factors and low unit cost across high-volume passenger-car platforms. Demand concentrates in the United States and China where assembly-line procurement volumes anchor regional pleated-media fabrication.
- Cylinder Filters:Radial pleating around a central support tube delivers higher surface area for severe-service commercial applications. Fleet operators in Germany specify these designs for extended dust-holding capacity in construction and mining environments.
- Conical Filters:Tapered designs optimize airflow dynamics for performance aftermarket channels. K&N Engineering and similar specialists target enthusiast segments with oiled cotton-gauze variants.
- Cabin Filters:HVAC-integrated elements separate occupant comfort from engine protection functions. Activated carbon layering commands price premiums in premium vehicle segments where odor and VOC removal justify incremental margin pools.
Established volume favors Panel Filters; emerging adoption favors Cabin Filters.
Technology:
Filtration efficiency thresholds are compressing technology substitution curves as regulatory particulate standards tighten across major automotive markets.
- Electrostatic:Charged fiber matrices enhance sub-micron capture without dense media packing. The technology migrates from industrial HVAC into automotive intake systems as EPA particulate standards force efficiency upgrades.
- HEPA:High-efficiency particulate air specifications demand complex pleating geometries and thermal-bonding equipment. Qualification timelines extend 12-18 months under converging EMA and EPA nanoparticle certification thresholds.
- Activated Carbon:Adsorptive layers target cabin-air odor and VOC removal. Premium German OEMs now require full material-disclosure documentation under REACH and F-Gas Regulation interactions.
- Synthetic Media:Melt-blown polypropylene architectures deliver superior dust-holding capacity at reduced flow restriction. Turbocharged engine penetration across passenger-car and light-truck platforms pulls premium substrate demand fastest.
Technology migration is accelerating most sharply toward Synthetic Media; HEPA faces qualification bottlenecks.
End User:
Procurement authority splits between captive manufacturing demand and distributed replacement cycles with divergent pricing power.
- OEMs:Original equipment manufacturers specify filtration systems during powertrain development. MANN+HUMMEL GmbH anchors European engineering standards through R&D intensity in pleated-media systems for German OEM procurement.
- Aftermarket:Independent service channels handle replacement demand outside warranty periods. Severe-service commercial operators in North America favor integrated supply agreements over spot purchasing.
- Automotive Manufacturers:Assembly-plant procurement teams consolidate suppliers through multi-year total-cost-of-ownership contracts. Mexico's expansion near Guanajuato and Puebla creates captive demand for regional pleated-media fabrication.
- Part Suppliers:Tier-2 and Tier-3 component distributors serve fragmented repair-shop networks. Catalog distributors face margin compression as fleet procurement consolidates around telematics-integrated suppliers.
Contract concentration favors Automotive Manufacturers; margin expansion favors Aftermarket specialists with reusable designs.
Material:
Substrate economics reflect raw-material volatility and performance-tier differentiation across replacement-cycle segments.
- Paper:Cellulose pulp substrates dominate economy-tier supply contracts. Raw-material cost swings squeeze margin pools for suppliers locked into long-term OEM agreements.
- Foam:Open-cell polyurethane structures offer washability for select aftermarket applications. Performance enthusiasts in Germany pay premium multiples for cleanable designs.
- Cotton:Oiled gauze media target reusable aftermarket channels. K&N Engineering specializes in designs that eliminate recurring replacement spend.
- Synthetic Fiber:Melt-blown and spun-bond polypropylene displaces traditional paper in high-performance segments. Resin-formulation expertise is elevating as a competitive differentiator.
Cost pressure concentrates in Paper; technology displacement favors Synthetic Fiber.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA particulate standards in the United States anchor the dominant geography, forcing commercial fleet operators to accelerate filtration system upgrades and expand aftermarket replacement volumes across North American distribution channels.
United States
Commercial vehicle fleets dominate procurement volumes as operators replace filters to meet stricter EPA tailpipe standards. Severe-service operators in construction and mining sectors specify high-efficiency synthetic media for extended dust-holding capacity. Manufacturing clusters in Michigan and Ohio supply pleated-media components to Detroit-based OEM assembly plants.
Germany
Premium OEM procurement drives engineering intensity as automakers specify pleated-media systems during powertrain development. EMA monitoring of REACH and F-Gas Regulation interactions tightens material-certification requirements for HVAC-integrated modules. Production concentrates in Baden-Württemberg and Bavaria where tier-1 suppliers operate R&D facilities near Stuttgart and Munich.
China
Domestic pleated-media producers gain share as MIIT GB standards for intake-system integrity disqualify low-efficiency imports. Dual carbon alignment mandates force certification upgrades across passenger-car and commercial platforms. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta supply assembly plants in Shanghai and Guangzhou.
Mexico
Engine-component manufacturing expansion near Guanajuato and Puebla creates captive demand for regional pleated-media fabrication. Automakers localize supply chains to serve North American assembly operations with reduced logistics exposure. Filter suppliers establish production facilities in the Bajío Region to meet OEM procurement requirements.
India
Commercial vehicle production growth drives aftermarket replacement demand as fleet operators upgrade filtration systems for dusty operating conditions. BIS certification requirements align with stricter emission norms for heavy-duty applications. Manufacturing concentrates in Maharashtra and Tamil Nadu where tier-1 suppliers serve domestic OEM assembly plants.
Automotive Engine Air Filter Market Vendor Landscape
Scale-driven OEM suppliers and specialized aftermarket fabricators split the market into divergent procurement channels with distinct margin structures and qualification timelines. Consolidation pressures concentrate around telematics-integrated fleet contracts and multi-year total-cost-of-ownership agreements. Three archetypes dominate: European engineering-intensive specialists, North American severe-service providers, and Asian cost-optimized volume producers. Competitive moves center on pleating automation investments and regional production expansion near OEM assembly clusters.
Among European engineering-intensive specialists, MANN+HUMMEL GmbH and Hengst SE exemplify the R&D-driven archetype with German GmbH structures. Donaldson Company occupies a position within the North American severe-service tier. These three anchors demonstrate how geographic origin and corporate form signal strategic positioning across the filtration value chain.
| Leading Market Players |
|---|
| MAHLE GmbH |
| WIX Filters |
| MANN+HUMMEL GmbH |
| K&N Engineering |
| Hengst SE |
| Denso Corporation |
| Fram Group |
| Donaldson Company |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Cellulose pulp volatility in paper-based substrates compresses margin pools for economy-tier suppliers locked into long-term OEM contracts, forcing tiered pricing spreads between synthetic media premium tiers and cellulose legacy positions while concentrating pleated-media production in Germany and China to minimize logistics exposure.
Pricing Analysis
Unit economics diverge sharply between German OEM procurement and Chinese domestic supply, with premium synthetic media commanding three-tier pricing structure across premium, standard, and economy levels based on dust-holding capacity ratings and MIIT GB certification tiers. Price differentiation stems from resin-formulation expertise and thermal-bonding equipment scale, with turbocharged engine specifications pulling premium substrate demand fastest. Pricing pressure stems from extended-drain synthetic oils compressing traditional replacement rhythms in commercial fleets. Fleet procurement teams show lowest price sensitivity due to total-cost-of-ownership contracting, while catalog distributors face acute margin compression.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for substrate importers serving North American assembly operations. Pleated-media fabrication concentrates in Germany, China, and Mexico, with raw material flows drawing from polypropylene resin suppliers in the US Gulf Coast and cellulose pulp markets in Scandinavia. Single-source geographic risk intensifies during logistics disruptions when production clusters in Baden-Württemberg and the Yangtze River Delta face simultaneous constraints. Distribution runs through captive OEM supply agreements for assembly-line procurement and fragmented tier-2 distributors for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across procurement channels creates white-space opportunities as fleet consolidation around telematics-integrated suppliers displaces traditional catalog distributors, generating niche entry points for specialized substrate innovators and regional fabricators near OEM assembly clusters.
For Market Incumbents: Pre-empt synthetic media substitution by accelerating pleating automation capex in Mexico's Bajío Region to serve localized engine-component manufacturing near Guanajuato and Puebla. Lock in multi-year total-cost-of-ownership contracts with severe-service commercial operators before telematics integration becomes table stakes. Channel control through predictive maintenance analytics bundling represents the critical defensive lever against margin compression.
For New Entrants and Emerging Players: Pursue reusable cotton-gauze aftermarket positioning in the United States and Germany where performance enthusiasts pay premium multiples for cleanable designs that eliminate recurring replacement spend. The severe-service commercial segment offers the most penetrable white space due to incumbent concentration around OEM supply agreements. A direct-to-enthusiast digital channel with technical content marketing bypasses consolidated fleet procurement gatekeepers.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors resin-formulation specialists with pleating automation capabilities over legacy cellulose-dependent fabricators. Long-term viability over the next decade hinges on nanoparticle certification readiness as EMA and EPA convergence extends qualification timelines. Acquisition targets should demonstrate material-disclosure documentation under REACH and F-Gas Regulation interactions. The signal to watch is telematics integration capabilities becoming a mandatory procurement criterion in North American fleet RFPs.
| Strategic Initiative | Industry Significance |
|---|---|
| Pleating Automation Investment | High-speed rotary pleaters in Mexico's Bajío Region reduce logistics exposure for North American OEM assembly. |
| Resin-Formulation R&D Partnership | Collaboration with polypropylene suppliers secures proprietary melt-blown architectures for turbocharged engine specifications. |
| Telematics Integration Development | Predictive maintenance analytics bundling meets fleet procurement consolidation toward integrated supply agreements. |
| Nanoparticle Certification Pre-Submission | Early engagement with EPA and EMA qualification timelines accelerates supplier approval for sub-micron filtration thresholds. |
| Reusable Aftermarket Channel Buildout | Direct-to-enthusiast positioning in the United States and Germany captures premium multiples for cleanable cotton-gauze designs. |
Methodological Framework
Cross-validation between primary fieldwork with OEM platform engineers and secondary validation through vehicle production databases anchors the qualitative findings in operational reality. The research team conducted structured interviews with Tier 1 supplier procurement leads, aftermarket distributors, fleet maintenance directors, and pleated-media fabrication plant managers across Germany, the United States, China, and Mexico. Secondary sources included customs and trade flow data, EPA and EMA regulatory filings, MIIT GB standard documentation, and SEC disclosures from publicly traded filtration suppliers. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers to ensure internal consistency.
Calibration against historical replacement-cycle data and turbocharger penetration rates refines the projection framework across the analysis window. The analytical model segments by filter architecture, material substrate, technology tier, and end-user procurement channel, with additional dimensioning by regional production cluster and certification requirement tier. CAGRs derive from regression analysis of correlated drivers including commercial fleet utilization rates, synthetic oil adoption curves, and regulatory phase-in schedules. Key inputs include OEM powertrain specification databases and aftermarket catalog distributor pricing indices.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian cost-optimized volume producers or accelerated nanoparticle certification by European engineering specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Diesel Engine Catalyst Market
Powertrain
Global Automotive Pumps Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
North America Precision Gearbox Market
Powertrain
Automotive Fluid Reservoir Market
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Crankshaft Position Sensor Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
Spark Plugs Market
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
Racing Clutches Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Engine Tuner Market
Powertrain
Automotive Variable Discharge Oil Pump Market