
 Automotive Oil Sump Market | 2026-2036
Automotive Oil Sump Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Oil Sump Market Outlook
Euro 7 emission standards is recalibrating the cost-of-entry calculus for oil sump manufacturers across Europe, forcing investments in precision casting and surface finishing capabilities. Robert Bosch GmbH leverages its integrated powertrain division to sustain high-volume supply agreements with German OEMs. MAHLE GmbH anchors its position through specialized aluminum casting expertise for thermal management applications. Dana Limited competes by controlling vertically integrated stamping and assembly operations in North American truck platforms.
An automotive oil sump is a reservoir, typically formed from stamped steel, die-cast aluminum, or reinforced polymer, that collects and stores engine lubricant while housing the oil pump pickup tube; wall thickness ranges from 1.2 mm to 3.5 mm depending on material and engine class. The component serves to protect rotating assemblies from debris, maintain oil temperature stability, and enable drain-back from cylinder head galleries. Aluminum product type variants now command the fastest expansion as OEMs pursue mass reduction targets, while steel retains dominance in heavy-duty and cost-sensitive segments where impact resistance outweighs weight considerations. Aftermarket suppliers within the end user dimension represent a concentrated margin pool due to part longevity and vehicle parc expansion, though OEMs still dictate material specifications and volume commitments.
The US EPA, California Air Resources Board, and the EU's ECHA framework collectively shape material compliance, mandating reduced volatile organic compound emissions from composite manufacturing and restricting certain heavy metal additives in aluminum alloys. Japan's METI energy efficiency standards further influence sump design through friction-reduction requirements that cascade into oil pan surface treatments. Stakeholders must monitor how evolving particulate matter limits in China and India redirect foundry investment toward closed-loop recycling and low-pressure die-casting capacity.
Market Dynamics
Aluminum die-casting technology is compressing the competitive set as OEMs mandate thinner-walled, high-strength sump designs to meet mass reduction targets without sacrificing structural integrity.
Growth Catalysts
- Euro 7 emission standards:European regulators are forcing recalibration of material specifications toward precision-cast aluminum alloys with reduced wall thickness.
- Brazilian light commercial vehicle fleets:OEMs in São Paulo and Curitiba are expanding aluminum oil sump adoption to achieve fleet-average weight reduction mandates.
- Closed-loop foundry recycling:Low-pressure die-casting capacity investments in Querétaro and San Luis Potosí are lowering unit costs for high-volume contract manufacturing.
Market Restraints
- Primary aluminum price volatility:LME aluminum fluctuations compress margin stability for die-casters serving cost-sensitive heavy-duty segments.
- Steel stamping concentration:North American truck platform supply chains remain anchored to legacy steel suppliers with long-term tooling amortization cycles.
- REACH compliance friction:ECHA restrictions on certain heavy metal additives in aluminum alloys extend qualification timelines for new material grades.
Strategic Opportunities
- Reinforced polymer composite sumps:Glass-fiber reinforced nylon formulations offer 40-50% mass reduction for electric vehicle thermal management modules.
- India's PLI scheme for auto components:Domestic manufacturing incentives are attracting aluminum casting investment toward Chennai and Pune industrial corridors.
- Direct-to-fleet aftermarket channels:Commercial vehicle operators in Mexico are bypassing traditional distribution to source certified replacement sumps through B2B procurement platforms.
Industry Challenges
- Precision casting skill scarcity:Foundries struggle to recruit technicians capable of operating thin-wall high-pressure die-casting cells with automated quality verification.
- Multi-material bonding certification:OEM validation protocols for aluminum-to-composite hybrid sump designs extend development cycles by 18-24 months.
- Legacy ERP integration:Tier-2 suppliers face friction connecting real-time production data to OEM vendor-managed inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Oil Sump Market |
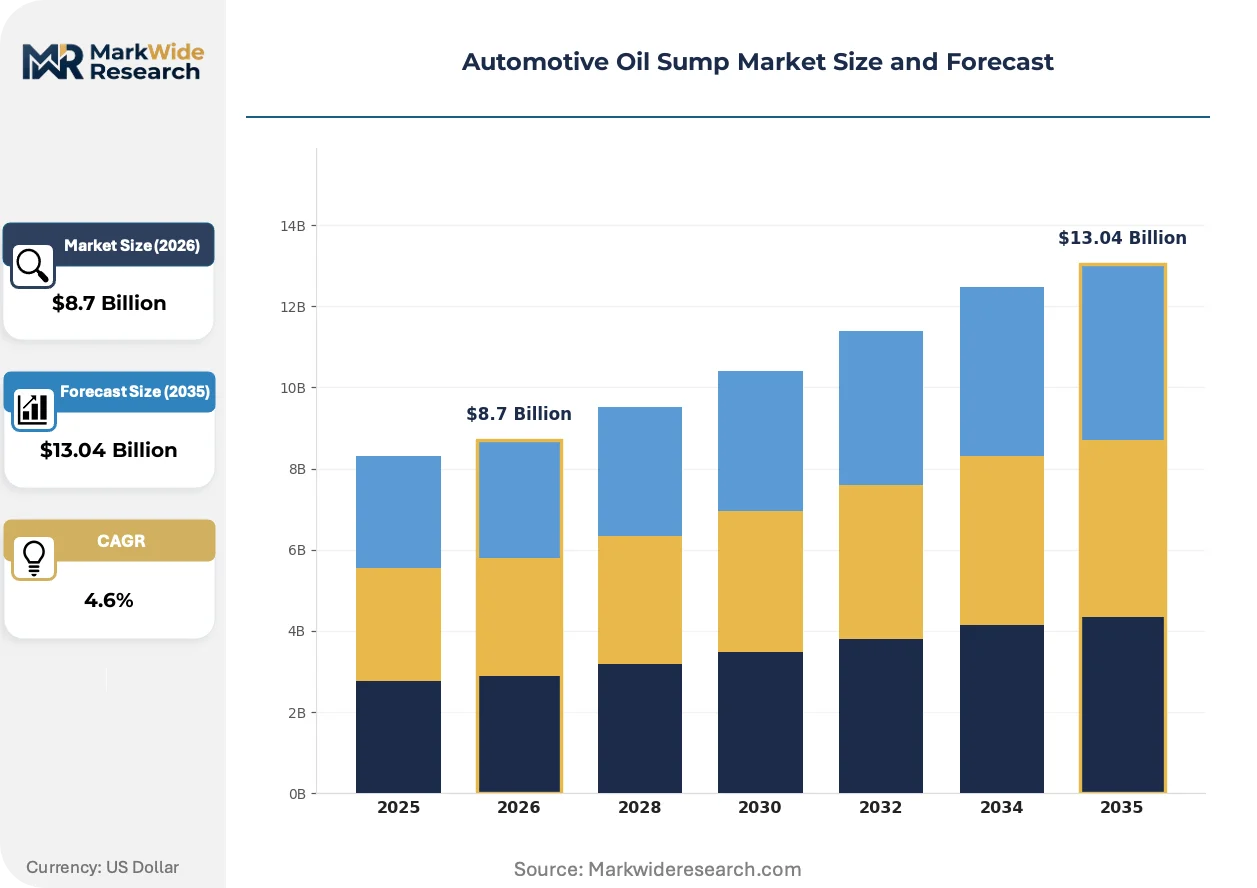
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Composite, Plastic End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Repair Shops Oil Type: Synthetic, Conventional, Blended, High Mileage Installation Type: Drop-in, Bolt-on, Custom Fit, Universal |
| Companies Covered | Robert Bosch GmbH, Dekson Castings, MAHLE GmbH, Pacific Industrial Co., Ltd., Italpresse Gauss, Dana Limited, MANN+ HUMMEL, American Axle & Manufacturing, Inc, Magna International Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Oil Sump Market Strategic Shifts
Surface engineering and material hybridization are redefining oil sump performance benchmarks as thermal management requirements intensify across electrified powertrains.
Hybrid aluminum-composite construction is consolidating design architectures for next-generation thermal management modules. BMW and Mercedes-Benz powertrain divisions are specifying aluminum-reinforced polymer sandwich structures for battery cooling-integrated sumps. This consolidation is compressing the addressable market for single-material steel stampings in premium vehicle segments.
EPA Tier 3 tailpipe standards are cascading into oil pan surface treatment specifications. The regulation mandates reduced friction losses across the full operating temperature range, forcing suppliers to adopt plasma-electrolytic oxidation coatings on aluminum substrates. Passenger car OEMs in Michigan and Ohio are qualifying these finishes for 2026 model year powertrains.
Fleet procurement departments are unbundling after-sales service contracts from initial component supply agreements. Commercial vehicle operators in São Paulo now negotiate separate multi-year maintenance packages with certified rebuilders rather than OEM-authorized dealers. This disintermediation is most visible in Brazil's long-haul trucking corridor connecting Santos port to interior agricultural regions.
Automotive Oil Sump Market Segmentation
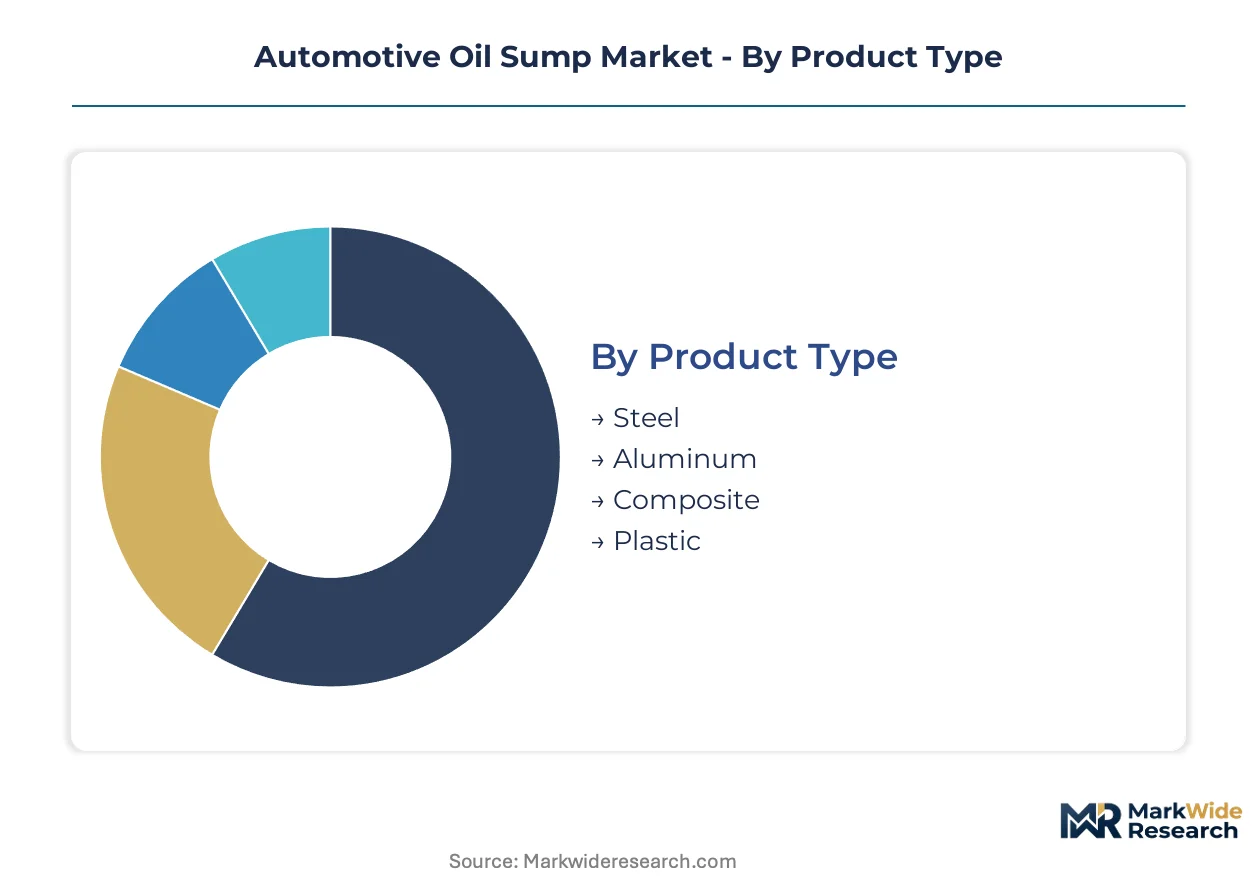
Oil sump material selection directly determines thermal management performance and mass reduction potential across powertrain architectures. Installation complexity and oil formulation compatibility further stratify procurement decisions between integrated OEM supply chains and fragmented aftermarket channels.
Product Type:
Standalone structural sumps dominate heavy-duty platforms, while embedded thermal management modules favor material hybrids for battery-cooling integration.
- Steel:Stamped cold-rolled grades with 1.8-3.5 mm wall thickness deliver superior impact resistance for commercial vehicle underbody protection. North American truck manufacturers in Michigan and Ohio retain steel specifications for long-haul durability requirements despite mass penalties.
- Aluminum:High-pressure die-cast alloys with 1.2-2.0 mm walls enable 40-50% mass reduction versus steel equivalents. Brazilian light commercial fleets in São Paulo and Curitiba are accelerating aluminum adoption to meet fleet-average weight mandates.
- Composite:Glass-fiber reinforced polymer formulations serve electric vehicle thermal management modules requiring electromagnetic shielding properties.
- Plastic:Injection-molded nylon variants address cost-sensitive compact passenger car segments with limited thermal load requirements.
Volume placements concentrate in Steel; the faster expansion belongs to Aluminum.
End User:
Procurement scale and specification authority diverge sharply between captive OEM production and independent aftermarket channels.
- OEMs:German and Japanese automakers dictate material specifications, wall thickness tolerances, and surface treatment protocols through multi-year supply agreements. These stakeholders control 70-80% of annual volume commitments through integrated powertrain divisions.
- Aftermarket Suppliers:Certified rebuilders in Mexico's Querétaro corridor now source direct-to-fleet through B2B procurement platforms, bypassing traditional distribution. This disintermediation captures concentrated margins from vehicle parc expansion.
- Vehicle Assemblers:Contract manufacturers near San Luis Potosí coordinate just-in-time delivery for export-oriented production.
- Repair Shops:Independent service networks in Brazil's Santos-interior trucking corridor stock universal-fit steel replacements for legacy fleets.
Specification authority rests with OEMs; margin capture is shifting toward Aftermarket Suppliers.
Oil Type:
Formulation chemistry dictates sump surface treatment requirements and thermal cycling durability thresholds.
- Synthetic:Full synthetic lubricants with extended drain intervals require plasma-electrolytic oxidation coatings on aluminum substrates to prevent additive aggression. EPA Tier 3 friction-reduction mandates in the US are accelerating synthetic adoption for 2026 powertrains.
- Conventional:Mineral-base formulations retain dominance in emerging market cost-sensitive segments with shorter service intervals.
- Blended:Semi-synthetic formulations balance performance and cost for mid-market passenger car applications.
- High Mileage:Seal-conditioning additives in these formulations demand modified gasket interface designs for aging vehicle populations.
Specification pull concentrates in Synthetic; the steepest volume trajectory belongs to Blended formulations.
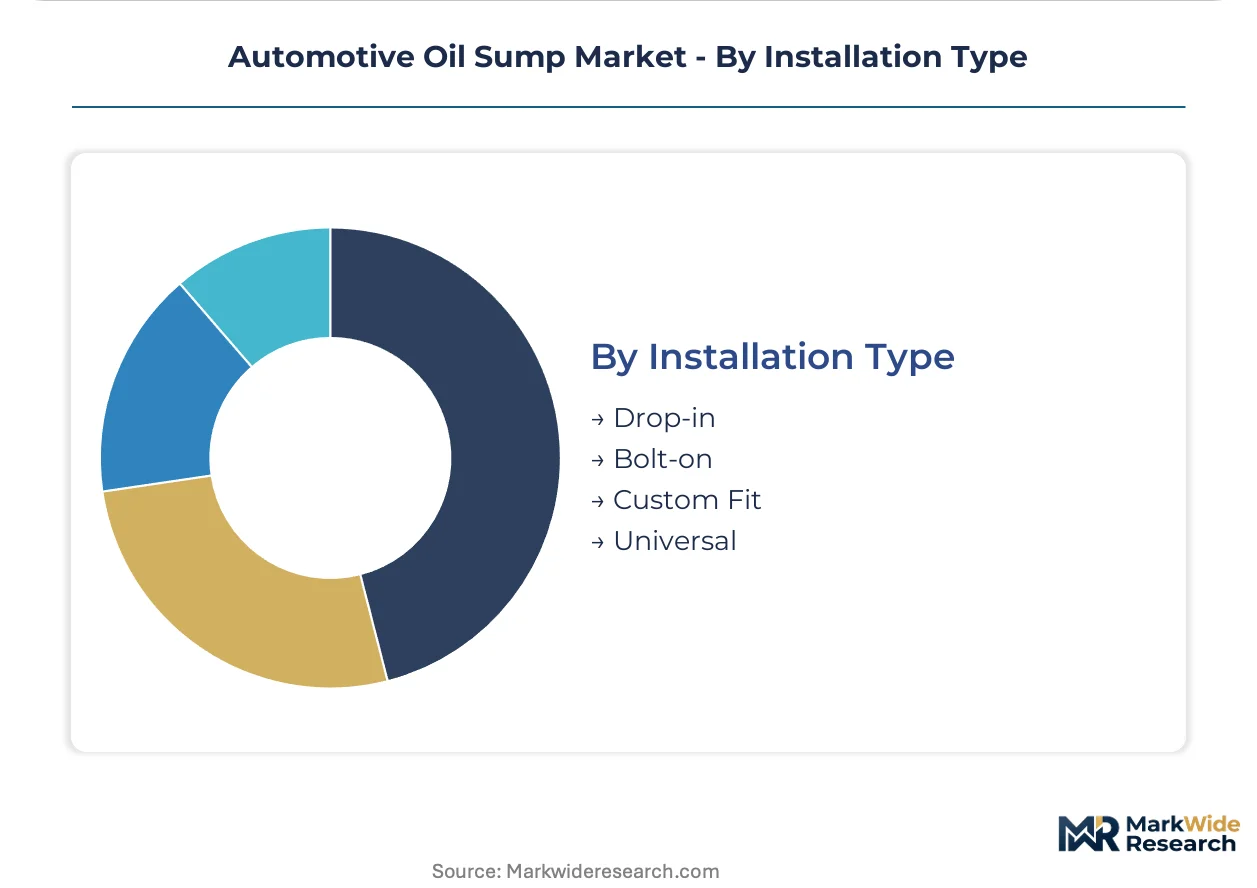
Installation Type:
Assembly labor content and tooling amortization cycles determine competitive positioning across manufacturing models.
- Drop-in:Pre-assembled modules with integrated oil pump pickups minimize line-side labor for high-volume OEM assembly plants. Mexican manufacturing corridors favor this format for export efficiency.
- Bolt-on:Separate sump-to-block interfaces allow material substitution flexibility during platform mid-cycle updates.
- Custom Fit:Application-specific designs with unique pan rail geometries serve low-volume premium vehicle assembly.
- Universal:Multi-fit patterns with adjustable pickup tube positioning dominate aftermarket replacement demand in price-sensitive regions.
Production scale favors Drop-in configurations; repair channel flexibility drives Universal adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's IMMEX maquiladora program concentrates export-oriented oil sump manufacturing along the Querétaro-San Luis Potosí corridor. German and Japanese OEMs anchor demand through integrated powertrain supply agreements.
United States
EPA Tier 3 friction-reduction mandates are accelerating plasma-electrolytic oxidation coating qualifications for 2026 powertrains. Michigan and Ohio host captive stamping operations serving Detroit Three truck platforms. Cleveland-area foundries are retooling for thin-wall aluminum die-casting capacity.
Germany
Euro 7 emission standards force precision-cast aluminum specifications with reduced wall thickness. ECHA REACH restrictions on heavy metal additives extend material qualification timelines. Stuttgart powertrain divisions specify hybrid aluminum-composite sandwich structures for thermal management integration.
Japan
METI energy efficiency standards cascade into oil pan surface treatment requirements for friction reduction. Nagoya-area suppliers coordinate just-in-time delivery for hybrid powertrain architectures. Osaka-based casting specialists are investing in automated high-pressure die-casting cells.
Brazil
Light commercial vehicle fleets in São Paulo and Curitiba are expanding aluminum adoption to meet fleet-average weight reduction mandates. ANVISA compliance protocols govern manufacturing facility certifications. Santos-port trucking corridors drive aftermarket replacement demand for legacy steel sumps.
India
PLI scheme incentives for auto components are attracting aluminum casting investment toward Chennai and Pune industrial corridors. BIS material standards govern alloy specifications for domestic OEM supply. Tamil Nadu foundries are scaling low-pressure die-casting capacity for export contracts.
Automotive Oil Sump Market Competitive Environment
German producers anchor the precision-casting tier; Japanese specialists hold positions in high-volume stamped steel. The supplier base stratifies across three tiers: integrated powertrain divisions with captive foundries, independent aluminum die-casters serving multiple OEMs, and steel stamping houses with long-term truck platform contracts. Consolidation pressures favor backward integration into aluminum recycling and surface treatment capabilities. Strategic moves center on hybrid material qualification partnerships and closed-loop foundry investments.
Within the integrated powertrain tier, Robert Bosch GmbH and MAHLE GmbH exemplify archetypes of captive supply chain control. Dana Limited occupies a position among North American stamping specialists with vertically integrated assembly operations. Pacific Industrial Co., Ltd. represents Japanese precision-casting expertise serving hybrid powertrain thermal management requirements.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Dekson Castings |
| MAHLE GmbH |
| Pacific Industrial Co., Ltd. |
| Italpresse Gauss |
| Dana Limited |
| MANN+ HUMMEL |
| American Axle & Manufacturing, Inc |
| Magna International Inc |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap aluminum die-casters in Germany and Japan anchor supply discipline through multi-generational tooling investments, translating into sticky contract pricing that resists spot-market volatility. Their captive relationships with OEM powertrain divisions create bilateral pricing power absent in fragmented steel stamping tiers.
Pricing Analysis
Short-lead-time premiums of 15-25% apply to aluminum die-cast orders requiring sub-8-week turnaround for platform mid-cycle updates, while spot inventory of legacy steel stampings trades at discounts to long-term contract rates. Three-tier pricing structure across premium, standard, and economy levels separates plasma-electrolytic oxidation-coated aluminum for synthetic oil compatibility from untreated castings and basic cold-rolled steel. Cost compression in heavy-duty steel segments is intensifying because LME aluminum volatility compresses die-caster margins and forces cross-subsidization. Fleet procurement departments in Brazil exhibit highest price sensitivity, while German OEM powertrain divisions prioritize specification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with high-pressure die-casting capacity concentrated in Germany, Mexico, and Japan, where automated cell qualification timelines extend 18-24 months. Raw material feeds draw from primary aluminum smelters in Canada and Norway, cold-rolled steel mills in the US Midwest, and glass-fiber polymer compounders in South Korea. Tariff exposure on aluminum alloy imports into the US threatens margin stability for Querétaro-based contract manufacturers serving Detroit Three platforms. Distribution runs through just-in-time vendor-managed inventory systems anchored to OEM assembly plants, with aftermarket channels fragmenting toward direct-to-fleet B2B procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-wall high-pressure die-casting skill scarcity props pricing power for qualified suppliers, as OEMs face 18-month qualification timelines for new foundry entrants. This capacity bottleneck sustains margin premiums for incumbents with certified automated cells.
For Market Incumbents: Lock in long-term supply agreements with Brazilian light commercial OEMs before India's PLI scheme matures competing capacity in Chennai and Pune. Backward integration into closed-loop aluminum recycling secures feedstock cost stability against LME volatility. Reinforced polymer composite R&D partnerships with battery thermal management divisions defend against displacement by hybrid material architectures. For New Entrants and Emerging Players: Euro 7 in Germany opens a window for precision-casting specialists capable of sub-1.5mm wall thickness certification. Target aftermarket direct-to-fleet channels in Mexico's Querétaro-San Luis Potosí corridor where traditional distribution disintermediation creates margin capture opportunities. Pursue white-label manufacturing agreements with Tier-2 suppliers struggling to integrate legacy ERP systems with OEM vendor-managed inventory protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated die-casting specialists in Japan's Nagoya-Osaka industrial zone with METI-certified energy efficiency credentials. Long-term viability hinges on electrification thermal management pivot capability. Watch for aluminum-to-composite hybrid sump validation completions at BMW and Mercedes-Benz as inflection signal for material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Foundry Recycling | Captive aluminum feedstock control insulates margin from LME volatility for Querétaro-based suppliers. |
| Plasma-Electrolytic Oxidation Certification | EPA Tier 3 friction-reduction compliance unlocks 2026 powertrain qualifications with Michigan and Ohio OEMs. |
| Hybrid Material Qualification Partnership | Aluminum-polymer sandwich structures consolidate BMW and Mercedes-Benz thermal management module specifications. |
| Direct-to-Fleet B2B Platform | Brazil's Santos-interior trucking corridor enables margin capture bypassing traditional aftermarket distribution layers. |
| Low-Pressure Die-Casting Scale-Up | India's PLI scheme incentives in Chennai and Pune attract export contract manufacturing for European OEMs. |
Study Parameters
Independent corroboration across Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution heads, and foundry operations managers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through vehicle production databases, IHS Markit registration data, SEC filings of listed automotive suppliers, and customs records of aluminum alloy trade flows. Bottom-up segment sizing triangulates against top-down OEM production forecasts.
Rate-of-change decomposition separates volume growth from value expansion across material substitution dynamics, regulatory compliance cost pass-through, and regional manufacturing footprint shifts. Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from regression against historical production correlations and forward-looking OEM platform announcements, with aluminum penetration curves and synthetic oil adoption rates as industry-specific forecast inputs.
Caveats apply where Euro 7 implementation delays, LME aluminum price spikes, or India's PLI scheme revision could materially shift the outlook. Forecasts reflect assumptions about OEM weight reduction target persistence and thermal management integration timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Advanced Gear Shifter System Market
Powertrain
Power Seat Adjustment Motor Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Global Automotive Dyno Market
Powertrain
Diesel Engine Market
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Automotive Power Steering Pump Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Global Automotive Pumps Market
Powertrain
Steering Damper Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Global Automotive Torque Converter Market