
 Trim Press Market | 2026-2036
Trim Press Market Size, Share, and Industry Trends Forecast 2026-2036
Trim Press Market Analytics
The distributor-to-OEM channel is narrowing as large automotive stampers consolidate procurement around direct manufacturer relationships. Schuler Group leverages captive engineering services to anchor long-term contracts with German automakers. AIDA Engineering competes on servo-press specialization across Asian electronics supply chains. Komatsu Industries sustains geographic dominance in heavy-capacity installations for Japanese aerospace subcontractors.
A trim press is a metalforming machine that applies controlled force through a reciprocating ram to shear, blank, or trim sheet metal and coil stock, typically operating at tonnages from 50 to 3,000 metric tons and stroke rates up to 1,000 strokes per minute in mechanical configurations. Its primary industrial purpose is producing dimensionally precise edges on stamped components where subsequent machining would add unacceptable cycle time or cost. Servo press technology commands expanding margin pools as programmable slide motion reduces die wear and enables warm-forming of high-strength alloys. Hydraulic press systems retain structural share in ultra-high-capacity segments above 2,000 tons where sustained pressure profiles outrun mechanical or servo alternatives for thick-gauge aerospace alloys.
OSHA machine-guarding standards and ISO 16092 safety requirements for mechanical presses shape North American product specifications, while CE marking under the EU Machinery Directive governs European market access and forces integration of light-curtain interlocks and brake-monitoring systems. Japan's METI energy-efficiency benchmarks and China's GB standards on industrial equipment safety add compliance layers for manufacturers serving multiple national markets. Stakeholders must monitor how servo-press digital-control architectures intersect with emerging cybersecurity frameworks for industrial automation before committing to next-generation platform investments.
Market Dynamics
Servo-electric drive architectures are compressing replacement cycles for mechanical trim presses as ISO energy-efficiency standards harden procurement specifications across automotive supply chains.
Growth Catalysts
- ISO 16092 safety mandates:European and North American OEMs now require brake-monitoring systems and light-curtain interlocks, forcing fleet upgrades at tier-one stampers.
- High-strength aluminum warm-forming:Programmable slide motion in servo presses enables processing of 6xxx and 7xxx series alloys for electric vehicle battery enclosures and structural members.
- Tool-and-die cluster concentration:Stuttgart, Nagoya, and Detroit anchor dense supplier ecosystems that accelerate technology diffusion and reduce commissioning timelines for new installations.
Market Restraints
- Servo drive cost premium:Variable-frequency drives and permanent-magnet motors add thirty to fifty percent to initial capital outlay versus mechanical clutch-brake systems, extending payback periods for mid-capacity buyers.
- Specialized maintenance labor scarcity:Servo press diagnostics require mechatronics competencies that conventional hydraulic technicians lack, constraining uptime in secondary manufacturing regions.
- Ultra-high-tonnage hydraulic lock-in:Aerospace alloy forming above two thousand metric tons sustains incumbent hydraulic architectures where sustained pressure profiles outperform electromechanical alternatives.
Strategic Opportunities
- India automotive capacity buildout:PLI scheme incentives for advanced manufacturing equipment create first-mover advantage for servo-press vendors establishing local assembly operations.
- Cybersecurity-integrated control platforms:Convergence of IEC 62443 industrial security standards with servo-press digital architectures opens premium pricing for hardened automation stacks.
- Direct manufacturer contracting:Large stampers are consolidating procurement away from distributors, rewarding engineering-intensive vendors with captive service capabilities.
Industry Challenges
- Die engineering talent bottleneck:Warm-forming process design for high-strength alloys demands thermomechanical simulation expertise that outpaces vocational pipeline output in Germany and Japan.
- Legacy hydraulic integration friction:Mixed-fleet operators face control-protocol incompatibilities when retrofitting servo presses alongside existing press lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trim Press Market |
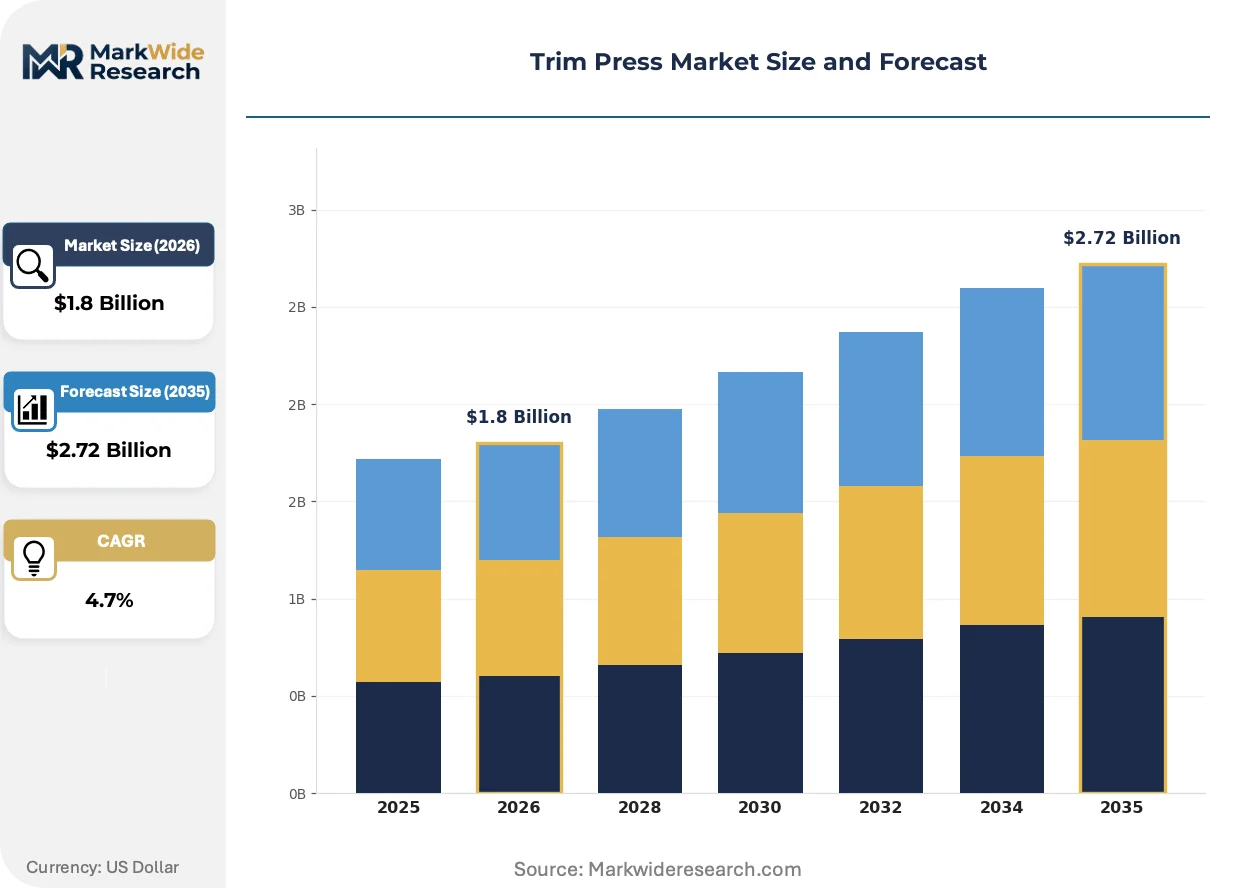
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Press, Hydraulic Press, Pneumatic Press, Servo Press End User: Automotive, Aerospace, Electronics, Consumer Goods Technology: Automatic, Semi-Automatic, Manual, Digital Control Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | Schuler Group, AIDA Engineering, Komatsu Industries, Amada, LVD Group, Macrodyne Technologies, Neff Press, Erie Press Systems, Bosch Rexroth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trim Press Market Evolving Landscape
Digital motion control and connected safety systems are redefining competitive differentiation in trim press manufacturing, compressing the viable technology lag between equipment generations.
Servo motor and drive technology with programmable kinematic profiles is rendering obsolete fixed-stroke mechanical presses in automotive body-panel applications. Tier-one stampers in Germany and the United States are specifying all-electric architectures for new capacity additions. This transition is compressing residual values for mechanical clutch-brake equipment and redistributing margin pools toward motion-control specialists.
CE marking under the EU Machinery Directive now mandates integrated safety-rated monitored functions for brake systems and two-hand control circuits. This regulatory tightening is elevating compliance costs for non-European exporters while creating protected market access for vendors with established notified-body relationships. Asian equipment manufacturers are responding by establishing EU-based engineering centers to accelerate certification timelines.
Automotive OEMs are consolidating supplier relationships around direct manufacturer contracts with embedded engineering services. Large stampers in Japan and the United States are disintermediating traditional distributor networks, preferring long-term service agreements with equipment builders. This channel restructuring concentrates volume with vertically integrated vendors and marginalizes pure-distribution players lacking technical depth.
Trim Press Market Segmentation
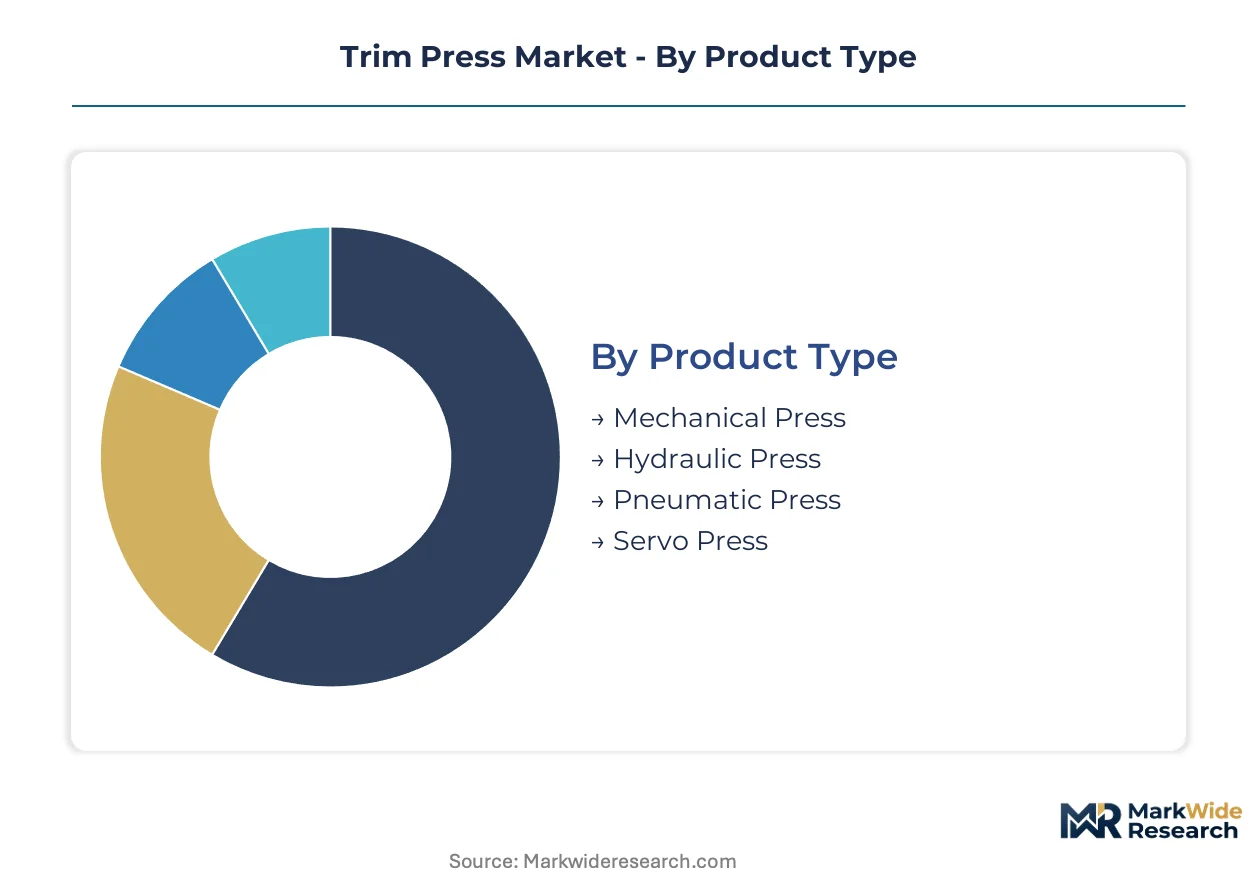
Trim press segmentation reveals how technology maturity and application intensity create divergent margin structures across equipment categories. Understanding these splits enables vendors to align R&D spend with segments where programmable motion and safety compliance command pricing power.
Product Type:
Mature mechanical architectures coexist with emerging servo-electric platforms as energy-efficiency mandates rewrite procurement specifications across automotive supply chains.
- Mechanical Press:Flywheel-driven clutch-brake systems deliver fixed-stroke operation at stroke rates reaching 1,000 strokes per minute. Fleet concentration persists among tier-two stampers in the United States and Germany where capital replacement cycles lag OEM-tier requirements.
- Hydraulic Press:Fluid-powered rams generate sustained pressure profiles essential for thick-gauge aerospace alloy forming above 2,000 metric tons. Japanese aerospace subcontractors in Nagoya anchor demand for ultra-high-capacity installations where mechanical alternatives cannot match force consistency.
- Pneumatic Press:Compressed-air actuation serves light-duty blanking operations below 100 tons in consumer goods packaging. Cost-sensitive manufacturers in secondary electronics clusters favor these systems for short-run production.
- Servo Press:Programmable slide motion via permanent-magnet motors enables warm-forming of 6xxx and 7xxx aluminum series for electric vehicle battery enclosures. German automakers specify all-electric architectures for new body-panel capacity.
Mechanical Press retains volume leadership; Servo Press holds the steepest expansion curve.
End User:
Application intensity varies sharply across customer verticals, with automotive procurement scale dictating technology roadmaps that filter downstream to smaller segments.
- Automotive:OEM stamping operations demand ISO 16092-compliant brake monitoring and light-curtain interlocks for high-volume body-in-white production. Direct manufacturer contracting is consolidating procurement around vendors with captive engineering services.
- Aerospace:Structural titanium and aluminum forming requires sustained pressure profiles achievable only through hydraulic systems above 2,000 tons. Japanese METI energy-efficiency benchmarks are beginning to penetrate this historically conservative segment.
- Electronics:Miniaturized connector and shield blanking drives demand for precision servo presses with micron-level slide positioning. Asian supply chains in Taiwan and South Korea specify programmable kinematics for high-strength copper alloys.
- Consumer Goods:Appliance panel and packaging metalforming operates on extended replacement cycles with lower safety compliance burdens. Distributor channels retain relevance here due to fragmented buyer scale.
Automotive commands the largest equipment spend; Electronics is climbing the fastest as connector miniaturization accelerates.
Technology:
Control sophistication separates premium pricing tiers, with digital architectures intersecting emerging industrial cybersecurity frameworks.
- Automatic:Fully programmed cycle operation with integrated part handling dominates high-volume automotive lines. These systems embed safety-rated monitored functions required for CE marking under the EU Machinery Directive.
- Semi-Automatic:Operator-assisted loading with automated forming cycles serves mid-volume job shops where batch flexibility outweighs throughput maximization. German tool-and-die clusters favor this configuration for prototype-to-production transitions.
- Manual:Hand-fed operation persists in ultra-low-volume custom fabrication and maintenance repair operations. OSHA machine-guarding standards in the United States impose two-hand control requirements that elevate retrofit costs.
- Digital Control:Servo-press architectures with IEC 62443-hardened automation stacks enable remote diagnostics and predictive maintenance. Premium pricing attaches to platforms with integrated cybersecurity certifications.
Automatic systems dominate current installed base; Digital Control is gaining share fastest as OEMs consolidate around connected safety architectures.
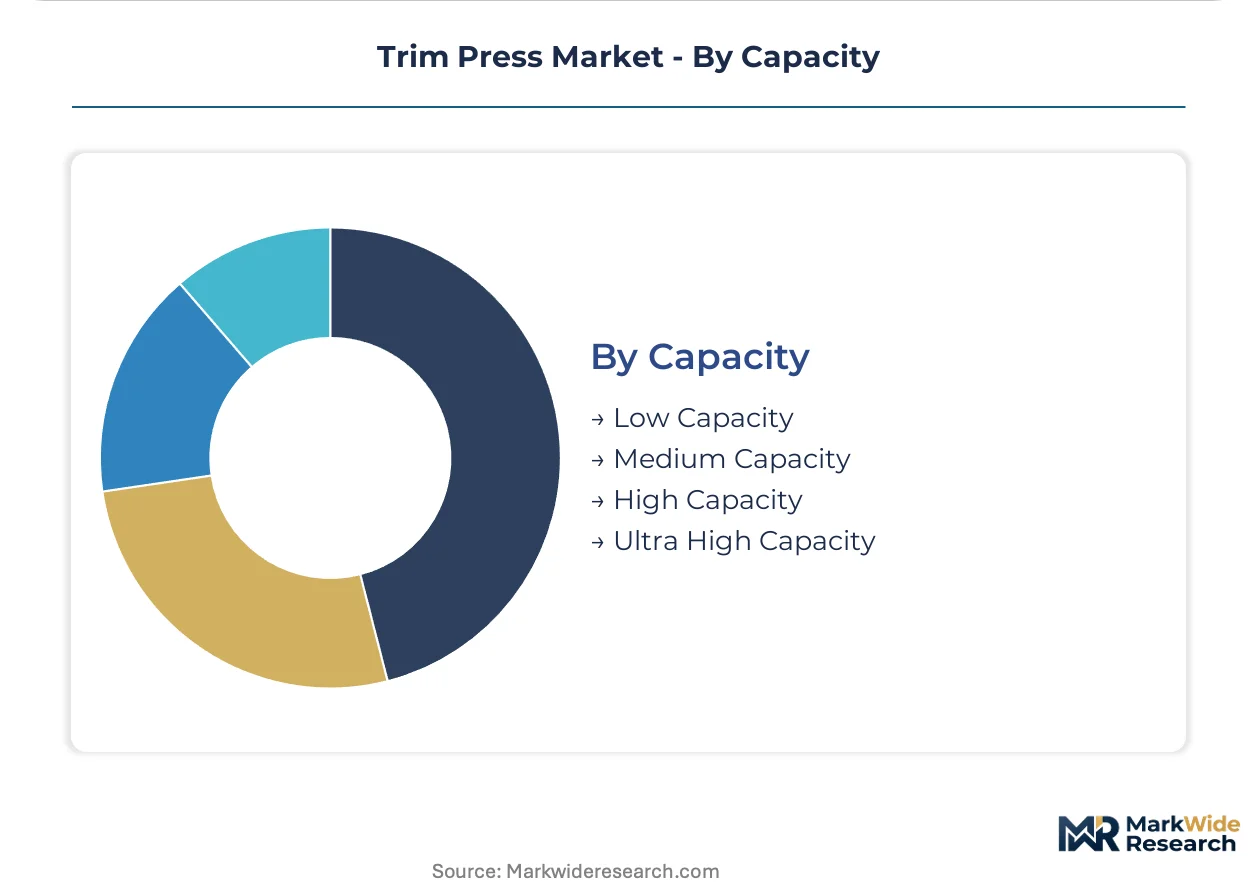
Capacity:
Tonnage thresholds map directly to technology lock-in, with ultra-high segments preserving hydraulic incumbency against servo-electric displacement.
- Low Capacity:Systems below 200 tons serve electronics connector and small appliance blanking. Pneumatic and mechanical architectures compete on first cost in price-sensitive Asian manufacturing.
- Medium Capacity:The 200-800 ton range captures the majority of automotive body-panel stamping. Servo-electric penetration is deepest here as programmable motion reduces die wear and enables warm-forming.
- High Capacity:800-2,000 ton installations handle structural automotive members and heavy appliance panels. Mixed-fleet operators face control-protocol incompatibilities when retrofitting servo presses alongside legacy hydraulic lines.
- Ultra High Capacity:Above 2,000 tons, sustained pressure requirements for aerospace alloy forming sustain hydraulic dominance. Japanese and German aerospace subcontractors anchor this thin but high-margin segment.
Medium Capacity holds the largest unit volume; Ultra High Capacity maintains the most defensible margin structure against technology substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's role in European metalforming equipment trade, handling precision machinery exports to automotive clusters across the continent. This infrastructure underwrites technology diffusion patterns that shape regional demand.
United States
Automotive stamping operations in Michigan and Ohio drive servo-press procurement as OEMs tighten body-panel tolerances. OSHA machine-guarding standards mandate brake-monitoring systems and light-curtain interlocks for fleet upgrades. Detroit's tool-and-die cluster accelerates commissioning timelines for new installations through dense supplier ecosystems.
Germany
CE marking under the EU Machinery Directive forces integration of safety-rated monitored functions for brake systems. Stuttgart anchors precision metalforming supply chains where engineering-intensive vendors capture direct manufacturer contracts. The country's automotive OEMs specify all-electric architectures for new body-panel capacity.
Japan
METI energy-efficiency benchmarks penetrate aerospace and automotive segments historically resistant to technology substitution. Nagoya's aerospace subcontractors sustain demand for ultra-high-capacity hydraulic installations above two thousand metric tons. Kansai-based electronics supply chains specify programmable kinematics for miniaturized connector blanking.
India
PLI scheme incentives for advanced manufacturing equipment create first-mover advantage for servo-press vendors establishing local assembly operations. Automotive capacity buildout in Maharashtra and Tamil Nadu concentrates procurement around direct manufacturer relationships. Pune's emerging tool-and-die cluster reduces commissioning timelines for tier-one stampers.
China
GB standards on industrial equipment safety add compliance layers for manufacturers serving domestic automotive supply chains. Yangtze River Delta electronics manufacturers specify precision servo presses for high-strength copper alloy processing. Shenzhen's battery enclosure producers drive warm-forming adoption for electric vehicle structural members.
Trim Press Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying drives, controls, and safety systems. The vendor base concentrates around vertically integrated equipment builders with captive engineering services and pure-play component suppliers lacking installation capabilities. Two strategic archetypes dominate: engineering-intensive system integrators anchoring long-term service contracts, and motion-control specialists capturing margin pools from servo-electric transitions. Competitive moves center on direct manufacturer contracting consolidation and geographic expansion through local assembly operations.
Among Germany-based equipment builders, Schuler Group GmbH exemplifies the engineering-intensive system integrator archetype, while Japanese specialists including AIDA Engineering Co., Ltd. and Komatsu Industries, Ltd. occupy positions within the servo-press and heavy-capacity installation segments respectively. These three entities represent distinct competitive vectors: European engineering services, Asian servo-electric specialization, and Japanese ultra-high-tonnage dominance.
| Leading Market Players |
|---|
| Schuler Group |
| AIDA Engineering |
| Komatsu Industries |
| Amada |
| LVD Group |
| Macrodyne Technologies |
| Neff Press |
| Erie Press Systems |
| Bosch Rexroth |
| Others |
Value Network & Pricing Analysis
Tariff exposure on permanent-magnet servo motors and variable-frequency drives from China determines both pricing tier spreads and supply chain shape in the trim press market. OEM procurement teams now face thirty to fifty percent capital outlay premiums for servo-electric architectures, forcing tiered sourcing strategies that segregate German and Japanese component streams from price-sensitive mechanical alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates trim press procurement. Premium tiers attach to servo-press platforms with IEC 62443 cybersecurity certifications and embedded engineering services from Schuler Group and AIDA Engineering. Standard tiers capture mechanical clutch-brake systems with ISO 16092 safety compliance for tier-one automotive stampers. Economy tiers serve pneumatic and legacy hydraulic installations in consumer goods packaging where distributor channels retain relevance. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in standard-tier mechanical presses is intensifying because tier-two stampers in the United States and Germany extend replacement cycles. Electronics manufacturers in Taiwan and South Korea exhibit highest price sensitivity due to batch-flexibility requirements, while German automakers show least sensitivity given tolerance mandates for body-in-white production.
Supply Chain Analysis
Permanent-magnet motors, precision ball screws, and safety-rated control systems feed from concentrated manufacturing bases in Germany, Japan, and China. Servo drive production draws from Bosch Rexroth facilities in Germany and domestic suppliers in Japan's Kansai region. Raw material dependencies span rare-earth magnet processing, high-grade steel forgings for press frames, and specialized hydraulic fluids for ultra-high-capacity installations. Single-source vulnerability concentrates in rare-earth magnet supply chains tethered to Chinese processing facilities. Distribution runs through direct manufacturer contracting for large automotive stampers, while secondary electronics clusters and appliance manufacturers retain distributor relationships for lower-complexity equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trim press market rewards vendors who control scarce mechatronics engineering talent and captive die-design capabilities. Servo-press diagnostics and warm-forming process simulation expertise now outpaces vocational pipeline output across Germany and Japan.
For Market Incumbents: Entrench position by deepening backward integration into permanent-magnet motor supply chains and establishing EU-based engineering centers to accelerate CE marking timelines. Schuler Group's captive engineering services model provides template for anchoring long-term contracts with direct manufacturer procurement teams. Defend against Asian servo-specialist encroachment by hardening automation stacks around IEC 62443 cybersecurity certifications before emerging players achieve scale. For New Entrants and Emerging Players: India's PLI scheme corridors in Maharashtra and Tamil Nadu offer the most penetrable geographic entry point for servo-press assembly operations. Pune's emerging tool-and-die cluster reduces commissioning friction for first-mover vendors establishing local presence. Target tier-two automotive stampers with hybrid financing models that bridge servo-electric capital premiums against energy-efficiency payback timelines. Partner with German or Japanese component suppliers to bypass rare-earth magnet supply vulnerabilities. For Investors and Strategic Acquirers: Motion-control specialists with servo-drive intellectual property represent the priority acquisition archetype for platform integrators seeking technology differentiation. Long-term viability over the coming decade hinges on cybersecurity-hardened control architectures intersecting with industrial automation frameworks. Watch for inflection signals in India's automotive capacity buildout and METI energy-efficiency penetration into Japanese aerospace subcontractor bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Manufacturing | Captures margin pools from permanent-magnet motor supply chains while reducing tariff exposure on Chinese-sourced components. |
| EU Engineering Center Establishment | Accelerates CE marking timelines under Machinery Directive and anchors direct manufacturer relationships with Stuttgart-based automotive OEMs. |
| Cybersecurity Certification Investment | Enables premium pricing for IEC 62443-hardened platforms as OEMs consolidate procurement around connected safety architectures. |
| Local Assembly Operations in India | Captures PLI scheme incentives for advanced manufacturing equipment while reducing logistics costs to Maharashtra and Tamil Nadu stampers. |
| Die Engineering Talent Acquisition | Addresses thermomechanical simulation scarcity for warm-forming process design in high-strength aluminum alloys. |
Research Methodology
Cross-validation between primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchors the qualitative findings against secondary validation. Equipment utilization data from customs and trade filings, SEC disclosures by listed industrial machinery manufacturers, and production statistics from automotive industry associations provide quantitative grounding. Bottom-up triangulation from installed base estimates and top-down reconciliation against capital expenditure disclosures ensure segmentation coherence across mechanical, hydraulic, pneumatic, and servo press categories.
Calibration against historical technology substitution patterns in metalforming equipment shapes the analytical framework across the projection horizon. Segmentation dimensions include drive architecture, end-use vertical, capacity tier, and control sophistication level. CAGRs derive from regression analysis of equipment replacement cycles, energy-efficiency mandate adoption curves, and automotive production forecasts. Warm-forming process adoption for electric vehicle battery enclosures and aerospace alloy forming intensity provide industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese equipment manufacturers or accelerated rare-earth magnet supply diversification would shift outcomes. Cross-checking against automotive OEM capital expenditure disclosures and METI energy-efficiency compliance timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
CNC Leather Cutting Machine Market
Tools
Pneumatic Marking Machines Market
Tools
Allen Key Market
Tools
Hand Saw Market
Tools
Mechanical Springs Market
Tools
Asia Pacific Power Tools & Hand Tools Market
Tools
Broaching Tools Market
Tools
Pneumatic Tools Market
Tools
Global Diamond Tools Market
Tools
Woodpecker Tools Market
Tools
Workholding Tools Market
Tools
Handheld Pipe Cutter Market
Tools
Europe Power Tools Market
Tools
Fine Blanking Tools Market
Tools
Friction Washer Market
Tools
Reamer Market