
 Workholding Tools Market | 2026-2036
Workholding Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Workholding Tools Market Insights
Equipment leasing and pay-per-use tooling programs is reshaping capital deployment among mid-sized machine shops, lowering barriers to precision workholding adoption. SCHUNK leverages its modular quick-change system to sustain premium positioning across European automotive supply chains. Hardinge Inc. anchors North American distribution through vertically integrated spindle and chuck manufacturing. DESTACO competes in robotic end-of-arm tooling by extending its pneumatic clamp expertise into automated assembly lines.
Workholding tools are mechanical, hydraulic, pneumatic, magnetic, or vacuum devices engineered to secure workpieces during machining, assembly, or inspection operations, typically achieving positional repeatability within 0.005 mm for precision-grade fixtures. Their primary industrial purpose is to eliminate dimensional variation, protect surface integrity, and enable unattended multi-axis machining cycles. Hydraulic chucks dominate high-torque metal machining applications where clamping force consistency directly impacts tool life and part conformance. Magnetic workholding represents the fastest-expanding technology segment, displacing mechanical alternatives in five-sided milling of ferrous components where fixture interference limits access. Vises remain the mature volume category across machine shops, though margin pools concentrate in custom aerospace fixtures engineered to AS9100 traceability standards.
OSHA machine guarding regulations mandate interlocked clamping systems for automated cells, while the EU Machinery Directive requires CE-marked workholding with documented force ratings for cross-border equipment sales. ISO 9001 and AS9100 certification frameworks shape supplier qualification thresholds, particularly for aerospace fabricators sourcing fixtures with full material and process traceability. Stakeholders must monitor how NIST cybersecurity guidelines for smart manufacturing intersect with networked hydraulic clamping systems, as digital retrofitting of legacy equipment introduces both compliance obligations and competitive differentiation opportunities.
Market Dynamics
Automated fixture adoption is compressing setup cycles in aerospace fabrication while hydraulic chuck digitization forces incumbent suppliers to retrofit legacy mechanical portfolios for networked shop floors.
Growth Catalysts
- EU Machinery Directive CE marking:Cross-border equipment sales now require documented force ratings, accelerating replacement of uncertified mechanical clamps in European metalworking corridors.
- Five-sided milling demand:Aerospace fabricators specify magnetic workholding to eliminate fixture interference on complex titanium geometries, pulling magnetic chuck installations into high-mix production cells.
- Germany precision engineering concentration:Stuttgart-to-Dresden toolmakers integrate smart hydraulic chucks into Industry 4.0 workflows, creating reference architectures adopted by tier-two suppliers.
Market Restraints
- Neodymium price volatility:Magnetic workholding systems face input cost swings from rare-earth supply concentration in Chinese processing facilities, squeezing margin predictability for European chuck manufacturers.
- AS9100 certification timelines:Aerospace fixture qualification requires 18-24 month material traceability documentation, freezing smaller toolmakers out of tier-one supply chains.
- Mechanical vise substitution ceiling:General machine shops resist hydraulic upgrade costs for low-volume jobs, capping premium technology penetration in the volume tier.
Strategic Opportunities
- India PLI scheme for precision manufacturing:Domestic machine tool builders qualify for production-linked incentives when sourcing CE-marked workholding, opening captive demand for European hydraulic chuck suppliers.
- Equipment leasing penetration:Pay-per-use tooling programs lower capital barriers for mid-sized German automotive subcontractors, converting upfront fixture purchases into recurring revenue streams.
- NIST cybersecurity guidelines:Networked clamping systems that embed encrypted force-feedback protocols capture preference among US defense contractors modernizing legacy machining cells.
Industry Challenges
- Multi-axis programming competency gaps:Automated fixture operation requires CAM integration skills scarce in aging US toolroom workforces, delaying unattended machining deployment.
- Retrofit capex burden:Legacy hydraulic systems demand sensor and actuator upgrades for Industry 4.0 connectivity, forcing mid-cap fabricators into staged modernization programs.
- ISO 9001 traceability reconciliation:Smart chuck data logs must align with existing quality management system documentation, creating IT integration friction for tier-two suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workholding Tools Market |
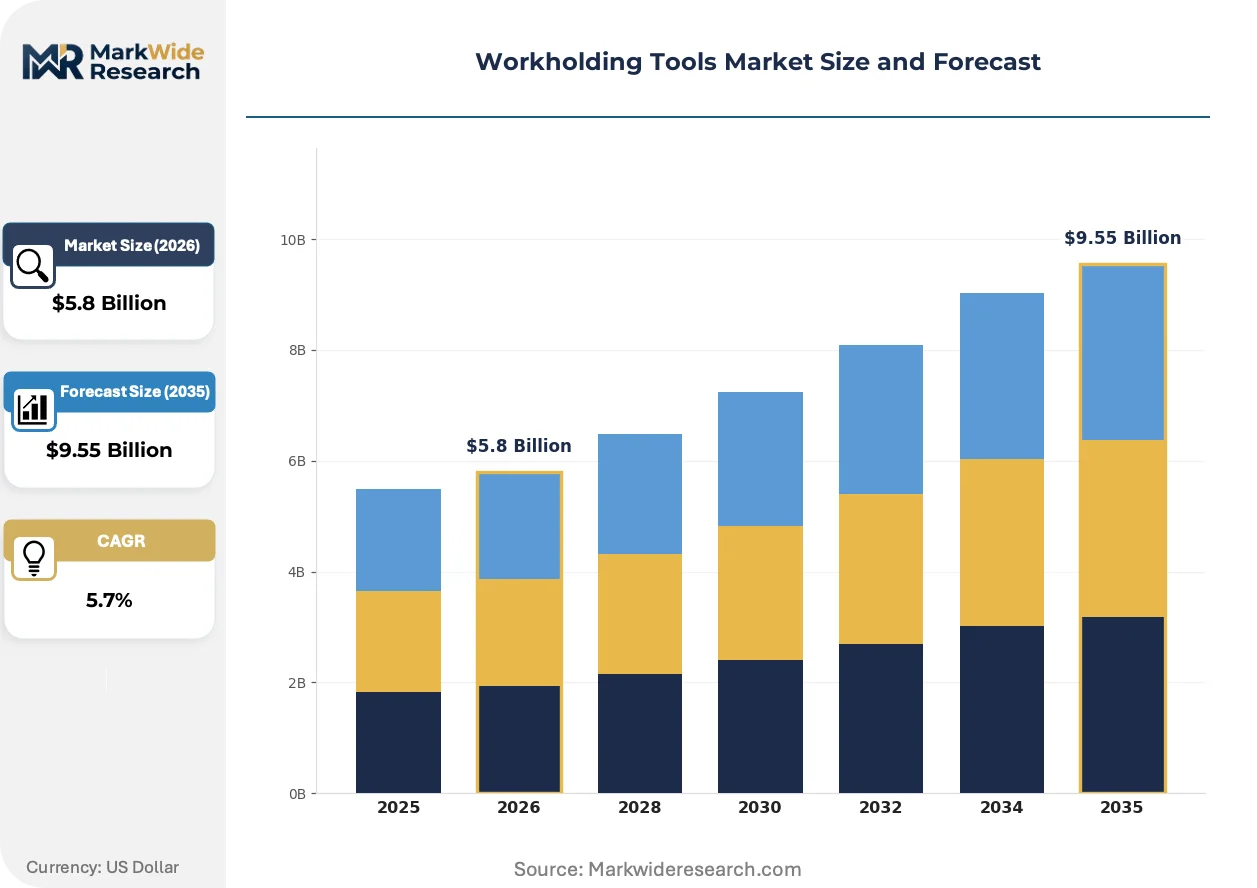
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chucks, Clamps, Vises, Fixtures, Collets Technology: Hydraulic, Pneumatic, Mechanical, Magnetic, Vacuum Application: Metal Machining, Woodworking, Aerospace Component Manufacturing, Precision Engineering End User: Machine Shops, Tool & Die Makers, Aerospace Fabricators, Electronics Assemblers |
| Companies Covered | Hardinge Inc., SCHUNK, Röhm GmbH, Jergens Inc., Kurt Workholding, DESTACO, Kitagawa, LMC Workholding, Carr Lane Manufacturing Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workholding Tools Market Trends and Innovations
Digital retrofitting of mechanical clamping systems is fragmenting competitive advantage between sensor-embedded premium suppliers and cost-optimized mechanical incumbents.
Permanent-electro magnetic chucks combine residual magnetism with electrical pulse control, eliminating continuous power draw during machining cycles. Japanese automotive stamping houses adopt these systems for 24-hour unmanned press lines. The technology is rendering obsolete traditional electromagnetic alternatives that require sustained current and thermal management infrastructure.
OSHA machine guarding standards now mandate interlocked clamping systems for automated cells, forcing pneumatic fixture suppliers to redesign valve architectures for safety-rated control circuits. US metal fabricators in Michigan and Ohio face 90-day compliance windows for existing robotic welding stations, accelerating replacement of legacy manual clamp configurations.
Outcome-based tooling contracts now bundle fixture maintenance with per-part charging metrics, displacing capital purchase models among mid-sized German automotive suppliers. Leasing providers assume obsolescence risk while capturing lifecycle value through predictive wear monitoring. This shift concentrates most visibly in Baden-Württemberg, where tier-two drivetrain suppliers face margin pressure from OEM consolidation.
Workholding Tools Market Segmentation
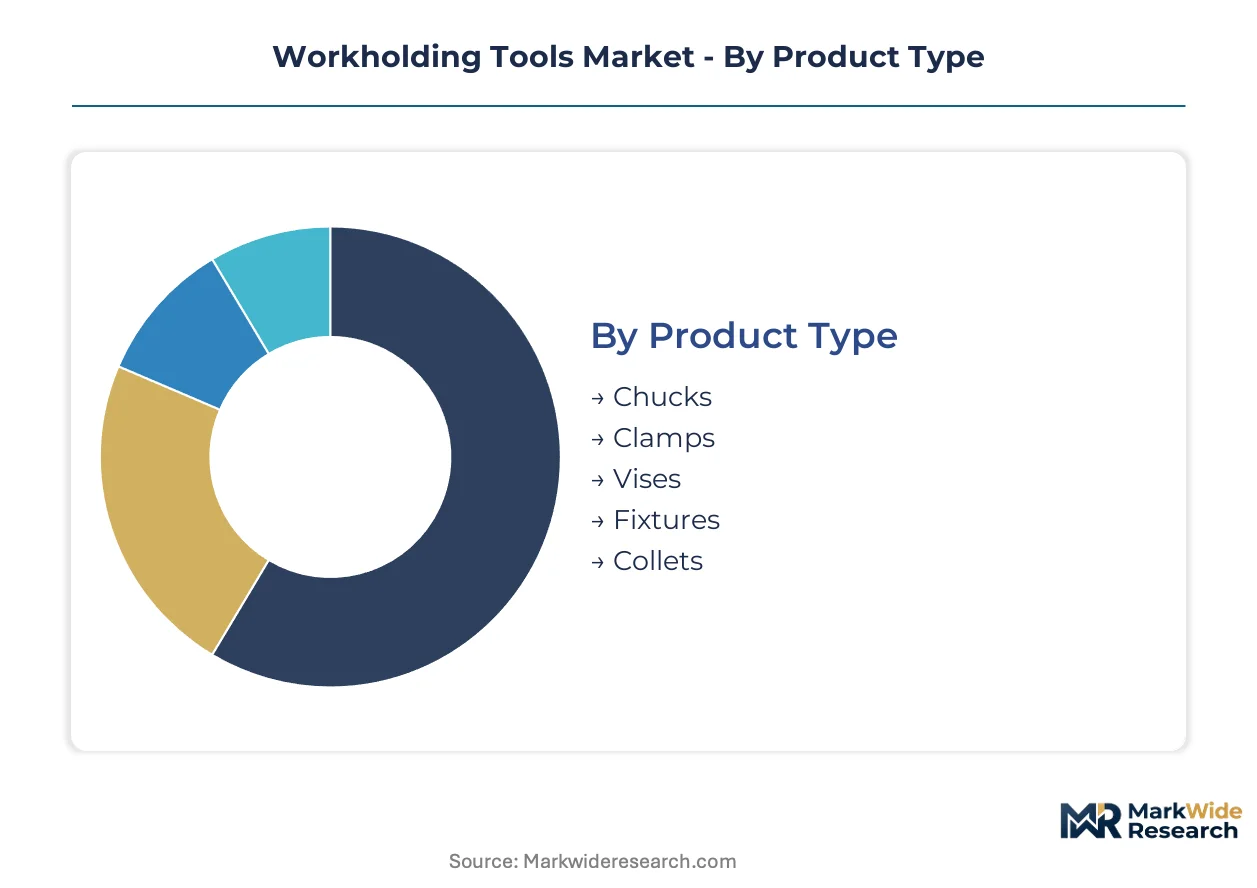
Workholding tool selection dictates maintenance scheduling, spare parts logistics, and field service deployment intensity. Segmentation reveals where aftermarket revenue concentrates and which technology shifts force service model reinvention.
Product Type:
After-sales service intensity varies sharply across product categories, with precision fixtures demanding calibration contracts and high-wear clamps generating replacement part volume.
- Chucks:Self-centering and independent jaw configurations deliver clamping force repeatability within 0.01 mm for CNC turning centers. German automotive subcontractors in Baden-Württemberg specify smart hydraulic chucks with embedded force sensors, triggering predictive maintenance alerts before spindle damage occurs.
- Clamps:Pneumatic swing clamps and manual toggle clamps secure workpieces during welding and assembly cycles. DESTACO's robotic end-of-arm tooling extensions dominate automated assembly lines in Michigan and Ohio, where OSHA machine guarding mandates interlocked clamping systems.
- Vises:Machine vises remain the volume workhorse across general-purpose machine shops, with Kurt and Gerardi models commanding premium positioning through hardened steel construction and quick-change jaw systems.
- Fixtures:Custom aerospace fixtures engineered to AS9100 traceability standards require 18-24 month qualification cycles, freezing smaller toolmakers out of tier-one supply chains.
- Collets:Precision collets for tool holding and workpiece gripping deliver sub-0.005 mm runout for Swiss-type lathes and grinding applications.
By volume, Vises leads. By growth pace, Fixtures is ahead.
Technology:
Cost tier stratification separates capital-intensive hydraulic systems from entry-level mechanical alternatives, with magnetic technology disrupting mid-market positioning.
- Hydraulic:High-pressure hydraulic chucks generate consistent clamping force across temperature variations, protecting carbide tooling in titanium machining. Stuttgart-to-Dresden toolmakers integrate these into Industry 4.0 workflows, creating reference architectures for networked shop floors.
- Pneumatic:Compressed-air actuation delivers rapid clamp cycling for automated cells, with valve architectures redesigned for safety-rated control circuits under updated OSHA standards.
- Mechanical:Screw-operated and cam-actuated clamps persist in low-volume job shops where hydraulic upgrade costs face capital constraints.
- Magnetic:Permanent-electro magnetic chucks eliminate continuous power draw, displacing electromagnetic alternatives in Japanese automotive stamping houses running 24-hour unmanned press lines.
- Vacuum:Porous and non-porous vacuum workholding secures non-ferrous and composite materials where magnetic or mechanical clamping risks surface damage.
Mechanical technology holds installed base dominance. Magnetic systems are climbing the fastest.
Application:
Application segmentation tracks how tolerance requirements and batch size interact to determine fixture complexity and supplier qualification thresholds.
- Metal Machining:Turning, milling, and grinding operations demand workholding that withstands cutting forces while preserving dimensional stability across thermal cycles.
- Woodworking:CNC routers and panel processing equipment use vacuum and mechanical clamps optimized for dust-laden environments and lower force requirements.
- Aerospace Component Manufacturing:Titanium and Inconel machining for turbine disks and structural brackets specifies magnetic workholding to enable five-sided access without fixture interference.
- Precision Engineering:Medical device and instrumentation fabricators in Germany's precision engineering corridor require 0.005 mm repeatability and full process traceability.
Metal Machining commands the largest addressable base. Aerospace Component Manufacturing shows the steepest expansion trajectory.
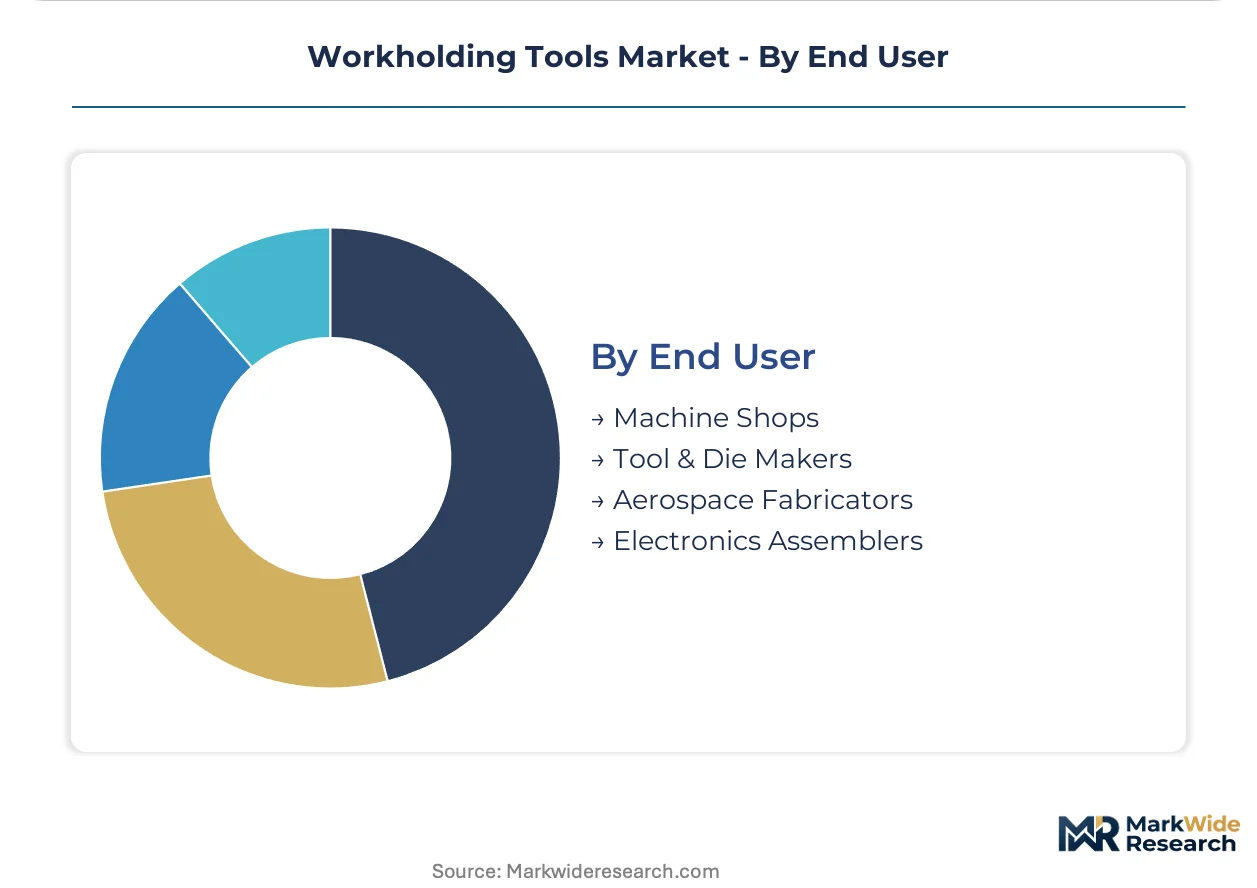
End User:
Customer type determines procurement patterns, with aerospace fabricators imposing certification barriers that general machine shops cannot satisfy.
- Machine Shops:General-purpose job shops purchase standardized vises and chucks through distributor networks, resisting hydraulic upgrades for low-volume work.
- Tool & Die Makers:Mold and die fabricators require high-precision fixtures with rapid setup capabilities to accommodate prototype-to-production transitions.
- Aerospace Fabricators:Tier-one suppliers source AS9100-certified fixtures with full material and process traceability, consolidating procurement among qualified vendors.
- Electronics Assemblers:PCB handling and semiconductor packaging equipment uses precision collets and vacuum chucks optimized for fragile substrates.
Machine Shops represent the broadest installed base. Aerospace Fabricators are gaining share fastest on technology upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workholding tools flow disproportionately from German precision engineering clusters toward aerospace fabricators in North America and Asia. Import dependence for magnetic chuck components concentrates in Japanese automotive stamping corridors, while hydraulic system exports dominate transatlantic trade lanes serving automated machine shops.
Germany
Stuttgart-to-Dresden toolmakers integrate smart hydraulic chucks into Industry 4.0 workflows, creating reference architectures adopted by tier-two automotive suppliers. The EU Machinery Directive mandates CE-marked workholding with documented force ratings, accelerating replacement of uncertified mechanical clamps. Baden-Württemberg hosts the densest concentration of precision fixture manufacturers serving BMW and Mercedes-Benz drivetrain subcontractors.
United States
Michigan and Ohio metal fabricators face compressed compliance windows for OSHA machine guarding standards on robotic welding stations. The NIST cybersecurity guidelines for smart manufacturing intersect with networked hydraulic clamping systems, creating procurement preference among defense contractors. Greater Detroit anchors North American demand for automated fixture systems in automotive powertrain machining.
Japan
Automotive stamping houses adopt permanent-electro magnetic chucks for 24-hour unmanned press lines, displacing electromagnetic alternatives. METI industrial standards shape chuck performance certification requirements for export-bound machine tools. Nagoya's Chubu region concentrates precision workholding R&D serving Toyota's just-in-time production networks.
India
The PLI scheme for precision manufacturing creates captive demand for CE-marked hydraulic chucks among domestic machine tool builders. Machine shops in Pune and Chennai resist premium technology upgrades for low-volume jobs, capping penetration rates. Gujarat's emerging automotive cluster attracts European fixture suppliers seeking production-linked incentive qualification.
China
Rare-earth processing concentration in Chinese facilities generates neodymium price volatility for magnetic workholding system manufacturers. GB standards for machine tool safety create parallel certification tracks alongside ISO frameworks. Yangtze River Delta fabricators source hydraulic chucks for five-axis machining centers serving domestic aerospace programs.
Workholding Tools Market Competitive Landscape
On the supply side, the industry is tiered between precision-grade fixture specialists and volume-driven mechanical clamp manufacturers. Three archetypes dominate: German hydraulic system integrators with Industry 4.0 connectivity, Japanese magnetic chuck innovators, and North American distributors with vertically integrated spindle portfolios. Competitive moves concentrate on modular quick-change system licensing and predictive maintenance service bundling.
Among German-based precision engineering groups, SCHUNK and Röhm GmbH occupy positions within the premium hydraulic tier, while Hardinge Inc. anchors North American distribution through captive spindle manufacturing. These three exemplify divergent strategic postures: European modularity, Japanese magnetic innovation, and American vertical integration into rotating equipment.
| Leading Market Players |
|---|
| Hardinge Inc. |
| SCHUNK |
| Röhm GmbH |
| Jergens Inc. |
| Kurt Workholding |
| DESTACO |
| Kitagawa |
| LMC Workholding |
| Carr Lane Manufacturing Co. |
| Others |
Pricing and Supply Chain Analysis
Neodymium price volatility in Chinese rare-earth processing facilities determines both three-tier pricing spreads across premium magnetic chucks and economy mechanical vises and the geographic shape of component sourcing networks. Aerospace fabricators absorbing AS9100 certification costs face divergent supply chain configurations from general machine shops optimizing for spot purchasing flexibility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium hydraulic chucks with embedded force sensors command spreads based on ISO 9001 certification grade and predictive maintenance bundling, while economy mechanical vises compete on volume scale. Pricing pressure stems from rare-earth cost compression in magnetic systems, with tier-one aerospace fabricators showing least price sensitivity due to traceability mandates and job shops exhibiting highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Extended payment terms from German precision engineering clusters now stretch 90-120 days for tier-two automotive subcontractors, reshaping working capital requirements across the network. Component manufacturing concentrates in Germany, Japan, and China, with rare-earth magnet production anchored in Chinese processing facilities and precision hydraulic systems sourced from Stuttgart-to-Dresden corridors. Single-source vulnerability runs through neodymium supply concentration, while distribution feeds from captive OEM procurement teams in Baden-Württemberg and distributor networks serving North American machine shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The workholding tools market sits in early-cycle recovery as aerospace production rates normalize and capital equipment replacement accelerates across automated fabrication cells.
For Market Incumbents: Harden defensive positioning by deepening backward integration into sensor-embedded chuck manufacturing and locking long-term rare-earth supply agreements with Chinese processors. Magnetic workholding substitution threatens mechanical vise margins, making predictive maintenance service bundling the critical retention lever against leasing providers. For New Entrants and Emerging Players: Pursue white-space capture in India's PLI-qualified precision manufacturing corridor, where domestic machine tool builders seek CE-marked hydraulic chucks for incentive eligibility. Equipment leasing penetration among mid-sized German automotive subcontractors offers the most penetrable entry vector, with pay-per-use tooling contracts providing recurring revenue anchoring against capital purchase resistance. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-grade fixture specialists with AS9100 certification infrastructure. Long-term viability hinges on cybersecurity-embedded smart manufacturing integration over the next decade. Acquisition targets should demonstrate NIST-aligned force-feedback protocols and established aerospace traceability documentation. Watch for inflection in India PLI scheme utilization rates as domestic machine tool buildout accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Chuck Digital Retrofit | Embedded force sensors in hydraulic chucks capture preference among Stuttgart automotive subcontractors modernizing Industry 4.0 workflows. |
| Permanent-Electro Magnetic Patent Licensing | Japanese automotive stamping houses adopting 24-hour unmanned press lines drive technology transfer demand across Asian manufacturing corridors. |
| AS9100 Certification Fast-Track | Accelerated qualification timelines unlock tier-one aerospace procurement access currently frozen out by 18-24 month documentation cycles. |
| Outcome-Based Leasing Expansion | Pay-per-use tooling programs convert upfront fixture purchases into recurring revenue streams among margin-pressed German drivetrain suppliers. |
| Cybersecurity Protocol Integration | NIST-aligned encrypted force-feedback systems capture US defense contractor preference for networked legacy machining cell modernization. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at tier-one aerospace fabricators, aftermarket service heads at hydraulic system distributors, OEM procurement teams in German automotive supply chains, and maintenance directors at US metalworking shops, then refined against secondary validation from customs trade data, SEC 10-K filings of listed precision tool manufacturers, VDMA machine tool order statistics, and AS9100 certification registry databases. Bottom-up demand modeling across end-user segments triangulated against top-down production capacity assessments.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeling spanning product type, technology tier, application intensity, and end-user procurement sophistication. CAGRs derived from production capacity expansion schedules, replacement cycle analysis, and technology substitution curves. Industry-specific forecast inputs included neodymium price trajectory assumptions and EU Machinery Directive enforcement intensity across European metalworking corridors.
Macroeconomic conditions sit as an overlay; deviation in aerospace production rates, rare-earth export restrictions, or German automotive capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and technology adoption elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Vertical Milling Machine Market
Tools
Engraver Machine Market
Tools
Wood-Sanding Machine Market
Tools
Power Press Machines Market
Tools
Deburring Tool Market
Tools
Allen Key Market
Tools
Hacksaw Blades Market
Tools
Cold and Hot Tool Steel Market
Tools
Floor Saw Market
Tools
Edge Banding Machine Market
Tools
End Milling Machine Market
Tools
Shape Moulding Machines Market
Tools
China Power Tools and Hand Tools Market
Tools
Clamps Market
Tools
Vinyl Bending Machine Market
Tools
Digital Laser Levels Market