
 Impact Wrenches Market | 2026-2036
Impact Wrenches Market Size, Share, and Industry Trends Forecast 2026-2036
Impact Wrenches Market Foresight
Aftermarket service revenue for battery pack refurbishment and tool calibration is tilting margin pools away from pure hardware sales toward recurring lifecycle contracts. Ingersoll Rand leverages its global service network to capture maintenance contracts across heavy-duty fleets. Makita U.S.A., Inc. anchors its position through vertical integration into lithium-ion cell sourcing and charger ecosystems. Hytorc specializes in controlled bolting solutions for energy infrastructure, differentiating through precision torque software rather than raw power specifications.
An impact wrench is a rotary power tool that delivers high torque output via stored rotational energy, typically generating instantaneous torque pulses of 100 to 2,000 foot-pounds through a hammering anvil mechanism to tighten or loosen fasteners without continuous operator reaction force. The device serves primary industrial purpose in assembly line fastening, heavy equipment maintenance, and structural steel erection where manual torque application proves insufficient or unsafe. Cordless electric variants now lead unit growth as brushless motor efficiency and 20-volt battery platforms displace pneumatic lines in mobile construction environments. Ultra high torque pneumatic systems still dominate margin pools in shipbuilding and oil rig assembly where sustained duty cycles exceed battery thermal limits. Compact sizing represents the fastest-growing dimensional category as aerospace maintenance and confined-space manufacturing drive demand for reduced head length and pistol-grip ergonomics.
The United States Department of Labor enforces OSHA vibration exposure limits under 29 CFR 1910.95 and 1926.52, compelling manufacturers to redesign impact mechanisms and add anti-vibration handles to maintain jobsite compliance. The European Union Machinery Directive 2006/42/EC mandates CE marking with noise emission declarations and ergonomic risk assessments, creating a two-tier access structure between certified OEMs and uncertified imports. China's SAMR enforces GB standards for power tool electromagnetic compatibility and battery safety, adding compliance layers for brands seeking domestic production qualification. Stakeholders must monitor regulatory divergence between battery transport classifications and workplace exposure limits as these rules increasingly determine which product architectures can cross borders profitably.
Market Dynamics
Automotive assembly lines are forcing a platform shift from pneumatic to cordless electric systems as lithium-ion energy density crosses thermal thresholds for sustained industrial duty cycles. This transition is compressing margins for legacy pneumatic specialists while opening service revenue pools around battery lifecycle management.
Growth Catalysts
- OSHA vibration exposure mandates:United States workplace safety rules under 29 CFR 1910.95 compel fleet operators to replace aging tools with anti-vibration designs, accelerating replacement cycles in heavy equipment maintenance.
- Stuttgart-Wolfsburg automotive corridor:Germany's concentrated OEM manufacturing footprint generates dense demand for precision fastening tools with Industry 4.0 connectivity protocols.
- Brushless motor efficiency gains:Advanced motor controllers extend cordless runtime by 40% versus brushed equivalents, enabling displacement of compressed air infrastructure in mobile construction sites.
Market Restraints
- Lithium carbonate price volatility:Battery cell input costs swing with commodity markets, compressing hardware margins for cordless variants versus stable pneumatic operating costs.
- Ultra high torque pneumatic lock-in:Shipbuilding and offshore rig assembly require sustained 3,000+ foot-pound duty cycles beyond current battery thermal dissipation limits.
- EU machinery directive compliance layering:CE marking with noise emission declarations and ergonomic risk assessments creates certification friction for uncertified import brands.
Strategic Opportunities
- India PLI scheme for advanced cell manufacturing:Domestic battery production incentives reduce import dependency and enable localized cordless tool assembly for South Asian construction growth.
- Controlled bolting software integration:Energy infrastructure maintenance contracts favor precision torque data logging over raw power specifications, opening subscription revenue streams.
- Refurbishment service networks:Battery pack reconditioning and calibration contracts capture recurring revenue from heavy-duty fleets seeking to extend asset life.
Industry Challenges
- Skilled technician scarcity for brushless motor repair:Advanced electronic diagnostics require training investments that distributor networks struggle to scale across fragmented construction labor markets.
- Dual certification timelines for cross-border sales:Harmonizing OSHA vibration limits with EU machinery directive requirements extends product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impact Wrenches Market |
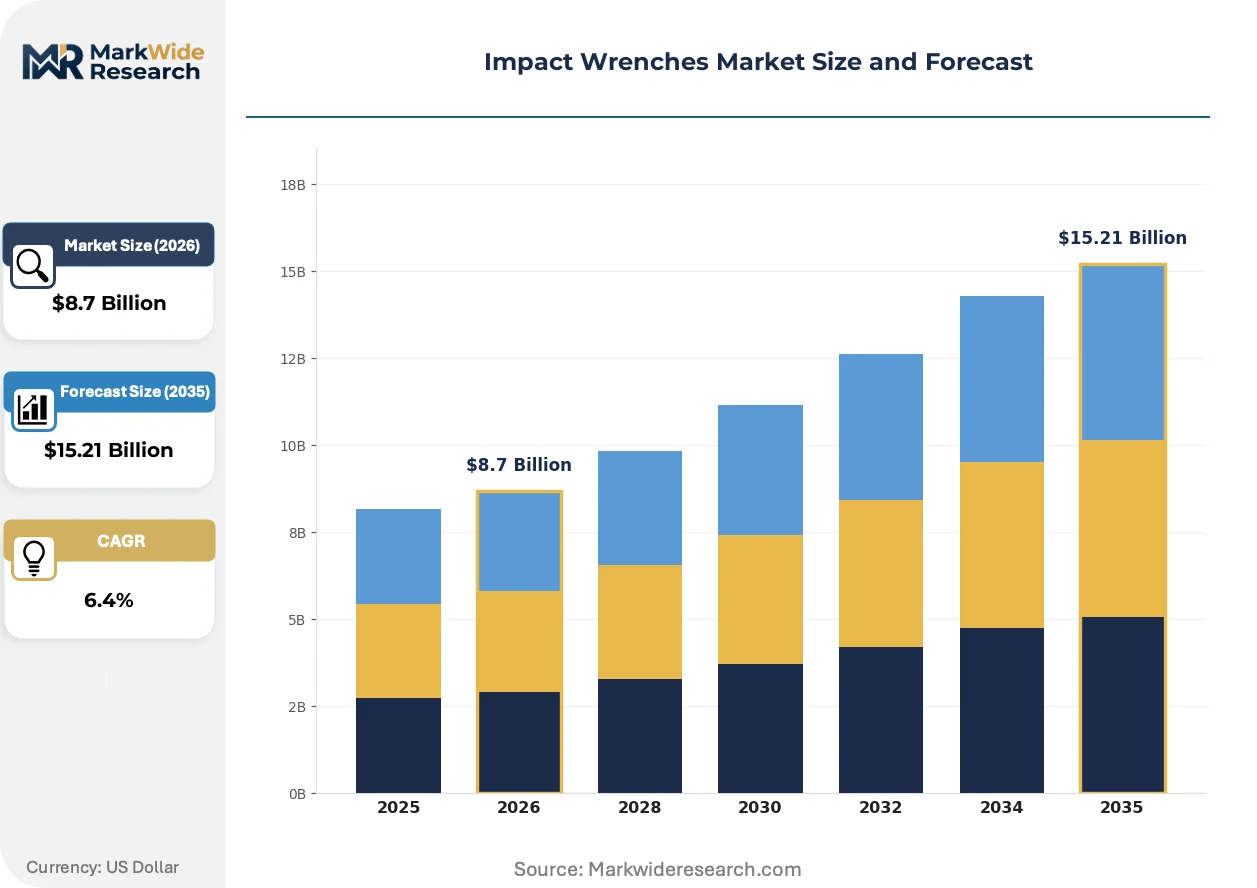
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Pneumatic, Electric, Cordless, Hydraulic Power Rating: Low Torque, Medium Torque, High Torque, Ultra High Torque End User: Automotive, Construction, Manufacturing, Maintenance Size: Compact, Standard, Heavy-duty, Ultra-compact |
| Companies Covered | Mile-X Equipment, Inc., Chicago Pneumatic, Ingersoll Rand, Sioux Tools, Cleco, Makita U.S.A., Inc., TE-CO Manufacturing LLC, Hytorc, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impact Wrenches Market Shifts & Advancements
Tool connectivity and embedded diagnostics are transforming impact wrenches from commodity hardware into data-generating assets, creating new competitive battlegrounds around software ecosystems and fleet management platforms.
Brushless motor controllers with integrated torque sensors and Bluetooth telemetry are digitizing maintenance workflows for automotive OEMs and energy infrastructure operators. Assembly line engineers at plants in Germany and the United States now capture fastening data directly into quality management systems, compressing defect traceability from days to minutes. This capability is digitizing procurement criteria, shifting vendor selection toward software integration depth rather than standalone torque specifications.
The European Union Machinery Directive 2006/42/EC now mandates CE marking with explicit noise emission declarations and ergonomic risk assessments for handheld power tools entering the single market. Manufacturers must redesign impact mechanisms and document anti-vibration handle performance to maintain compliance. Heavy-duty pneumatic suppliers serving shipbuilding yards in Poland and Romania face the steepest redesign burdens, as legacy tool architectures predate current acoustic testing protocols.
Construction fleet managers are unbundling tool ownership from maintenance responsibility, preferring lifecycle contracts that cover battery refurbishment, calibration, and replacement logistics. Equipment rental channels in the United States and Germany now capture 35-40% of cordless unit volume, displacing direct OEM sales for mid-tier performance segments. This shift is most visible in commercial building construction across Texas and Bavaria, where project-based procurement favors operational expenditure models over capital equipment balance sheet entries.
Impact Wrenches Market Segmentation
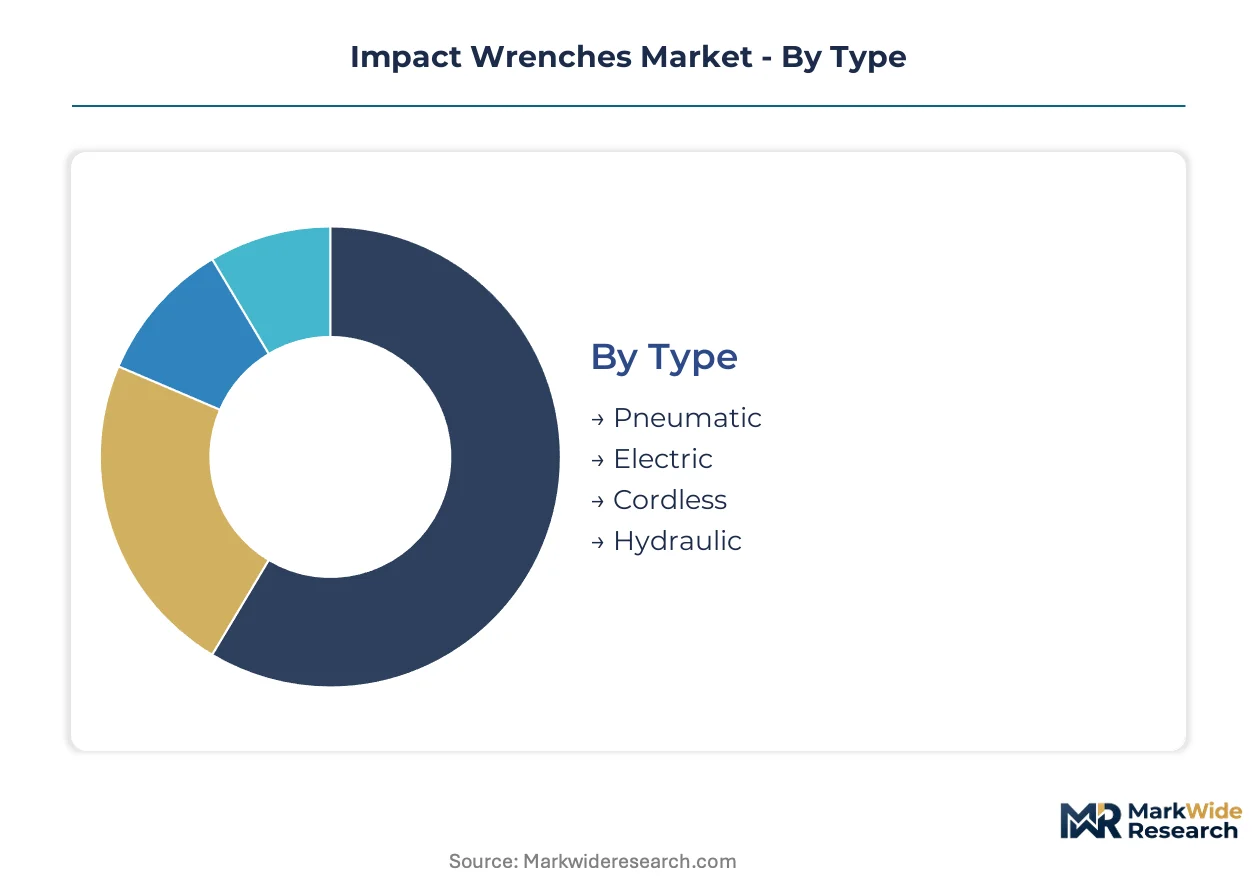
Impact wrench segmentation separates tool architectures by power delivery mechanism, torque specification, and dimensional constraints. Procurement criteria diverge sharply between fixed assembly line installations and mobile field service applications.
Type:
Power source architecture determines mobility constraints, infrastructure requirements, and total cost of ownership across deployment environments.
- Pneumatic:Compressed air systems deliver sustained high torque through vane motors without thermal fade. Shipbuilding yards in Poland and Romania rely on pneumatic infrastructure for 3,000+ foot-pound fastening sequences exceeding battery dissipation limits.
- Cordless:Lithium-ion platforms with brushless motors now displace compressed air lines in mobile construction across Texas and Bavaria. Stuttgart automotive assembly lines specify cordless tools with Industry 4.0 connectivity for quality data logging.
- Electric:Corded AC motor designs serve fixed workstation applications with unlimited duty cycles. German manufacturing corridors favor electric systems for precision torque control in sub-assembly operations.
- Hydraulic:Fluid power systems generate extreme torque density for oil rig assembly and wind turbine bolting. Offshore energy infrastructure in the North Sea specifies hydraulic wrenches for subsea fastening operations.
Pneumatic holds installed capacity. Cordless is rotating up the share rankings.
Power Rating:
Torque classification maps directly to fastener size, material grade, and safety-critical application requirements.
- Ultra High Torque:Exceeding 2,000 foot-pounds for structural steel erection and heavy equipment maintenance. Shipbuilders in Gdansk specify these systems for hull plate assembly where joint integrity is safety-critical.
- High Torque:1,000-2,000 foot-pound range serving commercial vehicle assembly and energy infrastructure. Texas oilfield maintenance contractors favor high-torque cordless platforms for wellhead servicing.
- Medium Torque:General industrial fastening across automotive component plants. Bavarian suppliers deploy medium-torque tools for powertrain sub-assembly where cycle time optimization drives procurement.
- Low Torque:Precision applications in electronics assembly and aerospace component installation. Stuttgart-area aerospace maintenance facilities specify low-torque compact wrenches for confined-space operations.
Ultra High Torque commands premium positioning. Medium Torque is expanding most quickly through cordless displacement.
End User:
Industry verticals impose distinct performance specifications, connectivity requirements, and compliance protocols on tool selection.
- Automotive:Assembly line fastening with traceable torque data and 4.0 protocol integration. Wolfsburg OEM plants require real-time quality management system connectivity for defect traceability.
- Construction:Mobile deployment favors cordless platforms with rental channel procurement. Texas commercial building contractors prefer operational expenditure models over capital equipment ownership.
- Manufacturing:Fixed-station precision fastening with ergonomic compliance mandates. OSHA vibration exposure limits under 29 CFR 1910.95 compel manufacturing fleet replacement cycles.
- Maintenance:Field service operations requiring portable power and calibration traceability. Heavy equipment fleets in the United States contract refurbishment services to extend asset life.
Automotive holds installed capacity. Construction is rotating up the share rankings.
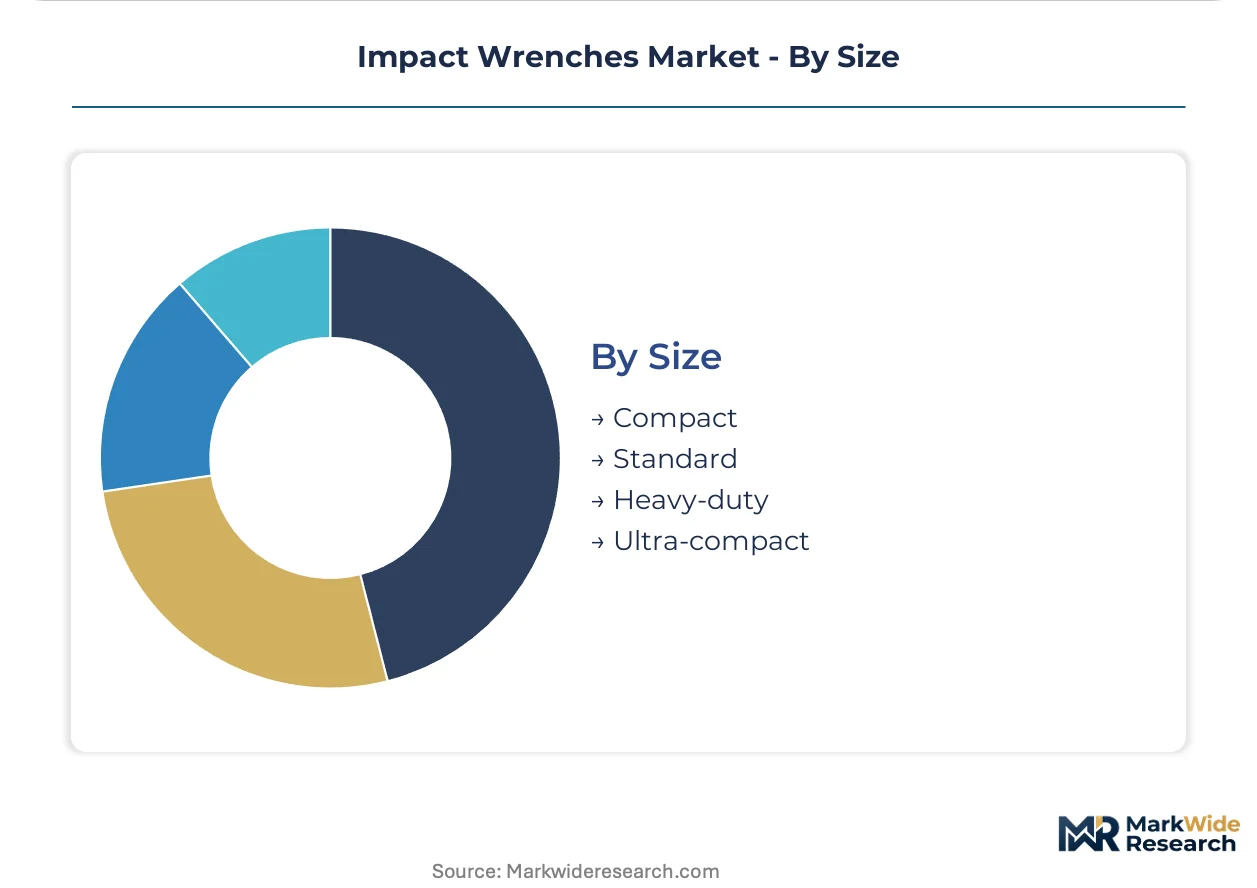
Size:
Dimensional categories align with workspace geometry constraints and operator fatigue management.
- Compact:Reduced head length and pistol-grip ergonomics for confined-space manufacturing. Aerospace maintenance facilities in Hamburg specify compact wrenches for engine bay access.
- Ultra-compact:Miniaturized designs for precision electronics and medical device assembly. Stuttgart-area specialty manufacturers deploy ultra-compact tools for cleanroom fastening operations.
- Standard:Balanced weight-to-power ratio for general industrial applications. German construction sites specify standard sizes for structural steel erection with moderate portability requirements.
- Heavy-duty:Reinforced housings and extended anvils for sustained high-torque duty. Shipyards in Romania favor heavy-duty configurations for hull assembly sequences.
Standard holds installed capacity. Compact is climbing the fastest through aerospace and maintenance demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors in India demonstrate the highest price elasticity, while German automotive OEMs absorb premium pricing for traceability features. This demand-elasticity contrast shapes regional vendor strategies and product architecture decisions.
United States
OSHA vibration exposure mandates under 29 CFR 1910.95 compel fleet replacement cycles in heavy equipment maintenance. The Department of Labor enforces strict workplace safety protocols that disqualify aging pneumatic inventories. Texas commercial building contractors concentrate demand around cordless platforms with rental channel procurement.
Germany
EU Machinery Directive 2006/42/EC mandates CE marking with noise emission declarations and ergonomic risk assessments. Stuttgart-Wolfsburg automotive corridor OEMs specify Industry 4.0 connectivity protocols for assembly line fastening tools. Bavarian suppliers deploy medium-torque cordless systems for powertrain sub-assembly optimization.
China
SAMR enforces GB standards for power tool electromagnetic compatibility and battery safety compliance. Domestic construction growth drives demand for localized cordless tool assembly. Yangtze River Delta manufacturing clusters absorb premium hydraulic systems for shipbuilding and offshore energy infrastructure.
India
PLI scheme incentives for advanced cell manufacturing reduce import dependency for lithium-ion battery packs. Price-sensitive construction contractors favor operational expenditure models over capital equipment ownership. Maharashtra and Gujarat industrial corridors concentrate demand for medium-torque cordless platforms in commercial building projects.
Japan
METI industrial standards emphasize precision torque control and brushless motor efficiency benchmarks. Automotive component suppliers in Aichi Prefecture specify compact wrenches for confined-space manufacturing operations. Kanto region maintenance contractors drive aftermarket service revenue for battery refurbishment and calibration contracts.
Impact Wrenches Market Competitive Landscape
Capability concentration sits with precision torque specialists; scale advantage sits with diversified power tool conglomerates. The vendor base organizes around three strategic archetypes: controlled bolting software integrators, full-line cordless platform providers, and pneumatic infrastructure legacy players. Dominant competitive moves include backward integration into lithium-ion cell sourcing and captive supply of charger ecosystems.
Among diversified industrial equipment manufacturers, Ingersoll Rand anchors the premium service network tier through global maintenance contract capture. Makita U.S.A., Inc. occupies the vertical integration position with in-house production of battery cell supply chains. Hytorc exemplifies the precision torque specialist archetype, differentiating through software-driven controlled bolting solutions rather than raw power specifications.
| Leading Market Players |
|---|
| Mile-X Equipment, Inc. |
| Chicago Pneumatic |
| Ingersoll Rand |
| Sioux Tools |
| Cleco |
| Makita U.S.A., Inc. |
| TE-CO Manufacturing LLC |
| Hytorc |
| Bosch |
| Others |
Supply & Pricing Matrix
Yangtze River Delta port congestion fluctuations directly compress margin pools for cordless tool assemblers sourcing lithium-ion cells from South Korean suppliers, while simultaneously amplifying price premiums for pneumatic systems with stable compressed air economics in German automotive corridors.
Pricing Analysis
Aftermarket service revenue tiers spanning battery refurbishment contracts and calibration subscriptions now drive lifetime value capture more than initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified cordless platforms with Industry 4.0 connectivity from uncertified imports and legacy pneumatic rentals. Cost compression in mid-torque cordless segments is intensifying because lithium carbonate input volatility transfers directly to bill-of-materials pressure. Construction fleet operators in Texas demonstrate highest price elasticity, while Stuttgart-area automotive OEMs absorb premium positioning for traceable torque data integration.
Supply Chain Analysis
Lithium carbonate feedstock from Chilean and Australian mining operations feeds South Korean and Japanese cell manufacturing, with final pack assembly concentrating in China and Vietnam for cost-optimized cordless platforms. Brushless motor controllers, precision-machined anvil mechanisms, and anti-vibration handle composites constitute critical component dependencies. Single-source vulnerability in rare earth magnet supply for high-efficiency motors creates chokepoint exposure. Distribution runs through equipment rental channels and direct OEM fleet contracts rather than traditional retail hardware networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
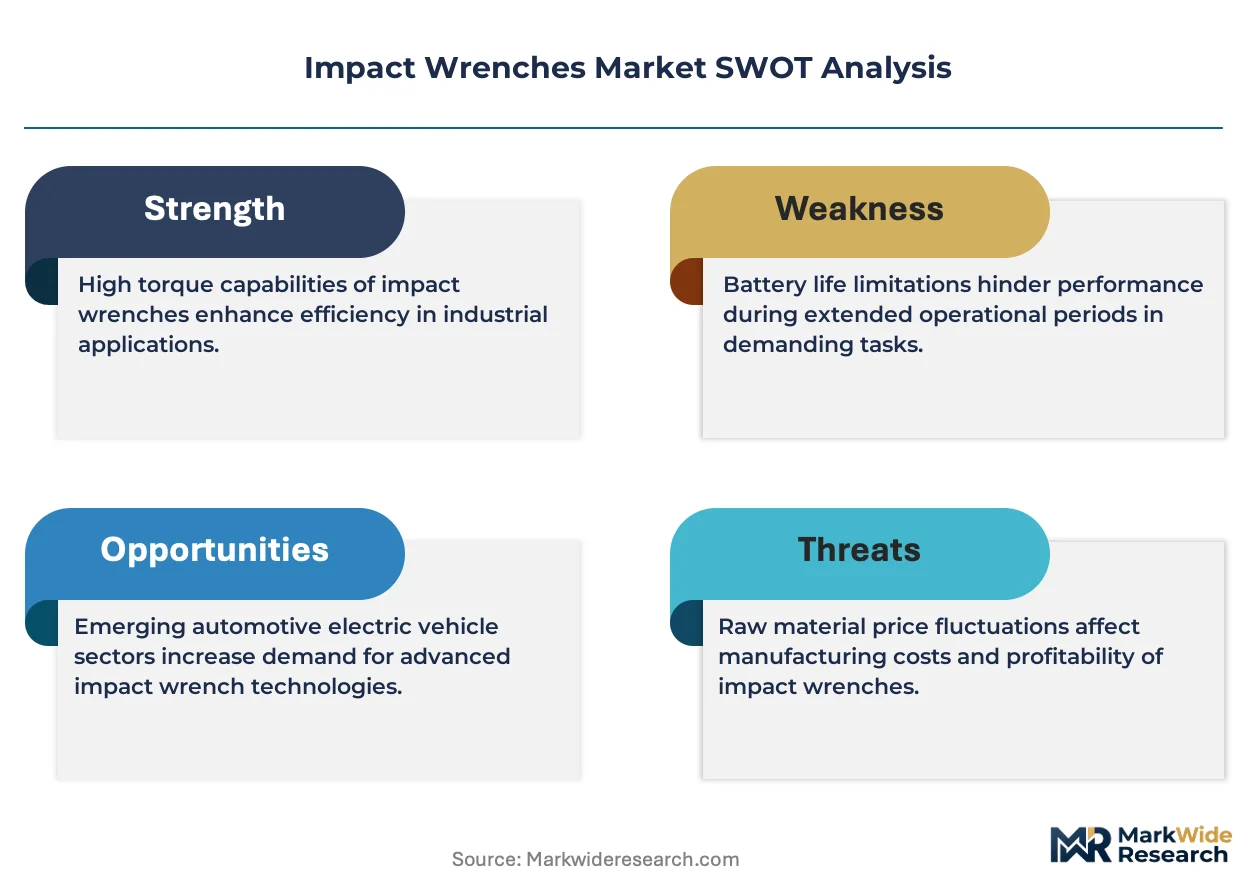
OSHA vibration exposure mandates and EU Machinery Directive compliance layering are forcing platform obsolescence for legacy pneumatic inventories, creating asymmetric growth windows for cordless specialists with certified ergonomic designs.
For Market Incumbents: Entrench service network density across heavy-duty maintenance fleets before battery lifecycle management contracts lock in competitor relationships. Ingersoll Rand's global maintenance contract capture demonstrates the defensive value of preemptive aftermarket positioning. Prioritize backward integration into lithium-ion cell sourcing to buffer margin compression from commodity volatility.
For New Entrants and Emerging Players: Establish a beachhead in India's price-sensitive construction corridor by partnering with PLI-qualified domestic battery assemblers for localized cost structures. Maharashtra and Gujarat industrial corridors offer the most penetrable white-space for medium-torque cordless displacement of pneumatic rentals. Lead with operational expenditure procurement models that mirror Texas contractor preferences rather than capital equipment sales.
For Investors and Strategic Acquirers: Precision torque software specialists with energy infrastructure maintenance contracts represent the highest-conviction acquisition archetype for long-term viability. Hytorc's controlled bolting differentiation illustrates how data-logging capabilities command recurring revenue premiums beyond hardware commoditization. Monitor OSHA enforcement intensity and EU CE marking timeline compression as inflection indicators for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Captive lithium-ion sourcing insulates margins from Chilean carbonate volatility for cordless assemblers. |
| Certification Investment for EU Machinery Directive | CE marking with noise emission declarations unlocks Stuttgart-Wolfsburg automotive corridor procurement. |
| Refurbishment Service Network Expansion | Battery pack reconditioning contracts convert one-time hardware sales into recurring lifecycle revenue. |
| Controlled Bolting Software Development | Precision torque data logging commands subscription premiums in North Sea offshore energy maintenance. |
| Rental Channel Partnership Deepening | Equipment rental capture in Texas and Bavaria displaces direct OEM sales for mid-tier cordless segments. |
Research Methodology
The analysis maps cordless electric, pneumatic, hydraulic, and corded AC architectures, each validated through maintenance directors at heavy equipment fleets, automotive assembly line engineers, procurement leads at energy infrastructure operators, and aftermarket service heads. Primary interviews triangulated against customs trade data for power tool imports, OSHA enforcement records, EU CE marking registries, and SEC filings from diversified industrial equipment manufacturers. Bottom-up unit shipment estimates across torque ratings and power sources reconcile with top-down market value construction.
Assumptions held lithium-ion energy density improvement trajectories and regulatory enforcement intensity fixed at current trajectory levels across the analysis window, while varying construction spending cycles and automotive production volumes as demand-side sensitivities. Segmentation dimensions modeled include power source architecture, torque specification tier, end-use vertical, dimensional category, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to validated base-year estimates, with brushless motor efficiency gains and battery thermal management improvements serving as key technology input variables.
Stress conditions across lithium carbonate price bands, OSHA citation rate acceleration, and EU machinery directive scope expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology substitution rates and compliance timeline rigidity. Cross-checking against IHS Markit industrial equipment production data and national power tool trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Sandblasting Media Market
Tools
Europe Woodworking Power Tools Market
Tools
Mechanical Springs Market
Tools
Air Hammer Market
Tools
Diamond Hole Saw Market
Tools
Woodpecker Tools Market
Tools
Hand and Power Tools Market
Tools
Industrial Ladder Market
Tools
Ratchet Wringer Market
Tools
Water Pump Pliers Market
Tools
Boring-Milling Machines Market
Tools
Machining Centers Market
Tools
Fixed Cutter Bits Market
Tools
Scroll Saws Market
Tools
Lathe Machines Market
Tools
MIG Guns Market