
 Italy Patient Monitoring Market | 2026-2036
Italy Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Patient Monitoring Market Foresight
The EU Medical Device Regulation is repositioning compliance costs for device manufacturers entering Italy. Philips leverages its established service network across northern Italian hospitals to sustain installed-base loyalty. Dragerwerk AG & Co KGaA anchors critical care monitoring through specialized ventilation-integrated platforms. GE Healthcare competes on imaging-to-monitoring workflow convergence in large academic medical centers.
Patient monitoring encompasses continuous or intermittent physiological measurement systems—electrocardiography, pulse oximetry, capnography, non-invasive blood pressure—typically operating at sampling frequencies from 125 Hz to 250 Hz for cardiac signals, with wireless transmission via Bluetooth Low Energy or Wi-Fi 802.11 standards to central nursing stations or cloud repositories. Its primary purpose is early detection of clinical deterioration, enabling intervention before adverse events escalate. Wearable devices and cardiac monitors capture expanding margin pools as ambulatory and post-acute settings extend monitoring beyond traditional bedside boundaries. Telehealth solutions and cloud-based platforms represent the fastest-expanding technology dimension, though hospitals remain the dominant end-user channel by procurement volume and contract value.
Italy's Ministry of Health, the National Agency for Regional Health Services, and CE marking requirements under the EU MDR collectively shape device approval timelines, reimbursement eligibility, and post-market surveillance obligations for manufacturers. The Italian Medicines Agency enforces vigilance reporting that accelerates field safety corrective actions and influences hospital purchasing committees. Stakeholders must monitor how regional health autonomy in Italy fragments procurement standardization and where centralized tenders consolidate supplier selection.
Market Dynamics
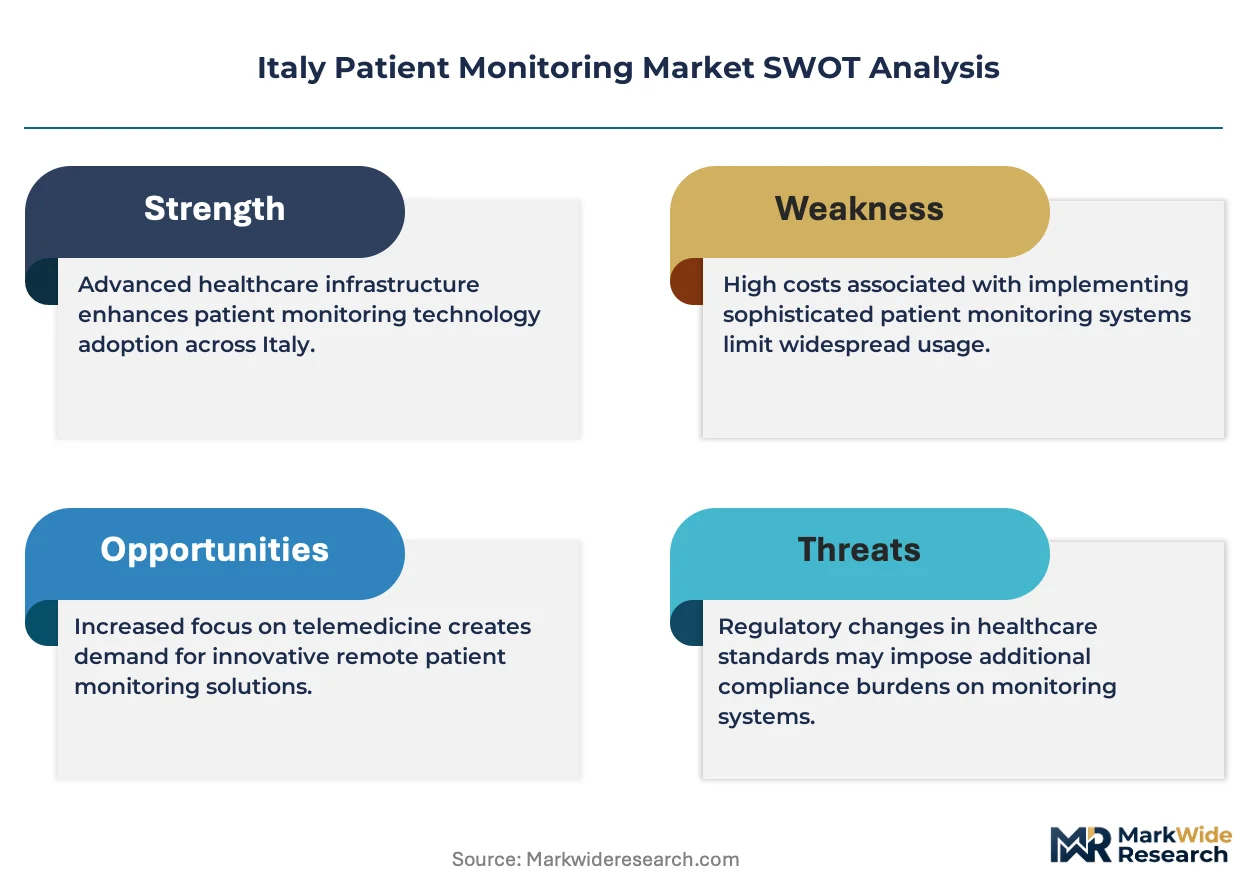
Wireless telemetry and cloud-native architectures are compressing replacement cycles across Italian hospitals, forcing incumbent suppliers to restructure service contracts around data integration rather than hardware maintenance alone.
Growth Catalysts
- EU Medical Device Regulation:The MDR's enhanced clinical evidence requirements favor established manufacturers with robust post-market surveillance infrastructure, accelerating consolidation among notified bodies serving Italy.
- Lombardy regional health system:Lombardy's centralized procurement for connected care infrastructure creates anchor demand that validates wireless monitoring platforms for subsequent regional adoption.
- Bluetooth Low Energy 5.3:Improved power efficiency and range in BLE 5.3 enable continuous ambulatory monitoring without patient mobility constraints, expanding addressable settings beyond traditional bedside deployment.
Market Restraints
- Semiconductor component concentration:Analog front-end chips and specialized sensors for physiological signal acquisition concentrate among Taiwanese and German suppliers, exposing Italian device assemblers to allocation volatility.
- CE marking timeline extension:MDR transition has extended notified body review periods for Class IIa and IIb patient monitors, delaying market entry for iterative product improvements.
- Interoperability fragmentation:Proprietary data formats between competing central station platforms prevent seamless device substitution, locking hospitals into incumbent vendor ecosystems.
Strategic Opportunities
- Emilia-Romagna telehealth expansion:The region's investment in rural connectivity infrastructure creates deployment-ready channels for home-based cardiac monitoring and post-acute surveillance.
- AI-integrated alarm management:Machine learning algorithms that reduce false positive rates are converging with edge computing hardware, creating premium positioning for next-generation central monitoring stations.
- National Recovery and Resilience Plan:PNRR funding streams for digital health transformation provide co-financing mechanisms that accelerate procurement decisions for cloud-connected monitoring systems.
Industry Challenges
- Biomedical engineering talent scarcity:Italian universities produce insufficient specialists in clinical signal processing and medical device cybersecurity, forcing manufacturers to recruit from competing EU markets.
- Legacy central station integration:Hospital IT departments face complex middleware requirements when connecting new wireless devices to installed-base central monitoring architectures from prior-generation suppliers.
- Post-market clinical follow-up burden:MDR mandates for systematic literature review and PMCF studies strain regulatory affairs teams, particularly for small and mid-sized device firms serving niche monitoring applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Patient Monitoring Market |
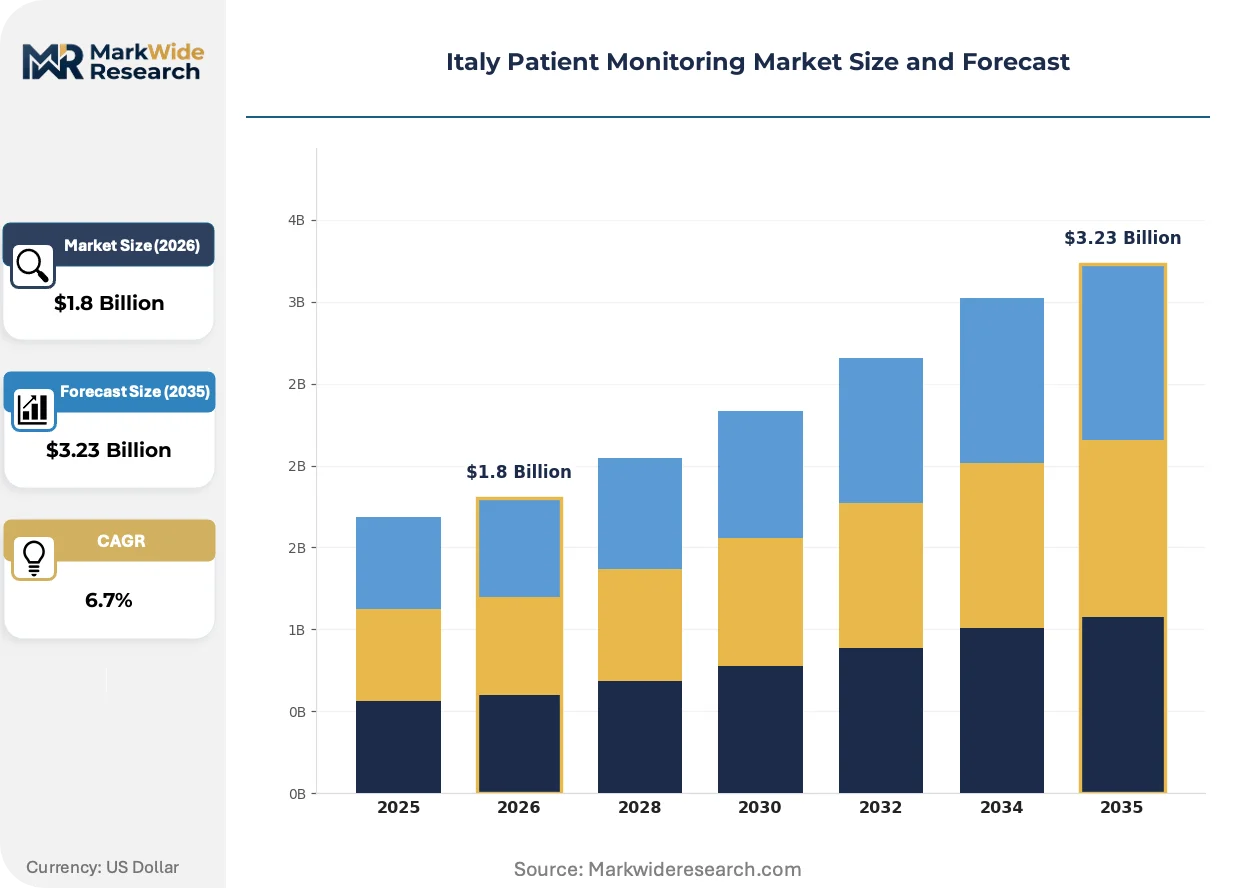
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Vital Signs Monitors, Cardiac Monitors, Neuro Monitoring Systems Technology: Wireless Monitoring, Software-as-a-Service, Telehealth Solutions, Cloud-Based Platforms End User: Hospitals, Home Care Providers, Rehabilitation Centers, Long-term Care Facilities Application: Chronic Disease Management, Emergency Care, Post-operative Monitoring, Preventive Care |
| Companies Covered | Abbott Laboratories, Dragerwerk AG & Co KGaA, Philips, OMRON Corporation, Edwards Lifesciences Corporation, GE Healthcare, Nihon Kohden Corporation, Dexcom Inc, Medtronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Patient Monitoring Market Shifts & Advancements
Italian healthcare providers are reconfiguring monitoring infrastructure around continuous data streams rather than episodic measurement, compressing the boundary between acute and ambulatory care settings.
Multi-parameter wearable patches incorporating ECG, SpO2, and temperature sensing are consolidating discrete bedside devices into single-patient platforms that follow individuals across care transitions. Lombardy's largest hospital networks have accelerated pilot deployments of these systems for post-surgical monitoring. The technology is consolidating previously separate product categories—holter monitors, pulse oximeters, and telemetry transmitters—into unified procurement decisions that favor integrated platform suppliers.
Italy's transposition of the EU AI Act into national law imposes conformity assessment requirements for machine learning algorithms embedded in monitoring devices that automate clinical decision support. Manufacturers must now document algorithmic performance across diverse patient populations before CE marking. Cardiac arrhythmia detection modules face the most stringent scrutiny, with notified bodies demanding prospective validation studies that extend approval timelines by twelve to eighteen months.
Hospital purchasing committees are unbundling long-term service contracts from capital equipment sales, negotiating separate agreements for software maintenance, cybersecurity updates, and predictive analytics subscriptions. This disaggregation favors vendors with modular service architectures over those with rigid bundled offerings. The pattern is most pronounced in academic medical centers in Milan and Bologna, where procurement teams seek operational flexibility amid uncertain technology refresh cycles.
Italy Patient Monitoring Market Segmentation
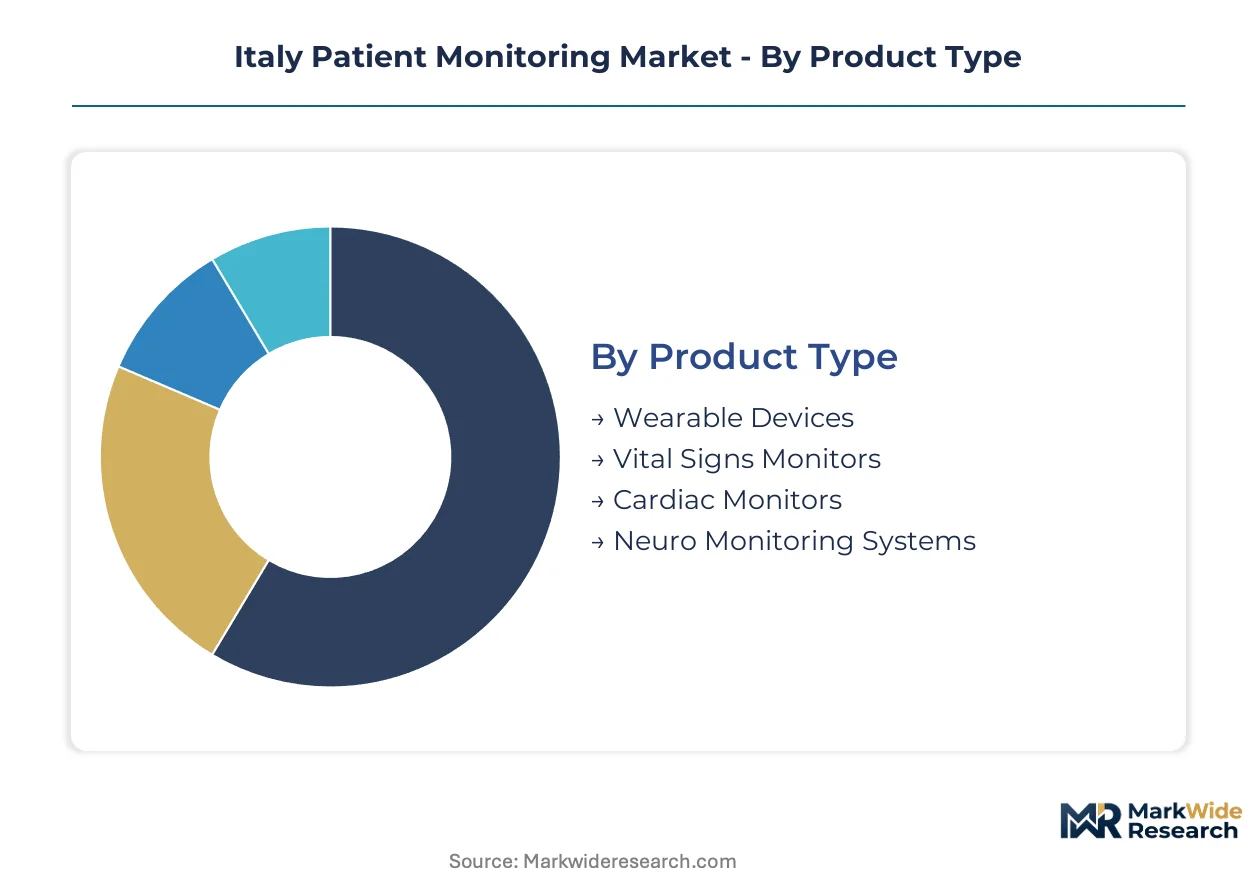
Patient monitoring procurement in Italy fragments across four distinct dimensions, each governed by different stakeholder priorities and reimbursement pathways. Understanding these segment boundaries clarifies where CE marking complexity concentrates and where regional health system tenders create volume anchors.
Product Type:
Supply concentration tilts toward manufacturers with integrated hardware-software capabilities, favoring platforms that span multiple physiological parameters over single-function devices.
- Wearable Devices:Multi-parameter patches incorporating ECG, SpO2, and temperature sensing consolidate previously discrete categories. Lombardy's hospital networks have accelerated pilot deployments for post-surgical ambulatory monitoring, validating wireless form factors for regional procurement standardization.
- Cardiac Monitors:Arrhythmia detection modules face stringent EU AI Act conformity assessments, with notified bodies demanding prospective validation studies that extend approval timelines. Academic medical centers in Milan and Bologna unbundle long-term service contracts from capital sales, seeking operational flexibility.
- Vital Signs Monitors:Bedside multi-parameter systems remain the procurement volume anchor across Italian acute care facilities, though replacement cycles compress as cloud-native architectures displace installed-base central stations.
- Neuro Monitoring Systems:Specialized platforms for intracranial pressure and EEG monitoring concentrate in tertiary neurosurgical centers, with limited vendor competition due to clinical validation requirements.
Today's leader: Cardiac Monitors. Tomorrow's challenger: Wearable Devices.
Technology:
Cost tier differentiation separates premium cloud-native platforms from legacy hardware-dependent systems, with reimbursement eligibility increasingly tied to interoperability certifications.
- Cloud-Based Platforms:Native architectures enable seamless data aggregation across regional health systems, attracting PNRR co-financing for digital health transformation. Emilia-Romagna's rural connectivity investments create deployment-ready channels for these systems.
- Wireless Monitoring:Bluetooth Low Energy 5.3 implementations enable continuous ambulatory surveillance without patient mobility constraints, expanding addressable settings beyond traditional bedside deployment into home-based cardiac monitoring.
- Telehealth Solutions:Remote consultation and asynchronous review capabilities integrate with monitoring data streams, though regional autonomy fragments standardization across Italian health systems.
- Software-as-a-Service:Subscription models for predictive analytics and cybersecurity updates disaggregate from capital equipment sales, favoring vendors with modular service architectures over rigid bundled offerings.
Cloud-Based Platforms command current procurement budgets; Wireless Monitoring gains share fastest as BLE 5.3 deployments scale.
End User:
Customer type determines contract structure complexity, with hospitals demanding enterprise-wide integration while post-acute settings prioritize standalone deployability.
- Hospitals:Centralized procurement committees negotiate multi-year framework agreements, unbundling software maintenance and cybersecurity updates from hardware acquisition. IT departments face complex middleware requirements when connecting new wireless devices to legacy central monitoring architectures.
- Home Care Providers:Patient-operated devices require simplified interfaces and cellular connectivity fallback, with reimbursement pathways still crystallizing under regional health autonomy.
- Rehabilitation Centers:Transitional care monitoring bridges acute and ambulatory settings, creating demand for devices that follow patients across care transitions.
- Long-term Care Facilities:Staffing constraints drive demand for automated alert systems and centralized oversight capabilities, though budget limitations favor refurbished or tier-two equipment.
Hospitals dominate contract value today. Home Care Providers represent the steepest expansion trajectory as telehealth reimbursement stabilizes.
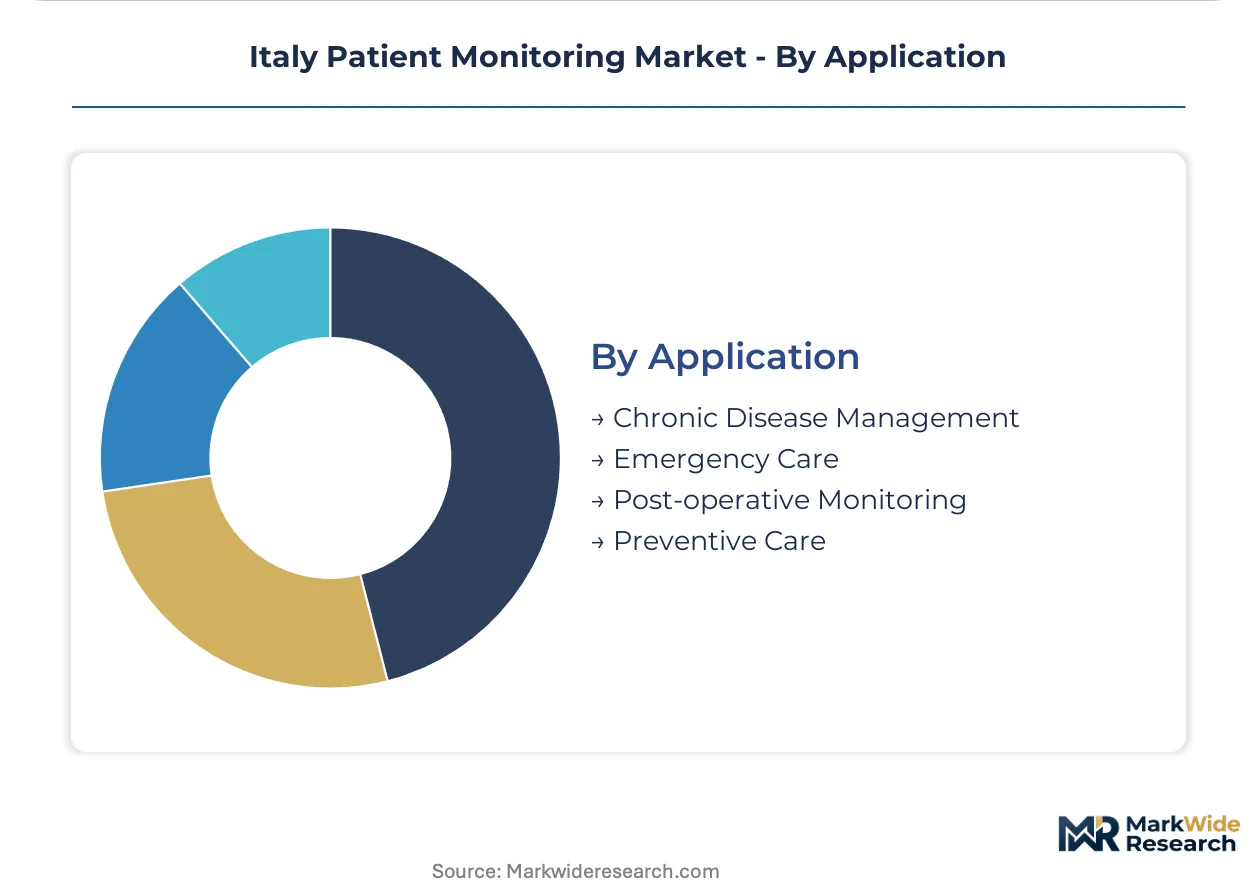
Application:
Application focus shapes regulatory scrutiny intensity, with emergency and post-operative use cases facing the most stringent clinical evidence requirements under MDR.
- Chronic Disease Management:Longitudinal monitoring for heart failure and COPD patients aligns with Lombardy's investment in connected care infrastructure, creating anchor demand that validates platforms for subsequent regional adoption.
- Post-operative Monitoring:Early discharge protocols drive demand for wearable platforms that maintain surveillance fidelity outside acute settings, with AI-integrated alarm management reducing false positive rates.
- Emergency Care:Pre-hospital and resuscitation monitoring requires ruggedized hardware with rapid deployment protocols, concentrating procurement among established critical care suppliers.
- Preventive Care:Population health screening applications face reimbursement uncertainty, limiting deployment to pilot programs and self-pay wellness initiatives.
Post-operative Monitoring captures current investment flows. Chronic Disease Management is climbing the fastest as regional health systems reorient toward longitudinal cost containment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient monitoring technology first achieved clinical scale in Italy through post-war reconstruction of hospital infrastructure in the 1950s and 1960s, with subsequent waves of digital transformation concentrating investment in northern industrial regions where medical device manufacturing clusters had already formed.
Lombardy
Milan's hospital networks drive procurement volume for wireless telemetry systems, with centralized purchasing committees negotiating multi-year framework agreements. The region's health system invests heavily in connected care infrastructure under CE marking requirements from the EU MDR. Academic medical centers in Milan unbundle software maintenance contracts from hardware acquisition, creating demand for modular service architectures.
Emilia-Romagna
Bologna anchors telehealth expansion with rural connectivity investments that create deployment-ready channels for home-based cardiac monitoring. Regional health authorities channel PNRR funding into cloud-connected monitoring systems. The technology cluster around Bologna validates platforms for subsequent adoption across central Italian health systems.
Piedmont
Turin's manufacturing heritage supports medical device component supply chains serving patient monitor assemblers. The regional health system concentrates procurement for critical care monitoring in tertiary centers. Industrial engineering capabilities from the automotive sector transfer into medical device production, strengthening local supplier networks.
Veneto
Padua and Verona hospital networks pilot AI-integrated alarm management systems that reduce false positive rates in cardiac monitoring. Regional procurement standards favor vendors with established service networks. The Veneto health system participates in cross-border tenders with neighboring Austrian and Slovenian regions.
Lazio
Rome's ministry-level regulatory oversight shapes national reimbursement eligibility and post-market surveillance obligations for device manufacturers. The Agenas national agency coordinates regional health system standardization efforts. Hospital procurement in the capital follows centralized tender processes that consolidate supplier selection for high-value monitoring contracts.
Italy Patient Monitoring Market Competitive Landscape
The competitive structure tilts toward diversified health technology conglomerates with integrated hardware-software capabilities. Market concentration favors established manufacturers with robust post-market surveillance infrastructure under MDR requirements. Two strategic archetypes dominate: imaging-to-monitoring workflow convergers and critical care platform specialists. Competitive moves center on unbundling service contracts from capital sales and restructuring around data integration rather than hardware maintenance alone.
Among diversified health technology groups, Philips and GE Healthcare exemplify the imaging-to-monitoring convergence archetype, while Dragerwerk AG & Co KGaA occupies a position within the critical care specialization tier. Abbott Laboratories and Medtronic sit within the wearable and cardiac monitoring segment, reflecting broader industry patterns of portfolio diversification into ambulatory settings. These five named entities represent the competitive anchor points around which procurement decisions in Italian hospitals increasingly cluster.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dragerwerk AG & Co KGaA |
| Philips |
| OMRON Corporation |
| Edwards Lifesciences Corporation |
| GE Healthcare |
| Nihon Kohden Corporation |
| Dexcom Inc |
| Medtronic |
| Others |
Supply & Pricing Matrix
Captive sensor manufacturing by Taiwanese and German semiconductor specialists anchors both supply security and pricing power for Italian patient monitor assemblers facing EU MDR compliance costs. This upstream control over analog front-end chips and specialized physiological signal acquisition components allows tier-one manufacturers to buffer procurement committees against allocation volatility while commanding premium positioning in unbundled service negotiations.
Pricing Analysis
The bundled-versus-unbundled service split now dominates contract architecture across Milan and Bologna hospital networks. SaaS-tiered subscriptions for predictive analytics and cybersecurity updates separate from capital equipment sales, with price differentiation resting on CE marking tier and after-sales service depth. Cost compression in standard-grade bedside monitors intensifies as regional health systems consolidate tenders, while academic medical centers show least price sensitivity for AI-integrated alarm management platforms.
Supply Chain Analysis
CE marking and EU MDR qualification requirements gate supplier participation more than geographic concentration alone. Analog front-end chips and pulse oximetry sensors draw from Taiwan, Germany, and the United States, with single-source vulnerability for BLE 5.3 wireless modules exposing Italian assemblers to allocation delays. Distribution runs through authorized medical device distributors serving regional health system procurement committees, with direct manufacturer relationships reserved for high-value academic medical center contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian patient monitoring has matured into a late-cycle quality story where hospital purchasing committees now prioritize MDR-compliant platforms with validated AI algorithms over lowest-bid hardware procurement.
For Market Incumbents: Acquire specialized AI algorithm validation capabilities to defend against emerging cloud-native entrants unburdened by legacy central station integration obligations. Deepen backward integration into sensor manufacturing to secure allocation priority during semiconductor supply constraints. Strengthen service network density across Lombardy and Emilia-Romagna to capture unbundled software maintenance contracts. For New Entrants and Emerging Players: Home care providers operating under regional health autonomy represent the most penetrable buyer archetype, with reimbursement pathways still crystallizing for patient-operated cardiac monitors. Target rural connectivity corridors in Emilia-Romagna where PNRR co-financing accelerates procurement decisions. Pursue partnership-first go-to-market models with telehealth platform vendors rather than direct hospital sales. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR compliance costs strain regulatory affairs capacity at mid-tier device firms serving niche monitoring applications. Five-to-ten year viability favors targets with established notified body relationships and modular service architectures. Watch for inflection when AI Act transposition into Italian national law triggers acquisition of algorithm validation specialists by diversified health technology conglomerates.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR transition timelines determine competitive entry windows for wireless monitoring platforms. |
| Hospital System Partnership | Lombardy's centralized procurement creates anchor demand validating platforms for regional adoption. |
| Software Companion Development | AI-integrated alarm management modules command premium positioning in academic medical centers. |
| Reimbursement Strategy | Telehealth tariff crystallization under regional autonomy shapes home care provider addressability. |
| Backward Integration | Sensor manufacturing control buffers Italian assemblers against Taiwanese allocation volatility. |
Research Methodology
Coverage spans Lombardy, Emilia-Romagna, Piedmont, Veneto, and Lazio, with primary inputs from each region's hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from Agenas procurement databases, EU MDR guidance documents, and PNRR digital health funding disclosures. Bottom-up demand modeling triangulated against top-down regional health system expenditure patterns.
Granularity-level modeling operated at product type, technology, end user, and application dimensions, with additional disaggregation by regional procurement autonomy cluster. CAGRs were derived from installed-base replacement cycle analysis and telehealth reimbursement trajectory assessment across the projection horizon. Forecast inputs incorporated BLE 5.3 adoption curves and AI Act conformity assessment timeline extensions.
Underlying measurement precision varies by segment; cloud-based platforms and wireless monitoring carry tighter precision than preventive care applications where reimbursement uncertainty persists. Forecasts reflect assumptions about PNRR funding continuity and MDR notified body capacity expansion. A model refresh is warranted upon material change in EU AI Act enforcement guidance or regional telehealth tariff finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Patient Monitoring Pods Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
Middle East and Africa Patient Monitoring Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
Urine Monitoring Systems Market
Patient Monitoring
Multiparameter Patient Monitoring System Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Patient Monitoring Accessories Market