
 Ready-To-Drink (RTD) Protein Beverages Market | 2026-2036
Ready-To-Drink (RTD) Protein Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-To-Drink (RTD) Protein Beverages Market Insights
Single-serve bottle bundling is restructuring how consumers stock protein beverages for weekly consumption. PepsiCo leverages its beverage distribution network to dominate convenience store placement. Nestlé anchors its portfolio through dairy-backed protein formulations with extended shelf stability. Glanbia competes via specialized whey protein isolate technologies that target performance nutrition segments.
Ready-to-drink protein beverages are shelf-stable liquid formulations containing 15–40 grams of protein per serving, manufactured through ultra-high-temperature processing and aseptic filling to ensure microbial safety without refrigeration. These products serve athletes, fitness enthusiasts, and time-constrained consumers seeking portable macronutrient delivery. Whey protein variants occupy the largest volume share due to superior leucine bioavailability and established taste profiles. Plant-based protein formats are expanding fastest as oat, pea, and fava bean blends overcome solubility challenges. Tetra Pak packaging captures margin pools through lightweight logistics and extended ambient shelf life.
FDA nutrition labeling rules and EFSA health claim frameworks constrain how brands communicate muscle recovery benefits on packaging. USDA organic certification and EU organic regulations create tiered market access depending on ingredient sourcing and manufacturing audit trails. Stakeholders must monitor evolving protein content verification standards and sugar taxation thresholds as these will determine which formulations retain retail authorization.
Market Dynamics
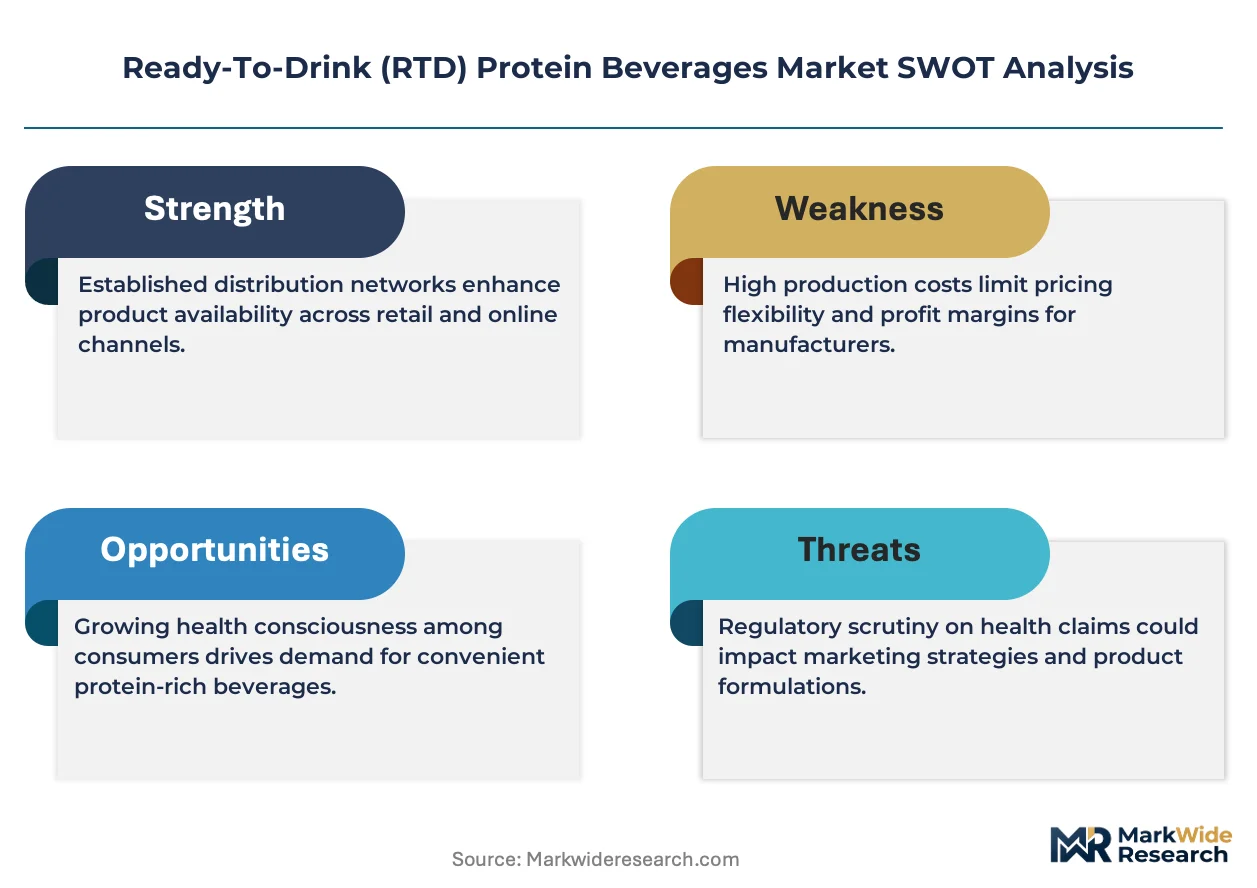
Clean-label formulation mandates from FDA and EFSA are forcing manufacturers to reformulate around artificial sweeteners and synthetic preservatives, compressing product development cycles and raising ingredient qualification costs across the supply base.
Growth Catalysts
- Post-workout recovery protocols:Professional sports teams and collegiate athletic programs are standardizing RTD protein protocols, creating institutional procurement pipelines that stabilize volume commitments.
- EFSA health claim frameworks:Approved muscle maintenance claims on packaging are unlocking retail authorization across EU member states, particularly in Germany and France where pharmacy channels dominate sports nutrition.
- Aseptic filling infrastructure:Capital deployment into Tetra Pak-compatible production lines is extending ambient shelf life to 12 months, enabling distributor inventory pooling and reducing cold-chain dependency.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity price swings tied to New Zealand and EU milk powder auctions create margin compression for mid-tier brands without forward contracting capabilities.
- Supply concentration in flavor houses:Three specialty ingredient suppliers control 70% of heat-stable natural flavor systems, creating bottlenecks during formulation pivots.
- Technical limitation in plant protein solubility:Pea and fava protein isolates require hydrocolloid stabilizers that add viscosity, limiting mouthfeel parity with dairy-based benchmarks.
Strategic Opportunities
- Underpenetrated India:Urban gym penetration is below 5% in Tier-2 cities, creating first-mover advantage for brands establishing localized flavor profiles ahead of FSSAI protein claim standardization.
- Regulatory tailwind from USDA organic:Certified organic RTD lines command 40% shelf price premiums in natural retail channels, with audit trail requirements creating defensible positioning.
- Direct-to-consumer subscription models:Weekly bundling platforms are displacing traditional retail replenishment cycles, capturing lifetime value through personalized macronutrient targeting.
Industry Challenges
- Food technologist scarcity:Formulation expertise spanning protein chemistry, emulsion stability, and sensory science commands premium compensation, constraining R&D team scaling.
- Clean-label certification timelines:Non-GMO Project verification and USDA organic audits require 8-14 month lead times, delaying product launches relative to conventional alternatives.
- Aseptic line validation complexity:FDA process authority requirements for low-acid aseptic beverages demand extensive microbial challenge studies, extending facility commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-To-Drink (RTD) Protein Beverages Market |
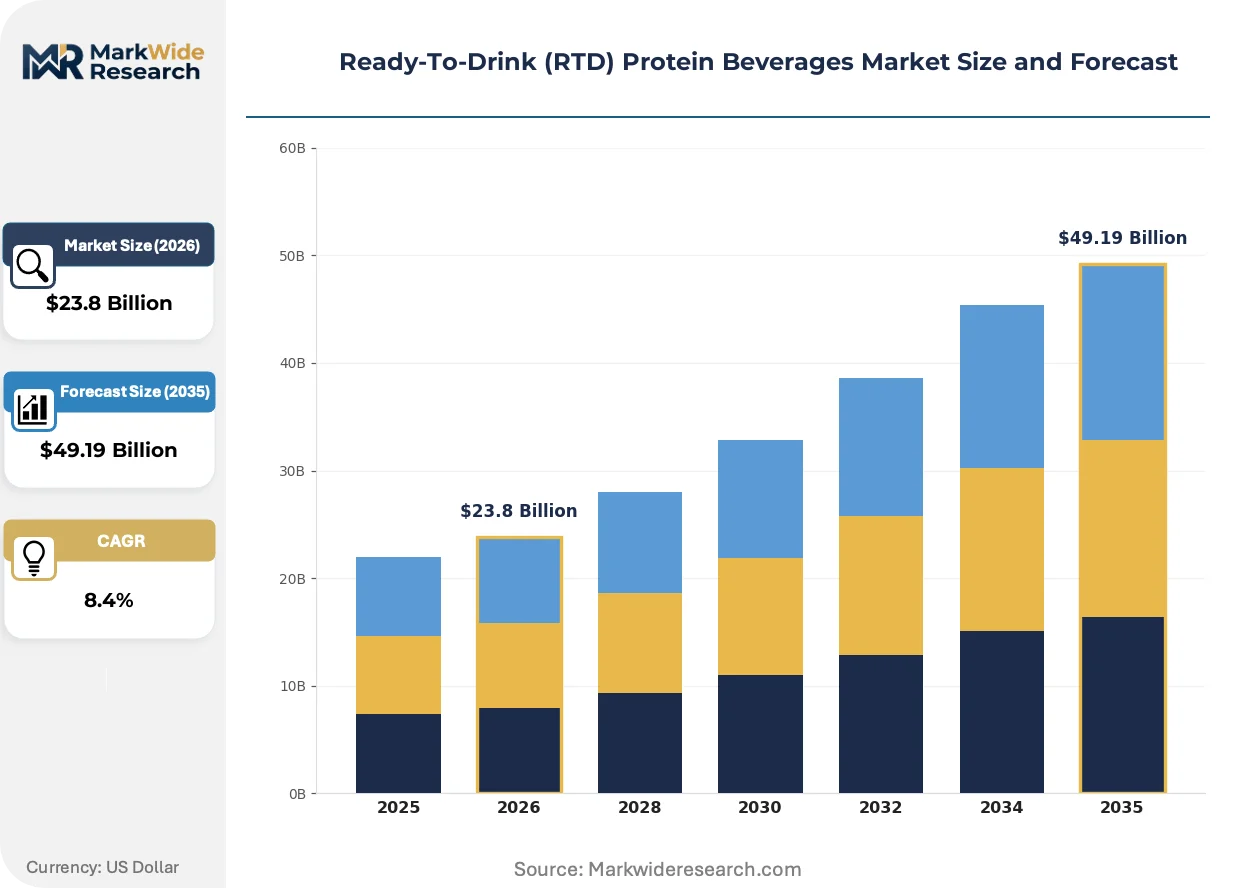
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $49.19 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Plant-Based Protein, Casein Protein, Egg Protein Flavor: Chocolate, Vanilla, Strawberry, Coffee Packaging Type: Bottles, Cans, Tetra Paks, Pouches Distribution Channel: Supermarkets, Health Stores, Online Retail, Convenience Stores |
| Companies Covered | PepsiCo, Glanbia, Nestlé, The Coca-Cola Company, Abbott, Danone, Post Holdings, Arla Foods, Premier Nutrition Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-To-Drink (RTD) Protein Beverages Market Trends and Innovations
Formulation science and packaging engineering are converging to redefine shelf-stable protein delivery, with automation and regulatory precision replacing legacy batch-processing approaches across manufacturing footprints.
High-pressure processing (HPP) is automating cold-chain bypass for refrigerated-positioned brands seeking ambient distribution economics. Sports nutrition specialists in California and Texas are retrofitting HPP tunnels into existing bottling lines, cutting thermal degradation of heat-sensitive bioactive peptides. This automation is compressing the traditional trade-off between microbial safety and functional ingredient integrity.
EFSA's 2023 guidance on protein quality scoring is reshaping label communication strategies for brands operating across EU member states. The PDCAAS-to-DIAAS transition is forcing reformulation toward leucine-dense whey isolates and away from lower-scoring plant blends. German and Dutch manufacturers are responding fastest, submitting novel food dossiers for emerging protein sources ahead of harmonized standards.
Subscription-based replenishment is displacing impulse-driven convenience store purchasing among core fitness demographics. Digital-native brands are capturing recurring revenue through app-integrated consumption tracking, while legacy beverage distributors struggle to replicate retention mechanics. This behavioral pivot is most visible in US coastal metros and London, where gym-attached micro-fulfillment is reducing last-mile delivery costs.
Ready-To-Drink (RTD) Protein Beverages Market Segmentation
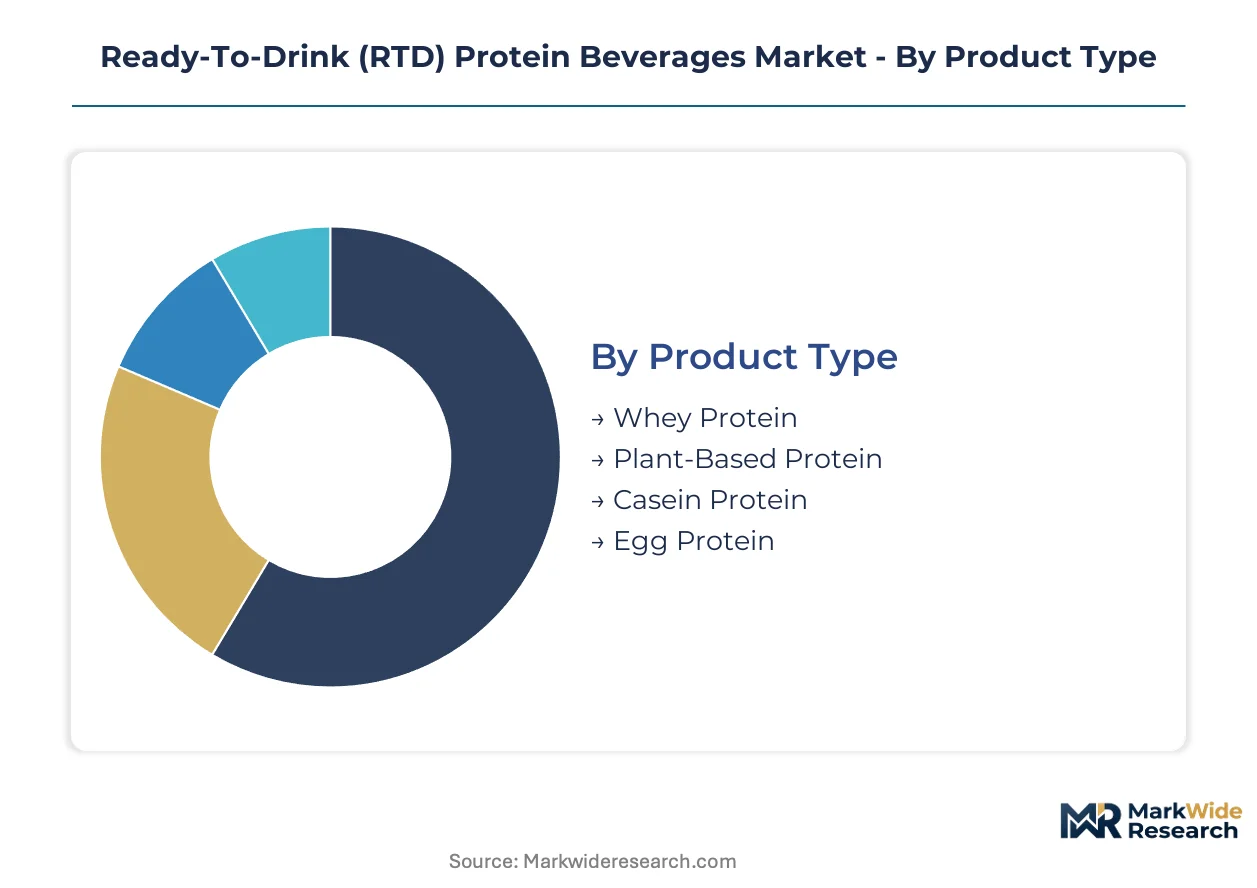
Segmentation in the RTD protein beverage market reveals how formulation chemistry, sensory preferences, and logistics infrastructure create distinct competitive arenas. Each category carries unique margin profiles and regulatory burdens that determine which manufacturers can operate profitably.
Product Type:
Customization spans from commodity dairy derivatives to precision-engineered plant isolates, with standardization concentrated in mass-market whey formats.
- Whey Protein:Rapidly absorbed complete protein with superior leucine density drives post-workout recovery positioning. Demand clusters in United States collegiate athletic programs and German pharmacy channels where EFSA muscle maintenance claims carry retail weight. Whey concentrate volatility from New Zealand milk powder auctions compresses margins for brands lacking forward contracts.
- Plant-Based Protein:Oat, pea, and fava bean blends overcome earlier solubility limitations through hydrocolloid stabilization. United States coastal metros and London show steepest expansion trajectory as fitness demographics prioritize sustainability credentials. Mouthfeel parity with dairy benchmarks remains the technical constraint limiting repeat purchase rates.
- Casein Protein:Slow-digesting micellar structures target overnight recovery applications with extended amino acid release profiles.
- Egg Protein:Lactose-free alternative with complete amino acid scoring serves allergen-sensitive segments in specialty health retail.
Leading the category by volume: Whey Protein. Growing fastest: Plant-Based Protein.
Flavor:
Flavor selection maps directly onto consumption occasion patterns, with chocolate and vanilla anchoring routine daily use while coffee captures morning meal replacement.
- Chocolate:Dominant volume share across all distribution channels with established cocoa-masking properties for protein off-notes. United States convenience stores and German supermarkets stock chocolate SKUs as default protein beverage entries. Heat-stable natural chocolate flavor systems concentrate supply among three specialty houses, creating procurement bottlenecks during formulation pivots.
- Vanilla:Neutral base enables protein-forward taste profiles with minimal masking requirements. China shows particular concentration as local manufacturers develop vanilla variants for Tier-2 city gym penetration ahead of FSSAI protein claim standardization. Clean-label vanilla extraction from Madagascar and Indonesian sources commands premium ingredient qualification costs.
- Strawberry:Seasonal demand spikes align with Q1 fitness enrollment cycles in North American and European markets.
- Coffee:Caffeine-protein combination targets morning consumption occasions competing with specialty coffee shop formats.
Chocolate maintains volume leadership. Coffee demonstrates the steepest climb as meal-replacement positioning expands.
Packaging Type:
Packaging economics determine cold-chain dependency, shelf-life extension, and last-mile logistics cost structures across ambient and refrigerated positioning.
- Tetra Paks:Aseptic filling technology enables 12-month ambient shelf life with lightweight logistics advantages. German and Dutch manufacturers deploy Tetra Pak lines most aggressively for EU-wide distribution without refrigeration. Capital deployment into compatible production lines demands extensive FDA process authority validation for low-acid aseptic beverages.
- Bottles:Single-serve PET and HDPE formats dominate United States convenience store placement through PepsiCo's beverage distribution network. Weekly bundling platforms favor bottle formats for subscription-based replenishment models in US coastal metros. Recyclability mandates from state-level extended producer responsibility laws are forcing material specification changes.
- Cans:Aluminum formats serve sports stadium and gym vending applications with superior chill-speed properties.
- Pouches:Flexible packaging reduces shipping cube for direct-to-consumer subscription logistics with lower per-unit material costs.
Bottles lead by installed capacity. Tetra Paks gain share fastest as ambient distribution economics displace refrigerated alternatives.
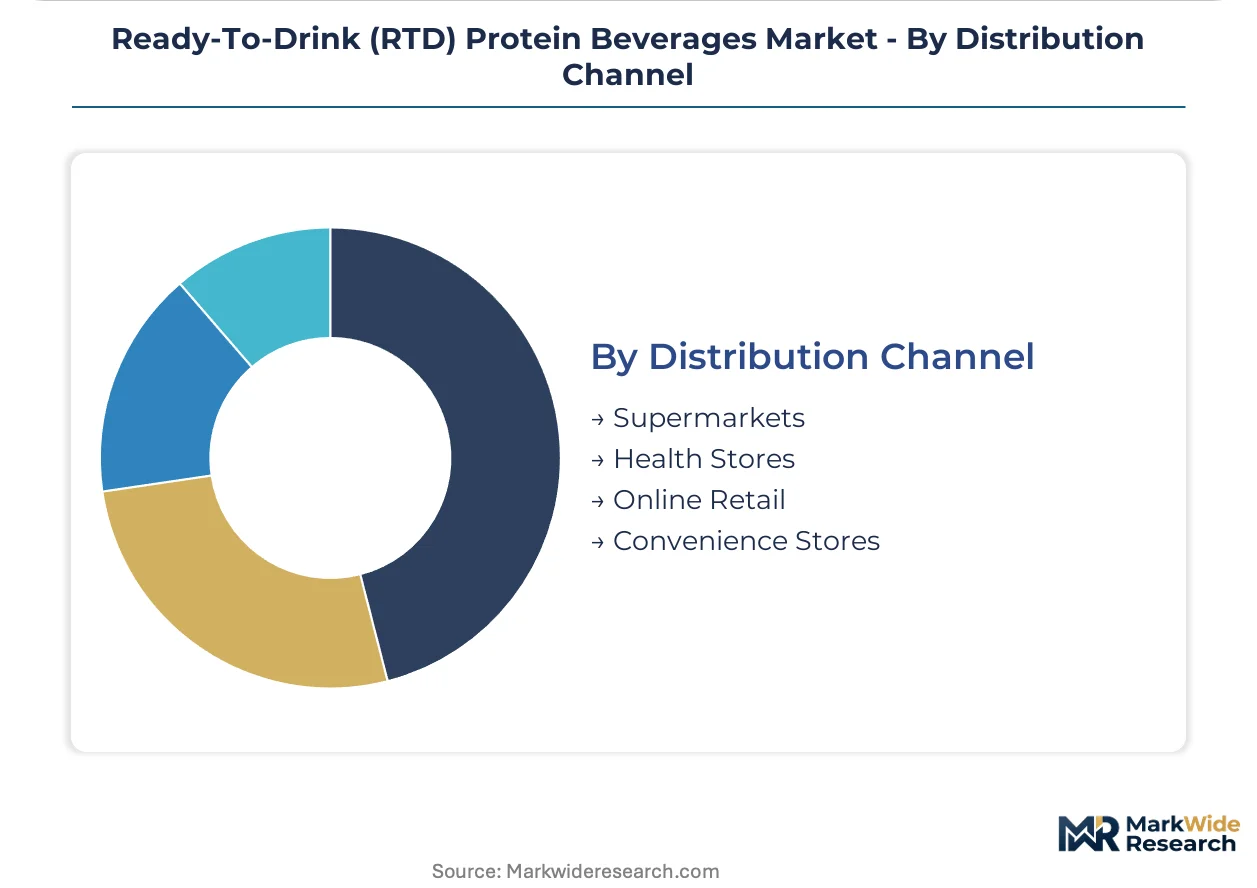
Distribution Channel:
Channel selection determines customer acquisition economics, with impulse placement competing against subscription retention models for lifetime value capture.
- Online Retail:Direct-to-consumer platforms enable personalized macronutrient targeting and app-integrated consumption tracking. United States and United Kingdom show highest penetration as digital-native brands displace traditional retail replenishment cycles. Subscription mechanics capture recurring revenue with reduced customer acquisition costs versus impulse channels.
- Supermarkets:Mass-market authorization requires slotting fee negotiations and standardized case-pack configurations. Germany and France concentrate volume through pharmacy-channel sports nutrition specialization where EFSA health claim frameworks unlock retail placement. USDA organic certification commands 40% shelf price premiums in natural retail sub-channels.
- Health Stores:Specialized sports nutrition retail provides educated staff recommendation and sampling opportunities.
- Convenience Stores:Impulse-driven single-serve placement targets time-constrained consumers with immediate consumption intent.
Supermarkets dominate volume throughput. Online retail climbs fastest as subscription models reshape replenishment behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and the Netherlands while consumption concentrates in the United States and China, creating transatlantic and transpacific trade flows in whey protein isolates and aseptic packaging equipment.
United States
Collegiate athletic programs and professional sports franchises drive institutional procurement of RTD protein protocols. FDA nutrition labeling rules constrain muscle recovery claims on packaging. California and Texas sports nutrition specialists retrofit high-pressure processing tunnels into existing bottling lines.
Germany
Pharmacy-channel sports nutrition specialization concentrates demand in EFSA-regulated muscle maintenance claim environments. EFSA health claim frameworks unlock retail placement across EU member states. North Rhine-Westphalia and Bavaria host Tetra Pak-compatible production lines for ambient distribution economics.
China
Tier-2 city gym penetration below 5% creates first-mover opportunities for localized flavor development. FSSAI protein claim standardization is pending, creating regulatory uncertainty. Yangtze River Delta manufacturers develop vanilla variants ahead of harmonized national standards.
Netherlands
Dairy commodity trading infrastructure anchors whey protein concentrate sourcing for European formulation. EU organic regulations create tiered market access for certified lines. Dutch manufacturers submit novel food dossiers for emerging protein sources ahead of harmonized EU standards.
United Kingdom
Digital-native subscription platforms capture recurring revenue through app-integrated consumption tracking. GDPR compliance requirements shape direct-to-consumer data collection practices. London gym-attached micro-fulfillment reduces last-mile delivery costs for weekly bundling models.
Ready-To-Drink (RTD) Protein Beverages Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and distribution infrastructure tiers. The vendor base spans multinational beverage networks, dairy-backed nutrition platforms, and specialized whey protein technology developers. Three strategic archetypes dominate: conglomerate beverage distributors leveraging existing retail placement, dairy-integrated nutrition companies with captive protein supply, and performance-focused ingredient technology specialists. Competitive moves concentrate on aseptic filling capacity expansion and direct-to-consumer subscription platform development.
Within the conglomerate tier, PepsiCo and The Coca-Cola Company exemplify beverage distribution network leverage for convenience store channel dominance. Nestlé occupies a position anchoring dairy-backed formulation with extended shelf stability capabilities. Glanbia sits within the performance nutrition specialist archetype, representing specialized whey protein isolate technology development. These three companies collectively illustrate the strategic divergence between scale-driven placement, supply-integrated formulation, and technical ingredient specialization.
| Leading Market Players |
|---|
| PepsiCo |
| Glanbia |
| Nestlé |
| The Coca-Cola Company |
| Abbott |
| Danone |
| Post Holdings |
| Arla Foods |
| Premier Nutrition Corporation |
| Others |
Pricing and Supply Chain Analysis
Food technologist scarcity in California and Texas commands premium compensation that widens spreads between premium whey isolate formulations and economy-tier concentrates. Labor-cost differentials between specialized protein chemistry hubs and general beverage manufacturing regions directly map onto pricing-tier stratification across the RTD protein beverage market.
Pricing Analysis
Cost-down pressure on mid-tier whey concentrate brands accelerates because New Zealand milk powder auction volatility compresses margins for players lacking forward contracting capabilities. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified lines from conventional formulations from private-label alternatives. Price differentiation rests on certification grade and volume scale, with organic audit trails commanding shelf premiums while bulk institutional procurement stabilizes contract pricing. Fitness enthusiasts in subscription channels show lowest price sensitivity; convenience store impulse buyers exhibit highest elasticity.
Supply Chain Analysis
Formulation expertise shortages in North Rhine-Westphalia and Bavaria constrain Tetra Pak-compatible production line scaling for EU-wide ambient distribution. Supply concentrates in Germany, the Netherlands, and the United States, with Dutch dairy commodity trading infrastructure anchoring whey protein isolate sourcing. Raw material dependencies center on New Zealand milk powder, Madagascar vanilla extraction, and heat-stable natural chocolate flavor systems from specialty houses. Single-source vulnerability in flavor house concentration creates procurement bottlenecks during formulation pivots. Distribution runs through PepsiCo's convenience store network in the United States and pharmacy-channel specialization in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RTD protein beverage market economics function as a cost-of-compliance story where FDA process authority requirements for low-acid aseptic beverages erect barrier-to-entry moats protecting validated incumbents.
For Market Incumbents: Extend aseptic filling capacity in Tetra Pak-compatible geographies to capture ambient distribution economics displacing refrigerated alternatives. Deepen backward integration into whey protein isolate production to buffer New Zealand milk powder auction volatility. Certification investment in USDA organic audit trails defends margin position against private-label encroachment in natural retail channels. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest customer acquisition cost route for digital-native brands seeking recurring revenue capture. Target Tier-2 cities in China ahead of FSSAI protein claim standardization for first-mover advantage in underpenetrated gym infrastructure. App-integrated consumption tracking serves as the primary go-to-market angle for personalized macronutrient targeting. For Investors and Strategic Acquirers: Re-rating potential sits with specialized whey protein isolate technology developers given EFSA's PDCAAS-to-DIAAS transition forcing reformulation toward leucine-dense formulations. Long-term viability favors players with captive protein supply and validated aseptic infrastructure over asset-light brand marketers. Watch FDA process authority approval timelines as the inflection indicator for manufacturing capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Filling Capacity Expansion | Tetra Pak-compatible lines extend ambient shelf life to 12 months, reducing cold-chain dependency. |
| Direct-to-Consumer Platform Launch | Subscription mechanics capture lifetime value through personalized macronutrient targeting in US coastal metros. |
| USDA Organic Certification Investment | Audit trail requirements create defensible positioning with 40% shelf price premiums in natural retail. |
| Backward Integration into Whey Isolate | In-house production buffers margin compression from New Zealand milk powder auction volatility. |
| High-Pressure Processing Retrofit | California and Texas specialists automate cold-chain bypass while preserving heat-sensitive bioactive peptides. |
Research Methodology
Independent corroboration across formulation scientists, sports nutrition brand managers, and Tetra Pak equipment suppliers underwrites the qualitative findings in this study. Primary interviews with food technologists, procurement leads at flavor houses, and pharmacy-channel category buyers combined with secondary validation from FDA process authority filings, EFSA novel food dossiers, and customs records on whey protein concentrate trade flows. Bottom-up segment sizing and top-down market reconciliation triangulate volume and value estimates across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, flavor, packaging format, and distribution channel dimensions. The analytical framework models CAGRs through driver-based elasticity analysis rather than extrapolation, incorporating protein content verification standards evolution and sugar taxation threshold developments as industry-specific forecast inputs throughout the projection horizon.
The model holds under stable regulatory interpretation of FDA nutrition labeling rules and EFSA health claim frameworks; deviation in FSSAI standardization timing or EU organic audit trail stringency would shift growth trajectories. Forecasts reflect assumptions on aseptic line commissioning schedules and flavor house supply concentration. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Protein-Based Fat Replacer Market
Functional Food and Beverage
Middle East and Africa Functional Beverages Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Saudi Arabia Protein Bar Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
Functional Coffee Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Fermented Protein Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Global Functional Mushrooms Market