
 Asia-Pacific Functional Beverages Market | 2026-2036
Asia-Pacific Functional Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Functional Beverages Market Outlook
E-commerce platforms across Southeast Asia are rewriting distribution economics for functional beverages, collapsing traditional wholesale layers and enabling direct-to-consumer replenishment models. Suntory Holdings Limited leverages its FOSHU-certified portfolio to sustain premium positioning in Japanese convenience channels. PepsiCo Inc competes through localized flavor development and sports-drink bundling with major athletic events. Red Bull GmbH dominates energy-drink mindshare through event sponsorship density and youth-culture embedding across Indonesian and Thai metropolitan markets.
Functional beverages are non-alcoholic drinks formulated with bioactive compounds, vitamins, minerals, amino acids, or herbal extracts at specified concentrations to deliver targeted physiological effects beyond basic hydration. Manufacturing involves aseptic cold-fill processing or hot-fill pasteurization to preserve thermolabile ingredients such as probiotics and B-vitamins, with shelf stability governed by pH modulation and oxygen barrier packaging. Energy drinks occupy the largest revenue pool due to established consumption rituals among working professionals and students, while nutritional beverages with protein and probiotic content represent the fastest-expanding margin segment as aging populations in Japan and South Korea seek meal-replacement solutions. Enhanced water trails in value contribution but attracts new entrants given lower formulation complexity and cleaner-label positioning.
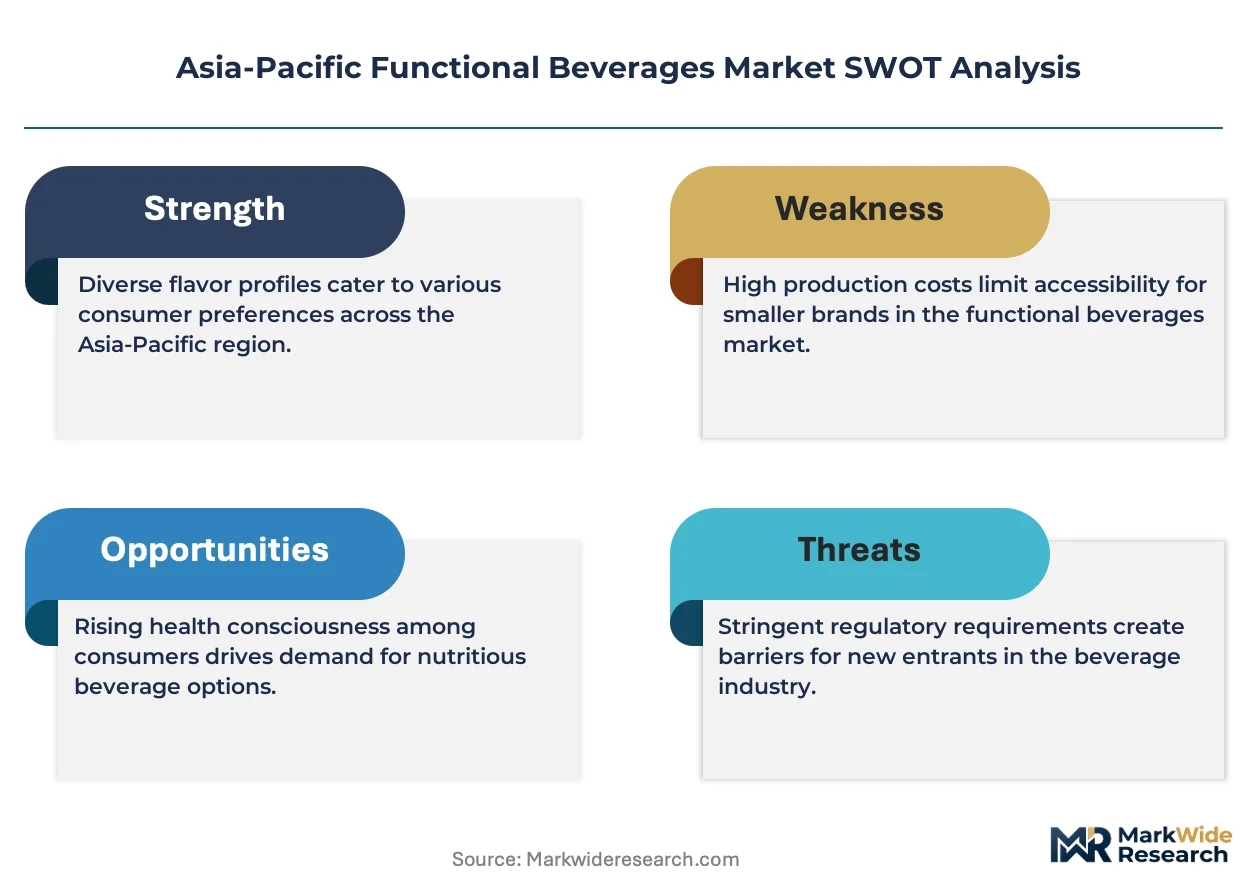
Japan's Ministry of Health, Labour and Welfare enforces FOSHU claims verification, creating a compliance moat that rewards documented efficacy and deters speculative health positioning. China's SAMR and National Health Commission impose dual-layer registration for novel food ingredients and permitted additive lists, slowing foreign brand entry but protecting domestic formulation leaders. Australia's TGA and FSANZ standards influence export-oriented producers across the region. Stakeholders must monitor evolving permissible claim languages and ingredient approval timelines, as regulatory divergence between Northeast and Southeast Asian regimes increasingly determines where formulation R&D investment flows.
Market Dynamics
Japan's FOSHU certification system exerts gravitational pull across Asia-Pacific formulation strategies, forcing competitors to document clinical efficacy before premium positioning becomes viable. This regulatory architecture concentrates R&D investment in documented bioactive compounds rather than speculative health claims.
Growth Catalysts
- Aging demographics in Japan and South Korea:Consumers over 55 seek protein-fortified meal replacements and probiotic beverages, expanding the nutritional beverages segment faster than energy drinks.
- FOSHU framework export:Thailand's FDA and Vietnam's Ministry of Health are adopting Japan's efficacy-verification models, accelerating premium product registration timelines for documented formulations.
- E-commerce infrastructure maturation:Direct-to-consumer replenishment models collapse wholesale margins in Indonesia and Philippines, enabling subscription-based functional hydration delivery.
Market Restraints
- Thermolabile ingredient instability:Probiotics and B-vitamins degrade under standard hot-fill pasteurization, requiring costly aseptic cold-fill lines that concentrate production among capitalized manufacturers.
- Dual-layer registration in China:SAMR and National Health Commission reviews for novel food ingredients extend 18-24 months, freezing formulation pipelines for foreign entrants.
- Clean-label ingredient cost premiums:Natural sweeteners and plant-derived amino acids trade at 3-4x synthetic equivalents, compressing gross margins for mid-tier positioning.
Strategic Opportunities
- Tier-two Chinese city penetration:Health consciousness diffuses beyond Beijing and Shanghai into Chengdu and Hangzhou, where functional beverage penetration trails tier-one benchmarks by 40 percentage points.
- Post-exercise recovery positioning:Collagen peptide and electrolyte combinations target female fitness communities in Australia and South Korea, a demographic underserved by male-skewed energy drink marketing.
- Biodegradable oxygen barrier packaging:Convergence of modified atmosphere technology and seaweed-derived films enables shelf-stable probiotic delivery without petroleum-based plastics.
Industry Challenges
- Formulation talent scarcity:Food scientists with dual competency in bioactive stability and sensory optimization command premium compensation in Tokyo and Singapore, constraining mid-size manufacturer R&D staffing.
- Legacy ERP integration with DTC fulfillment:Traditional beverage distributors struggle to synchronize inventory visibility between warehouse management systems and TikTok Shop or Shopee storefronts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Functional Beverages Market |
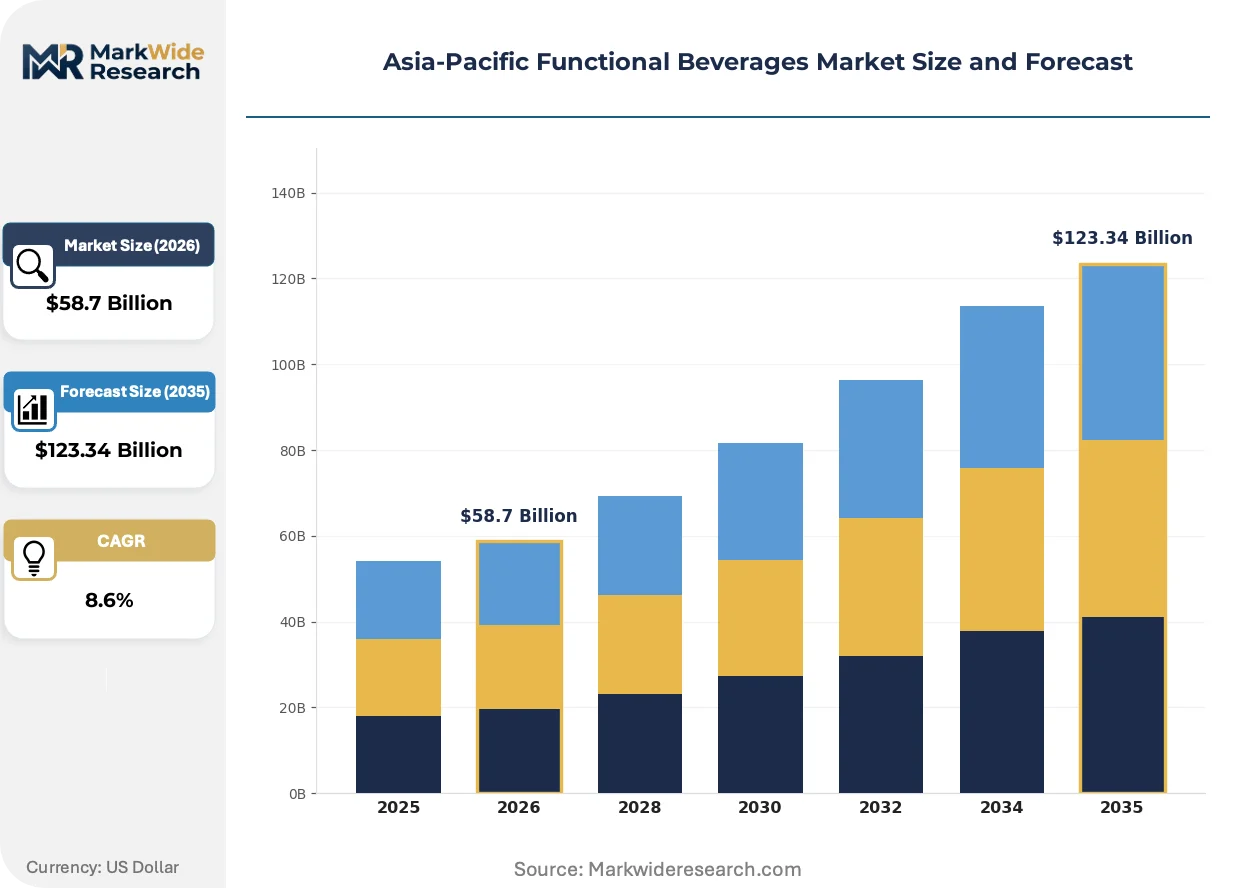
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $123.34 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Sports Drinks, Nutritional Beverages, Enhanced Water Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Retail End User: Health Conscious Consumers, Athletes, Working Professionals, Students Ingredient Type: Vitamins, Amino Acids, Herbal Extracts, Probiotics |
| Companies Covered | Suntory Holdings Limited, Nestlé S A, Vitasoy International Holdings Ltd, Danone S A, Red Bull GmbH, PepsiCo Inc, The Coca-Cola Company, Keurig Dr Pepper Inc, Otsuka Holdings, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Functional Beverages Market Strategic Shifts
Formulation science and distribution architecture are diverging sharply across Asia-Pacific, with cold-chain infrastructure investments in Northeast Asia enabling entirely different product categories than ambient-stable formats dominating Southeast Asian shelves.
Aseptic cold-fill processing with nitrogen dosing is rendering obsolete conventional hot-fill lines for probiotic and vitamin-fortified beverages. Japanese and South Korean manufacturers are retrofitting plants at pace, while Thai and Indonesian bottlers delay capital commitments. This technology divergence is rendering obsolete the historical pattern of exporting identical SKUs across all Asia-Pacific markets.
China's SAMR is tightening permissible claim language for "immune support" and "gut health" positioning, requiring human clinical data for registration. Domestic brands with established trial documentation gain shelf advantage as foreign competitors pause launch timelines. Nutritional beverages with documented probiotic colony counts are most affected, with several international brands withdrawing pending SKUs rather than funding required studies.
Subscription replenishment through e-commerce platforms is displacing convenience-store impulse purchasing among working professionals in Jakarta and Bangkok. Younger consumers pre-schedule monthly energy drink and enhanced water deliveries, bypassing traditional retail markup layers. This behavioral pivot is most visible among Indonesian software developers and Thai financial services employees, who prioritize uninterrupted supply over variety-seeking.
Asia-Pacific Functional Beverages Market Segmentation
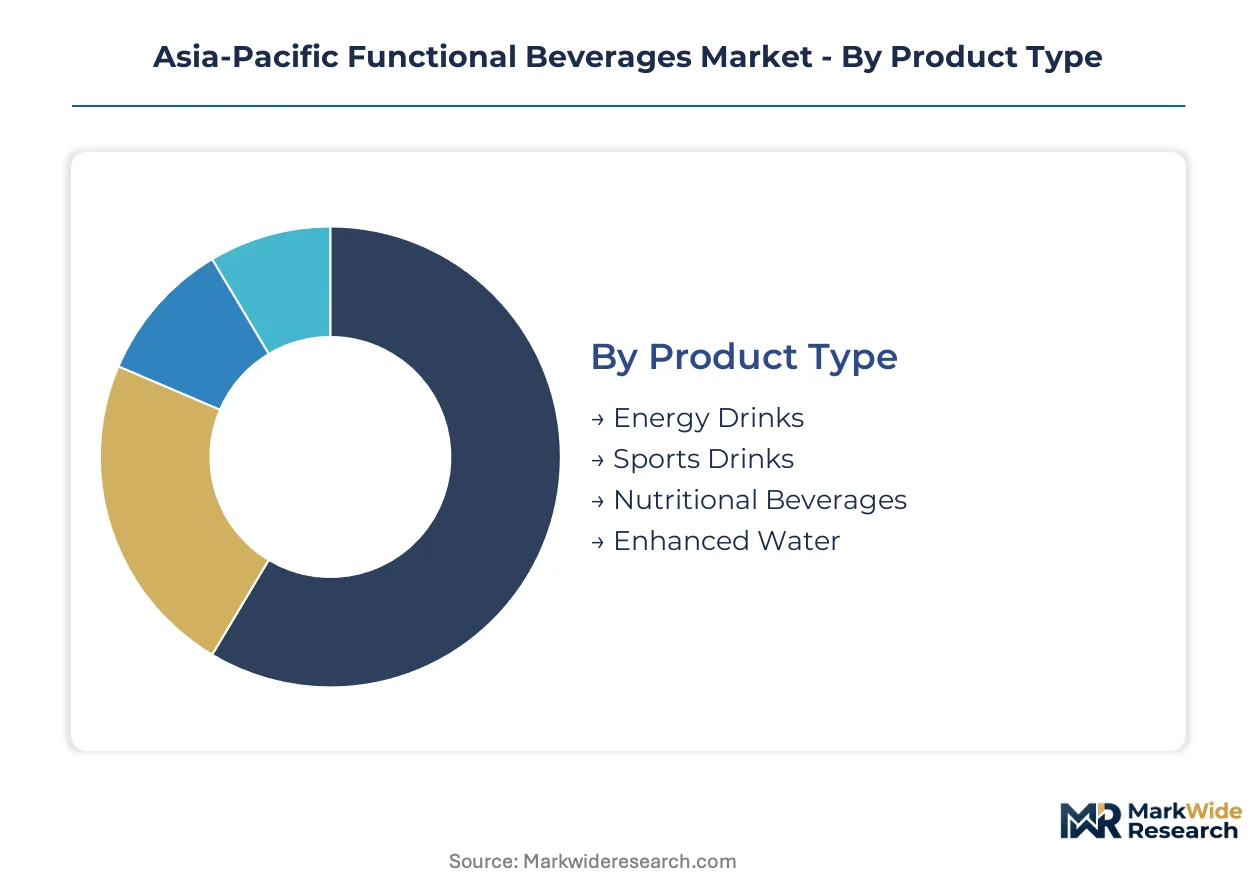
Segmentation in the Asia-Pacific functional beverages market reveals divergent growth mechanics across formulation technologies and channel architectures. Product maturity varies sharply between established energy drink rituals and emerging probiotic formats requiring cold-chain infrastructure.
Product Type:
Mature formats with established consumption rituals coexist alongside emerging categories demanding new manufacturing capabilities and distribution investments.
- Energy Drinks:Caffeine-taurine formulations dominate working professional consumption in Japan, South Korea, and Australia with entrenched daily-use rituals. Convenience store placement in Tokyo and Seoul sustains impulse-driven replenishment despite e-commerce encroachment.
- Nutritional Beverages:Protein-fortified and probiotic drinks target aging populations in Japan and South Korea seeking meal-replacement solutions. Cold-fill aseptic processing requirements concentrate production among capitalized Japanese and South Korean manufacturers with retrofitting capabilities.
- Sports Drinks:Electrolyte formulations serve athletic hydration needs across Australian fitness communities and Southeast Asian tropical climates.
- Enhanced Water:Vitamin-infused and mineral-enriched variants attract clean-label seekers in Chinese tier-one cities with lower formulation complexity barriers.
Energy drinks retain volume leadership; nutritional beverages hold the steepest expansion curve.
Distribution Channel:
Channel cost structures and consumer touchpoint density determine margin capture and brand building velocity across diverse Asia-Pacific retail ecosystems.
- Convenience Stores:Dense urban networks in Tokyo, Seoul, and Bangkok sustain impulse purchasing for energy drinks and functional hydration. 24-hour operations align with irregular working schedules among software developers and financial services employees.
- Online Retail:Direct-to-consumer replenishment through Shopee, Lazada, and TikTok Shop collapses wholesale layers in Indonesia and Philippines. Subscription models among Jakarta and Bangkok professionals displace variety-seeking with uninterrupted supply prioritization.
- Supermarkets:Shelf space competition in Chinese tier-one and tier-two cities drives promotional intensity for established brands.
- Specialty Retail:Fitness centers and health food stores in Australian and South Korean metropolitan areas curate premium functional hydration for dedicated wellness consumers.
Convenience stores anchor immediate consumption; online retail captures the fastest channel share gains.
End User:
User archetypes segment by physiological need state, consumption occasion, and price sensitivity rather than demographic abstraction alone.
- Working Professionals:Sustained cognitive performance demands drive daily energy drink and nootropic beverage adoption across Tokyo, Singapore, and Sydney financial districts. Irregular hours and high-stakes decision environments prioritize reliable supply chains over variety exploration.
- Health Conscious Consumers:Clean-label scrutiny and ingredient provenance awareness concentrate in Chinese tier-one cities and Australian metropolitan markets. FOSHU certification recognition among Japanese consumers extends to export-oriented Thai and Vietnamese formulations adopting similar efficacy-verification models.
- Athletes:Post-exercise recovery positioning with collagen peptides and electrolyte combinations targets underserved female fitness communities in South Korea and Australia.
- Students:Examination-period consumption spikes drive seasonal demand volatility for caffeine-forward formulations across Southeast Asian university towns.
Working professionals generate the largest revenue pool; health conscious consumers command the premium pricing tier.
Ingredient Type:
Ingredient stability requirements and regulatory approval pathways determine formulation feasibility and geographic market entry sequencing.
- Probiotics:Live culture beverages require aseptic cold-fill processing and refrigerated distribution, limiting viable markets to Northeast Asian cold-chain infrastructure in Japan and South Korea. Thailand's FDA adoption of FOSHU-style efficacy verification accelerates premium product registration for documented colony count formulations.
- Vitamins:B-vitamin fortification dominates energy drink formulations with established hot-fill pasteurization compatibility enabling broader Southeast Asian production.
- Amino Acids:Taurine and branched-chain amino acid inclusion supports sports drink and recovery beverage positioning across Australian and South Korean fitness markets.
- Herbal Extracts:Ginseng, ashwagandha, and traditional medicine-derived compounds attract Chinese and Southeast Asian consumers seeking culturally familiar functional claims.
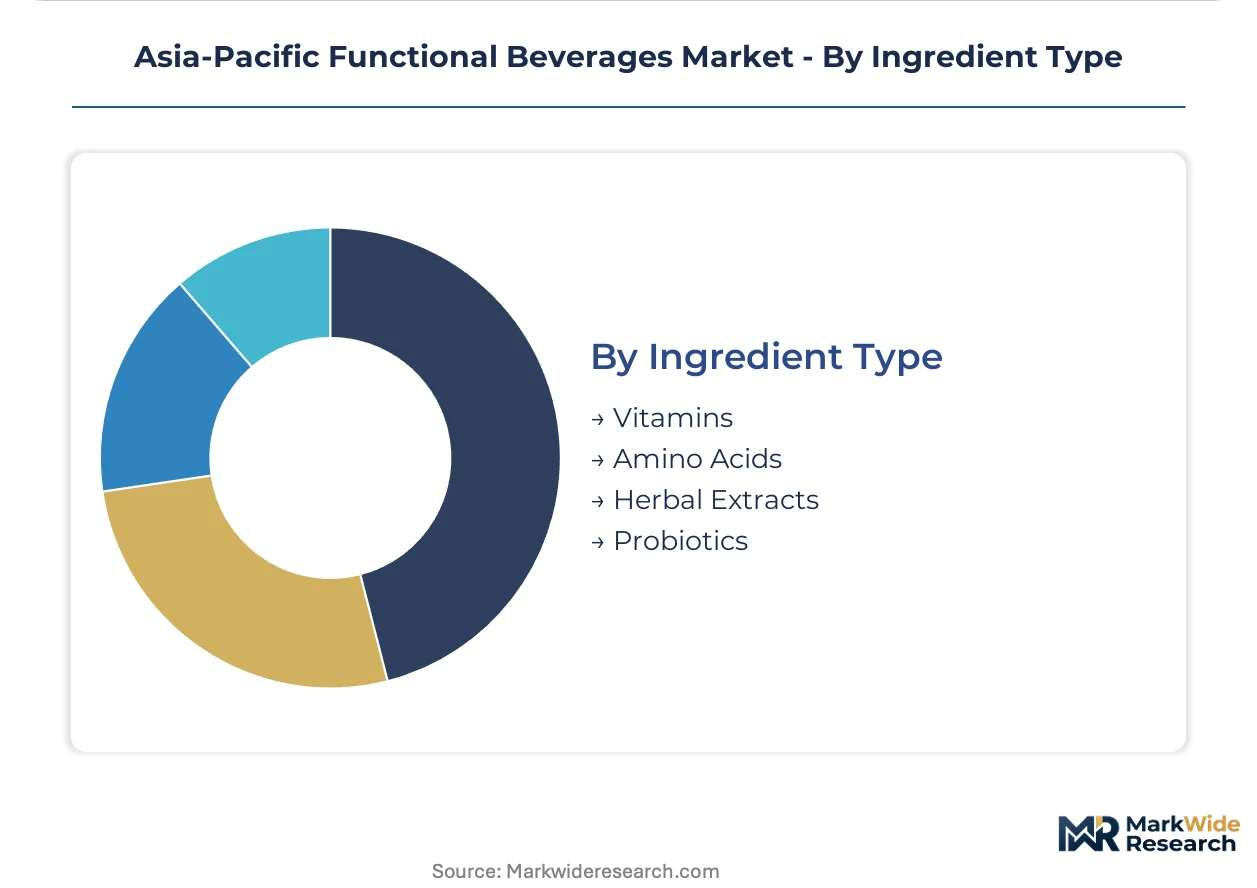
Vitamins sustain the broadest formulation application; probiotics face the steepest expansion constraints from infrastructure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Japanese and South Korean metropolitan markets where FOSHU-style efficacy verification commands consumer trust, while Southeast Asian volume growth absorbs cost-optimized formulations from regional production hubs.
Japan
Aging consumers over 55 drive protein-fortified nutritional beverage demand in Tokyo and Osaka. The Ministry of Health, Labour and Welfare enforces FOSHU claims verification that rewards documented clinical efficacy. Kanto region manufacturers retrofit aseptic cold-fill lines to preserve thermolabile probiotics for premium positioning.
China
Tier-one city professionals prioritize sustained cognitive performance beverages over conventional soft drinks in Beijing and Shanghai. SAMR and the National Health Commission impose dual-layer registration extending 18-24 months for novel ingredients. Yangtze River Delta formulation leaders exploit domestic trial documentation advantages as foreign competitors pause launch timelines.
South Korea
Post-exercise recovery positioning with collagen peptides targets underserved female fitness communities in Seoul and Busan. MFDS adopts efficacy-verification models accelerating premium product registration for documented formulations. Seoul Capital Area cold-chain infrastructure enables live culture probiotic distribution unavailable in tropical climates.
Thailand
Younger professionals in Bangkok pre-schedule monthly functional hydration deliveries through Shopee and Lazada subscription models. The FDA adopts Japan's FOSHU-style efficacy verification accelerating premium registration timelines. Bangkok metropolitan bottlers delay aseptic cold-fill capital commitments while exporting ambient-stable formats regionally.
Indonesia
Software developers in Jakarta prioritize uninterrupted energy drink supply over variety-seeking through TikTok Shop direct-to-consumer replenishment. The national food and drug regulator maintains additive approval lists that protect domestic formulation leaders. Java-based distributors struggle to synchronize legacy ERP systems with e-commerce storefront inventory visibility.
Asia-Pacific Functional Beverages Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with ingredient and processing technology advantages. Market structure consolidates around diversified beverage conglomerates with cross-category portfolios and regional formulation specialists with documented efficacy credentials. Three archetypes dominate: FOSHU-certified premium players, mass-market energy drink distributors, and cold-chain probiotic specialists. Competitive moves concentrate on regulatory pre-approval investments and e-commerce direct-to-consumer infrastructure buildout.
Among diversified beverage conglomerates, Suntory Holdings Limited and PepsiCo Inc exemplify contrasting strategic positions. Suntory leverages FOSHU-certified portfolio depth to sustain premium pricing in Japanese convenience channels. PepsiCo competes through localized flavor development and sports-drink bundling with major athletic events. Nestlé S A occupies a position bridging nutritional science credibility with mass-market distribution scale across Southeast Asian e-commerce platforms.
| Leading Market Players |
|---|
| Suntory Holdings Limited |
| Nestlé S A |
| Vitasoy International Holdings Ltd |
| Danone S A |
| Red Bull GmbH |
| PepsiCo Inc |
| The Coca-Cola Company |
| Keurig Dr Pepper Inc |
| Otsuka Holdings |
| Others |
Value Chain & Pricing Dynamics
Aseptic cold-fill processing equipment concentration in Japan and South Korea concentrates premium formulation margins among capitalized manufacturers with retrofit capabilities, while Southeast Asian bottlers absorbing ambient-stable formats capture volume at compressed economics. This upstream technology bifurcation directly determines where FOSHU-certified premium positioning versus cost-optimized standard tiering becomes viable.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the Asia-Pacific functional beverages landscape. FOSHU certification and documented clinical efficacy command the premium tier in Japanese convenience channels, while clean-label ingredient provenance drives price differentiation in Chinese tier-one cities. Cost compression in the standard tier is intensifying because natural sweeteners and plant-derived amino acids trade at multiples against synthetic equivalents. Working professionals in Tokyo and Seoul show least price sensitivity for verified efficacy, whereas Southeast Asian students and mass-market consumers exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration among Japanese and South Korean aseptic cold-fill specialists with probiotic preservation capabilities anchors premium nutritional beverage supply. Raw material dependencies center on B-vitamin premixes from Chinese chemical manufacturers, taurine from Japanese amino acid specialists, and collagen peptides from South Korean marine processing facilities. Single-source vulnerability in aseptic packaging film supply creates exposure for live culture formulations requiring oxygen barrier properties. Distribution runs through e-commerce direct-to-consumer platforms in Indonesia and Philippines alongside traditional convenience store networks in Japan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across the Asia-Pacific functional beverages landscape as aging demographics and e-commerce infrastructure maturation create demand-side niches underserved by incumbent portfolio breadth. Working professionals seeking sustained cognitive performance and health-conscious consumers demanding clean-label transparency pull the market toward specialized formulation competencies.
For Market Incumbents: Harden FOSHU certification moats through expanded clinical trial documentation for emerging bioactive compounds before Thailand and Vietnam complete regulatory harmonization. Deepen backward integration into aseptic cold-fill capacity in the Seoul Capital Area to preempt supply constraints as Southeast Asian demand for live culture formats matures. Defensive positioning against direct-to-native replenishment models requires synchronizing legacy ERP systems with TikTok Shop and Shopee inventory visibility before mid-tier competitors capture subscription relationships. For New Entrants and Emerging Players: Tier-two Chinese cities including Chengdu and Hangzhou represent the most penetrable entry point where functional beverage penetration trails tier-one benchmarks and domestic formulation leaders face SAMR registration delays. Post-exercise recovery positioning with collagen peptide and electrolyte combinations targeting underserved female fitness communities in South Korea and Australia offers white-space differentiation from male-skewed energy drink incumbents. Go-to-market execution through fitness center specialty retail and Instagram-native community building bypasses convenience store slotting fee barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aseptic cold-fill processing as Japanese and South Korean manufacturers retrofit plants for thermolabile ingredient preservation. Long-term viability over the next decade favors acquisition targets with documented efficacy credentials and established cold-chain distribution partnerships rather than ambient-stable commodity players. The signal to watch is Thailand FDA and Vietnam Ministry of Health adoption velocity for FOSHU-style efficacy verification, which will determine which formulation R&D investments translate into premium registration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FOSHU Certification Expansion | Documented clinical efficacy unlocks premium positioning in Japanese convenience channels and emerging Southeast Asian regulatory harmonization markets. |
| Aseptic Cold-Fill Retrofit | Preservation capabilities for probiotics and B-vitamins concentrate production economics among capitalized Northeast Asian manufacturers. |
| E-Commerce DTC Infrastructure | Subscription replenishment through Shopee and TikTok Shop collapses wholesale margins and captures working professional loyalty in Jakarta and Bangkok. |
| Clean-Label Ingredient Sourcing | Natural sweeteners and plant-derived amino acids command margin premiums from health-conscious consumers in Chinese tier-one cities. |
| Regional Production Footprint | Ambient-stable format concentration in Thai and Indonesian bottlers enables cost-optimized volume absorption across tropical climate markets. |
Study Parameters
Cross-validation between regulatory filing analysis and trade flow data anchors the qualitative findings in this study. Primary interviews with FOSHU registration specialists, aseptic processing plant managers, e-commerce platform category leads, and convenience store buyers in Tokyo, Seoul, and Jakarta combined with secondary validation from Japan Ministry of Health Labour and Welfare documentation, China SAMR novel food ingredient registries, and Southeast Asian customs records. Bottom-up SKU-level demand modeling and top-down category value triangulation reconcile volume and value estimates.
Calibration against historical FOSHU approval timelines and e-commerce penetration trajectories in Indonesian metropolitan markets refines the analytical framework. Segmentation dimensions span product type, distribution channel, end user archetype, and ingredient stability requirements across the projection horizon. CAGRs derive from fitted trend extrapolation moderated by regulatory approval velocity assumptions and cold-chain infrastructure investment pacing. Industry-specific forecast inputs include probiotic colony count documentation standards and nitrogen dosing technology adoption curves.
Practitioners should monitor SAMR claim language tightening and Thailand FDA FOSHU adoption velocity for early signals of premium registration timeline compression. Forecasts reflect assumptions regarding regulatory harmonization pacing and e-commerce fulfillment infrastructure maturation. Quarterly review of aseptic cold-fill capacity utilization rates and clean-label ingredient cost indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Fermented Protein Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Functional Tea Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
Antioxidant Beverages Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
Non-GMO Verified Sports Drink Market
Functional Food and Beverage
APAC Functional Food Ingredients Market