
 Global Functional Mushrooms Market | 2026-2036
Global Functional Mushrooms Market Size, Share, and Industry Trends Forecast 2026-2036
Global Functional Mushrooms Market Foresight
A shortage of trained mycologists and fermentation technologists is unwinding production scalability for premium extract grades. Four Sigmatic leverages its direct-to-consumer channel control to sustain brand premiums in North American wellness markets. Hokkaido Reishi Co., Ltd. anchors its competitive position through decades of specialized cultivation expertise in Japanese Reishi strains. Nammex differentiates by supplying certified organic mushroom extracts to supplement manufacturers seeking verified raw material provenance.
Functional mushrooms comprise the fruiting bodies and mycelial biomass of species cultivated or wild-harvested for bioactive compounds including beta-glucans, triterpenoids, and erinacines, with standardized extraction protocols yielding powders and liquid concentrates for therapeutic and preventive health applications. Reishi and Lion's Mane extracts command premium positioning due to clinical validation of their immunomodulatory and neurotrophic properties, while Chaga maintains steady demand in antioxidant support formulations. Powder and capsule forms dominate volume throughput, though liquid extracts and functional teas capture expanding shelf space in specialty retail and wellness center channels.
FDA dietary supplement regulations and EU Novel Food frameworks shape extract purity standards and new ingredient market access, while China's NMPA and GB standards govern export quality for raw material supply chains originating in Asian cultivation hubs. The USDA National Organic Program and equivalent European certifiers influence procurement criteria for North American and European finished goods manufacturers. Stakeholders must monitor evolving novel food approvals and organic certification reciprocity agreements to secure compliant supply positions across fragmented regulatory jurisdictions.
Market Dynamics
Standardized extraction protocols for beta-glucans and triterpenoids are concentrating procurement power among certified organic suppliers, while FDA and EU Novel Food enforcement is fragmenting market access for unvalidated biomass products.
Growth Catalysts
- EU Novel Food Regulation:Approved Reishi and Lion's Mane extracts gain automatic market access across 27 member states, compressing regulatory timelines for compliant suppliers.
- Clinical nutrition channels:Hospital formulary acceptance of mushroom extracts for adjunct immunotherapy is expanding institutional procurement volumes in the United States and Germany.
- Submerged fermentation:Controlled mycelial cultivation in bioreactors is displacing wild-harvested Chaga, securing year-round supply consistency for extract manufacturers.
Market Restraints
- Input cost volatility:Hardwood substrate prices for Ganoderma cultivation fluctuate with forestry commodity cycles, compressing margin stability for non-integrated growers.
- Supply concentration risk:China's Zhejiang and Fujian provinces dominate raw Reishi powder output, creating single-source vulnerability for European and North American formulators.
- Regulatory friction:FDA's 2023 enforcement discretion shift on New Dietary Ingredient notifications is delaying market entry for novel mushroom species extracts.
Strategic Opportunities
- Brazil:ANVISA's accelerated natural product registration pathway is opening Latin America's largest nutraceutical market for standardized mushroom extracts.
- Pet nutrition:Veterinary functional food formulations incorporating immune-modulating mushroom extracts represent an underpenetrated application segment.
- E-commerce direct fulfillment:Subscription-based extract delivery is bypassing traditional supplement retail markups, capturing margin for branded finished goods.
Industry Challenges
- Fermentation technologist scarcity:Industrial-scale mycelial biomass production requires specialized bioprocess engineering expertise that outpaces current training pipeline output.
- Organic certification timelines:USDA National Organic Program and EU organic equivalency audits extend 18-24 months, delaying verified supply chain positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Functional Mushrooms Market |
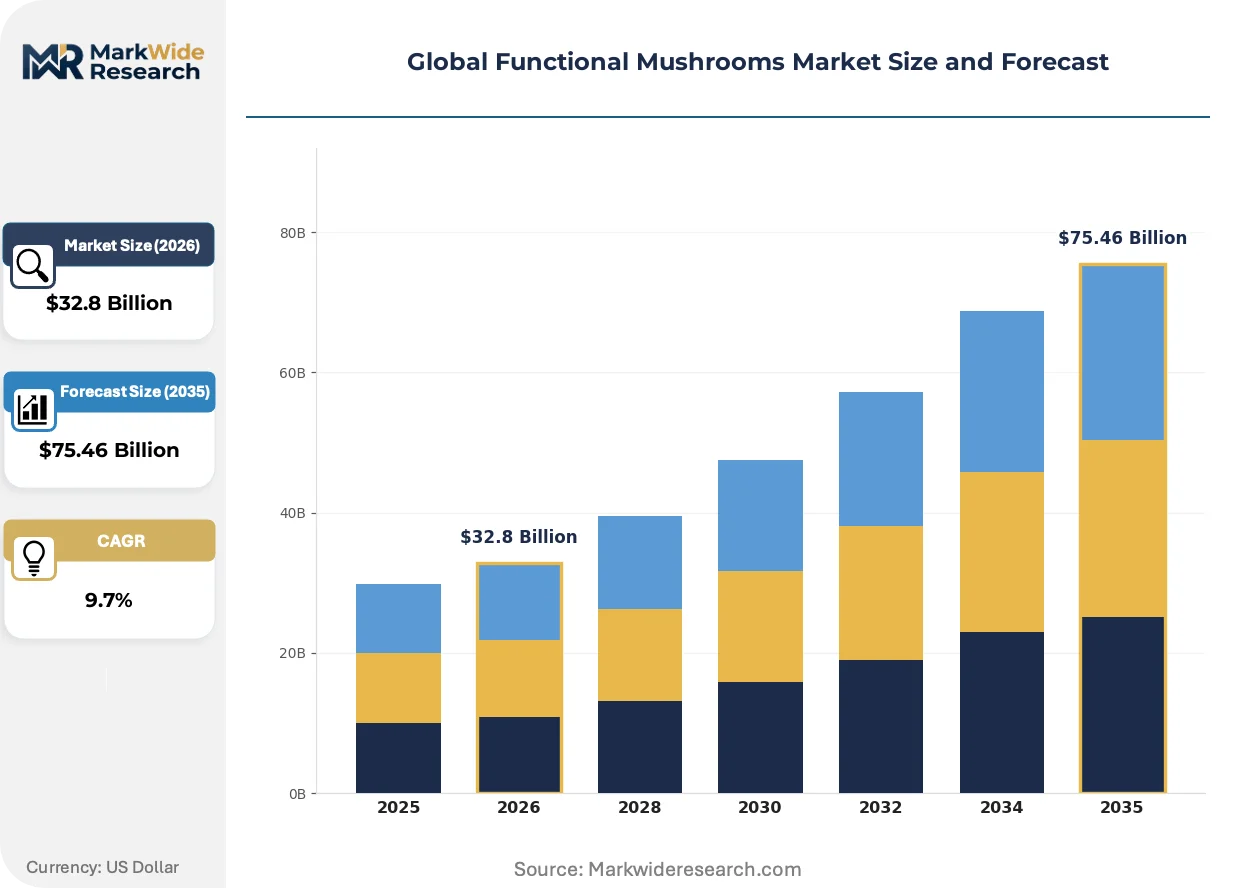
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $75.46 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reishi, Chaga, Lion's Mane, Cordyceps, Maitake, Turkey Tail Form: Powder, Extract, Capsule, Tea, Liquid, Tablet Application: Immune Support, Cognitive Enhancement, Energy Boost, Stress Relief, Sleep Aid, Antioxidant Support Distribution Channel: Online Retailers, Specialty Stores, Pharmacies, Health Clinics, Wellness Centers, Direct Sales |
| Companies Covered | Four Sigmatic, Hokkaido Reishi Co., Ltd., M2 Ingredients, Nammex, Real Mushrooms, Monterey Mushrooms Inc., Monaghan Mushrooms Group, Fungi Perfecti, Mitoku Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Functional Mushrooms Market Shifts & Advancements
Dual-extraction protocols combining hot water and ethanol phases are reshaping bioactive compound recovery rates, while regulatory divergence between FDA enforcement and EU Novel Food approvals is fragmenting formulation strategies across Atlantic markets.
Ultrasonic-assisted extraction is supplanting conventional heat-reflux methods for triterpenoid recovery from Reishi fruiting bodies. Premium supplement manufacturers in Germany and California are adopting this technology to achieve 40% higher ganoderic acid yields. The shift is compressing batch processing times from 48 hours to 6 hours, enabling smaller-scale producers to achieve pharmaceutical-grade output volumes.
EU Novel Food Regulation's 2024 expanded catalog of traditional foods from third countries is streamlining market access for documented mushroom species. This regulatory tailwind reduces safety dossier requirements for Japanese Reishi and Chinese Cordyceps strains with established consumption histories. North American extract importers are restructuring supply agreements to prioritize EU-validated raw material sources.
Specialty retail channel disintermediation is accelerating as wellness centers and functional medicine clinics source extracts directly from certified organic processors. This bypasses conventional supplement distributor markups of 35-50%. The pattern is most visible in United States metropolitan clusters where integrative health practitioners formulate custom mushroom blends for patient protocols.
Global Functional Mushrooms Market Segmentation
Channel configuration determines margin capture across the functional mushrooms value chain. Extract manufacturers calibrate product formats and species portfolios to match the compliance requirements and price sensitivity of each distribution pathway.
Product Type:
Reishi and Lion's Mane dominate pharmaceutical procurement channels, while Chaga and Cordyceps flow primarily through wellness retail and direct-to-consumer platforms.
- Reishi:Triterpenoid-rich fruiting body extracts command premium positioning in immunotherapy adjunct formulations. Hospital formulary acceptance in Germany and the United States concentrates institutional procurement volumes for standardized ganoderic acid products.
- Lion's Mane:Erinacine and hericenone compounds drive neurotrophic supplement demand. North American cognitive health brands source certified organic extracts for nootropic stack formulations targeting mental clarity applications.
- Chaga:Wild-harvested betulinic acid sources face supply pressure from submerged fermentation alternatives.
- Cordyceps:Cs-4 mycelial extracts dominate energy support applications in Asian and North American markets.
- Maitake:D-fraction beta-glucan concentrates serve oncology nutrition protocols in Japanese clinical settings.
- Turkey Tail:PSK and PSP polysaccharopeptides maintain steady demand in integrative cancer care formulations.
By volume, Reishi leads procurement across pharmaceutical and nutraceutical channels. By growth pace, Lion's Mane extracts are climbing the fastest in cognitive wellness applications.
Form:
Manufacturing cost tiers separate pharmaceutical-grade extracts from mass-market powders, with capsule and liquid formats capturing divergent margin profiles.
- Powder:Bulk raw material for supplement manufacturing and functional food integration. Chinese and Vietnamese processors supply standardized beta-glucan powders to European and North American formulators seeking cost-efficient blending inputs.
- Extract:Concentrated bioactive compounds from dual-extraction protocols. California and German specialty manufacturers deploy ultrasonic-assisted processing to achieve pharmaceutical-grade triterpenoid yields for clinical nutrition channels.
- Capsule:Convenience-driven consumer format with established shelf presence in US and European retail.
- Tea:Whole-fruiting-body or blended preparations for wellness center and specialty retail distribution.
- Liquid:Tincture and glycerite formats for functional medicine practitioner protocols.
- Tablet:Compressed formulations for pharmacy and mass-market supplement aisles.
Powder and capsule forms generate the highest absolute throughput. Extracts command the steepest price escalation and fastest value growth.
Application:
End-use concentration varies by regulatory environment, with immune and cognitive claims facing divergent substantiation requirements across FDA and EFSA jurisdictions.
- Immune Support:Beta-glucan and polysaccharide formulations for preventive health and adjunct therapy. German hospital nutrition departments and US integrative medicine clinics drive institutional procurement of validated Reishi and Turkey Tail extracts.
- Cognitive Enhancement:Nootropic positioning for Lion's Mane erinacines. Silicon Valley wellness brands and Tokyo functional food manufacturers compete for limited organic extract supply.
- Energy Boost:Cordyceps militaris and sinensis variants for athletic and occupational performance.
- Stress Relief:Adaptogenic Reishi formulations targeting cortisol modulation.
- Sleep Aid:Triterpenoid-rich extracts for circadian support applications.
- Antioxidant Support:Chaga melanin and superoxide dismutase concentrates for cellular protection claims.
Immune support commands the largest existing revenue base. Cognitive enhancement is gaining share fastest among premium-positioned applications.
Distribution Channel:
Channel selection determines compliance burden and margin retention, with direct and clinical pathways bypassing conventional retail markups.
- Online Retailers:Subscription models and marketplace platforms for branded finished goods. Four Sigmatic and similar direct-to-consumer operators capture recurring revenue through automated replenishment of powder and capsule formats.
- Specialty Stores:Curated assortments for educated wellness consumers. US metropolitan clusters and European urban centers host independent retailers emphasizing certified organic and dual-extracted products.
- Pharmacies:Regulated channel requiring substantiation documentation for health claims.
- Health Clinics:Practitioner-dispensed protocols for patient-specific formulations.
- Wellness Centers:On-premise retail and custom blending services.
- Direct Sales:Manufacturer-to-consumer fulfillment eliminating distributor margins.
Online retailers and specialty stores together move the highest product volumes. Health clinics and direct sales channels are expanding most quickly as practitioners and manufacturers seek margin protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German pharmaceutical channels while United States wellness retail absorbs margin compression from direct-to-consumer disintermediation. This asymmetry shapes regional procurement strategies and extract standardization investments.
United States
Integrative medicine clinics in California and New York Metro drive institutional procurement of dual-extracted Reishi and Lion's Mane for patient protocols. FDA's 2023 enforcement discretion shift on New Dietary Ingredient notifications is delaying novel species market entry. Silicon Valley wellness brands and Austin functional food manufacturers compete for limited certified organic extract supply.
Germany
Hospital nutrition departments in Bavaria and North Rhine-Westphalia anchor European demand for validated beta-glucan concentrates in adjunct immunotherapy. EFSA health claim substantiation requirements concentrate procurement among Novel Food-compliant suppliers. Heidelberg and Munich host specialty extract processors deploying ultrasonic-assisted extraction for pharmaceutical-grade triterpenoid yields.
China
Zhejiang and Fujian provinces dominate raw Reishi powder output for global nutraceutical formulators. NMPA and GB standards govern export quality certification for biomass and extract products. Qingdao and Shanghai processing clusters are integrating backward into controlled cultivation to secure year-round supply consistency.
Japan
Tokyo and Osaka functional food manufacturers sustain premium positioning for traditional Reishi and Maitake strains with documented consumption histories. METI and PMDA frameworks support streamlined Novel Food equivalency for established species in EU markets. Hokkaido cultivation clusters anchor specialized expertise in cold-climate Ganoderma strains.
Brazil
São Paulo and Rio de Janeiro wellness retail channels are expanding shelf space for standardized mushroom extracts in preventive health applications. ANVISA's accelerated natural product registration pathway is opening Latin America's largest nutraceutical market for compliant suppliers. Local formulators are restructuring procurement to prioritize EU-validated raw material sources.
Global Functional Mushrooms Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. Premium extract manufacturers in Germany and California deploy ultrasonic-assisted processing to achieve pharmaceutical-grade bioactive yields, while Chinese bulk processors compete on standardized beta-glucan powder volume. The vendor base stratifies into certified organic specialists, direct-to-consumer wellness brands, and integrated cultivation-extraction operators. Dominant competitive moves include backward integration into controlled cultivation and geographic diversification of raw material sourcing to mitigate single-region concentration risk.
Within the certified organic supply tier, Nammex and Real Mushrooms exemplify raw material provenance verification for North American and European formulators. Four Sigmatic occupies a position in the direct-to-consumer wellness brand archetype, leveraging subscription-based fulfillment to capture recurring revenue. Hokkaido Reishi Co., Ltd. anchors the specialized cultivation expertise segment through decades of focused Ganoderma strain development. These three player types represent the primary competitive vectors shaping procurement relationships and margin capture across pharmaceutical, nutraceutical, and wellness retail channels.
| Leading Market Players |
|---|
| Four Sigmatic |
| Hokkaido Reishi Co., Ltd. |
| M2 Ingredients |
| Nammex |
| Real Mushrooms |
| Monterey Mushrooms Inc. |
| Monaghan Mushrooms Group |
| Fungi Perfecti |
| Mitoku Company |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four month organic certification timelines compress inventory turnover for North American and European formulators, concentrating pricing power among pre-certified suppliers while forcing spot-market buyers into volatile short-term procurement. This lead-time rigidity amplifies cost premiums for verified Reishi and Lion's Mane extracts as FDA and EU Novel Food enforcement tightens compliance requirements.
Pricing Analysis
The customization-premium spread between practitioner-formulated extracts and mass-market powders spans three distinct tiers: pharmaceutical-grade ultrasonic-processed concentrates, certified organic dual-extracts for wellness brands, and commodity beta-glucan powders from Chinese processors. Price differentiation hinges on organic certification status and extraction technology sophistication, with ultrasonic-assisted triterpenoid recovery commanding substantial premiums over conventional heat-reflux methods. Cost compression in the commodity powder tier is intensifying as Vietnamese processors expand submerged fermentation capacity, eroding margins for non-integrated growers. Hospital procurement departments in Germany and California exhibit the lowest price sensitivity, while US mass-market supplement retailers face acute margin pressure from direct-to-consumer disintermediation.
Supply Chain Analysis
Inbound logistics costs for hardwood substrate shipments from Pacific Northwest forestry operations to Ganoderma cultivation facilities in Zhejiang province fluctuate with container availability on the Shanghai-Los Angeles trade lane. Raw material supply concentrates in China's Fujian and Zhejiang provinces for Reishi fruiting bodies, Japan's Hokkaido prefecture for cold-climate Ganoderma strains, and Vietnam's Da Lat highlands for controlled mycelial biomass. The supply chain draws from hardwood sawdust substrates, liquid fermentation media, and pharmaceutical-grade ethanol for dual-extraction protocols. Single-source vulnerability from Zhejiang's dominance of global Reishi powder output exposes European and North American formulators to tariff exposure and regulatory disruption. Distribution runs through certified organic processors to finished goods manufacturers, with wellness centers and direct-to-consumer channels bypassing conventional supplement distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against synthetic nootropic substitutes and plant-based adaptogen alternatives that threaten mushroom-derived cognitive and stress-relief positioning. Substitution risk intensifies as pharmaceutical manufacturers advance small-molecule compounds targeting similar immunomodulatory and neurotrophic pathways.
For Market Incumbents: Consolidate backward into controlled cultivation to secure year-round biomass supply and neutralize hardwood substrate cost volatility. Lock in multi-year organic certification pipelines to preempt competitor access to EU and North American premium channels. Synthetic nootropic launches from established pharmaceutical players threaten extract premiums in cognitive applications, making captive supply chains the critical defensive lever.
For New Entrants and Emerging Players: Practitioner-formulated custom blending services represent the most penetrable service-layer gap, as incumbent suppliers under-serve integrative medicine clinics seeking patient-specific protocols. Target Brazilian wellness retail through ANVISA's accelerated natural product registration pathway before established players localize supply chains. Deploy direct-to-subscription fulfillment models to capture recurring revenue without conventional retail margin sacrifice.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with under-monetized functional mushroom cultivation assets lacking extraction and branding capabilities. The five-to-ten year viability window favors acquisition of certified organic processors with validated Novel Food dossiers over speculative biomass expansion. Watch EU Novel Food approval velocity for Japanese and Chinese traditional strains as the signal for premium pricing sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Novel Food Dossier Completion | EU Novel Food approval unlocks automatic market access across 27 member states for compliant Reishi extracts. |
| Ultrasonic Extraction Scale-Up | German and California processors deploying this technology achieve pharmaceutical-grade triterpenoid yields in compressed batch cycles. |
| Controlled Cultivation Integration | Backward integration into bioreactor mycelial production neutralizes wild-harvested Chaga supply volatility and hardwood substrate cost exposure. |
| Direct-to-Practitioner Channel Development | Wellness center and functional medicine clinic bypass eliminates 35-50% distributor markups while capturing patient protocol loyalty. |
| ANVISA Registration Acceleration | Brazil's streamlined natural product pathway opens Latin America's largest nutraceutical market ahead of competitor localization. |
Research Methodology
The analysis maps Reishi cultivation clusters, Lion's Mane extraction technologies, Chaga supply alternatives, and Cordyceps fermentation systems, each validated through cultivation technologists, extraction process engineers, supplement formulators, and hospital nutrition procurement directors. Primary interviews with certified organic processors and wellness brand supply chain managers combined with secondary validation from FDA New Dietary Ingredient notifications, EU Novel Food approval databases, USDA National Organic Program certification records, and NMPA export quality filings. Bottom-up volume modeling from cultivation capacity and extraction throughput triangulated against top-down pharmaceutical and nutraceutical procurement estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled segmentation spanning mushroom species, extraction protocol sophistication, application claim substantiation requirements, and distribution channel compliance burden. CAGRs derived from trend extrapolation of procurement volumes in clinical nutrition and wellness retail channels, calibrated against organic certification pipeline constraints and Novel Food approval trajectories. Forecast inputs incorporated submerged fermentation capacity expansion, ultrasonic extraction technology adoption curves, and practitioner channel disintermediation velocity.
Material uncertainties — regulatory enforcement shifts, hardwood commodity price cycles, and synthetic substitute clinical advancement — sit outside the modeled envelope. Forecasts reflect assumptions about sustained EU Novel Food regulatory trajectory and continued hospital formulary acceptance of mushroom extracts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Middle East and Africa Functional Beverages Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Japan Functional Drinks Market
Functional Food and Beverage
Low Fat Protein Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Low-Fat and Low Protein Diet Market
Functional Food and Beverage
Functional Food and Beverage Market