
 Composites in Passenger Rail Market | 2026-2036
Composites in Passenger Rail Market Size, Share, and Industry Trends Forecast 2026-2036
Composites in Passenger Rail Market Analysis
EN 45545-2 fire safety certification for rail vehicle interiors is unwinding the supplier base as smaller compounders fail retesting cycles. Hexcel Corporation leverages its aerospace-derived prepreg expertise to qualify carbon fiber panels for European high-speed programs. Solvay anchors its position through integrated resin and adhesive supply to tier-one rail interior integrators. Gurit Holding AG specializes in vacuum-infused glass fiber structures for regional train retrofits across Northern Europe.
Composites in passenger rail encompass fiber-reinforced polymer systems—typically carbon fiber, glass fiber, or aramid fiber bound in epoxy matrices—engineered to achieve specific stiffness-to-weight ratios and fire-smoke-toxicity performance thresholds. These materials replace aluminum and steel in non-structural and semi-structural applications to reduce axle loads and improve energy efficiency. Carbon fiber formulations command premium positioning in body shells and roof components where weight reduction translates directly to operating cost savings. Glass fiber dominates flooring and interior panel applications where cost sensitivity outweighs marginal weight benefits. Epoxy resin systems capture expanding volume as OEMs consolidate adhesive and matrix supply under single-source qualification protocols.
The EU Green Deal's embedded carbon accounting rules and the F-Gas Regulation's phase-down of blowing agents for sandwich core production are reshaping material selection criteria across European supply chains. The US Federal Railroad Administration's passenger equipment safety standards and China's GB/T rail vehicle fire performance codes create divergent compliance pathways that fragment global product platforms. India's BIS certification requirements for rail interior materials are tightening as the country's national rail operator expands metro and semi-high-speed procurement. Stakeholders must track how regional qualification divergence affects platform standardization economics and supplier scale thresholds.
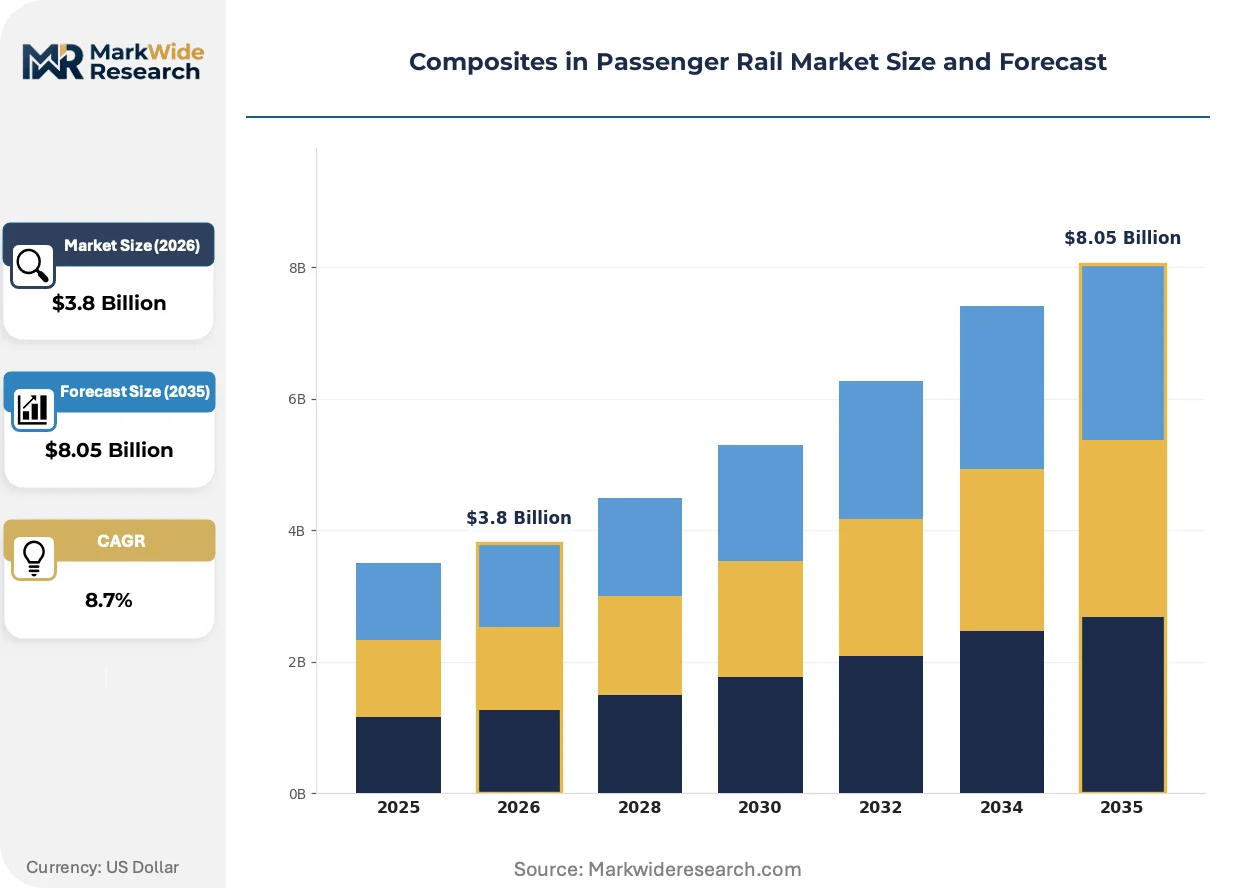
Market Dynamics
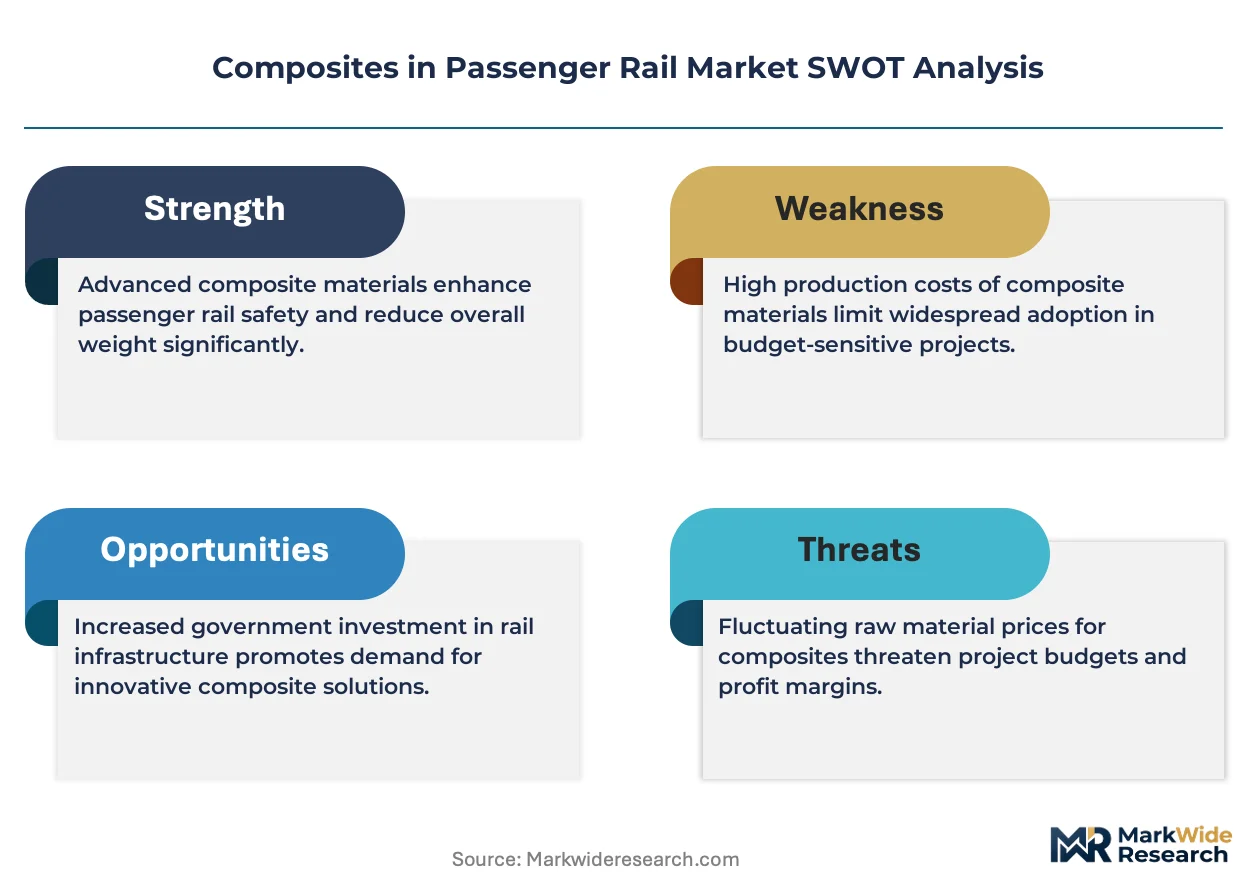
Fire safety certification under EN 45545-2 is compressing the supplier base for rail interior composites, as compounders face repeated retesting cycles that smaller firms cannot sustain. This regulatory filter is redistributing volume toward aerospace-qualified prepreg specialists and integrated resin-adhesive suppliers with captive testing infrastructure.
Growth Catalysts
- High-speed rail fleet expansion:Operators across Asia-Pacific are placing composite-intensive trainset orders to reduce axle loads and improve energy efficiency on new corridor builds.
- EU Green Deal embedded carbon accounting:Life-cycle assessment requirements are favoring fiber-reinforced polymers over aluminum in body shell applications where operating energy savings offset upstream emissions.
- Epoxy matrix consolidation:OEMs are consolidating adhesive and matrix supply under single-source qualification protocols, reducing supplier management overhead and accelerating platform homologation.
Market Restraints
- Fire-retardant resin cost volatility:Halogen-free phosphorus and nitrogen-based chemistries command premiums that strain flooring and interior panel economics.
- Prepreg supply concentration:Qualified aerospace-grade carbon fiber capacity clusters in the US and Japan, creating geographic single-source risk for European high-speed programs.
- Legacy aluminum substitution inertia:Established extrusion and welding infrastructure in regional train refurbishment channels slows composite retrofit adoption.
Strategic Opportunities
- India metro and semi-high-speed procurement:BIS certification tightening is creating first-mover advantage for compounders that pre-qualify under GB/T-aligned fire performance protocols.
- Vacuum-infused glass fiber regional retrofits:Northern European operators are unbundling interior refurbishment from OEM contracts, opening direct supplier relationships.
- F-Gas Regulation phase-down:The EU's restriction on hydrofluorocarbon blowing agents for sandwich core production is accelerating bio-based and thermoplastic alternative development.
Industry Challenges
- Multi-jurisdiction certification timelines:Divergent FRA, GB/T, and EN 45545 testing protocols force parallel qualification tracks that extend product launch cycles.
- Fire-smoke-toxicity formulation expertise scarcity:Compounders with proven EN 45545-2 R1-R7 compliance records command wage premiums that drain talent from mid-tier competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composites in Passenger Rail Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panels, Structures, Seating, Interiors Material: Carbon Fiber, Glass Fiber, Aramid Fiber, Epoxy Application: Body Shells, Roof Components, Window Frames, Flooring End User: Rail Operators, OEMs, Maintenance Providers, Component Suppliers |
| Companies Covered | Hexcel Corporation, Solvay, Toray Industries, Inc., TEIJIN LIMITED, BASF SE, Gurit Holding AG, Owens Corning, SGL Carbon, 3A Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composites in Passenger Rail Market Emerging Trajectories
Material qualification protocols and procurement models are diverging across regulatory jurisdictions, forcing suppliers to maintain parallel development tracks rather than global product platforms. Three developments are compressing competitive position.
Thermoplastic composite tapes are fragmenting the prepreg-dominated landscape for interior panels and flooring substrates. Tier-one rail interior integrators in Germany and France are piloting automated fiber placement with polyetherimide and polyphenylene sulfide matrices to enable welding-based assembly and end-of-life recyclability. This shift is fragmenting the historical epoxy-prepreg supply base into thermoplastic-qualified and legacy-only tiers.
The F-Gas Regulation's staged reduction of global warming potential in blowing agents is forcing core suppliers to reformulate sandwich structures. European OEMs are now specifying bio-based PET and thermoplastic foam cores in new tenders, with compliance deadlines compressing qualification windows for traditional polyurethane systems. High-speed body shell programs with long development cycles face the steepest reformulation penalties.
Buyers are unbundling interior refurbishment contracts from rolling stock OEMs and sourcing directly through specialized composite integrators. This channel disintermediation is visible in Northern Europe's regional train retrofit market, where operators like SJ and DSB are consolidating multi-fleet interior upgrades under single composite specialists rather than original train builders. The shift transfers fire safety liability and long-term material traceability obligations downstream.
Composites in Passenger Rail Market Segmentation
Segmentation in rail composites tracks how regulatory fire-safety tiers, material stiffness requirements, and procurement channel unbundling concentrate margin across distinct product categories. Each dimension carries divergent qualification burdens and supplier scale thresholds.
Product Type:
Domestic production concentrates in seating and interiors for regional retrofit programs, while export demand concentrates in structural panels for high-speed body shells. Chinese and Japanese OEMs source panels through captive tier-one integrators; European operators unbundle interiors for direct supplier relationships.
- Panels:Vacuum-infused glass fiber dominates flooring and sidewall applications where EN 45545-2 R1-R7 compliance is mandatory. Northern European operators like SJ and DSB source directly from specialized integrators rather than rolling stock OEMs. This channel shift transfers fire safety liability downstream and compresses pricing transparency.
- Structures:Carbon fiber prepreg formulations command premium positioning in load-bearing body shells and roof components. Demand concentrates in China's CRRC supply chain and Japan's Shinkansen expansion programs where axle load reduction translates to operating cost savings. Aerospace-qualified suppliers leverage existing testing infrastructure to meet rail qualification cycles.
- Seating:Fire-retardant polyurethane and thermoplastic shells dominate metro and regional train procurement. India's BIS certification tightening is disqualifying legacy compounders without captive testing labs.
- Interiors:Integrated ceiling, luggage rack, and partition systems require harmonized smoke-toxicity performance across adhesive and substrate. OEMs are consolidating matrix and adhesive supply under single-source protocols to accelerate homologation.
Structures holds the largest share; momentum sits with panels as refurbishment channels unbundle from OEM contracts.
Material:
Cost tiers separate aerospace-grade carbon fiber from commodity glass fiber, with epoxy resin systems capturing expanding volume as qualification protocols consolidate. Thermoplastic tapes are fragmenting the traditional prepreg base for interior applications.
- Carbon Fiber:Aerospace-derived prepreg expertise transfers to rail body shells where stiffness-to-weight ratios determine energy efficiency gains. Qualified capacity clusters in the US and Japan, creating geographic single-source risk for European high-speed programs.
- Glass Fiber:Vacuum-infused E-glass and S-glass formulations dominate flooring and interior panels where cost sensitivity outweighs marginal weight benefits. Northern European regional retrofits represent the fastest-expanding demand channel as operators prioritize lifecycle cost over upfront capital.
- Aramid Fiber:Ballistic and puncture-resistant applications in cab fronts and underframe guards. Niche volume concentrated in specialized security-specified trainsets.
- Epoxy:Dominant matrix chemistry for fire-retardant formulations, with halogen-free phosphorus and nitrogen-based systems commanding supply premiums. OEM consolidation of adhesive and matrix supply under single-source qualification protocols is favoring integrated resin suppliers with captive compounding.
Glass fiber captures the highest volume; carbon fiber claims the steepest expansion trajectory as high-speed fleet orders accelerate.
Application:
Application segmentation tracks the structural hierarchy from primary load-bearing shells to replaceable interior substrates, with each tier carrying distinct fire-safety classification and supplier qualification requirements.
- Body Shells:Carbon fiber sandwich structures with aluminum honeycomb or bio-based PET cores. EU Green Deal embedded carbon accounting favors these systems over aluminum where operating energy savings offset upstream emissions. F-Gas Regulation deadlines are forcing core reformulation for programs with long development cycles.
- Roof Components:Curved carbon fiber panels for pantograph housings and HVAC enclosures. Weight reduction here improves center-of-gravity stability and reduces catenary wear.
- Window Frames:Pultruded glass fiber profiles replacing aluminum extrusions. Simpler fire-safety classification than structural shells allows mid-tier compounder participation.
- Flooring:Glass fiber-reinforced epoxy with fire-retardant additives. Halogen-free chemistry premiums strain economics in high-volume metro procurement.
Body shells command the highest unit value; flooring represents the largest addressable volume across retrofit and new-build channels.
End User:
Procurement authority is shifting from integrated OEMs to direct operator relationships in refurbishment channels, while new-build high-speed programs retain OEM-centric sourcing.
- Rail Operators:Northern European incumbents like Deutsche Bahn and SNCF are unbundling interior refurbishment from rolling stock contracts. Direct sourcing transfers material traceability obligations and long-term fire safety liability to specialized composite integrators.
- OEMs:CRRC, Alstom, and Siemens Mobility consolidate tier-one composite supply for new high-speed and metro platforms. Single-source qualification protocols for epoxy matrix and adhesive systems favor integrated resin suppliers.
- Maintenance Providers:Regional retrofit specialists in Germany and France are capturing vacuum-infused glass fiber volume as operators consolidate multi-fleet interior upgrades.
- Component Suppliers:Tier-two compounders face compression as EN 45545-2 retesting cycles disqualify smaller firms without captive fire-testing infrastructure.
OEMs retain dominant procurement share for new-build platforms; rail operators are gaining the fastest procurement authority in refurbishment channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal embedded carbon accounting and F-Gas Regulation deadlines are redrawing procurement maps across high-speed corridors. Operators in Germany, China, Japan, India, and France now drive divergent qualification protocols that fragment global product platforms.
China
CRRC's tier-one composite ecosystem captures expanding fleet orders for carbon-intensive trainsets on Beijing-Shanghai and Chengdu-Chongqing corridors. GB/T rail vehicle fire performance codes create compliance pathways distinct from European EN 45545 standards. Qingdao and Changchun manufacturing clusters concentrate vacuum-infused panel production for domestic metro and export high-speed programs.
Germany
Deutsche Bahn's unbundling of interior refurbishment contracts opens direct supplier relationships for Northern European regional retrofits. KBA oversight of rail vehicle approval tightens material traceability obligations under EU Green Deal lifecycle assessment rules. Bavaria and North Rhine-Westphalia host specialized composite integrators serving multi-fleet upgrade programs.
Japan
Shinkansen expansion programs on Hokkaido and Kyushu lines prioritize axle load reduction through carbon fiber body shell procurement. METI industrial policy supports domestic prepreg capacity expansion for rail-aerospace crossover applications. Nagoya industrial corridor concentrates Toray-affiliated composite fabrication for next-generation N700S derivatives.
India
BIS certification tightening for rail interior materials accelerates as Indian Railways expands metro and semi-high-speed procurement in Mumbai, Delhi, and Bangalore corridors. PLI scheme incentives for domestic manufacturing attract compounders with captive fire-testing infrastructure. Gujarat and Maharashtra industrial zones emerge as qualification hubs for GB/T-aligned protocol adaptation.
France
SNCF's direct sourcing consolidation for TGV interior refurbishment transfers fire safety liability to specialized integrators. ANSM oversight of material safety intersects with REACH chemical compliance for halogen-free resin formulations. Auvergne-Rhône-Alpes and Île-de-France clusters concentrate thermoplastic tape pilot programs for automated fiber placement.
Composites in Passenger Rail Market Vendor Landscape
Player mix skews toward aerospace-qualified prepreg specialists and integrated resin-adhesive suppliers with captive testing infrastructure. Market structure concentrates around three strategic archetypes: carbon fiber formulators with rail-qualified body shell capacity, glass fiber vacuum-infusion specialists for refurbishment channels, and thermoplastic tape developers disrupting epoxy-prepreg dominance. Competitive moves center on single-source qualification protocol consolidation and geographic capacity expansion near CRRC and European OEM assembly points.
Within the aerospace-derived tier, Hexcel Corporation and Toray Industries occupy positions exemplifying carbon fiber prepreg expertise transfer to rail qualification cycles. Gurit Holding AG represents the vacuum-infusion specialization vector for Northern European retrofit markets. Solvay anchors the integrated resin-adhesive supply archetype favored by OEMs consolidating matrix and bonding systems under unified protocols.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Solvay |
| Toray Industries, Inc. |
| TEIJIN LIMITED |
| BASF SE |
| Gurit Holding AG |
| Owens Corning |
| SGL Carbon |
| 3A Composites |
| Others |
Supply Flow & Price Mechanics
Twelve-month qualification timelines for EN 45545-2 R1-R7 compliance compress supplier margins while concentrating pricing power among compounders with captive fire-testing infrastructure. This lead-time rigidity forces buyers into long-term offtake contracts that lock in resin and fiber pricing before volume ramps materialize.
Pricing Analysis
Certification tier creates the primary spread across composite formulations, with aerospace-qualified prepreg commanding premiums over commodity glass fiber in body shell applications. Three-tier pricing structure separates EN 45545-2 certified systems from GB/T-aligned alternatives and uncertified legacy compounds. Pricing pressure stems from halogen-free phosphorus resin premiums that strain flooring economics in high-volume metro procurement. Regional train operators exhibit highest price sensitivity, while high-speed OEMs prioritize performance over unit cost.
Supply Chain Analysis
China and Japan anchor carbon fiber prepreg capacity for rail-aerospace crossover applications, while Germany and Northern European clusters concentrate vacuum-infused glass fiber production for refurbishment channels. Raw material dependencies center on Toray-affiliated PAN precursor supply, Huntsman epoxy resin systems, and bio-based PET core alternatives accelerating under F-Gas Regulation deadlines. Single-source vulnerability concentrates in qualified aerospace-grade carbon fiber capacity clustered outside Europe. Distribution runs through tier-one rail interior integrators consolidating multi-fleet contracts under direct operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proven fire-smoke-toxicity formulation expertise has become the scarcest capability in rail composites, with compounders bearing EN 45545-2 compliance records commanding wage premiums that drain talent from mid-tier competitors. This talent compression justifies aggressive capability-building investments.
For Market Incumbents: Secure captive fire-testing infrastructure to accelerate retesting cycles that disqualify smaller compounders under EN 45545-2 protocols. Consolidate epoxy matrix and adhesive supply under single-source qualification frameworks to deepen OEM relationships. Expand vacuum-infusion capacity in Northern European industrial zones to capture unbundled refurbishment contracts from Deutsche Bahn and SNCF. For New Entrants and Emerging Players: GB/T-aligned certification fast-tracks offer entry pathways into Indian Railways procurement as BIS requirements tighten for metro and semi-high-speed corridors. Target vacuum-infused glass fiber regional retrofits where operators like SJ and DSB have unbundled interiors from OEM contracts. Partner with specialized composite integrators to transfer fire safety liability downstream while building track records. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EN 45545-2 retesting cycles are structurally compressing the supplier base toward aerospace-qualified prepreg specialists and integrated resin-adhesive suppliers. Target compounders with captive fire-testing labs and existing rail qualification records rather than greenfield technology bets. Watch thermoplastic tape pilot programs at SNCF and Deutsche Bahn as inflection indicators for epoxy-prepreg displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Hexcel and Solvay anchor positions by controlling halogen-free phosphorus chemistry supply for EN 45545-2 compliance. |
| GB/T Certification Pre-Qualification | First-mover compounders capture Indian Railways metro procurement as BIS requirements align with Chinese fire performance protocols. |
| Thermoplastic Tape Pilot Scale-Up | Automated fiber placement with polyetherimide matrices enables welding-based assembly and end-of-life recyclability for SNCF and Deutsche Bahn. |
| Bio-Based PET Core Development | F-Gas Regulation deadlines force sandwich core reformulation, accelerating qualification windows for traditional polyurethane alternatives. |
| Direct Operator Relationship Consolidation | SJ and DSB unbundling transfers fire safety liability to specialized integrators, compressing tier-two compounder channel access. |
Methodological Framework
A standing panel of rail interior procurement directors, composite compounder R&D leads, EN 45545-2 testing laboratory managers, and tier-one integrator supply chain executives provided ongoing calibration across primary fieldwork. Secondary validation drew from EU Official Journal regulatory filings, CRRC annual supplier disclosures, BIS certification registries, and customs trade data for carbon fiber and epoxy resin flows. Bottom-up segment modeling triangulated against top-down corridor fleet order aggregation.
Cross-referencing against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, material chemistry, application structural tier, and procurement channel authority dimensions. CAGRs derived from fleet replacement cycles, regulatory compliance deadlines, and OEM platform homologation timelines. Key inputs included high-speed trainset order pipelines, F-Gas Regulation phase-down schedules, and embedded carbon accounting thresholds under EU Green Deal implementation.
Decision-makers should treat outputs as directional under assumptions of sustained EN 45545-2 enforcement stringency and continued CRRC supply chain concentration; material deviation in regulatory harmonization or thermoplastic substitution rates would warrant model refresh. Recalibration cycles align with material shifts in fire safety certification protocols, core material substitution deadlines, and operator procurement unbundling momentum.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Train Transformer Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Poland Rail Freight Transport Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Point Machine Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Railway Sleepers Market
Railway Transportation
Rail Pads Market