
 Railway Roof Switches Market | 2026-2036
Railway Roof Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Roof Switches Market Analytics
Urban metro operators is rotating demand away from legacy freight-focused infrastructure providers toward passenger-rail modernization programs. Siemens leverages its integrated signaling portfolio to anchor large-scale European retrofit contracts. Wabtec competes through North American freight-rail specialization, while Alstom sustains competitive positioning via high-speed rail expertise across multiple continents. Knorr-Bremse dominates braking and switching integration, a technical pairing that railway procurement teams increasingly specify.
Railway roof switches are electromechanical devices mounted on rolling stock roofs to route high-voltage power between pantograph contact systems and onboard electrical networks, typically rated for 15-25 kV AC or 1.5-3 kV DC operation with mechanical endurance exceeding 100,000 cycles. Their primary purpose is enabling safe isolation, grounding, and transfer of traction power during multi-system locomotive border crossings or depot maintenance sequences. Electric switches command the largest installed base due to widespread 25 kV electrification, though IoT-enabled systems represent the fastest-expanding category as predictive condition monitoring reduces unplanned downtime. Digital systems capture concentrated margin pools where operators bundle roof switches with train control management system upgrades.
EU F-Gas Regulation and REACH compliance frameworks constrain material selection for insulating components, pushing manufacturers toward halogen-free thermoset formulations. The US Federal Railroad Administration enforces crashworthiness and electrical clearance standards that shape roof switch housing geometries for North American rolling stock. China's GB standards and NMPA-equivalent rail certification processes govern market entry for foreign suppliers serving CRRC procurement channels. Stakeholders must monitor how carbon-border adjustment mechanisms and copper-alloy sourcing rules reshape total cost of ownership calculations for switch assemblies.
Market Dynamics
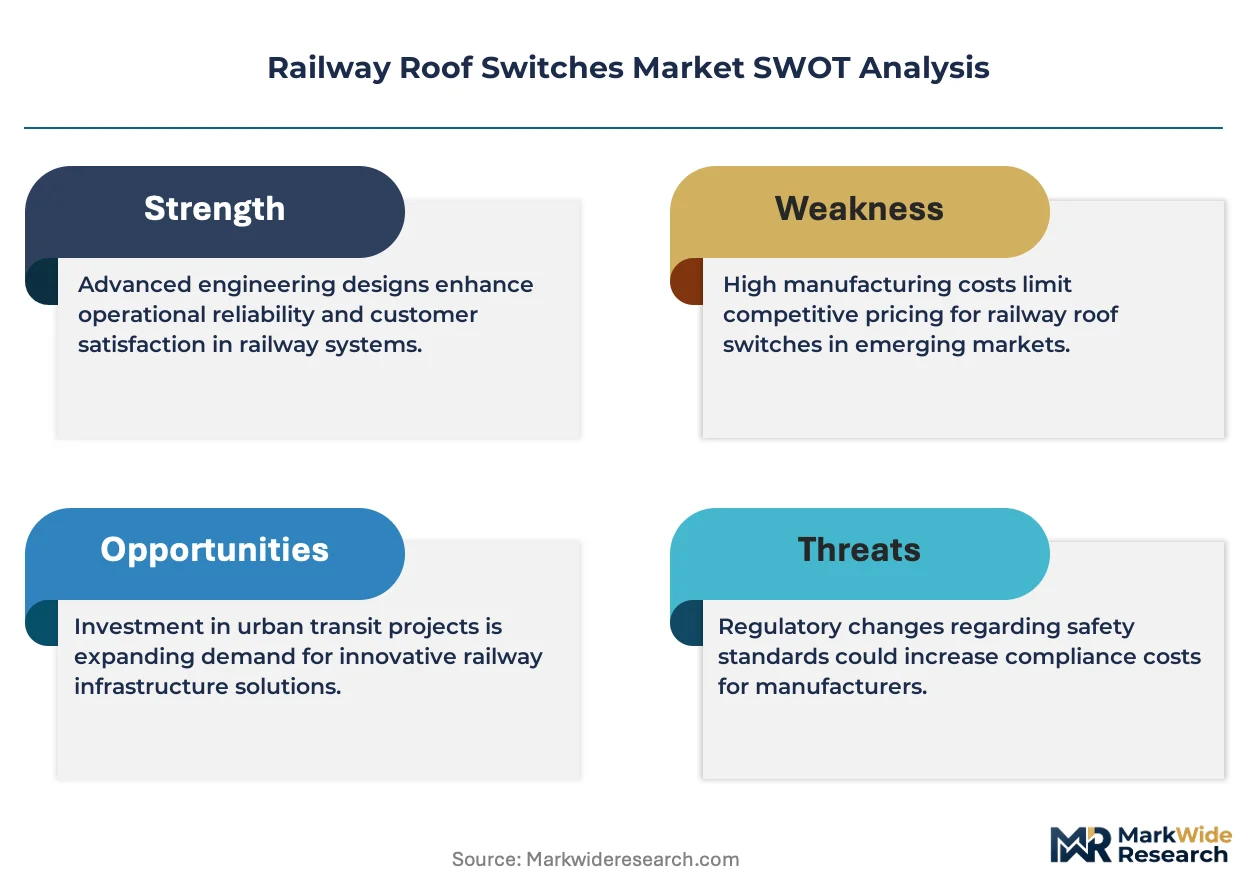
The EU F-Gas Regulation is compressing replacement cycles for legacy roof switch assemblies across European electrified networks. Operators now face material compliance deadlines that accelerate capital deployment toward climate-compatible switching architectures.
Growth Catalysts
- Urban Metro Electrification:Passenger-rail operators in Germany's Ruhr corridor are modernizing legacy fleets with 25 kV AC roof switch systems. Depot infrastructure upgrades drive parallel demand for integrated grounding and isolation hardware.
- REACH Material Mandates:Halogen-free thermoset formulations are displacing legacy insulating compounds in switch housings. Manufacturers reformulate production lines to maintain EU market access under ECHA compliance frameworks.
- Multi-System Locomotive Deployment:Border-crossing traction power requirements in Central Europe necessitate dual-voltage roof switch configurations. Rolling stock procurement specifications increasingly embed switching flexibility as standard.
Market Restraints
- Copper-Alloy Input Volatility:Contact assembly materials face price instability from concentrated Chilean and Peruvian mining output. Switch manufacturers absorb margin compression or pass costs to rail operators through indexed contracts.
- Specialized Supplier Concentration:Precision-machined contact systems depend on a limited German and Swiss supplier base. Geographic clustering creates vulnerability to regional logistics disruptions or energy cost spikes.
- Mechanical Endurance Ceilings:Conventional electromechanical designs approach operational limits near 150,000 cycles. Physical wear mechanisms constrain maintenance-interval extensions that operators demand.
Strategic Opportunities
- IoT-Enabled Predictive Systems:Condition-monitoring sensors embedded in roof switch housings enable downtime reduction through failure-anticipation algorithms. European operators pilot these systems in high-frequency metro deployments.
- Train Control Management Convergence:Digital roof switch integration with TCMS upgrades creates bundled procurement opportunities. Vendors capture expanded margin pools where switching hardware and control software merge.
- North American Freight Retrofit:US Class I railroads face FRA-mandated electrical clearance standard updates. Crashworthiness-compliant roof switch housing redesigns open replacement demand in aging diesel-to-electric conversion programs.
Industry Challenges
- High-Voltage Certification Timelines:IEC 60077 and EN 50155 testing protocols extend product validation cycles to 18-24 months. Development teams must front-load capital before revenue recognition.
- Legacy System Integration Friction:Digital switching architectures encounter compatibility barriers with 1980s-era trainline communication buses. Retrofit projects require custom interface engineering that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Roof Switches Market |
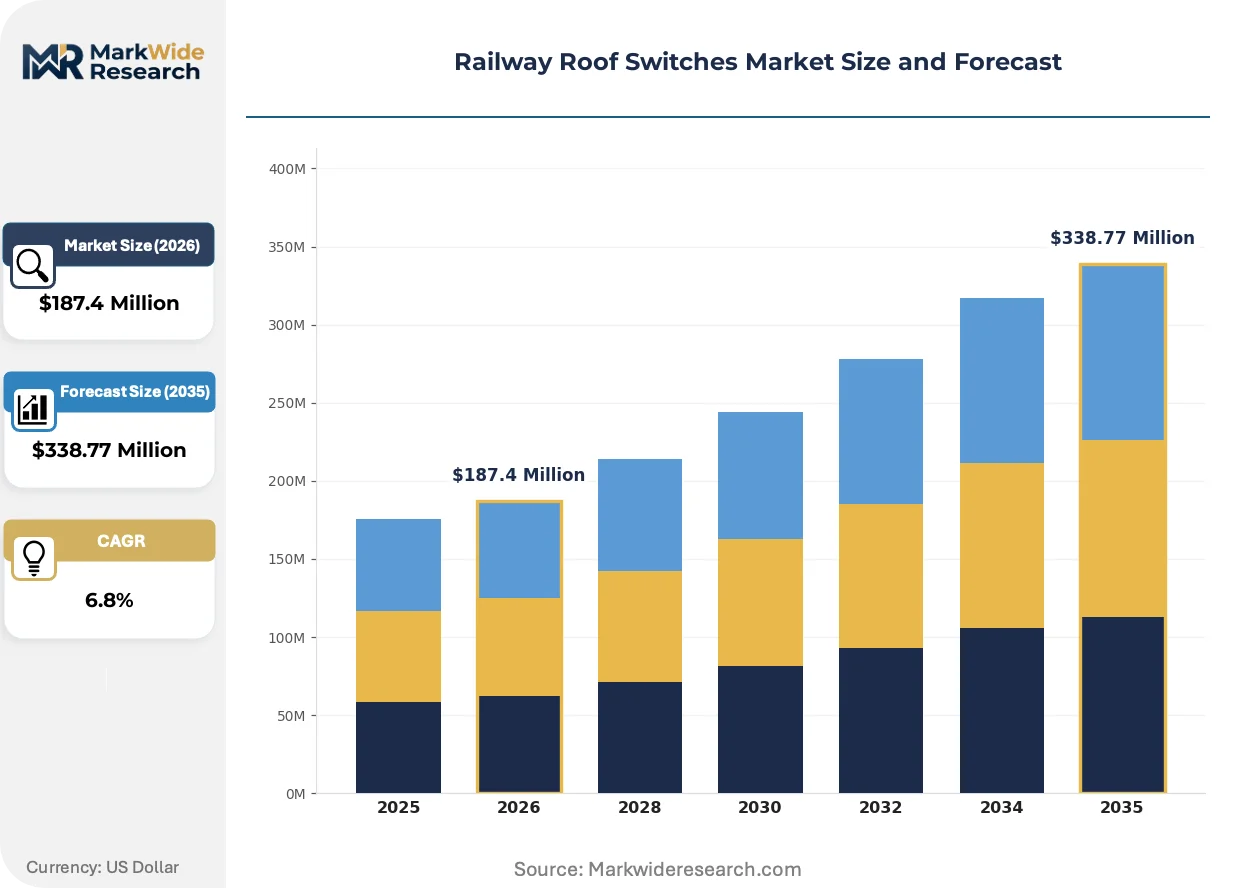
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Switches, Electric Switches, Pneumatic Switches, Remote Control Switches Application: Railway Interlocking, Track Maintenance, Station Operations, Signal Control End User: Railway Operators, Infrastructure Providers, Maintenance Contractors, Government Agencies Technology: Analog Systems, Digital Systems, IoT-enabled Systems, Hybrid Systems |
| Companies Covered | Siemens, Wabtec, Narstco, Vossloh, Alstom, Knorr-Bremse, DT, China Railway Shanhaiguan Bridge Group, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Roof Switches Market Evolving Landscape
Electrification architecture decisions are forcing roof switch technology toward modular, software-defined configurations. Hardware-software integration is becoming the primary axis of vendor differentiation.
Silicon carbide power semiconductors are entering traction power distribution circuits with superior thermal performance and switching speed. High-speed rail operators in France and Japan test these materials for 25 kV system efficiency gains. The technology is bifurcating procurement specifications between legacy electromechanical buyers and solid-state early adopters.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-related material bans that indirectly constrain switch housing polymer selection. Insulating component suppliers reformulate halogen-free compounds to maintain dielectric performance under humidity cycling. German KBA type-approval processes now embed climate-impact documentation requirements that extend certification timelines.
After-sales service unbundling is separating hardware procurement from maintenance contracting in European metro authorities. Paris and Vienna operators now source roof switches through capital budgets while negotiating predictive maintenance subscriptions separately. This bifurcation compresses upfront equipment margins while expanding recurring revenue pools for diagnostics-capable vendors.
Railway Roof Switches Market Segmentation
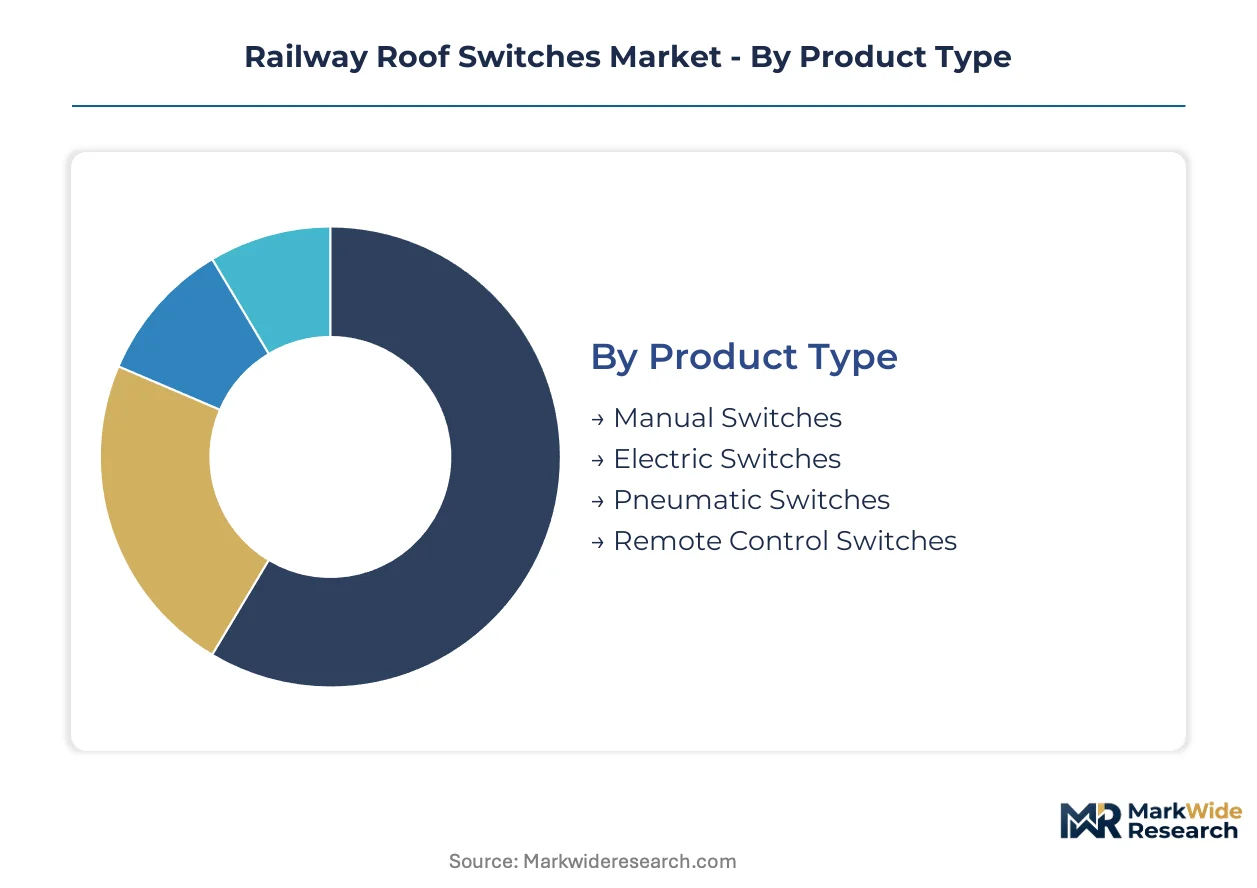
Roof switch procurement patterns diverge sharply across product architectures and operational contexts. Margin concentration follows electrification intensity and predictive maintenance adoption curves rather than raw unit volume.
Product Type:
Margin pools concentrate in electrified switching systems where depot integration and high-voltage certification create technical barriers to substitution.
- Manual Switches:Mechanical lever-actuated assemblies requiring direct operator intervention for circuit isolation. Demand persists in heritage railway preservation networks and developing-market freight corridors where electrification density remains low.
- Electric Switches:Solenoid-driven contact mechanisms rated for 15-25 kV AC traction power distribution. Germany's Ruhr corridor operators specify these for high-frequency metro turnarounds where automated depot sequences compress dwell times.
- Pneumatic Switches:Compressed-air actuated systems leveraging existing trainline pneumatic infrastructure. Legacy locomotive fleets in Central European border-crossing routes maintain these for compatibility with established maintenance protocols.
- Remote Control Switches:Wireless-actuated isolation systems enabling ground crew operation without roof access. Adoption concentrates in North American freight yards where FRA confined-space regulations elevate operator safety premiums.
Electric switches hold installed capacity. Remote control switches are rotating up the share rankings.
Application:
Application-based demand splits between infrastructure-bound installations and mobile rolling-stock integration, with divergent procurement cycles and technical specifications.
- Railway Interlocking:Trackside signal coordination systems requiring roof switch state feedback for route clearance authorization. European ERTMS deployment mandates drive specification harmonization across national networks.
- Track Maintenance:Temporary power isolation during overhead line inspection and repair sequences. Maintenance contractors in France's SNCF network prioritize rapid-deployment portable switching units for possession-time efficiency.
- Station Operations:Platform-level power management for stabling and turnaround maneuvers. Urban metro authorities in Vienna and Paris bundle these with platform screen door electrification upgrades.
- Signal Control:Integration with cab signaling and automatic train protection systems. Digital architectures here demand IEC 61375-compliant trainline communication interfaces that legacy electromechanical switches cannot satisfy.
Interlocking applications anchor replacement revenue. Station operations are climbing the fastest as urban electrification accelerates.
End User:
End-user procurement authority determines specification complexity and service bundling terms, with direct operators capturing the most integrated switching architectures.
- Railway Operators:Integrated passenger and freight carriers specifying roof switches as part of fleet-wide electrification programs. DB Cargo and SNCF Réseau drive dual-voltage flexibility requirements for cross-border traction power compatibility.
- Infrastructure Providers:Track and catenary system owners procuring switches for maintenance vehicle fleets. Germany's DB Netz segments these purchases from rolling-stock operator specifications, creating parallel certification pathways.
- Maintenance Contractors:Third-party service providers acquiring portable and temporary switching equipment. Specialized contractors in the UK rail privatization framework compete for possession-time minimization contracts that reward rapid isolation capability.
- Government Agencies:National transport ministries funding legacy network modernization through capital grant programs. EU Cohesion Fund allocations in Poland and Romania prioritize climate-compatible switching upgrades as conditionality for disbursement.
Railway operators dominate specification authority. Government agencies are expanding fastest where public funding backstops electrification transitions.
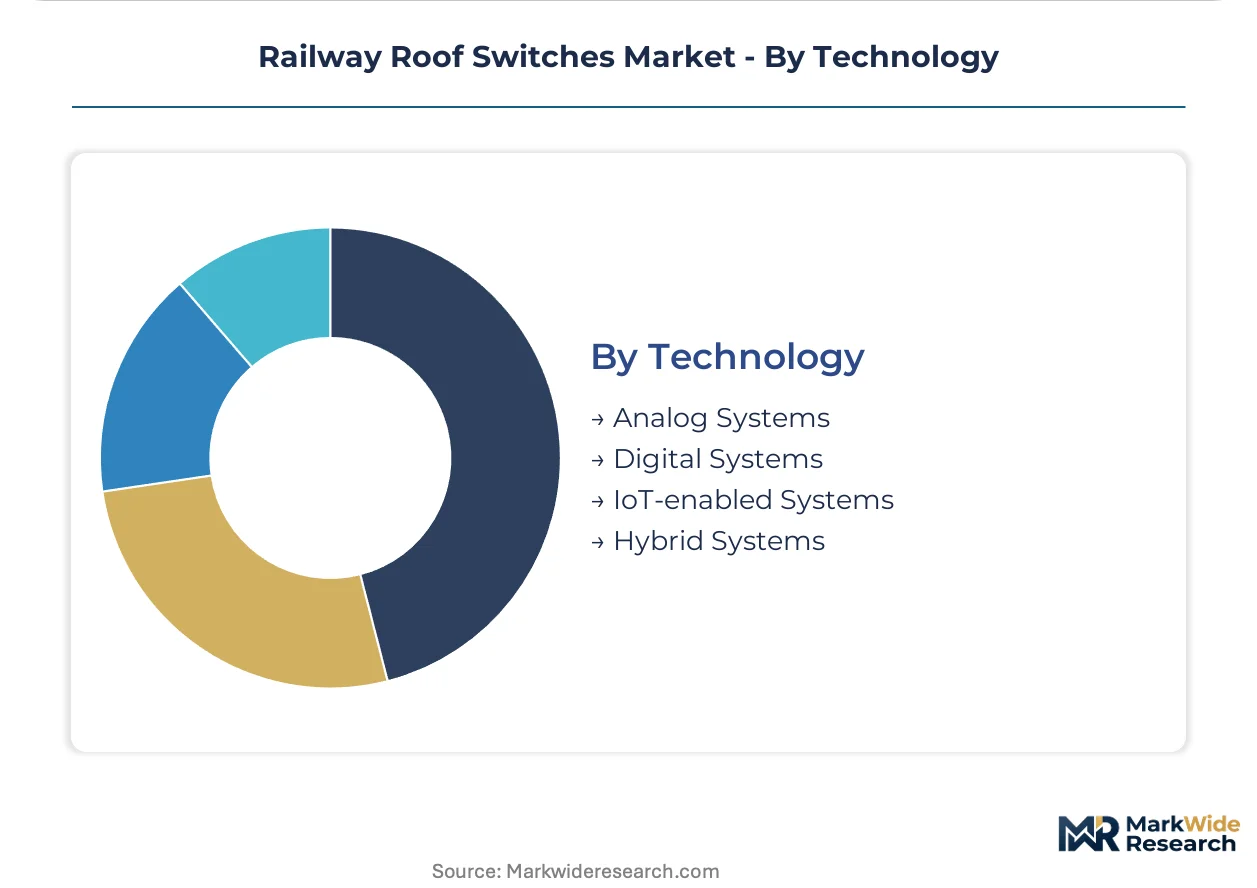
Technology:
Technology-based segmentation reveals a bifurcation between legacy electromechanical reliability and predictive digital architectures, with hybrid systems bridging transition timelines.
- Analog Systems:Hardwired electromechanical contactors with discrete position sensing and no trainline data integration. Installed base concentration in Eastern European freight corridors delays replacement where capital constraints persist.
- Digital Systems:Microprocessor-controlled switching with integrated diagnostics and TCMS compatibility. Siemens and Alstom embed these in new-build high-speed rolling stock to enable condition-based maintenance scheduling.
- IoT-enabled Systems:Sensor-embedded housings transmitting vibration, temperature, and contact wear data to cloud analytics platforms. Pilot deployments in London Underground and Tokyo Metro target unplanned downtime reduction through failure anticipation algorithms.
- Hybrid Systems:Electromechanical contact mechanisms with digital monitoring overlays preserving legacy reliability while adding diagnostic visibility. Operators in Switzerland's SBB network favor these for alpine route modernization where environmental harshness demands proven mechanical endurance.
Analog systems retain installed base dominance. IoT-enabled configurations are gaining share fastest where predictive maintenance contracts restructure vendor revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor's electrified freight density underwrites Germany's central role in European roof switch demand. High-voltage catenary networks spanning the Rhine-Alpine corridor create concentrated replacement cycles for legacy switching hardware.
Germany
DB Cargo's dual-voltage locomotive procurement drives specification complexity for border-crossing traction power. KBA type-approval processes now embed climate-impact documentation that extends certification timelines. The Ruhr corridor's depot modernization programs concentrate demand for automated isolation and grounding systems in Essen and Dortmund maintenance facilities.
France
SNCF Réseau's ERTMS deployment mandates harmonized roof switch state feedback for route clearance authorization. ANSM-equivalent rail safety frameworks govern material selection for insulating components in switch housings. The Île-de-France region's RER electrification upgrades anchor replacement demand in Paris suburban networks.
United States
Class I railroad diesel-to-electric conversion programs generate crashworthiness-compliant housing redesign requirements. FRA electrical clearance standards shape roof switch geometries for North American rolling stock. Chicago's intermodal freight terminals drive concentrated procurement for maintenance vehicle fleet upgrades.
China
CRRC's high-speed rail expansion sustains demand for 25 kV AC switching systems in new-build rolling stock. GB standards and NMPA-equivalent rail certification processes govern market entry for foreign suppliers. The Beijing-Tianjin-Hebei corridor's intercity electrification concentrates procurement authority in northern maintenance hubs.
Switzerland
SBB's alpine route modernization favors hybrid electromechanical-digital systems for environmental harshness endurance. Swissmedic-equivalent rail safety oversight constrains material selection for humidity-cycling performance. The Gotthard Base Tunnel's maintenance vehicle fleets require specialized high-altitude switching configurations.
Railway Roof Switches Market Competitive Landscape
Concentration sits with integrated rail technology conglomerates that bundle roof switches within broader electrification portfolios. Siemens and Alstom leverage signaling integration to anchor large-scale European retrofit contracts. Wabtec occupies the North American freight specialization vector. Knorr-Bremse dominates braking-switching integration that procurement teams increasingly specify. Strategic moves center on TCMS convergence partnerships and predictive maintenance service unbundling.
Among Germany-based industrial conglomerates, Siemens AG exemplifies the integrated signaling-electrification archetype. Alstom SA represents the high-speed rail specialization position across multiple continents. Wabtec Corporation anchors the North American freight-rail focus. These three occupy distinct competitive territories defined by geographic end-market concentration and rolling-stock category expertise rather than direct product overlap.
| Leading Market Players |
|---|
| Siemens |
| Wabtec |
| Narstco |
| Vossloh |
| Alstom |
| Knorr-Bremse |
| DT |
| China Railway Shanhaiguan Bridge Group |
| Hitachi |
| Others |
Value Network & Pricing Analysis
Halogen-free thermoset formulation substitution for legacy insulating compounds is redrawing supplier geography toward ECHA-compliant polymer producers while compressing margins for reformulation-dependent manufacturers serving EU procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and after-sales bundling intensity. Premium tiers capture IEC 60077 and EN 50155 certified systems with predictive maintenance subscriptions, while economy tiers serve developing-market freight operators with manual switch configurations. Price differentiation hinges on copper-alloy contact quality and KBA type-approval documentation completeness. Cost compression in mid-tier electric switches is intensifying because REACH compliance timelines accelerate material reformulation capex. Government agencies funding electrification grants exhibit lowest price sensitivity; maintenance contractors competing on possession-time efficiency show highest.
Supply Chain Analysis
Chilean and Peruvian mining concentration for copper-alloy contact materials creates single-source vulnerability for precision-machined contact assemblies. German and Swiss suppliers dominate high-voltage insulating component fabrication, while Chinese manufacturers scale standard-grade switch housings. Raw material flows draw from Chilean copper concentrate, German halogen-free polymer compounds, and Japanese silver-cadmium oxide contact tips. Distribution runs through rolling stock OEM procurement channels and infrastructure provider maintenance vehicle fleets, with depot-level spare parts stocking concentrated in Ruhr corridor and Beijing-Tianjin-Hebei maintenance hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railway operator consolidation across European passenger-rail networks is shifting procurement leverage toward integrated fleet electrification programs, amplifying buyer power in roof switch specification authority.
For Market Incumbents: Compound defensive positioning through backward integration into copper-alloy contact machining and captive halogen-free polymer compound production. Siemens and Alstom anchor large-scale retrofit contracts by embedding roof switches within TCMS upgrade bundles. Threat from IoT-enabled predictive system entrants demands accelerated certification investment in IEC 61375-compliant trainline interfaces. Priority lever: predictive maintenance service unbundling to capture recurring revenue pools separate from hardware margins. For New Entrants and Emerging Players: Differentiate on IoT-enabled condition monitoring for high-frequency metro deployments where unplanned downtime costs dominate procurement criteria. White-space targets include North American Class I freight diesel-to-electric conversion programs requiring FRA crashworthiness-compliant housing redesigns, and UK maintenance contractor portable switching equipment for possession-time minimization contracts. Go-to-market angle: predictive diagnostics subscriptions bundled with hardware procurement to restructure buyer TCO calculations. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid electromechanical-digital system specialists with proven alpine or harsh-environment endurance records. Long-term viability favors vendors bridging legacy reliability with diagnostic visibility as operators navigate 15-20 year fleet replacement cycles. Acquisition target archetype: precision-machined contact system suppliers with concentrated German-Swiss supplier relationships. Signal to watch: EU F-Gas Regulation phase-down acceleration forcing material reformulation capex compression among non-compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| TCMS Convergence Partnership | Digital roof switch integration with Siemens train control systems captures bundled procurement margin pools. |
| Predictive Maintenance Service Unbundling | Paris and Vienna metro authorities now source hardware through capital budgets while negotiating diagnostics subscriptions separately. |
| Halogen-Free Polymer Reformulation | ECHA compliance investments preserve EU market access as F-Gas Regulation constrains insulating material selection. |
| North American Freight Retrofit Program | FRA electrical clearance standard updates open replacement demand in aging diesel-to-electric conversion fleets. |
| Dual-Voltage Configuration Development | DB Cargo and SNCF Réseau specifications embed switching flexibility for cross-border traction power compatibility. |
Research Methodology
The analysis maps electric, pneumatic, remote control, and manual switch sub-sectors, each validated through rolling stock procurement directors, infrastructure maintenance vehicle fleet managers, and ERTMS deployment program officers. Primary interviews with OEM platform engineers, depot maintenance supervisors, and third-party maintenance contractors combined with secondary validation from IEC standard documentation, KBA type-approval records, and EU Cohesion Fund disbursement databases. Bottom-up unit deployment tracking and top-down electrification capex aggregation enable triangulation across modeling approaches.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, application context, end-user procurement authority, and technology generation tier. CAGRs derived from rolling stock fleet replacement cycle analysis, electrification program funding trajectories, and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporate ERTMS deployment schedules and F-Gas Regulation phase-down timelines.
The analysis sits within stated boundaries; outcomes outside sustained electrification funding commitment or copper-alloy price stability assumptions would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and fleet modernization program continuity. Practitioners should keep alternative scenarios live as EU climate-border adjustment mechanisms and REACH material restriction expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Point Machine Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Global Railcar Leasing Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Urban Rail Transit Signaling Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Autonomous Train Technology Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Train Transformer Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market