
 Railway Air Conditioning System Market | 2026-2036
Railway Air Conditioning System Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Air Conditioning System Market Analysis
EN 50155 railway electronic equipment certification is redrawing competitive boundaries for thermal system suppliers seeking European rolling stock contracts. Siemens AG leverages its embedded signaling and traction portfolio to bundle climate packages with platform modernization programs. Mitsubishi Electric Corporation anchors Asian high-speed rail projects through localized production and JIS-compliant component sourcing.
Railway air conditioning systems comprise vapor compression and absorption refrigeration assemblies engineered to maintain 22-26°C cabin environments across ambient ranges from -25°C to +55°C while withstanding continuous vibration, electromagnetic interference, and voltage fluctuations inherent to rail operation. Rooftop units dominate passenger coach deployments where space constraints and weight distribution favor ceiling-integrated configurations. Vapor compression technology leads installed base volumes but faces margin compression from refrigerant transition costs under evolving environmental protocols.
F-Gas Regulation in Europe and EPA SNAP program requirements in the United States are accelerating refrigerant phase-down timelines that force redesign cycles across compressor and heat exchanger architectures. China's NMPA-aligned rail equipment certification and India's BIS standards for rolling stock electromechanical systems add parallel compliance layers for multinational suppliers. Stakeholders must weigh captive refrigerant supply commitments against modular platform strategies as regulatory divergence deepens between major procurement jurisdictions.
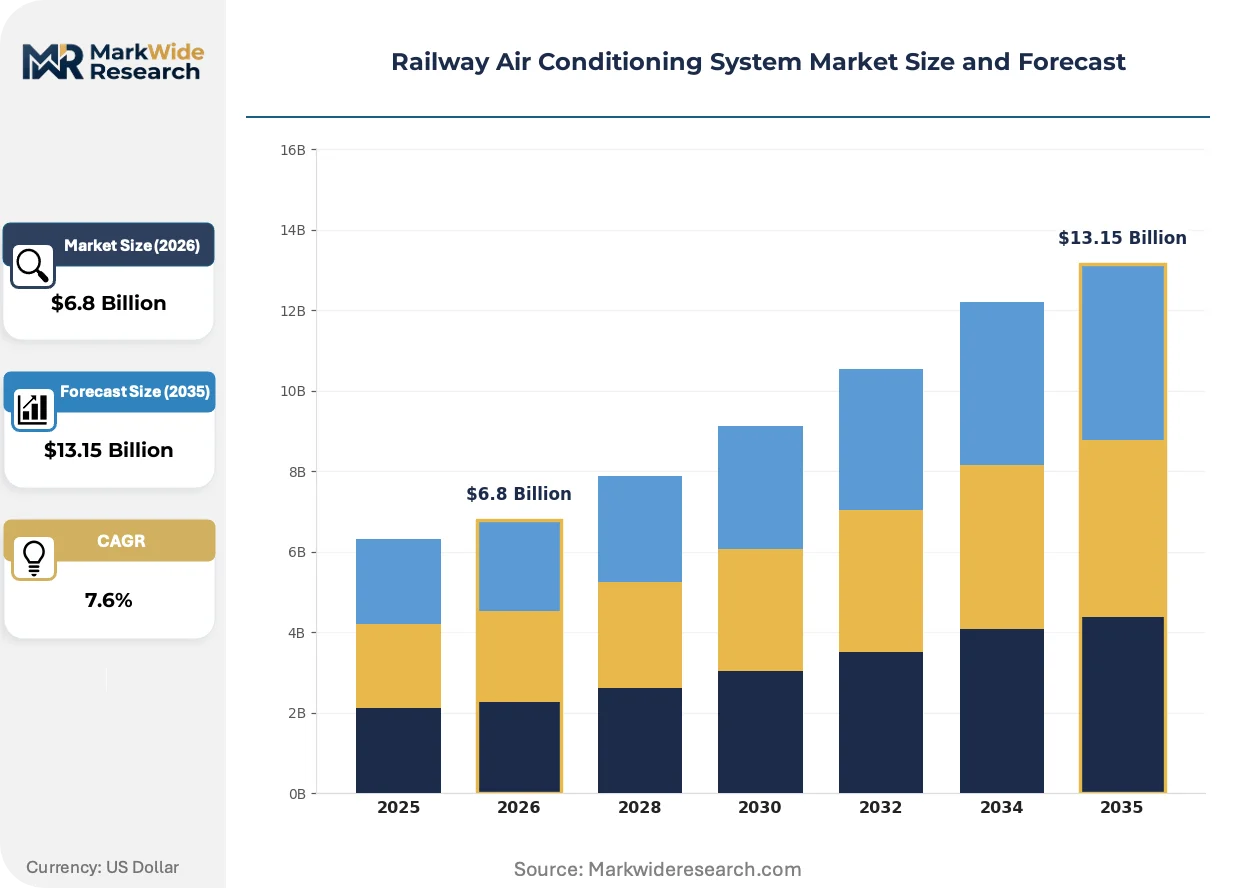
Market Dynamics
The railway air conditioning sector is undergoing forced refrigerant architecture redesign as F-Gas Regulation phase-down timelines compress product development cycles across European rolling stock procurement corridors.
Growth Catalysts
- India's BIS electromechanical certification:Rolling stock modernization mandates under the PLI scheme are accelerating climate-control retrofits across suburban and metro networks facing extreme thermal loads.
- High-speed rail electrification:China's dual carbon goals and fleet expansion programs are generating concentrated demand for integrated HVAC-traction bundles in new corridor deployments.
- Rooftop unit standardization:Space-constrained passenger coaches across urbanizing Asian corridors favor ceiling-integrated configurations that reduce weight distribution complexity.
Market Restraints
- Refrigerant cost volatility:Transition to low-GWP alternatives under EPA SNAP and F-Gas Regulation is inflating compressor and heat exchanger input costs before scale economies materialize.
- Supply concentration in compressor manufacturing:Critical rotating component production clusters in East Asian industrial zones expose procurement timelines to single-source vulnerability.
- Electromagnetic compatibility thresholds:EN 50155 certification requirements for railway electronics impose design constraints that extend validation timelines for thermal system controllers.
Strategic Opportunities
- Underpenetrated African corridors:Trans-African rail modernization initiatives present first-mover positioning for suppliers capable of delivering tropical-climate-rated rooftop units.
- Convergence of predictive maintenance and thermal telemetry:IoT-enabled condition monitoring integration with HVAC control systems opens recurring revenue streams through service unbundling.
- Japan's JIS-compliant component sourcing:METI-supported localization requirements for Shinkansen expansion create partnership pathways for qualified subsystem suppliers.
Industry Challenges
- Cross-certification timeline compression:Parallel EN 50155, BIS, and NMPA validation tracks for multinational suppliers strain technical documentation and testing capacity.
- Legacy fleet integration complexity:Retrofit installations in decades-old rolling stock require custom mounting adaptations that erode modular platform economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Air Conditioning System Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split System, Rooftop Unit, Compact Unit, Centralized System Technology: Vapor Compression, Absorption Refrigeration, Thermoelectric, Evaporative Cooling Application: Passenger Coaches, Freight Trains, Locomotives, Maintenance of Way End User: Transit Authorities, Private Operators, Freight Companies, Military Transport |
| Companies Covered | Knorr-Bremse AG, Mitsubishi Electric Corporation, Hitachi Ltd., Siemens AG, Liebherr-Transportation Systems, Honeywell International Inc., Thermo King Corporation, Trane Technologies plc, Songz Automobile Air Conditioning Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Air Conditioning System Market Emerging Trajectories
Refrigerant chemistry transitions and embedded intelligence are actively restructuring how thermal systems are specified, procured, and maintained across rail operator fleets.
CO2 transcritical cycle technology is fragmenting conventional vapor compression dominance in high-speed rail applications. European operators under F-Gas Regulation pressure are piloting these systems in cross-border corridor deployments. The technology is fragmenting supplier competitive sets by rewarding those with captive refrigerant handling capabilities and punishing pure-play assemblers.
REACH-aligned substance restrictions are forcing heat exchanger material substitutions across EU rolling stock supply chains. Aluminum microchannel designs are displacing copper-brass architectures in rooftop unit manufacturing. German and French procurement authorities are now specifying corrosion-resistant coatings that comply with both REACH and EN 50155 environmental testing protocols.
Operator procurement departments are consolidating HVAC specification authority into centralized fleet management functions. Regional rail authorities in Spain and Italy are unbundling climate system procurement from complete trainset contracts to enable multi-source thermal subsystem competition. This concentration of buying power is most visible in Mediterranean corridor electrification programs where lifecycle cost modeling now dominates capital expenditure evaluation.
Railway Air Conditioning System Market Segmentation
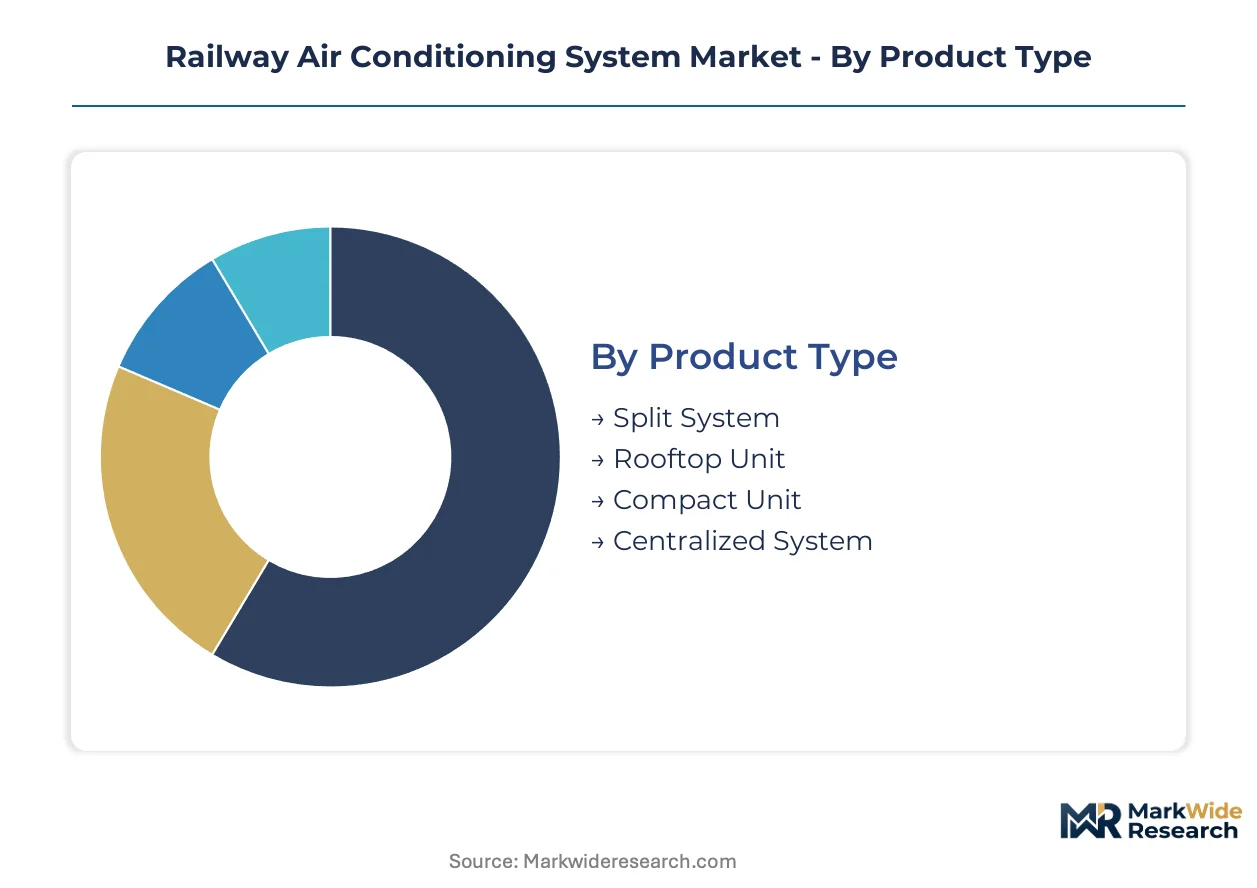
Railway air conditioning procurement splits across four dimensions that each carry distinct certification burdens and lifecycle economics. Product type determines physical integration constraints, while technology choice locks suppliers into specific refrigerant compliance pathways under regional environmental mandates.
Product Type:
F-Gas Regulation in Europe and EPA SNAP requirements in the United States impose divergent refrigerant handling protocols that reshape competitive positioning across unit architectures.
- Rooftop Unit:Ceiling-integrated assemblies dominate passenger coach deployments where space constraints and weight distribution favor compact overhead mounting. Indian metro networks under BIS electromechanical certification mandates are driving concentrated retrofit demand for these configurations in extreme summer thermal corridors.
- Split System:Separated compressor and evaporator arrangements enable flexible installation in legacy rolling stock with irregular internal geometries. Chinese high-speed rail operators pursuing dual carbon goals are specifying split architectures for integrated HVAC-traction bundles in new corridor electrification programs.
- Compact Unit:Self-contained modules serve narrow-gauge and regional services where axle load limits restrict equipment mass.
- Centralized System:Distributed cooling plants with carriage-length ducting appear in premium long-distance configurations requiring uniform cabin zoning.
Rooftop units handle the majority of throughput; split systems are expanding most quickly on share as retrofit flexibility gains procurement priority.
Technology:
Cost tier differentiation separates mature vapor compression from emerging alternatives facing scale and certification headwinds.
- Vapor Compression:Mechanical refrigeration cycles using synthetic or natural working fluids constitute the installed base majority. Transition costs to low-GWP alternatives under evolving environmental protocols are compressing margins for suppliers lacking captive refrigerant supply.
- Absorption Refrigeration:Thermal-driven systems using lithium bromide or ammonia pairs suit locomotive applications with waste heat recovery potential. Deployment concentrates in freight corridors where diesel-electric traction generates sufficient thermal energy to drive cooling cycles.
- Thermoelectric:Solid-state Peltier assemblies serve niche military transport specifications requiring vibration immunity and refrigerant-free operation.
- Evaporative Cooling:Water-based systems appear in arid-climate maintenance-of-way vehicles where humidity tolerance permits simplified thermal management.
Vapor compression maintains volume leadership; absorption refrigeration is climbing the fastest as waste heat integration economics improve.
Application:
Customer type concentration varies sharply across rolling stock categories, with passenger service commanding premium specification authority.
- Passenger Coaches:Climate-controlled cabins for commuter, intercity, and high-speed services require continuous operation across ambient ranges from -25°C to +55°C. EN 50155 certification for railway electronics imposes design constraints that extend validation timelines for thermal controllers in European procurement corridors.
- Locomotives:Cab cooling for motive power units prioritizes reliability over precision given intermittent occupancy and harsh electromagnetic environments.
- Freight Trains:Refrigerated wagon applications for temperature-sensitive cargo represent a specialized subsegment with distinct compressor duty cycles.
- Maintenance of Way:Track repair and inspection vehicles utilize simplified cooling given temporary occupancy and open-cab configurations.
Passenger coaches absorb the dominant share of specification investment; freight trains are gaining share fastest as cold-chain rail logistics expand.
End User:
Procurement centralization patterns split between public authority fleet management and fragmented private operator decision-making.
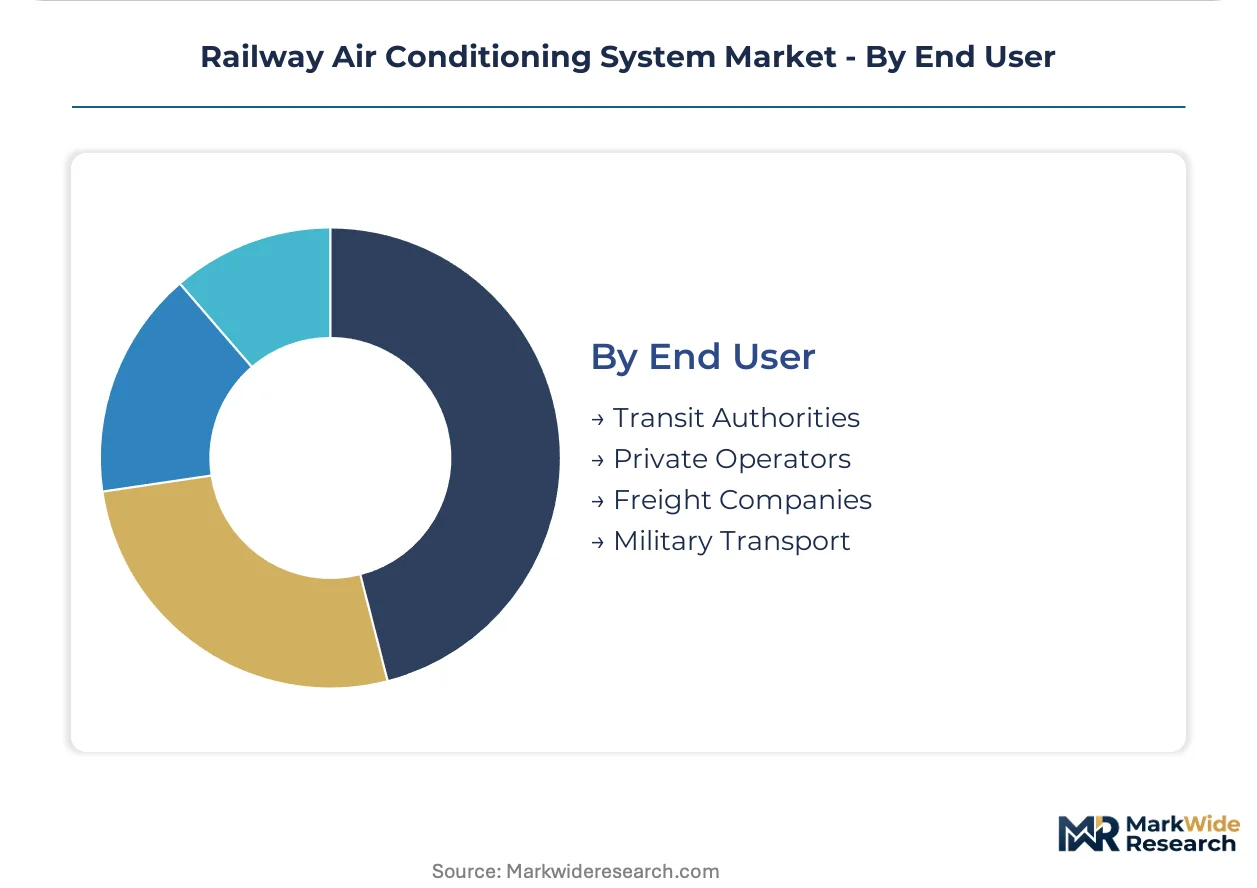
- Transit Authorities:Municipal and regional public operators in Spain and Italy are unbundling climate system procurement from complete trainset contracts to enable multi-source thermal subsystem competition.
- Private Operators:Commercial rail service providers prioritize lifecycle cost modeling over capital expenditure minimization in rolling stock replacement cycles.
- Freight Companies:Cargo rail operators specify cooling primarily for refrigerated wagon fleets and motive power cabs.
- Military Transport:Defense procurement channels demand hardened systems with electromagnetic pulse tolerance and extended mean-time-between-failures.
Transit authorities control the largest procurement volumes; private operators are expanding fastest as rail service liberalization proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Beijing-Shanghai high-speed corridor underwrites China's commanding position in railway air conditioning procurement volumes. India's Dedicated Freight Corridors and metro expansions in Delhi, Mumbai, and Bangalore generate concentrated climate-control retrofit demand. Germany's Rhine-Alpine freight axis anchors European specification authority for EN 50155-certified thermal systems.
China
High-speed rail electrification under dual carbon goals is driving integrated HVAC-traction bundles across new corridor deployments. NMPA-aligned rail equipment certification imposes parallel compliance layers for multinational suppliers seeking procurement access. Manufacturing clusters in Changchun and Qingdao concentrate rooftop unit production for domestic fleet expansion and export markets.
India
Metro networks in Delhi, Mumbai, and Bangalore face extreme summer thermal loads exceeding 45°C ambient temperatures. BIS electromechanical certification mandates under the PLI scheme accelerate climate-control retrofits across suburban corridors. Manufacturing activity concentrates in Pune and Chennai, where suppliers localize production for both domestic metro authorities and neighboring South Asian export markets.
Germany
Cross-border corridor electrification programs generate specification authority for EN 50155-certified thermal controllers in European rolling stock. F-Gas Regulation phase-down timelines compress product development cycles for compressor and heat exchanger architectures. Industrial concentration in Munich and Nuremberg supports systems integration with embedded signaling and traction portfolios.
United States
Amtrak fleet modernization and commuter rail electrification in the Northeast Corridor drive demand for split-system retrofits in legacy rolling stock. EPA SNAP program requirements accelerate refrigerant transition timelines that inflate input costs before scale economies materialize. Supplier engineering offices cluster in Pittsburgh and Chicago, proximate to major transit authority procurement decision centers.
Japan
Shinkansen expansion programs under METI-supported localization requirements create partnership pathways for qualified subsystem suppliers. JIS-compliant component sourcing standards reward suppliers with captive refrigerant handling capabilities and localized production footprints. Manufacturing concentration in Nagoya and Osaka supports integration with precision compressor and heat exchanger supply chains.
Railway Air Conditioning System Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage dimensions. The supplier base organizes around three strategic archetypes: diversified industrial conglomerates with embedded rail portfolios, pure-play thermal specialists with captive refrigerant capabilities, and regional fabricators serving localized procurement corridors. Competitive positioning hinges on cross-certification velocity for EN 50155, BIS, and NMPA standards. Consolidation pressure concentrates among mid-scale assemblers lacking backward integration into compressor manufacturing.
Within the diversified industrial tier, Siemens AG and Mitsubishi Electric Corporation exemplify platform bundling strategies that combine climate systems with signaling and traction portfolios. Knorr-Bremse AG occupies a position among brake and HVAC integrated suppliers serving European and Asian procurement authorities. These three entities represent contrasting geographic anchoring strategies—German platform integration, Japanese localized production, and cross-regional certification breadth.
| Leading Market Players |
|---|
| Knorr-Bremse AG |
| Mitsubishi Electric Corporation |
| Hitachi Ltd. |
| Siemens AG |
| Liebherr-Transportation Systems |
| Honeywell International Inc. |
| Thermo King Corporation |
| Trane Technologies plc |
| Songz Automobile Air Conditioning Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
EN 50155 certification gates both supplier qualification and price differentiation simultaneously, as European rolling stock procurement corridors reward validated thermal controllers with premium positioning while excluding uncertified competitors from specification lists entirely. F-Gas Regulation compliance costs cascade through refrigerant handling protocols, compressing margins for assemblers lacking captive supply while concentrating pricing power among integrated manufacturers.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with transit authorities leveraging consolidated fleet orders to extract standard-tier pricing from suppliers while private operators absorb premium rates for customized retrofit configurations. Price differentiation hinges on EN 50155 certification grade and after-sales service bundling, with certified controllers commanding substantial premiums over uncertified alternatives. Cost compression in standard-tier vapor compression systems is intensifying because refrigerant transition expenses under EPA SNAP and F-Gas Regulation are inflating input costs before scale economies materialize. Municipal transit authorities exhibit the highest price sensitivity, prioritizing lifecycle cost minimization over capital expenditure, while military transport procurement demonstrates the lowest sensitivity due to electromagnetic pulse tolerance requirements.
Supply Chain Analysis
Compressor manufacturing concentration in China, Japan, and Germany creates a chokepoint that exposes procurement timelines to single-source vulnerability when geopolitical disruptions interrupt component flows. Critical rotating component production draws from specialized steel alloys, rare-earth magnets, and precision-machined castings that rest on concentrated metallurgical supply chains. Tariff exposure runs through cross-border compressor shipments between East Asian industrial zones and European assembly plants. Distribution runs through OEM-integrated bundling with complete trainset contracts, though Spanish and Italian transit authorities are unbundling climate system procurement to enable multi-source thermal subsystem competition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railway air conditioning incumbents face substitution defense imperatives as CO2 transcritical cycle technology fragments conventional vapor compression dominance and rewards suppliers with captive refrigerant handling capabilities.
For Market Incumbents: Compound defensive positioning through backward integration into compressor manufacturing to secure supply chain control against East Asian production concentration risks, while accelerating EN 50155, BIS, and NMPA cross-certification velocity to outpace validation timeline compression that strains mid-scale assemblers. Prioritize captive refrigerant supply commitments over modular platform strategies as regulatory divergence deepens between European F-Gas Regulation and EPA SNAP compliance pathways. For New Entrants and Emerging Players: Anchor in underpenetrated African corridor modernization initiatives where tropical-climate-rated rooftop units face limited qualified competition, targeting first-mover positioning in Trans-African rail electrification programs. Exploit partnership pathways with METI-supported localization requirements for Japan's Shinkansen expansion through JIS-compliant component sourcing capabilities. Deploy IoT-enabled predictive maintenance integration as the primary go-to-market angle to capture recurring revenue streams through thermal telemetry service unbundling. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across CO2 transcritical cycle development programs as European operators pilot cross-border corridor deployments under F-Gas Regulation pressure. Target acquisition profiles should emphasize mid-scale assemblers possessing backward integration gaps but holding validated certification portfolios across multiple procurement jurisdictions. Monitor refrigerant cost volatility trajectories as the critical inflection signal, with sustained elevation in low-GWP alternative pricing indicating consolidation pressure concentration among pure-play thermal specialists lacking captive supply.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Certification Velocity Investment | Parallel EN 50155, BIS, and NMPA validation unlocks procurement access across European, Indian, and Chinese rolling stock corridors simultaneously. |
| Captive Refrigerant Supply Commitment | Backward integration into low-GWP refrigerant handling insulates margin compression from F-Gas Regulation and EPA SNAP transition cost inflation. |
| Predictive Maintenance Platform Integration | IoT-enabled thermal telemetry convergence with HVAC control systems generates recurring service revenue unbundled from equipment sales. |
| Localized Production Footprint Expansion | METI-supported JIS-compliant component sourcing in Nagoya and Osaka corridors captures Shinkansen expansion procurement preference. |
| African Corridor First-Mover Positioning | Tropical-climate-rated rooftop unit deployment in Trans-African rail modernization secures specification authority before incumbent saturation. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with rolling stock procurement officers, thermal system engineering directors, and rail operator maintenance chiefs, combined with secondary validation against UNIFE railway industry databases, national rolling stock production statistics, and EN 50155 certification registries. Bottom-up triangulation aggregated unit-level procurement data across China, India, Germany, the United States, and Japan, while top-down reconciliation applied macroeconomic rail infrastructure investment flows to constrain segment-level estimates.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, technology pathway, application category, and end-user procurement archetype, with CAGR derivation anchored in rail fleet electrification schedules and refrigerant transition timeline enforcement. Industry-specific inputs incorporated dual carbon goal implementation pacing in China, PLI scheme rollout acceleration in India, and cross-border corridor electrification program commitments in Europe.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory enforcement for F-Gas Regulation and EPA SNAP phase-down timelines; material deviation in environmental protocol implementation would warrant model refresh. Practitioners should keep alternative scenarios live as refrigerant cost volatility and electromagnetic compatibility threshold evolution reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Point Machine Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
Train Transformer Market
Railway Transportation
Rail Gangways Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Urban Rail Transit Signaling Market