
 Japan Rail Freight Transport Market | 2026-2036
Japan Rail Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Rail Freight Transport Market Foresight
Modular container configurations is repositioning buyer choice across the Japan rail freight sector. JR Freight leverages dedicated bulk cargo terminals to sustain heavy-haul contracts with steel and chemical producers. Nippon Express anchors intermodal services bridging port terminals to inland logistics parks. Seino Transportation competes through integrated door-to-door offerings that combine rail trunk lines with final-mile trucking.
Japan rail freight transport encompasses the movement of goods via electrified and diesel-operated railway networks, typically employing 20-foot and 40-foot intermodal containers, tank wagons, and specialized flatcars rated for axle loads up to 17 tons on standard gauge and 1,067 mm narrow gauge lines. Its primary commercial purpose is to provide energy-efficient, high-volume cargo movement between major ports, industrial zones, and consumption centers where road congestion or distance economics favor rail over trucking. Container transport and intermodal services dominate revenue generation, reflecting structural preference for standardized, transferable loads that minimize handling costs across the supply chain. Bulk cargo retains stable demand from steelmakers and utilities, though refrigerated transport represents the fastest-growing technology segment as food safety standards tighten and pharmaceutical cold chains expand.
METI enforces modal shift targets that mandate freight volume diversion from highways to rail and coastal shipping, directly shaping infrastructure investment and operator fleet decisions. JIS standards govern container specifications and rolling stock interoperability, while the Ministry of Land, Infrastructure, Transport and Tourism regulates track access pricing and safety compliance across the national network. Stakeholders must monitor how amendments to the Railway Business Act and carbon accounting rules under Japan's GX League initiative reshape cost structures and competitive positioning for rail freight operators.
Market Dynamics
METI's modal shift mandates are restructuring Japan's freight economics, compelling shippers to abandon long-haul trucking for electrified rail corridors serving the Kanto industrial belt.
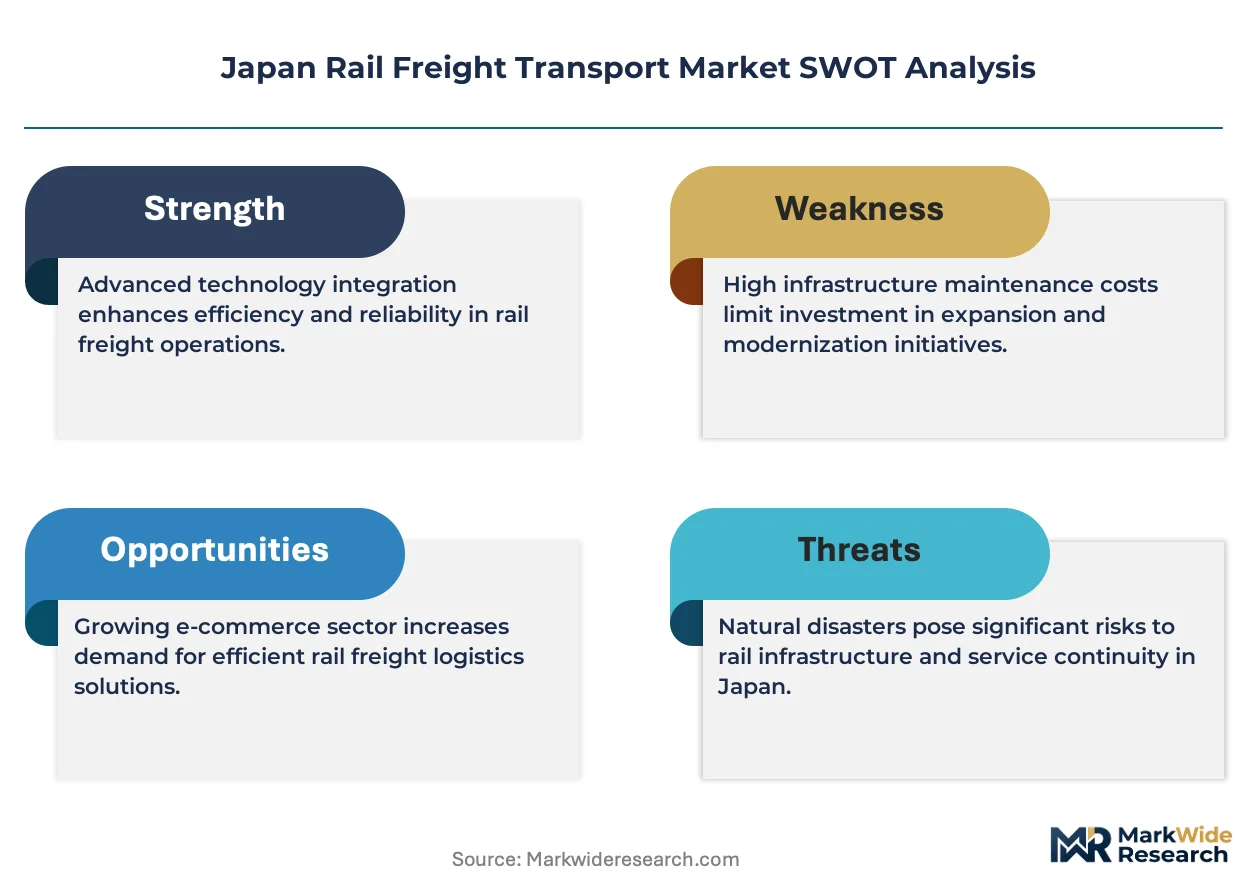
Growth Catalysts
- E-commerce fulfillment density:Online retailers are consolidating distribution into scheduled rail services connecting Tokyo Bay ports to Nagoya and Osaka logistics parks.
- GX League carbon accounting:Corporate emissions disclosure requirements under Japan's green transformation initiative are redirecting contract freight toward rail's lower carbon intensity.
- Pharmaceutical cold chain expansion:Temperature-controlled rail containers are capturing vaccine and biologics distribution from temperature-vulnerable road transport.
Market Restraints
- Track access pricing rigidity:Ministry of Land, Infrastructure, Transport and Tourism tariff structures prevent operators from matching truckload spot market flexibility.
- Last-mile trucking dependency:Final delivery from rail terminals remains captive to diesel truck fleets, eroding end-to-end cost advantages.
- Narrow gauge interoperability:The 1,067 mm track standard on secondary lines limits container dimensions and excludes certain chemical tank configurations.
Strategic Opportunities
- Kyushu semiconductor corridor:TSMC's Kumamoto fab cluster is generating specialized chemical and wafer transport demand underserved by current rail schedules.
- Hydrogen fuel cell locomotives:METI technology roadmaps are funding pilot programs to decarbonize non-electrified branch lines serving remote industrial sites.
- Port-rail synchronization:Automated gate systems at Yokohama and Kobe terminals are compressing container dwell times to under four hours.
Industry Challenges
- Locomotive engineer shortages:Japan's aging rail workforce faces recruitment gaps in diesel-electric hybrid operation certifications.
- Legacy signaling integration:Digital Automatic Train Control upgrades on freight-dedicated lines require extended service suspensions during installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Rail Freight Transport Market |
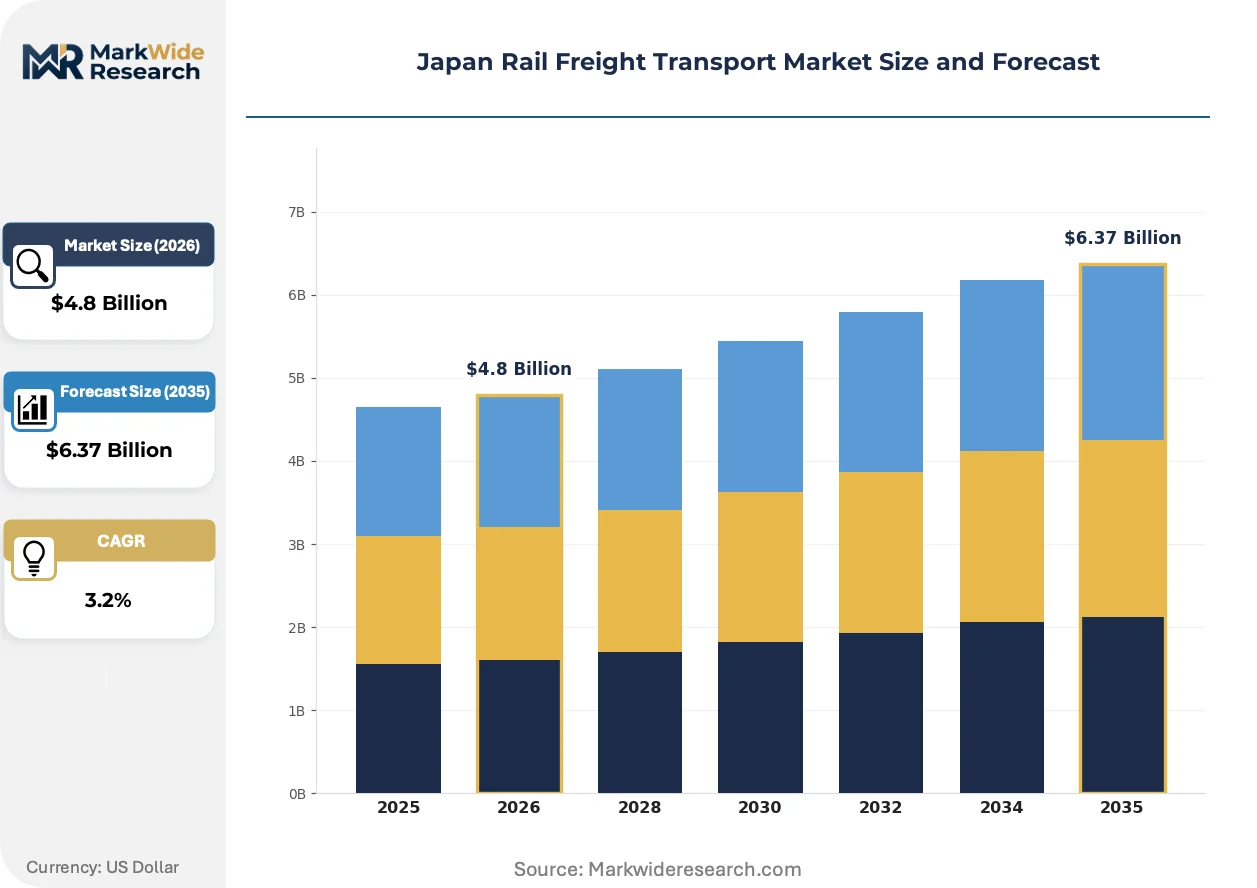
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Bulk Cargo, Container Transport, Intermodal, Finished Goods End User: Manufacturing, Agriculture, Retail, E-commerce Technology: Satellite Tracking, Automation, IoT Solutions, Refrigerated Transport Delivery Mode: Direct Transport, Terminal-to-Terminal, Door-to-Door, Scheduled Services |
| Companies Covered | Kamigumi Co., Ltd., Seino Transportation Co., Ltd., Japan Freight Railway Company (JR Freight), FESCO, Japan Freight Liner Co., Nippon Express Co., Ltd., AZ-COM Maruwa Holdings Co., Ltd., MAERSK, Yusen Logistics Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Rail Freight Transport Market Shifts & Advancements
Rail freight technology in Japan is converging around automation, emissions tracking, and intermodal fluidity. These developments are compressing transit times while expanding serviceable cargo categories.
Digital freight matching platforms are unifying shipper demand with JR Freight's scheduled capacity through real-time API connections. Chemical distributors and automotive parts suppliers are adopting these systems fastest, shifting from annual contracts to slot-based bookings. This technology is unifying previously fragmented spot markets into predictable, tradable capacity blocks.
METI's 2024 modal shift subsidy expansion tightens eligibility criteria to favor rail-sea intermodal chains over pure rail movements. Steel coil and construction material shippers now face documentation burdens proving carbon reduction thresholds. Bulk cargo terminals in Chiba and Kawasaki are responding by installing emissions verification sensors to qualify loads for preferential pricing.
Shippers are consolidating purchasing through third-party logistics providers who bundle rail, warehousing, and customs brokerage into single invoices. Food importers and electronics manufacturers are abandoning direct rail contracts for these integrated offerings. This consolidation is most visible in the Kansai region, where Nippon Express and Seino Transportation have captured refrigerated container volumes from independent forwarders.
Japan Rail Freight Transport Market Segmentation
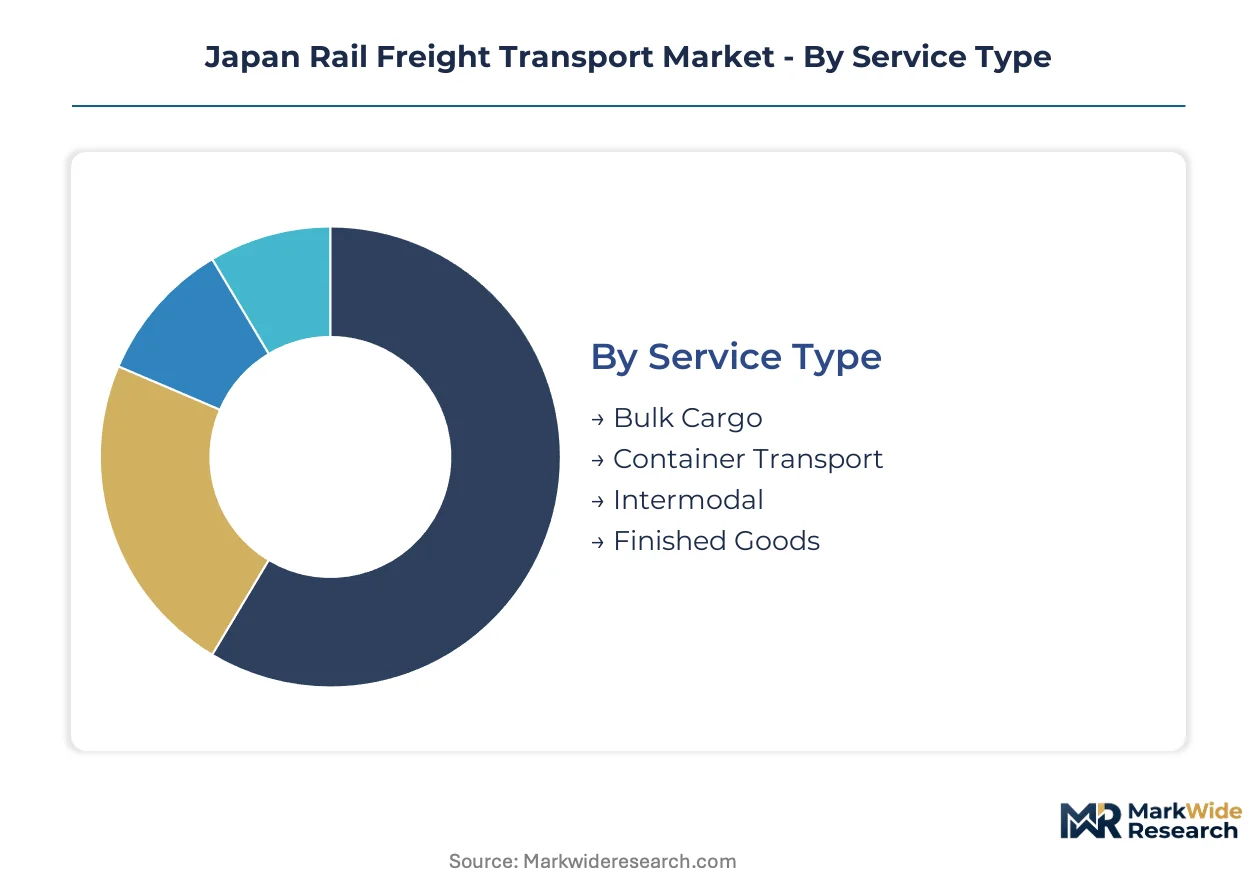
Segmentation in Japan's rail freight market reveals how modal shift policies reshape operator investment and shipper procurement. Service configurations and technology adoption vary sharply between bulk commodity corridors and high-velocity container networks serving e-commerce fulfillment.
Service Type:
Volume-heavy bulk cargo dominates tonnage moved, while premium container services command superior margins per load unit.
- Container Transport:Standardized 20-foot and 40-foot intermodal units move electronics, automotive parts, and consumer goods between Tokyo Bay ports and inland logistics parks. METI modal shift subsidies concentrate demand along electrified trunk lines connecting Kanto industrial zones to Nagoya and Osaka distribution hubs.
- Intermodal:Seamless rail-truck-barge combinations minimize handling through synchronized terminal operations. Nippon Express and Seino Transportation bundle these services for food importers and pharmaceutical distributors requiring temperature integrity across modal transfers.
- Bulk Cargo:Steel coils, chemicals, and construction materials move via dedicated flatcars and tank wagons from Chiba and Kawasaki terminals to manufacturing sites.
- Finished Goods:Assembled vehicles and machinery travel on specialized auto-rack wagons serving Toyota and Honda production networks.
Today's leader: Container Transport. Tomorrow's challenger: Intermodal.
End User:
Application intensity varies by supply chain complexity, with manufacturing procurement patterns differing fundamentally from retail replenishment cycles.
- E-commerce:Online retailers consolidate fulfillment into scheduled rail services to bypass highway congestion on Tokyo-Osaka corridors. GX League carbon disclosure requirements redirect contract freight toward rail's lower emissions profile compared with long-haul trucking.
- Manufacturing:Automotive and electronics producers rely on just-in-time rail deliveries from port terminals to inland assembly plants. TSMC's Kumamoto fab cluster is generating specialized chemical transport demand underserved by current network schedules.
- Retail:Department stores and supermarket chains use refrigerated container services for imported food products requiring cold chain integrity.
- Agriculture:Grain and fertilizer movements concentrate on secondary narrow-gauge lines serving Hokkaido and Tohoku production regions.
Manufacturing anchors current volume. E-commerce climbs the fastest as fulfillment density reshapes network planning.
Technology:
Margin capture separates commodity operators from technology-enabled service providers commanding premium pricing.
- Refrigerated Transport:Temperature-controlled containers with satellite-monitored cold chains capture vaccine and biologics distribution from road transport. Pharmaceutical safety standards tighten requirements for continuous temperature logging across the Kanto-Kansai corridor.
- IoT Solutions:Sensor networks provide real-time cargo condition monitoring and predictive maintenance alerts for rolling stock. Chemical distributors adopt these systems fastest for hazardous material compliance documentation.
- Satellite Tracking:GPS and GNSS positioning enables precise arrival forecasting and yard optimization at Yokohama and Kobe terminals.
- Automation:Automated gate systems and digital freight matching platforms compress container dwell times and unify shipper demand with scheduled capacity.
Refrigerated Transport commands premium positioning. IoT Solutions gain share fastest through compliance-driven adoption.
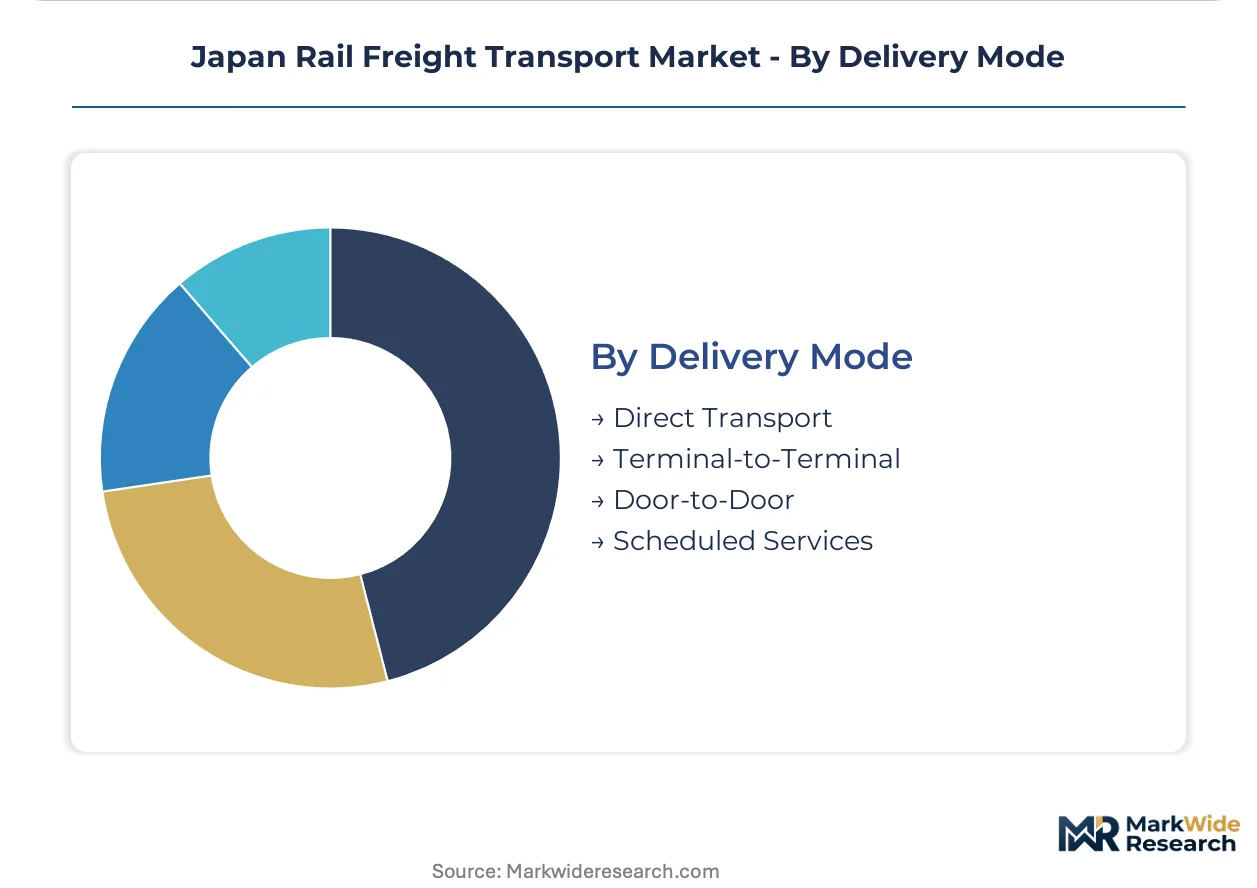
Delivery Mode:
Customer type determines configuration preference, with integrated logistics buyers favoring bundled solutions over point-to-point procurement.
- Door-to-Door:Third-party logistics providers bundle rail trunk lines with final-mile trucking into single-invoice offerings. Food importers and electronics manufacturers abandon direct rail contracts for these integrated services.
- Scheduled Services:Fixed-departure container trains offer predictable capacity for e-commerce fulfillment networks planning around guaranteed transit windows.
- Terminal-to-Terminal:Shippers with captive trucking fleets procure rail segments separately, concentrating at Chiba and Kawasaki bulk terminals.
- Direct Transport:Dedicated unit trains move single-commodity flows from specific origin-destination pairs without intermediate classification.
Door-to-Door leads revenue per shipment. Scheduled Services expand most quickly as density economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's rail freight network traces its modern origins to the post-war nationalization era, when the Japanese National Railways consolidated fragmented regional lines into a unified cargo system. The privatization of JNR in 1987 created JR Freight as the dedicated freight operator, establishing the current market architecture centered on electrified trunk corridors.
Kanto
Tokyo Bay ports generate the densest container flows, with Chiba and Kawasaki terminals handling steel coils and chemicals for inland manufacturing. METI modal shift subsidies concentrate investment along the Tohoku and Joetsu trunk lines connecting the capital region to Nagoya distribution hubs. The Keihin industrial belt anchors heavy-haul contracts with petrochemical refiners and automotive suppliers.
Kansai
Osaka and Kobe ports sustain intermodal services linking maritime cargo to Kyoto and Nara logistics parks. The Ministry of Land, Infrastructure, Transport and Tourism regulates track access pricing across the Kansai main line, where refrigerated container volumes expand for pharmaceutical and food importers. The Hanshin manufacturing corridor generates finished goods movements for electronics exporters.
Chubu
Nagoya's port complex serves as the primary interchange point between Kanto and Kansai freight corridors. The Tokaido main line electrification supports high-frequency container services for Toyota's just-in-time supply network. Yokkaichi chemical terminals dispatch tank wagons to the Chukyo industrial region under JIS hazardous materials protocols.
Kyushu
Kumamoto's emerging semiconductor cluster generates specialized chemical transport demand underserved by current rail schedules. The Kagoshima main line and Nagasaki main line retain narrow-gauge constraints that limit container dimensions for wafer and specialty gas movements. METI technology roadmaps are funding infrastructure studies to address this capacity gap.
Hokkaido
Agricultural bulk movements dominate tonnage, with grain and fertilizer flows concentrating on secondary lines serving the Ishikari Plain. The Muroran main line sustains steel product movements from Nippon Steel's integrated mill. Diesel-electric operations persist across non-electrified segments where freight density does not justify infrastructure upgrade.
Japan Rail Freight Transport Market Competitive Landscape
The competitive structure tilts toward integrated logistics conglomerates with captive rail access. Market concentration remains moderate, with JR Freight controlling trunk line infrastructure while third-party operators compete on value-added bundling. Three archetypes define the field: state-affiliated infrastructure owners, diversified freight forwarders with rail-truck integration, and specialized chemical and automotive logistics providers. Capacity expansion through terminal automation and strategic partnerships with port authorities represent the dominant competitive vectors.
Among diversified logistics operators, Nippon Express Co., Ltd. and Seino Transportation Co., Ltd. exemplify the integrated service model, while Japan Freight Railway Company (JR Freight) occupies the infrastructure-owner archetype. These three entities anchor the competitive landscape through their respective positions in intermodal bundling, door-to-door service integration, and trunk line capacity allocation. Their strategic postures reflect divergent responses to METI modal shift mandates and GX League carbon accounting requirements.
| Leading Market Players |
|---|
| Kamigumi Co., Ltd. |
| Seino Transportation Co., Ltd. |
| Japan Freight Railway Company (JR Freight) |
| FESCO |
| Japan Freight Liner Co. |
| Nippon Express Co., Ltd. |
| AZ-COM Maruwa Holdings Co., Ltd. |
| MAERSK |
| Yusen Logistics Co., Ltd. |
| Others |
Supply & Pricing Matrix
GX League carbon disclosure mandates are redirecting procurement contracts toward verified low-emission rail services, compelling operators to invest in emissions tracking infrastructure and recoup costs through premium pricing tiers for certified clean transport.
Pricing Analysis
Three-tier pricing structure across premium refrigerated, standard container, and economy bulk levels dominates Japan's rail freight market. Price differentiation hinges on temperature certification grade and volume commitment scale, with pharmaceutical shippers accepting substantial premiums for satellite-monitored cold chains. Cost compression in standard container services is intensifying because METI modal shift subsidies have tightened eligibility thresholds. E-commerce fulfillment networks exhibit lowest price sensitivity due to carbon compliance requirements, while agricultural bulk shippers remain most responsive to per-ton rates.
Supply Chain Analysis
Single-source vulnerability sits with China for specialized refrigerated container manufacturing and South Korea for precision sensor components. Japanese rail freight draws from domestic steel production for rolling stock and German signaling technology for network upgrades. Tariff exposure on Chinese container imports represents the dominant structural risk. Distribution runs through port-centric terminals at Tokyo Bay and Osaka Bay, with final-mile trucking captive to regional diesel fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's rail freight market represents a late-cycle quality story as pharmaceutical cold chain specifications tighten and GX League disclosure requirements elevate premium service tiers above commodity bulk movements.
For Market Incumbents: Deepen backward integration into refrigerated container manufacturing to capture margin from temperature-certified pharmaceutical contracts. METI's subsidy tightening threatens spot-market bulk operators lacking emissions verification infrastructure. Prioritize terminal automation investments at Yokohama and Kobe to compress dwell times below four-hour competitive thresholds. For New Entrants and Emerging Players: Capture specialized chemical transport demand from TSMC's Kumamoto semiconductor cluster, where current rail schedules remain underserved. The Kyushu corridor offers lowest competitive density among Japan's industrial regions. Lead with hydrogen fuel cell pilot program partnerships to differentiate from JR Freight's electrified trunk line dominance. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated logistics providers commanding door-to-door bundling capabilities across rail-truck intermodal chains. Five-to-ten year viability favors operators with captive port terminal access and pharmaceutical certification infrastructure. Watch METI technology roadmap funding allocations as the inflection signal for hydrogen locomotive deployment scale.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Container Fleet Expansion | Captures pharmaceutical cold chain demand as PMDA safety standards tighten temperature logging requirements. |
| Port-Rail Terminal Automation | Compresses container dwell times at Yokohama and Kobe to under four hours through automated gate systems. |
| Hydrogen Locomotive Pilot Deployment | Positions operators for METI decarbonization funding on non-electrified Kyushu and Hokkaido branch lines. |
| Third-Party Logistics Integration | Bundles rail trunk capacity with final-mile trucking for food importers abandoning direct rail contracts. |
| GX League Emissions Verification | Qualifies loads for preferential METI modal shift subsidies through sensor-documented carbon thresholds. |
Research Methodology
Coverage spans Kanto, Kansai, Chubu, Kyushu, and Hokkaido, with primary inputs from each region's logistics clusters. The analysis combines interviews with rail terminal operators, pharmaceutical distribution managers, chemical procurement leads, and third-party logistics executives with secondary validation from METI policy documents, Ministry of Land, Infrastructure, Transport and Tourism tariff filings, and JR Freight operational disclosures. Bottom-up container flow modeling and top-down modal shift target triangulation anchor volume estimates.
Granularity-level modeling disaggregates revenue across service type, end-user industry, technology tier, and delivery mode dimensions throughout the forecast period. CAGRs derive from segment-specific demand elasticity coefficients applied to METI freight diversion targets and GX League adoption curves. Semiconductor supply chain expansion in Kyushu and pharmaceutical cold chain regulatory tightening constitute key industry-specific forecast inputs.
Policy subsidy revisions, locomotive engineer shortage acceleration, and hydrogen infrastructure deployment delays are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding modal shift compliance trajectories and carbon accounting rule evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Railroad Tank Car Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Poland Rail Freight Transport Market
Railway Transportation
Railway Track Fittings Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Global Rail Freight Transport Market