
 Familial Hypercholesterolemia Treatment Market | 2026-2036
Familial Hypercholesterolemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Familial Hypercholesterolemia Treatment Market Analysis
The capital-intensity divergence between large-cap biologics manufacturers and targeted rare-disease specialists is redrawing competitive boundaries in familial hypercholesterolemia therapeutics. Amgen Inc. leverages its manufacturing scale to sustain supply chain dominance for injectable biologics across North American and European markets. Esperion Therapeutics, Inc. competes through oral small-molecule innovation, anchoring its position in patient segments seeking alternatives to injection-based regimens.
Familial hypercholesterolemia treatment encompasses pharmacological interventions targeting LDL receptor dysfunction, including statins that inhibit HMG-CoA reductase, PCSK9 inhibitors that enhance hepatic LDL receptor recycling, and bile acid sequestrants that interrupt enterohepatic cholesterol circulation, all aimed at reducing atherosclerotic cardiovascular risk in genetically predisposed patients. The PCSK9 inhibitor segment commands premium positioning due to superior LDL reduction in homozygous and severe heterozygous cases, while oral statins retain volume leadership across broader diagnosed populations. Injectable administration routes concentrate margin pools in specialty pharmacy and hospital outpatient settings, whereas oral formulations distribute value across retail and homecare channels with lower per-dose economics.
The FDA's orphan drug designation framework and the EMA's priority medicines scheme jointly shape development incentives and market exclusivity timelines for novel FH therapies. REACH compliance in Europe and EPA manufacturing standards in the United States impose purity and environmental controls on active pharmaceutical ingredient sourcing that filter market access for lower-cost entrants. Stakeholders must monitor evolving payer evidence requirements for cardiovascular outcomes data as regulators and health technology assessment bodies tighten reimbursement criteria beyond LDL reduction endpoints.
Market Dynamics
The FDA's accelerated approval pathways for orphan cardiovascular indications are compressing clinical trial timelines and redrawing competitive boundaries between injectable biologics and oral small-molecule developers.
Growth Catalysts
- EMA Priority Medicines Scheme:European developers gain expedited assessment timelines for novel LDL-lowering therapies, shortening market entry windows by 12-18 months for qualifying candidates.
- Germany's national screening programs:Systematic cascade screening protocols identify index cases and first-degree relatives earlier, expanding the addressable diagnosed population through specialized FH centers.
- Combination therapy protocols:Specialty lipid clinics in the United States are layering PCSK9 inhibitors atop maximally-tolerated statin regimens for severe heterozygous patients, driving protocol-driven demand for injectable adjuncts.
Market Restraints
- Injectable administration economics:Cold-chain distribution requirements and specialty pharmacy handling fees concentrate margin pools in hospital outpatient settings, limiting retail channel penetration for biologic therapies.
- REACH compliance costs:European active pharmaceutical ingredient sourcing faces escalating purity and environmental documentation burdens that filter lower-cost generic entrants from the supply base.
- Statin tolerance limitations:Myalgia and hepatotoxicity concerns in 5-10% of treated patients create adherence ceilings that oral small-molecule alternatives have not fully overcome.
Strategic Opportunities
- Underpenetrated homozygous FH segment:Ultra-rare homozygous populations in India and Brazil lack access to apheresis centers and gene therapy candidates, creating whitespace for novel mechanism developers.
- Oral PCSK9-targeting small molecules:Liver-targeted siRNA and oral cyclic peptide approaches converge with patient preference for non-injectable regimens, potentially capturing statin-intolerant and needle-averse segments.
- EPA manufacturing standards:United States environmental compliance creates sourcing barriers that vertically integrated API manufacturers can leverage for exclusive supply agreements with innovator drug sponsors.
Industry Challenges
- Cardiovascular outcomes data requirements:Payers and health technology assessment bodies in Germany and France now demand hard endpoint evidence beyond LDL reduction, extending post-approval study timelines and reimbursement negotiation cycles.
- Specialized genetic counseling workforce:Cascade screening expansion outpaces trained counselor availability in United States academic medical centers, creating diagnostic bottlenecks that delay treatment initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Familial Hypercholesterolemia Treatment Market |
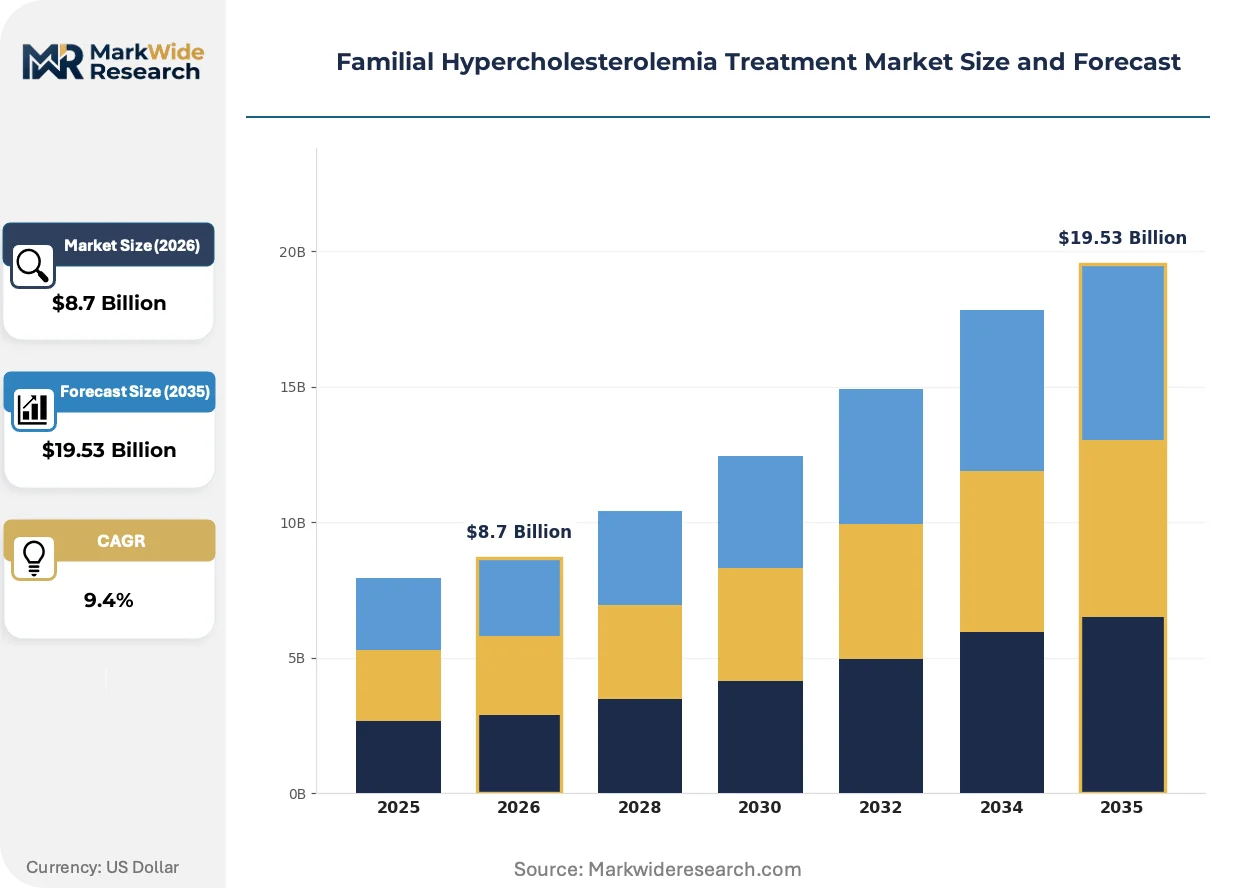
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Statins, PCSK9 Inhibitors, Cholesterol Absorption Inhibitors, Bile Acid Sequestrants Administration Route: Oral, Injectable, Transdermal, Intravenous End User: Hospitals, Clinics, Homecare Settings, Ambulatory Surgical Centers Treatment Stage: Acute Treatment, Long-Term Management, Preventive Care, Clinical Trials |
| Companies Covered | Amgen Inc., Sanofi S.A., Regeneron Pharmaceuticals, Inc., Novartis AG, Merck & Co., Inc., AstraZeneca plc, Pfizer Inc., Esperion Therapeutics, Inc., Ultragenyx Pharmaceutical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Familial Hypercholesterolemia Treatment Market Emerging Trajectories
Gene editing platforms and RNA interference mechanisms are displacing chronic administration models, while regulatory frameworks on both sides of the Atlantic accelerate orphan cardiovascular development timelines.
RNA interference therapies targeting hepatic PCSK9 synthesis are decomposing the chronic injection paradigm that has dominated severe familial hypercholesterolemia management. Infrequent dosing intervals—initially quarterly, now extending toward semi-annual administration—are attracting payers seeking to reduce specialty pharmacy administrative burdens. This technology is compressing the addressable market for monthly injectable monoclonal antibodies by capturing high-adherence-seeking segments in United States and German treatment centers.
REACH authorization requirements in Europe now mandate substance volume tracking and substitution hazard classifications for cholesterol-lowering API manufacturing. European chemical producers face reformulation costs or facility upgrades to maintain supply eligibility for EMA-registered drug products. Contract manufacturers in Switzerland and Ireland are responding by consolidating synthesis steps in-house to control documentation continuity across the value chain.
Patient-administered subcutaneous regimens are displacing clinic-based infusions as the preferred delivery mode for PCSK9-targeting therapies. United States specialty pharmacies now coordinate direct-to-home cold-chain distribution with telehealth follow-up, bypassing hospital outpatient infusion centers. This channel shift is most visible in employer-sponsored insurance populations seeking to reduce productivity loss from clinical visits.
Familial Hypercholesterolemia Treatment Market Segmentation
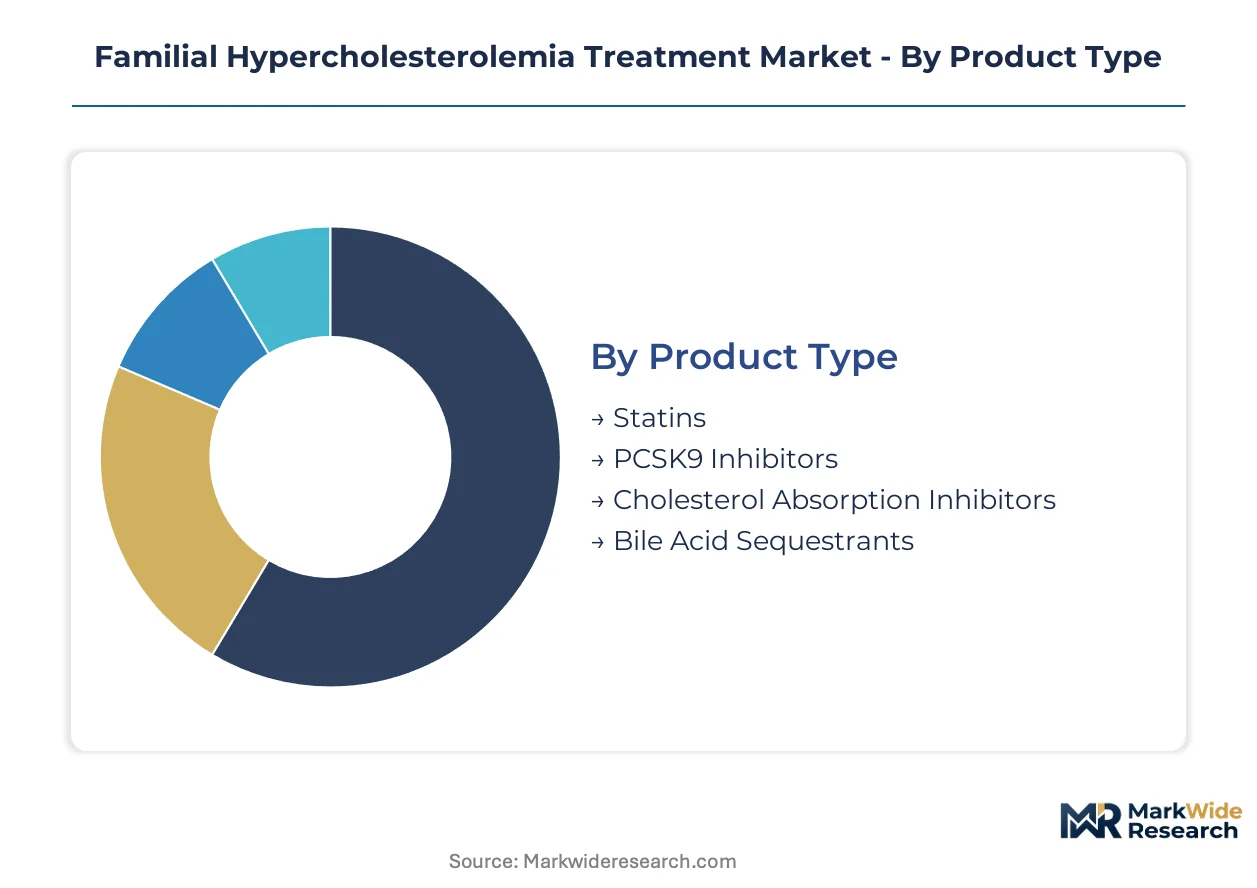
Segmentation in familial hypercholesterolemia therapeutics reveals how regulatory pathways, patient adherence profiles, and care delivery settings fragment commercial opportunity. Each dimension carries distinct margin structures and access barriers that shape portfolio prioritization for developers and distributors.
Product Type:
FDA orphan drug designation and EMA priority medicines status create divergent exclusivity timelines across mechanistic classes.
- Statins:First-generation HMG-CoA reductase inhibitors remain the foundational pharmacotherapy for heterozygous patients with functional LDL receptors. Volume concentrates in United States retail pharmacy channels where generic atorvastatin and rosuvastatin dominate maintenance protocols, though myalgia-driven discontinuation limits lifetime value per patient.
- PCSK9 Inhibitors:Monoclonal antibodies and siRNA constructs deliver superior LDL reduction in homozygous and statin-refractory cases through enhanced hepatic receptor recycling. Adoption clusters in German specialized FH centers and United States academic lipid clinics where prior authorization pathways favor documented genetic confirmation.
- Cholesterol Absorption Inhibitors:Ezetimibe-class compounds block intestinal NPC1L1 transporters as adjunctive therapy.
- Bile Acid Sequestrants:Resin-based enterohepatic interruption faces gastrointestinal tolerability constraints in long-term use.
Established volume favors statins; emerging adoption favors PCSK9 inhibitors.
Administration Route:
Patient preference and reimbursement mechanics split value capture between convenient oral delivery and high-efficacy injectable platforms.
- Oral:Small-molecule tablets and capsules dominate daily maintenance regimens across diagnosed populations, with retail pharmacy dispensing minimizing per-dose overhead. Statin-intolerant patients in United States employer-sponsored plans drive substitution demand toward non-statin oral alternatives.
- Injectable:Subcutaneous monoclonal antibodies and quarterly siRNA formulations command premium positioning in severe phenotypes. Cold-chain requirements and specialty pharmacy handling fees concentrate margin pools in hospital outpatient settings, limiting retail penetration.
- Transdermal:Patch-based delivery remains investigational for cholesterol-lowering APIs.
- Intravenous:Infusion protocols persist for acute lipid apheresis adjuncts in ultra-rare homozygous cases.
Oral routes sustain volume leadership; injectable platforms capture value concentration in severe disease segments.
End User:
Site-of-care economics and genetic counseling availability determine patient identification rates and treatment persistence.
- Hospitals:Academic medical centers with embedded lipid clinics manage complex homozygous cases requiring multidisciplinary coordination. German university hospitals anchor national screening networks with direct apheresis referral pathways.
- Clinics:Community-based specialty lipid practices in the United States drive protocol-driven combination therapy adoption for severe heterozygous patients.
- Homecare Settings:Telehealth-coordinated direct-to-home biologic delivery bypasses productivity loss from clinical visits.
- Ambulatory Surgical Centers:Limited FH-specific procedure volume restricts therapeutic relevance.
Hospital systems anchor complex case management; homecare channels expand access for maintenance populations.
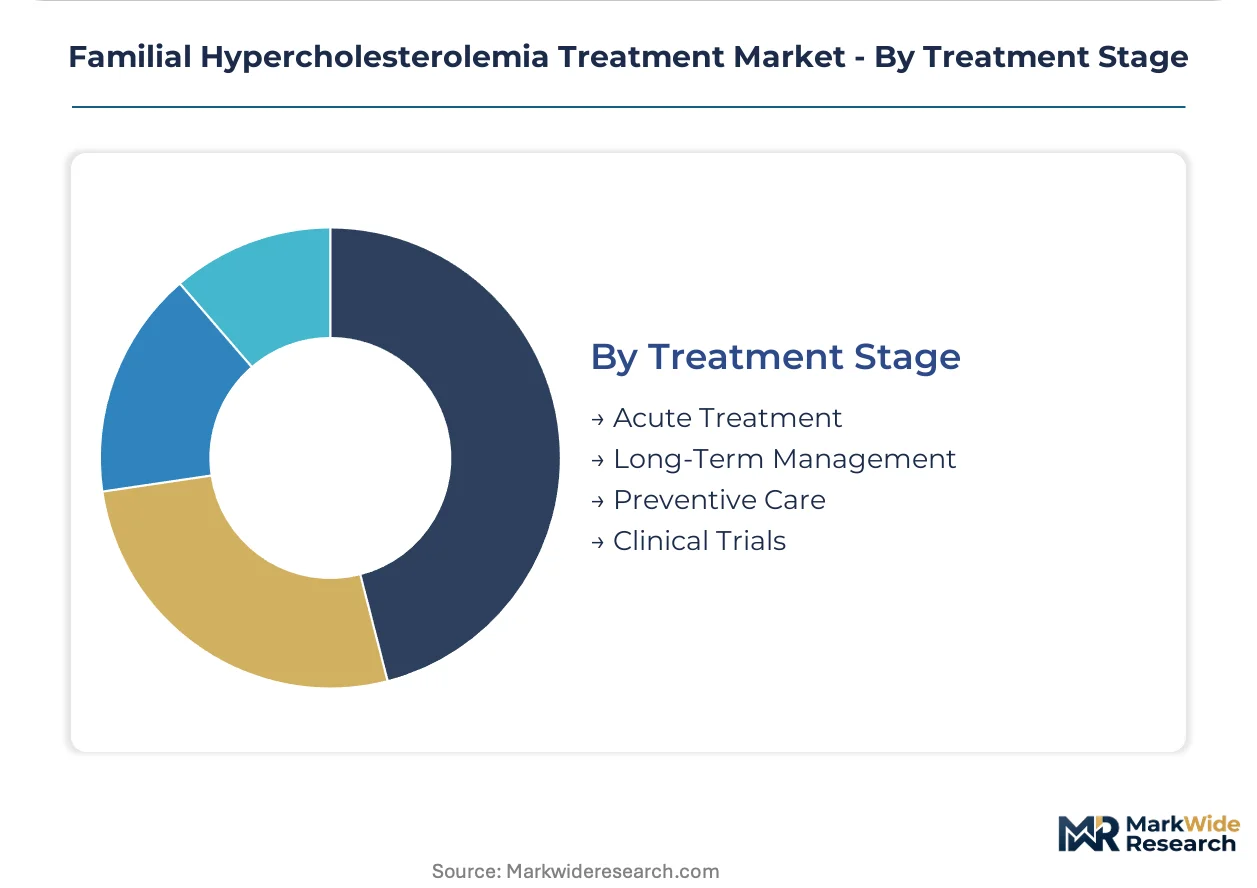
Treatment Stage:
Evidence requirements and reimbursement scrutiny intensify across the care continuum from acute intervention to preventive deployment.
- Acute Treatment:Emergency lipid apheresis and high-intensity combination protocols address cardiovascular event stabilization in extreme phenotypes.
- Long-Term Management:Chronic LDL reduction targets dominate commercial value, with United States and German payers demanding hard cardiovascular outcomes data beyond surrogate endpoints.
- Preventive Care:Cascade screening-identified relatives with subclinical elevation represent expansion opportunity.
- Clinical Trials:Gene therapy and base-editing candidates concentrate investigational activity.
Long-term management commands current revenue; preventive identification and clinical-stage innovation define expansion trajectories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across treatment markets. United States and German patients show limited price sensitivity due to comprehensive reimbursement frameworks, while Indian and Brazilian markets face acute access constraints that amplify cost responsiveness.
United States
Specialty lipid clinics in academic medical centers drive protocol-driven adoption of combination therapies for severe heterozygous cases. The FDA's accelerated approval pathways for orphan cardiovascular indications compress development timelines for novel mechanism candidates. Boston and New York Metro clusters anchor the highest concentration of genetic counseling capacity and apheresis referral networks.
Germany
National cascade screening programs identify index cases and first-degree relatives earlier than symptomatic presentation, expanding the diagnosed population base. The EMA priority medicines scheme grants expedited assessment timelines that shorten market entry windows for qualifying LDL-lowering therapies. University hospitals in Munich and Heidelberg coordinate specialized FH centers with direct apheresis pathways.
India
Ultra-rare homozygous populations lack access to apheresis centers and advanced biologic therapies, creating substantial underpenetration. The national pharmaceutical regulator maintains stringent import documentation requirements for cold-chain biologics that filter lower-cost distribution models. Mumbai and Delhi clinical clusters concentrate limited genetic counseling capacity amid expanding diagnostic demand.
Brazil
Public health system reimbursement constraints limit access to premium injectable therapies despite rising diagnosed prevalence. ANVISA's regulatory framework for rare disease therapies creates extended review timelines compared to reference markets. São Paulo's academic medical centers anchor the bulk of specialized lipid clinic capacity and clinical trial participation.
Switzerland
Contract manufacturers respond to REACH authorization requirements by consolidating synthesis steps in-house to control documentation continuity. Swissmedic's alignment with EMA standards enables rapid parallel market entry for qualifying therapies. Basel and Zurich clusters concentrate API manufacturing and specialized pharmacy distribution infrastructure.
Familial Hypercholesterolemia Treatment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in this market structure. Large-cap biologics manufacturers leverage manufacturing scale to sustain supply chain dominance across North American and European markets. Targeted rare-disease specialists compete through oral small-molecule innovation and patient segment focus. Dominant competitive moves include strategic partnerships for distribution access and portfolio diversification across administration routes.
Within the large-cap integrated tier, Amgen Inc. and Sanofi S.A. occupy positions anchored by manufacturing scale and established injectable platforms. Esperion Therapeutics, Inc. exemplifies the specialist archetype, competing through oral formulation innovation that addresses patient preference for non-injectable regimens. These three entities collectively represent the vertical span from volume-driven biologics supply to targeted small-molecule differentiation.
| Leading Market Players |
|---|
| Amgen Inc. |
| Sanofi S.A. |
| Regeneron Pharmaceuticals, Inc. |
| Novartis AG |
| Merck & Co., Inc. |
| AstraZeneca plc |
| Pfizer Inc. |
| Esperion Therapeutics, Inc. |
| Ultragenyx Pharmaceutical Inc. |
| Others |
Supply Flow & Price Mechanics
Manufacturing scale at Swiss and Irish API facilities anchors supply concentration and establishes price floors that smaller entrants cannot undercut without sacrificing REACH compliance documentation. Cold-chain biologics production concentrates margin pools with integrated manufacturers capable of absorbing EPA environmental validation costs, while oral small-molecule sourcing fragments across lower-tier contract producers.
Pricing Analysis
Specialty pharmacy handling fees and patient support programs drive lifetime value beyond per-dose acquisition costs in the injectable segment. Pricing stratifies across premium monoclonal antibodies, standard oral statin combinations, and economy-tier generic maintenance therapies, with differentiation resting on cardiovascular outcomes data depth and genetic confirmation requirements. Cost compression in the oral statin tier intensifies as Indian API producers expand volume capacity. Employer-sponsored insurance populations in the United States show lowest price sensitivity due to comprehensive prior authorization frameworks, while Brazilian public system procurement faces acute budget constraints.
Supply Chain Analysis
Just-in-time inventory models dominate oral formulation distribution through retail pharmacy networks, whereas strategic stockpiling of cold-chain biologics concentrates at United States specialty pharmacy hubs and German hospital outpatient centers. Active pharmaceutical ingredient synthesis draws from Switzerland, Ireland, and India, with cholesterol-lowering intermediate production resting on sterol derivative feedstocks and fermentation-based biocatalysts. Single-source vulnerability permeates siRNA construct manufacturing where proprietary lipid nanoparticle formulation expertise concentrates in Basel-area facilities. Distribution runs through temperature-controlled logistics partnerships that bridge manufacturer warehouses to patient home delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Familial hypercholesterolemia therapeutics constitute a defensive-moat market where EMA priority medicines status and FDA orphan drug exclusivity create regulatory entrenchment that protects incumbent positions against rapid generic substitution.
For Market Incumbents: Fortify manufacturing scale advantages through backward integration into lipid nanoparticle formulation capacity in Switzerland and Ireland. Expand genetic counseling partnerships with United States academic medical centers to secure cascade screening referral pathways before oral small-molecule competitors capture statin-intolerant segments. Prioritize cardiovascular outcomes trial investment to meet German and French payer evidence requirements.
For New Entrants and Emerging Players: Lead with oral PCSK9-targeting mechanisms to exploit patient preference for non-injectable regimens in employer-sponsored insurance populations. Target homozygous FH populations in India and Brazil where apheresis center scarcity creates acute access gaps. Deploy telehealth-coordinated direct-to-home distribution to bypass hospital outpatient channel concentration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors RNA interference platform holders with extended dosing interval advantages over monthly injectable antibodies. Five-to-ten year viability hinges on gene therapy pipeline optionality for ultra-rare homozygous populations. Watch for inflection when cardiovascular outcomes data from ongoing trials shifts German reimbursement criteria beyond LDL reduction endpoints.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Cardiovascular outcomes studies satisfy German G-BA evidence requirements for premium reimbursement tiers. |
| Regulatory Approval Pathway | FDA accelerated approval compresses commercialization timelines for orphan cardiovascular indications. |
| Manufacturing Scale-Up | Swiss contract manufacturers consolidate synthesis steps to maintain REACH authorization compliance. |
| Pipeline Diversification | Gene editing candidates address homozygous populations lacking apheresis access in emerging markets. |
| Strategic Partnership | Specialty pharmacy alliances enable cold-chain direct-to-home delivery bypassing hospital channels. |
Methodological Framework
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and payer access specialists provided ongoing calibration across primary data collection. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population sizing triangulated against top-down pharmaceutical revenue estimates to anchor segmentation integrity.
Consistency checks validated volume and value outputs against external benchmarks including formulary placement rates and specialty pharmacy dispensing records. The analytical framework modeled treatment line, administration route, patient population severity, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from patient flow analysis incorporating diagnosis rates, treatment persistence curves, and therapy switching probabilities.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement for combination therapy protocols or accelerated regulatory pathways would require recalibration. Forecasts reflect assumptions regarding cascade screening expansion and cardiovascular outcomes data generation timelines. Revision becomes warranted when payer evidence requirements cross thresholds that extend post-approval study obligations beyond current planning horizons.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Lyme Disease Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Peripheral Nerve Injuries Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Ringworm Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Giardiasis Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market