
 Global Radiodermatitis Treatment Market | 2026-2036
Global Radiodermatitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radiodermatitis Treatment Market Foresight
Silicone-based dressings is decoupling from petroleum-derived hydrogel economics as raw material volatility and biocompatibility premiums reshape formulation costs. Smith & Nephew leverages its wound care infrastructure to anchor radiodermatitis portfolios across European hospital networks. Mölnlycke Health Care dominates advanced dressing supply chains for Nordic oncology departments. Stratpharma AG specializes in film-forming spray technologies that differentiate its acute radiation burn protocols.
Radiodermatitis treatment encompasses topical, mechanical, and pharmacological interventions designed to prevent, mitigate, or heal ionizing radiation-induced cutaneous injury, with hydrogel dressings typically containing 90% water content to maintain moist wound environments and modulate inflammatory cytokine expression. The primary commercial purpose centers on preserving treatment continuity in radiotherapy regimens by reducing dose-limiting skin reactions. Hydrogel dressings command the largest revenue pool due to reimbursement anchoring in institutional procurement frameworks, while spray formulations represent the fastest-expanding delivery mode as ambulatory oncology shifts toward patient-administered protocols. Anti-inflammatory gels retain mature positioning in European markets where corticosteroid compounding traditions persist.
FDA radiation dermatology guidance, EMA advanced therapy medicinal product pathways, and Japan's PMDA skin barrier repair classification standards collectively determine market access timelines and clinical evidence requirements for novel formulations. REACH compliance for silicone monomers and EU MDR device-drug boundary classifications add layered compliance costs for cross-border suppliers. Stakeholders must monitor evolving reimbursement codes for home-based radiation skin care as tele-oncology protocols expand post-treatment monitoring responsibilities beyond clinic walls.
Market Dynamics
The transition from institutional procurement to patient-administered protocols is restructuring distribution economics and reimbursement anchoring across oncology care networks.
Growth Catalysts
- EMA Advanced Therapy Medicinal Product Pathways:Accelerated clinical evidence frameworks compress registration timelines for novel film-forming sprays in European hospital networks.
- Tele-oncology expansion:Remote post-treatment monitoring protocols in United States tertiary centers extend reimbursement coverage to home-based hydrogel applications.
- Silicone monomer biocompatibility premiums:REACH-compliant silicone chemistry enables premium positioning against petroleum-derived alternatives in Nordic procurement frameworks.
Market Restraints
- Petroleum-based hydrogel input volatility:Crude oil derivative pricing instability compresses margin predictability for standard moist wound dressing portfolios.
- EU MDR device-drug boundary friction:Classification ambiguity between medical devices and medicinal products extends compliance timelines for combination spray-hydrogel systems.
- Corticosteroid compounding substitution:Mature anti-inflammatory gel traditions in European ambulatory settings limit uptake of advanced silicone-based protocols.
Strategic Opportunities
- Japan PMDA skin barrier repair classification:Dedicated regulatory channel for radiation-induced injury creates differentiated market access for film-forming technologies.
- Home-based administration channel innovation:Direct-to-patient distribution models bypass institutional procurement bottlenecks in United States integrated cancer networks.
- Hydrogel-spray convergence:Hybrid delivery systems combining moist wound environment maintenance with patient self-application capture ambulatory oncology shifts.
Industry Challenges
- Clinical evidence generation timelines:Radiation dermatitis endpoint standardization delays across FDA and EMA frameworks prolong pivotal study completion.
- Wound care specialist integration:Cross-functional training requirements for oncology nursing staff constrain protocol adoption velocity in community cancer centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radiodermatitis Treatment Market |
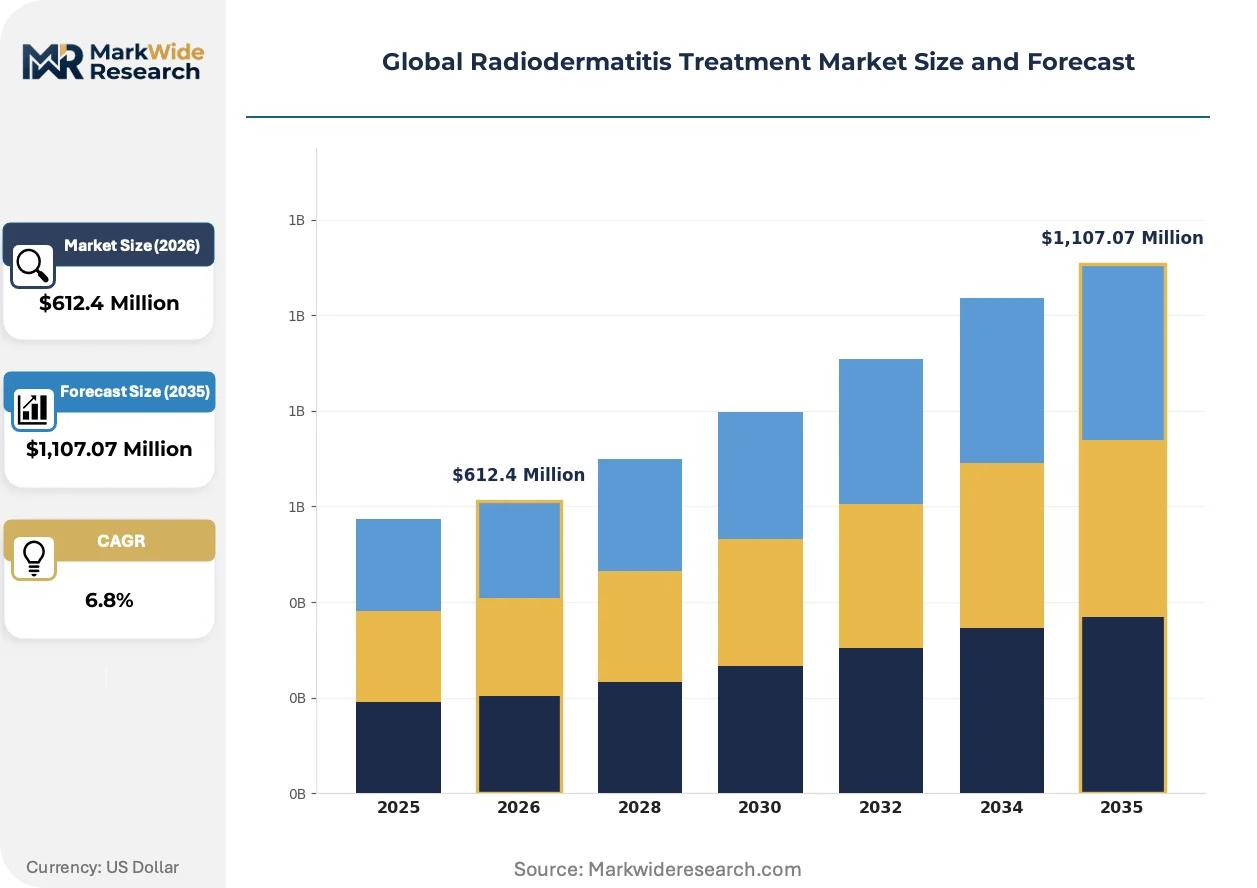
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
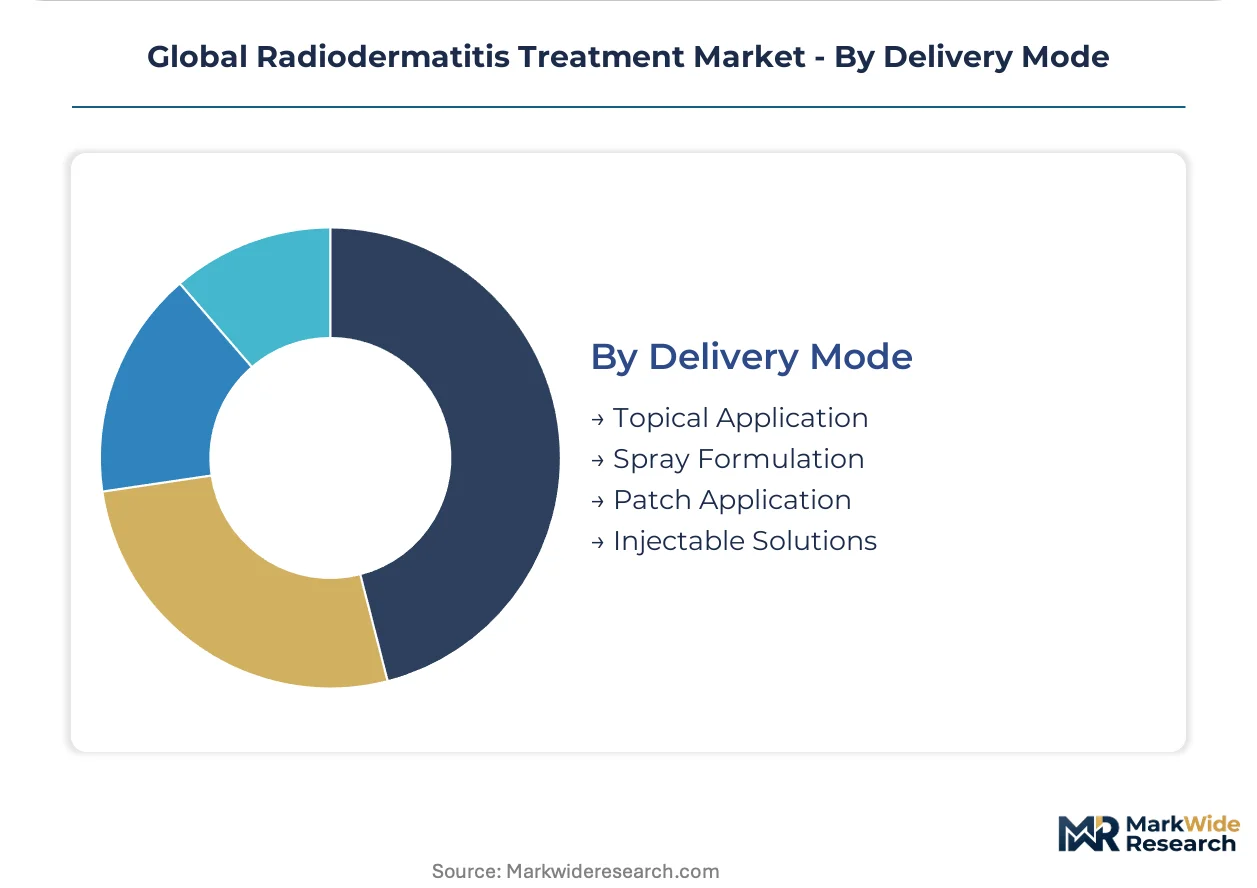
| Segmentation | Product Type: Topical Creams, Anti-inflammatory Gels, Moisturizing Lotions, Hydrogel Dressings, Herbal Ointments Therapy Area: Acute Radiodermatitis, Chronic Radiodermatitis, Radiation Burn Management, Skin Barrier Repair End User: Oncology Clinics, Dermatology Centers, Wound Care Facilities, Home Care Providers Delivery Mode: Topical Application, Spray Formulation, Patch Application, Injectable Solutions |
| Companies Covered | 3M, Smith & Nephew, ConvaTec, Mölnlycke Health Care, Stratpharma AG, Bausch Health Companies, LEO Pharma, Xequel Bio, Amryt Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radiodermatitis Treatment Market Shifts & Advancements
Film-forming spray technologies are compressing the traditional boundary between acute intervention and chronic wound management, forcing portfolio reconfiguration across dressing manufacturers.
Silicone-hydrogel hybrid chemistry is rewriting the cost-structure assumptions that have anchored institutional procurement decisions for two decades. United States tertiary cancer centers with integrated wound care programs are piloting these formulations for grade 2-3 radiation reactions. The technology is rewriting reimbursement negotiation dynamics by collapsing the distinction between preventive and therapeutic product categories.
REACH compliance mandates for silicone monomers are tightening raw material qualification requirements for cross-border suppliers into European Union markets. ECHA substance evaluation protocols now extend to residual catalysts in medical-grade silicone formulations. German hospital networks are responding by consolidating supplier qualification pools around vertically integrated polymer manufacturers with captive monomer supply.
Patient-administered protocol adoption is fragmenting historical purchasing concentration within hospital pharmacy departments. United States ambulatory oncology clinics are disintermediating traditional distributor relationships through direct manufacturer contracts for take-home dressing kits. This pattern is most visible in Medicare Advantage networks where bundled payment incentives align provider and patient convenience preferences.
Global Radiodermatitis Treatment Market Segmentation
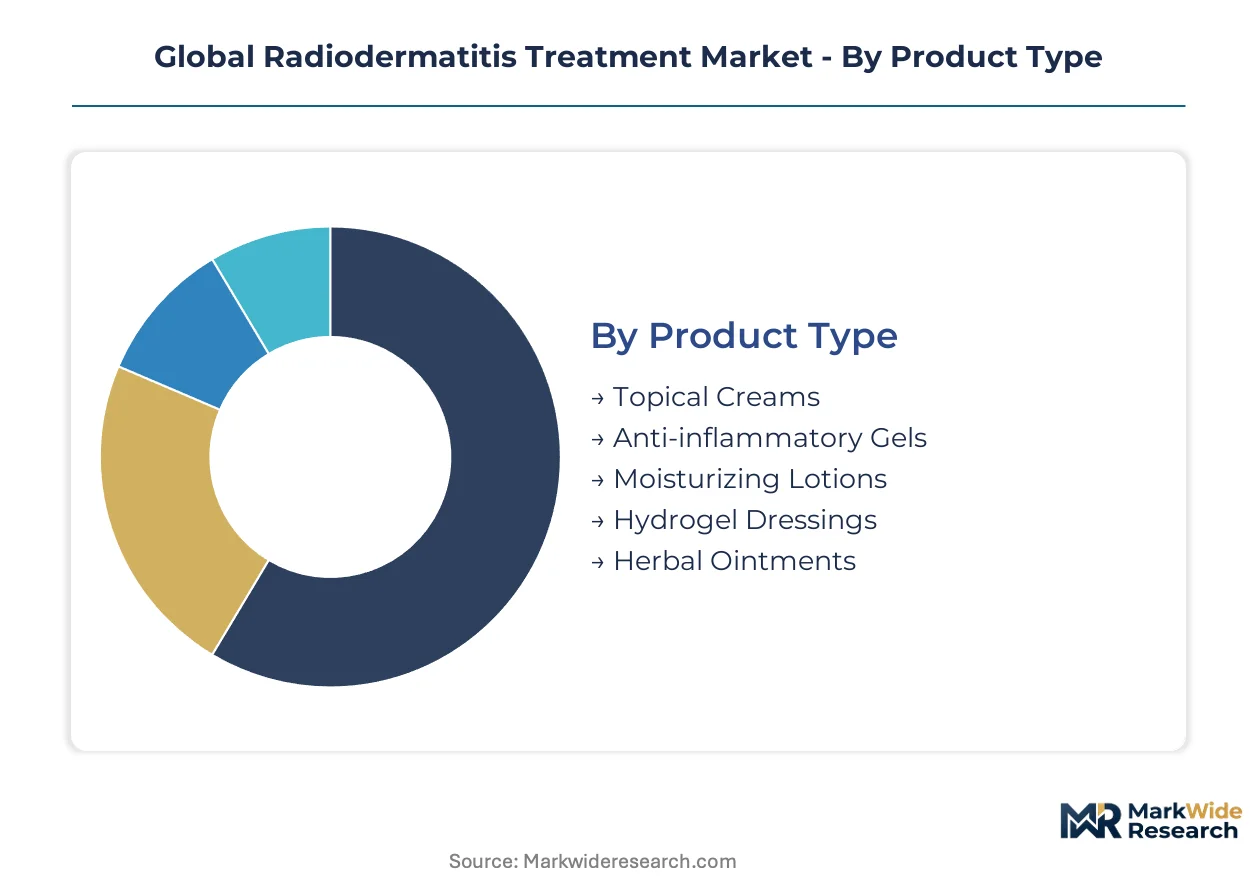
Product differentiation in radiodermatitis treatment follows distinct clinical workflows: institutional procurement favors advanced dressings with reimbursement codes, while ambulatory shifts reward patient-administered formats. Each segment category reflects a specific tension between clinical efficacy requirements and distribution economics.
Product Type:
The customization-vs-standardization spectrum spans petroleum-derived hydrogels at the commodity end to silicone-based formulations commanding biocompatibility premiums.
- Hydrogel Dressings:These polymer matrices maintain 90% water content to modulate inflammatory cytokine expression in moist wound environments. Oncology clinics across the United States and Germany anchor procurement volume through institutional reimbursement frameworks, though REACH compliance for silicone monomers is tightening supplier qualification requirements.
- Anti-inflammatory Gels:Corticosteroid-based formulations leverage compounding traditions in European ambulatory settings. Mature positioning in Germany and France limits uptake velocity of advanced alternatives, with EMA device-drug boundary classifications extending compliance timelines for novel entrants.
- Topical Creams:Standard emulsion-based vehicles dominate entry-level procurement tiers in community cancer centers with constrained wound care specialist staffing.
- Moisturizing Lotions:Barrier repair formulations align with Japan PMDA skin barrier repair classification standards, creating differentiated positioning for ceramide-containing protocols.
- Herbal Ointments:Plant-derived actives capture niche demand in South Korean and Australian markets where complementary medicine integration into oncology protocols persists.
Leading the category by volume: Hydrogel Dressings. Growing fastest: Anti-inflammatory Gels in European compounding networks.
Therapy Area:
Acute intervention formats command price premiums against chronic management protocols, with reimbursement anchoring favoring grade 2-3 reaction treatment over prevention.
- Acute Radiodermatitis:Film-forming spray technologies compress the boundary between immediate intervention and ongoing management. United States tertiary centers pilot these for grade 2-3 reactions, collapsing traditional preventive-therapeutic product distinctions in reimbursement negotiations.
- Chronic Radiodermatitis:Fibrotic skin changes from cumulative radiation exposure require extended protocol adherence. Japanese oncology departments integrate these into long-term survivorship programs under PMDA skin barrier repair frameworks.
- Radiation Burn Management:Severe cutaneous injury protocols concentrate in specialized wound care facilities with hyperbaric oxygen adjacency.
- Skin Barrier Repair:Post-treatment restoration protocols gain traction in Medicare Advantage networks where bundled payments align provider and patient convenience preferences.
Acute Radiodermatitis dominates current revenue concentration. Skin Barrier Repair climbs fastest as tele-oncology extends monitoring responsibilities beyond clinic walls.
End User:
Channel fragmentation is accelerating: institutional procurement retains volume concentration while direct-to-patient distribution models bypass traditional pharmacy intermediaries.
- Oncology Clinics:Integrated cancer networks in the United States consolidate purchasing through specialty distributors, with hydrogel dressing procurement anchored in GPO contracts. Staff training requirements for wound care protocol adoption constrain velocity in community settings.
- Home Care Providers:Take-home dressing kits disintermediate traditional distributor relationships through direct manufacturer contracts. This pattern concentrates in United States Medicare Advantage networks where patient convenience aligns with bundled payment incentives.
- Dermatology Centers:Specialized cutaneous oncology units in Germany and Switzerland manage complex radiation reactions with advanced dressing protocols.
- Wound Care Facilities:Hyperbaric oxygen-adjacent programs in Japan and the United States handle severe radiation-induced tissue injury requiring multidisciplinary intervention.
Oncology Clinics lead by procurement volume. Home Care Providers expand most quickly as ambulatory administration protocols proliferate.
Delivery Mode:
Patient self-application capabilities reshape formulation priorities, with spray and patch formats gaining share against traditional topical tubes in take-home prescribing.
- Spray Formulation:Film-forming technologies enable patient-administered protocols without nursing assistance. Stratpharma AG specializes in these acute radiation burn protocols, with EMA Advanced Therapy Medicinal Product pathways compressing registration timelines for European hospital network entry.
- Patch Application:Transdermal sustained-release formats align with chronic radiodermatitis management in Japanese long-term survivorship programs. METI standards for medical device classification create dedicated regulatory channels distinct from pharmaceutical pathways.
- Topical Application:Conventional tube and jar formats retain institutional procurement dominance through established reimbursement codes.
- Injectable Solutions:Intralesional corticosteroid delivery concentrates in severe fibrotic cases managed by specialized dermatology centers.
Topical Application retains volume leadership through reimbursement anchoring. Spray Formulation gains share fastest as patient-administered protocols displace clinic-dependent administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States tax-advantaged healthcare zones and Japan's special medical device districts concentrate radiodermatitis treatment manufacturing and clinical trial infrastructure. FDA radiation dermatology guidance and PMDA skin barrier repair classifications create divergent regulatory entry pathways. Oncology clinic procurement networks anchor demand across North American tertiary cancer centers and Japanese metropolitan hospital systems.
United States
Medicare Advantage bundled payment incentives accelerate home-based hydrogel adoption across integrated cancer networks. FDA evolving guidance on radiation-induced skin injury classification reshapes product registration timelines for novel film-forming sprays. Tertiary cancer centers in Boston and Houston pilot silicone-hydrogel hybrid protocols for grade 2-3 radiation reactions.
Germany
EMA Advanced Therapy Medicinal Product pathways compress clinical evidence frameworks for European hospital network entry. REACH compliance mandates for silicone monomers tighten raw material qualification requirements for cross-border suppliers. Bavarian hospital networks consolidate supplier pools around vertically integrated polymer manufacturers with captive monomer supply.
Japan
PMDA skin barrier repair classification standards create dedicated regulatory channels for radiation-induced injury treatments distinct from pharmaceutical pathways. METI medical device classification protocols enable patch-based sustained-release formats for long-term survivorship programs. Tokyo and Osaka oncology departments integrate chronic radiodermatitis protocols into extended patient monitoring frameworks.
United Kingdom
NHS England procurement frameworks for wound care specialties anchor hydrogel dressing volume through group purchasing organization contracts. MHRA post-Brexit device regulation alignment with EU MDR extends compliance timelines for combination spray-hydrogel systems. London and Manchester cancer centers drive adoption of patient-administered protocols through tele-oncology expansion.
Switzerland
Swissmedic streamlined assessment procedures for wound care devices accelerate market access for advanced dressing technologies. Federal procurement neutrality rules enable Nordic and German suppliers to compete for oncology clinic contracts on technical merit alone. Basel and Zurich hospital networks specialize in complex radiation burn management with hyperbaric oxygen adjacency.
Global Radiodermatitis Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional procurement favoring established wound care infrastructure players while ambulatory channels reward patient-administered format innovators. Market structure tilts toward consolidation among polymer science specialists with captive raw material supply, though spray formulation entrants fragment the premium tier. Three archetypes dominate: vertically integrated dressing manufacturers, film-forming technology specialists, and compounding pharmacy networks. M&A activity concentrates on hydrogel-spray convergence capabilities, while strategic partnerships target direct-to-patient distribution channel buildout.
Among diversified wound care conglomerates, Smith & Nephew and Mölnlycke Health Care occupy positions anchored by European hospital network infrastructure and Nordic oncology department supply relationships. Stratpharma AG exemplifies the film-forming spray specialization archetype, with its technology portfolio aligned to patient-administered protocol trends. These three entities represent distinct competitive vectors: institutional procurement anchoring, regional supply chain dominance, and delivery mode innovation.
| Leading Market Players |
|---|
| 3M |
| Smith & Nephew |
| ConvaTec |
| Mölnlycke Health Care |
| Stratpharma AG |
| Bausch Health Companies |
| LEO Pharma |
| Xequel Bio |
| Amryt Pharma |
| Others |
Supply & Pricing Matrix
Crude oil derivative benchmarks cascade through petroleum-based hydrogel economics, compressing margin predictability for standard moist wound dressing portfolios while REACH-compliant silicone monomers command biocompatibility premiums across Nordic and German procurement frameworks.
Pricing Analysis
Short lead-time premiums anchor pricing for emergency-grade hydrogel stock replenishment in United States tertiary cancer centers, while spot inventory discounts concentrate in European group purchasing organization contracts. Three-tier pricing structure across premium silicone-hydrogel hybrids, standard petroleum-derived hydrogels, and economy topical creams reflects certification grade and volume scale differentiation. Pricing pressure stems from corticosteroid compounding substitution in European ambulatory settings. Community cancer centers exhibit highest price sensitivity due to constrained wound care specialist staffing and institutional reimbursement limitations.
Supply Chain Analysis
REACH certification and FDA device establishment registration gates supplier qualification for cross-border hydrogel and spray formulation distribution. Manufacturing concentrates in Germany, the United States, and Japan, with silicone monomer supply anchored in vertically integrated polymer producers. Raw material dependencies rest on petroleum derivatives, medical-grade silicone precursors, and film-forming polymer resins. Single-source vulnerability concentrates in REACH-compliant silicone monomer streams. Distribution runs through specialty medical distributors serving oncology clinic networks and direct-to-patient channels in Medicare Advantage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Raw material volatility and regulatory compliance cost escalation are forcing portfolio consolidation among mid-tier suppliers without captive polymer supply or EMA/FDA dual-track registration capabilities.
For Market Incumbents: Acquire film-forming spray technology portfolios to capture patient-administered protocol shifts displacing clinic-dependent hydrogel applications. Backward integration into medical-grade silicone monomer production defends margin position against petroleum derivative volatility. Invest in dual-track FDA-EMA registration infrastructure to compress clinical evidence generation timelines for combination spray-hydrogel systems. For New Entrants and Emerging Players: Launch via direct-to-patient distribution models in United States Medicare Advantage networks where bundled payment incentives align provider and patient convenience preferences. Target home care provider channels with take-home dressing kits that bypass institutional procurement bottlenecks. White-space concentration sits in Japan PMDA skin barrier repair classification pathways for ceramide-containing moisturizing protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated polymer specialists with captive silicone monomer supply in Germany and Nordic markets. Long-term viability hinges on regulatory pathway diversification across FDA, EMA, and PMDA frameworks. Monitor EMA Advanced Therapy Medicinal Product pathway acceleration as inflection signal for film-forming spray valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Advanced Therapy Medicinal Product Registration | Compresses European hospital network entry timelines for novel film-forming spray entrants. |
| Silicone-Hydrogel Hybrid Formulation Development | Collapses preventive-therapeutic product distinctions in United States reimbursement negotiations. |
| Direct-to-Patient Distribution Channel Buildout | Disintermediates traditional pharmacy intermediaries in Medicare Advantage network contracts. |
| REACH-Compliant Monomer Supply Integration | Qualifies suppliers for German and Nordic oncology department procurement frameworks. |
| Tele-Oncology Protocol Integration | Extends reimbursement coverage to home-based hydrogel applications in United States tertiary centers. |
Research Methodology
Independent corroboration across oncology nursing directors, hospital GPO contract managers, wound care specialists, and regulatory affairs leads at dressing manufacturers underwrites the qualitative findings. Secondary validation draws from FDA radiation dermatology guidance documents, EMA Advanced Therapy Medicinal Product pathway filings, PMDA skin barrier repair classification standards, and hospital procurement database extracts. Bottom-up demand modeling triangulates against top-down market sizing across therapy area and delivery mode segments.
Comparable-period anchoring references historical hydrogel dressing adoption curves in United States tertiary cancer centers against spray formulation penetration rates in European hospital networks. The analytical framework segments by product type, therapy area, end user, and delivery mode across the projection horizon. CAGRs derive from patient-administered protocol adoption velocity, reimbursement code expansion for home-based care, and raw material cost trajectory assumptions.
Regulatory pathway delays, petroleum derivative price volatility, and tele-oncology reimbursement policy shifts are the dominant revision risks. A model refresh is warranted upon material change in FDA radiation-induced skin injury classification guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Myasthenia Gravis Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Microwave Ablation Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Global Fabry Disease Treatment Market
Medical Treatment
Giardiasis Treatment Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Brain Tumor Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Global Leukapheresis Market
Medical Treatment
Histoplasmosis Treatment Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Laser Therapy Market