
 Burns Treatment Market | 2026-2036
Burns Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Burns Treatment Market Outlook
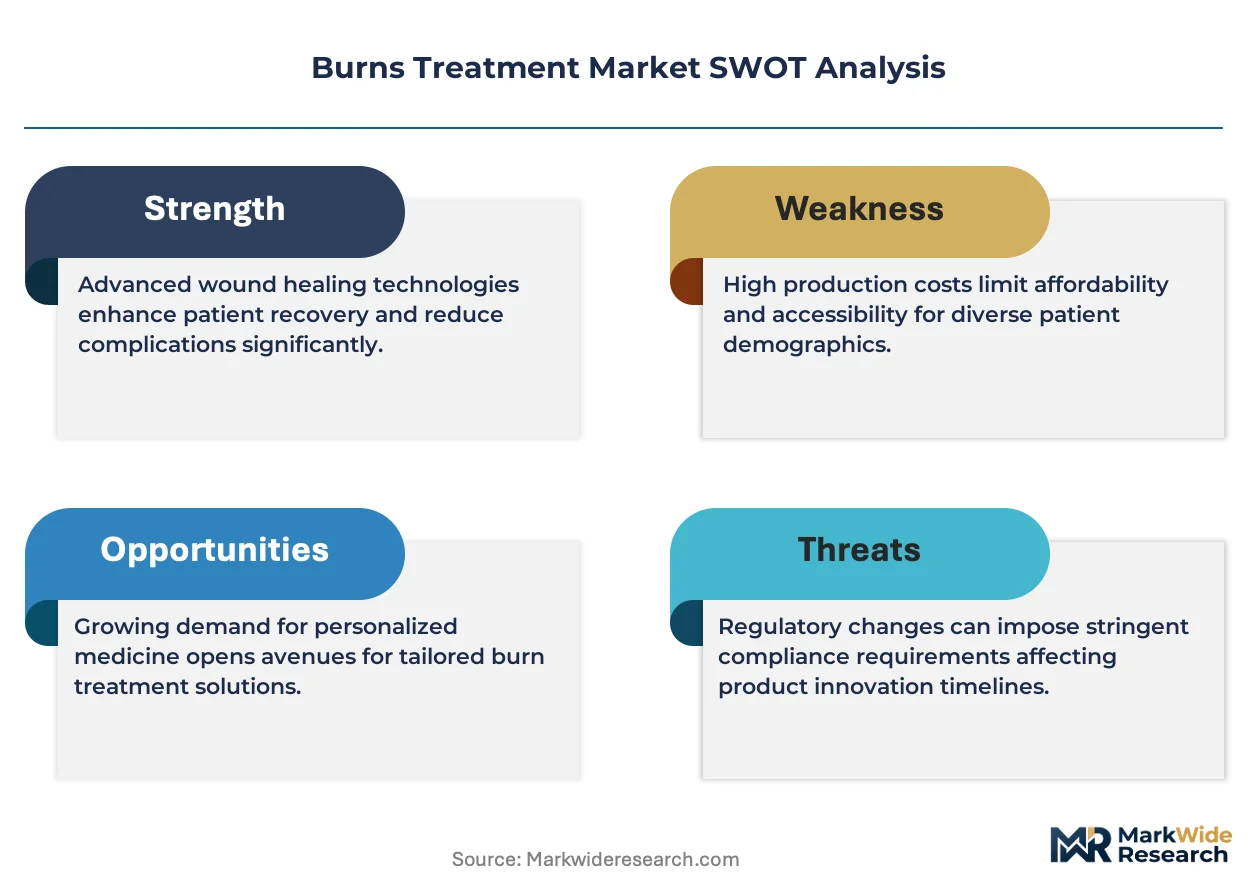
REACH compliance in Europe is broadening the cost-of-entry calculus for antimicrobial burn dressings containing silver sulfadiazine and other active compounds. Smith & Nephew leverages its vertically integrated biologics platform to sustain leadership in advanced wound matrices for partial-thickness injuries. Mölnlycke Health Care AB anchors Nordic supply chains through specialized hydrofiber manufacturing while B. Braun competes across Central European hospital procurement networks with comprehensive surgical and post-burn care portfolios.
Burns treatment encompasses the clinical management of thermal, chemical, electrical, and radiation-induced tissue injury through debridement, infection control, fluid resuscitation, and wound closure using autografts, allografts, or engineered skin substitutes. Silver-impregnated dressings and hydrogel formulations maintain moist wound environments while releasing antimicrobial ions at concentrations typically ranging from 0.5% to 1.0% active agent. Dressings and skin grafts command the deepest margin pools as hospitals shift toward single-application biologic products that reduce operating room time, while topical solutions face commoditization pressure from generic antiseptic alternatives. Emergency care centers represent the fastest-growing end user channel as regional trauma networks centralize initial burn stabilization before inter-facility transfer.
FDA 510(k) pathways and EMA Medical Device Regulation (MDR) classification rules determine market access timelines and clinical evidence requirements for novel burn therapeutics, with biologics facing additional CBER or CAT scrutiny depending on origin. The EU F-Gas Regulation and OSHA workplace safety standards indirectly shape demand through industrial prevention mandates and subsequent treatment volume. Stakeholders must monitor evolving reimbursement thresholds for autologous cell therapies and artificial skin products as health technology assessment bodies recalibrate cost-effectiveness benchmarks for severe burn interventions.
Market Dynamics
Hospital procurement networks are consolidating burn care purchasing around single-vendor biologics contracts that bundle advanced wound matrices with post-operative monitoring services, compressing supplier margins while locking in multi-year volume commitments.
Growth Catalysts
- CMS Reimbursement Realignment:United States Medicare payment schedules now weight biologic skin substitutes at 40-60% higher RVUs than split-thickness autografts, redirecting hospital capital toward engineered tissue platforms.
- REACH Antimicrobial Registration:European manufacturers completing ECHA dossiers for silver sulfadiazine dressings secure preferential tender access across German, French, and Nordic hospital systems.
- Trauma Network Centralization:Regional emergency medical systems in Texas, California, and Florida designate Level I burn receiving centers, funneling severe case volume into equipped facilities with dedicated biologics contracts.
Market Restraints
- Donor Tissue Supply Volatility:Allograft availability fluctuates with cadaveric donation rates, creating 15-25% quarterly volume swings that disrupt surgical scheduling at mid-sized burn centers.
- FDA 510(k) Evidence Burden:Novel hydrogel-antimicrobial combinations require predicate device matching and biocompatibility testing that extends pre-market timelines by 18-24 months versus traditional dressings.
- Autograft Substitution Persistence:Cost-conscious payers in Medicaid programs and emerging markets continue favoring split-thickness harvesting over engineered substitutes for partial-thickness injuries under 20% TBSA.
Strategic Opportunities
- Outpatient Burn Clinic Expansion:Ambulatory surgical centers in Arizona, Nevada, and Georgia are adding dedicated burn bays for minor thermal injuries, creating channel demand for single-application biologic dressings.
- EU MDR Quality Certification:Manufacturers achieving notified body approval under the 2017/745 Medical Device Regulation can command 20-35% price premiums in French and Belgian hospital tenders versus non-certified competitors.
- Cell Therapy Convergence:Autologous keratinocyte harvesting combined with 3D bioprinting scaffolds enables patient-specific graft production at regional tissue engineering facilities, reducing allograft dependency.
Industry Challenges
- Burn Surgeon Training Pipeline:Fellowship programs produce fewer than 60 certified burn surgeons annually in the United States, constraining expansion of dedicated center capacity regardless of capital availability.
- Cold Chain Integrity for Biologics:Engineered skin substitutes require controlled-rate freezing and liquid nitrogen storage that many community hospitals lack, limiting addressable market penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Burns Treatment Market |
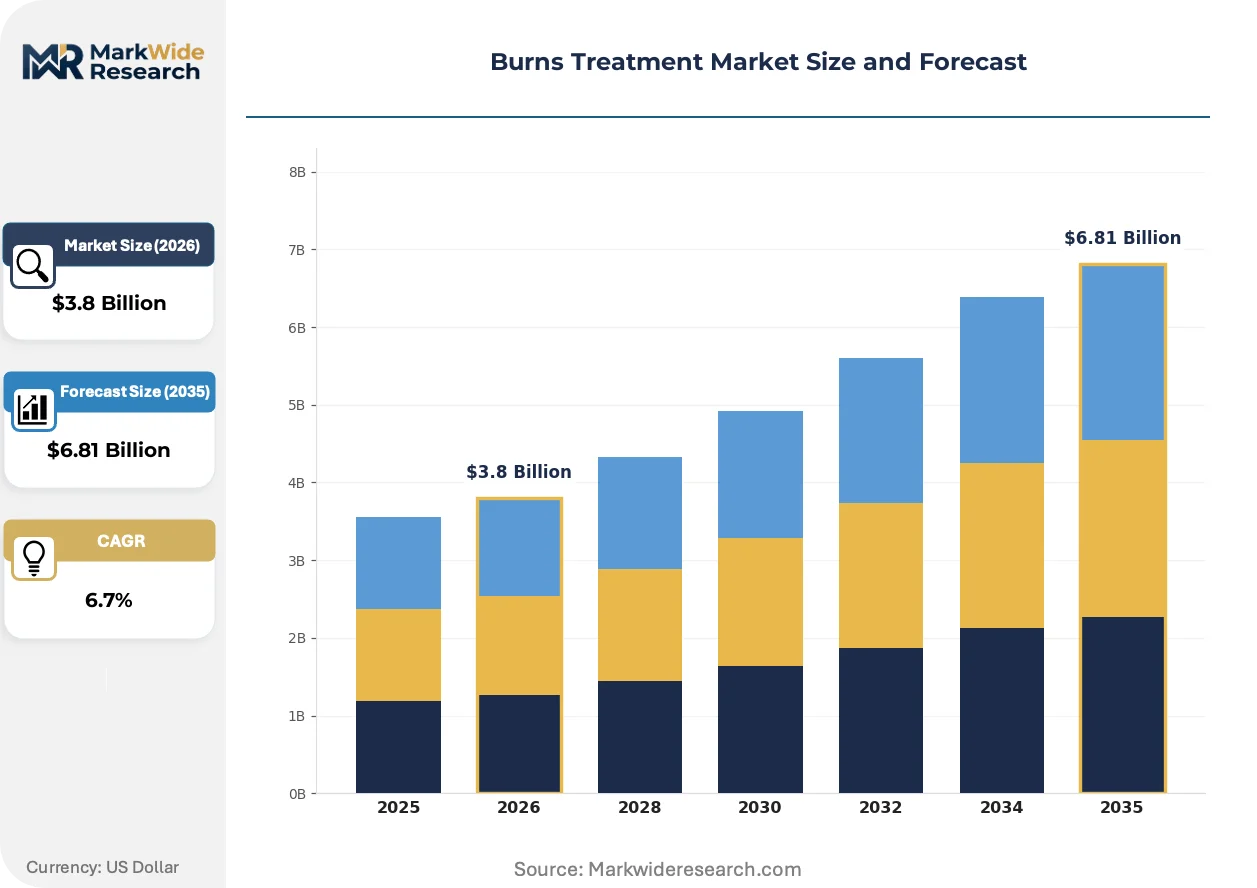
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Solutions, Skin Grafts, Dressings, Antimicrobial Agents Application: First-degree Burns, Second-degree Burns, Third-degree Burns, Thermal Burns End User: Hospitals, Clinics, Emergency Care Centers, Home Care Settings Delivery Mode: Injectable, Topical, Oral, Others |
| Companies Covered | Smith & Nephew, Mölnlycke Health Care AB, Johnson & Johnson, 3M, ConvaTec Group, Integra LifeSciences, Cardinal Health, B. Braun, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Burns Treatment Market Strategic Shifts
Biologic manufacturing platforms are compressing production cycles for patient-matched tissue while regulatory frameworks on both sides of the Atlantic recalibrate safety thresholds for novel antimicrobial delivery systems.
3D bioprinted dermal scaffolds seeded with autologous fibroblasts are overtaking cadaveric allografts as the preferred temporary wound coverage for deep partial-thickness burns. Major academic medical centers in Massachusetts, Pennsylvania, and Ohio have adopted these platforms within 18 months of FDA clearance. The technology is overtaking traditional procurement patterns by enabling on-demand graft fabrication that eliminates tissue bank intermediaries and their associated cold chain costs.
EMA Medical Device Regulation Annex XVI expansion now captures certain antimicrobial wound dressings previously regulated as medicinal products, forcing manufacturers to resubmit technical documentation under notified body review. German and Dutch hospital procurement associations have responded by demanding MDR certificates in all new tenders, effectively delisting non-compliant suppliers from 2024 contract cycles. The shift most impacts silver-impregnated hydrofiber manufacturers with legacy CE marks issued under the Active Implantable Medical Devices Directive.
Integrated service contracts that bundle biologic products with wound assessment telemedicine are displacing traditional product-only purchasing across United States integrated delivery networks. Burn centers in North Carolina, Tennessee, and Virginia now specify remote monitoring protocols in their RFPs, favoring vendors with established digital health infrastructure. The model concentrates purchasing power within systems that can demonstrate reduced readmission rates through continuous post-discharge surveillance.
Burns Treatment Market Segmentation
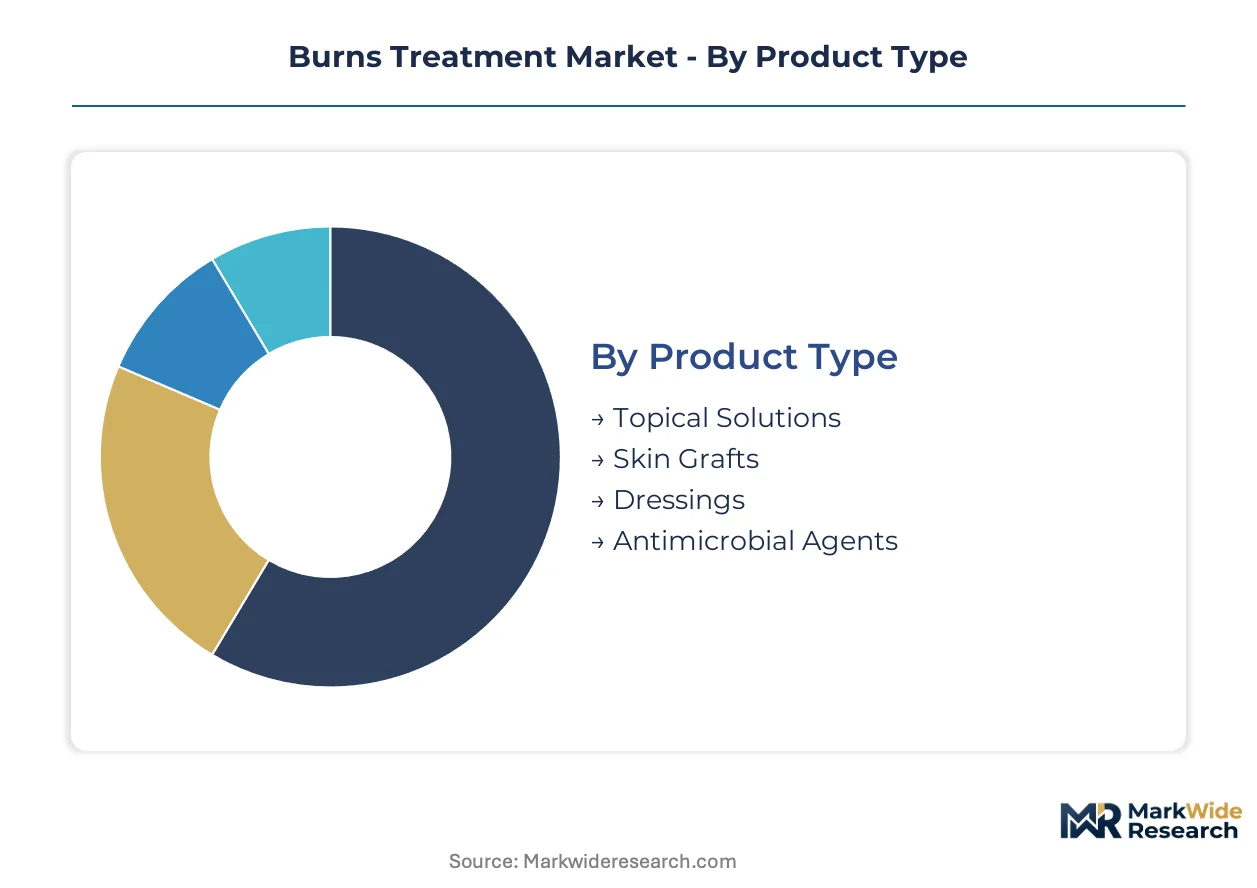
Segmentation in burns treatment reveals how procurement power concentrates around biologics-intensive channels while reimbursement policies reshape product mix across wound closure modalities. Understanding these divisions exposes where margin pools deepen versus where commoditization pressure intensifies.
Product Type:
Supply concentration in biologic manufacturing favors integrated platforms that control collagen sourcing through cryopreservation networks.
- Skin Grafts:Engineered dermal substitutes and allografts incorporate human keratinocytes or bovine collagen matrices with 0.3-0.5mm thickness specifications for partial-thickness coverage. Demand clusters in United States Level I burn centers where CMS reimbursement premiums justify acquisition costs for injuries exceeding 15% TBSA.
- Dressings:Hydrofiber and alginate formulations maintain moist wound environments while silver-impregnated variants release antimicrobial ions at controlled concentrations. German and French hospital tenders now require ECHA-compliant silver sulfadiazine documentation, filtering out non-REACH-registered suppliers.
- Topical Solutions:Antiseptic creams and hydrogels deliver active agents across superficial burns without surgical intervention.
- Antimicrobial Agents:Silver-based and iodine-based compounds prevent colonization in contaminated wound beds.
Today's leader: Skin Grafts. Tomorrow's challenger: Dressings with integrated biologic coatings.
Application:
Cost tier stratification separates emergency stabilization products from long-term reconstruction therapies in surgical burn care.
- Third-degree Burns:Full-thickness injuries penetrating dermis and subcutaneous tissue require staged debridement followed by permanent wound closure using autografts or cultured epithelial autografts. Texas and California trauma networks centralize these cases in designated receiving centers with dedicated biologics contracts.
- Second-degree Burns:Deep partial-thickness injuries involving dermal destruction drive demand for temporary coverage using xenografts or synthetic matrices before definitive grafting. Ambulatory surgical centers in Arizona and Nevada are expanding capacity for these intermediate cases.
- First-degree Burns:Superficial epidermal injuries resolve with topical emollients and protective dressings without surgical intervention.
- Thermal Burns:Flame and scald injuries constitute the predominant etiology across all age demographics.
Third-degree applications command premium pricing. Second-degree protocols are climbing the fastest as outpatient capacity expands.
End User:
Volume concentration in hospital procurement networks is displacing fragmented clinic purchasing through integrated delivery network consolidation.
- Hospitals:Dedicated burn centers and trauma units perform complex grafting procedures with operating room time exceeding 4-6 hours for extensive injuries. North Carolina, Tennessee, and Virginia IDNs now bundle biologic products with remote monitoring services in multi-year agreements.
- Emergency Care Centers:Regional trauma hubs stabilize patients before inter-facility transfer to definitive care facilities. Florida's centralized emergency medical services designation of burn receiving centers is funneling initial case volume into equipped facilities.
- Clinics:Outpatient settings manage minor thermal injuries and post-graft follow-up care.
- Home Care Settings:Discharge protocols for stable wounds extend treatment into residential environments with caregiver training.
Hospitals retain procurement dominance. Emergency Care Centers are gaining share fastest as regional networks mature.
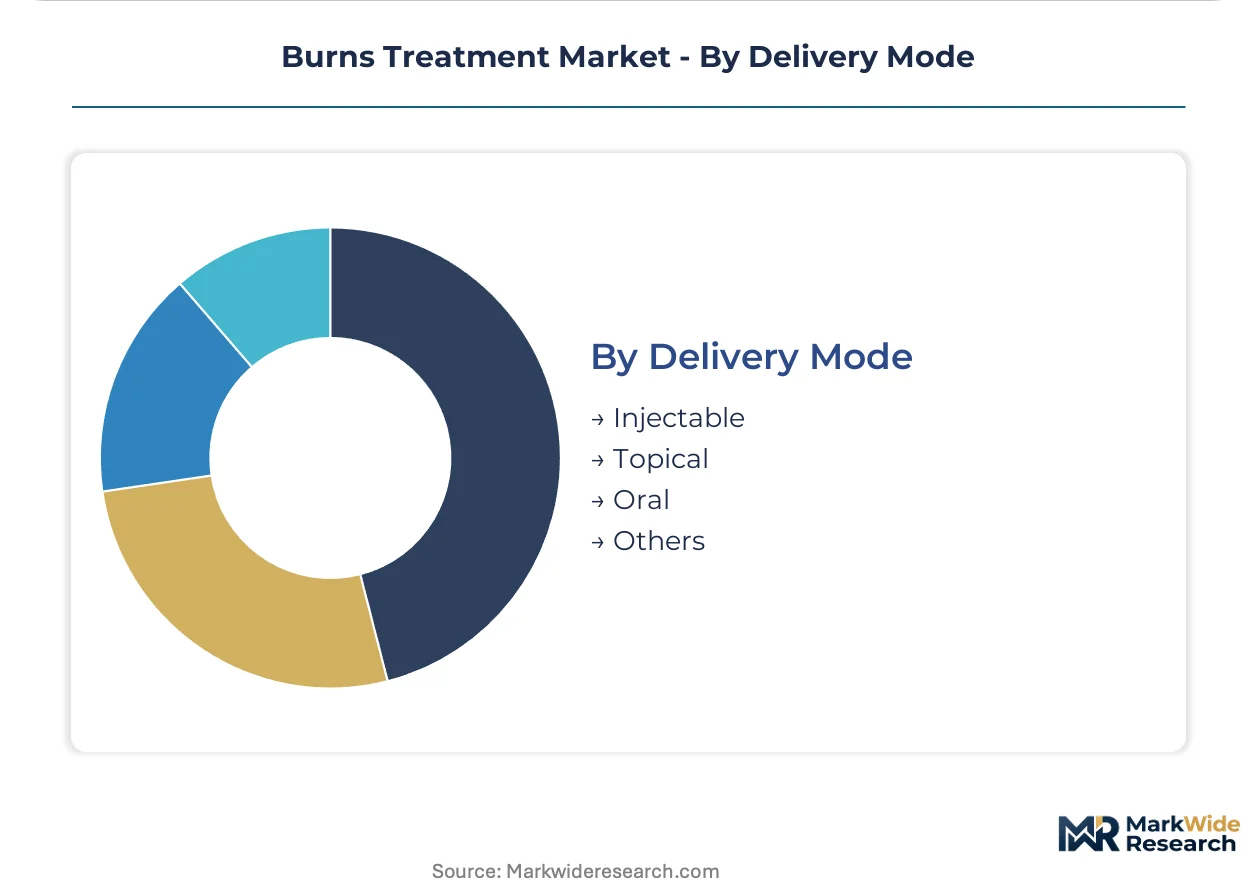
Delivery Mode:
Customer type differentiation separates acute surgical administration from extended outpatient management in therapeutic protocols.
- Topical:Direct application of creams, gels, and impregnated dressings enables localized drug delivery without systemic absorption. This modality dominates superficial and partial-thickness protocols across all care settings.
- Injectable:Subcutaneous or intradermal administration of biological agents supports wound bed preparation and scar modulation in specialized centers.
- Oral:Systemic antibiotics and analgesics complement local wound management in comprehensive treatment plans.
- Others:Inhalation and parenteral routes address specific complications including airway injuries and sepsis.
Topical delivery holds current preference. Injectable biologics present the steepest expansion trajectory as cell therapy platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern burn care crystallized in military field hospitals during the mid-twentieth century before migrating into civilian trauma systems. The United States built the first dedicated burn centers in Boston and Galveston during the 1940s, establishing clinical protocols that diffused globally. Today's market geography reflects where those institutional foundations intersect with reimbursement capacity and regulatory sophistication.
United States
CMS reimbursement premiums for biologic skin substitutes drive hospital capital allocation toward engineered tissue platforms. The FDA maintains stringent 510(k) evidence requirements for novel antimicrobial dressings, extending pre-market timelines for hydrogel combinations. Texas, California, and Florida anchor demand through designated Level I burn receiving centers that centralize severe case volume.
Germany
Hospital procurement associations demand ECHA-compliant REACH documentation for silver sulfadiazine dressings, filtering non-registered suppliers from tender cycles. The EU MDR Annex XVI expansion captures certain antimicrobial products previously regulated as medicinal products, forcing technical resubmissions. Bavaria and North Rhine-Westphalia concentrate manufacturing capacity for hydrofiber and advanced wound matrix production.
United Kingdom
NHS England's specialized burn care networks consolidate purchasing power around single-vendor biologics contracts with multi-year volume commitments. The MHRA operates under retained EU MDR alignment post-Brexit, maintaining parallel certification requirements for market access. London and Manchester host the largest dedicated burn centers, driving procurement for cultured epithelial autografts.
Japan
PMDA regulatory pathways for combination device-drug products create extended review timelines for antimicrobial-impregnated matrices. METI industrial safety mandates for chemical and thermal hazard prevention indirectly shape treatment volume through workplace standards. The Kanto region around Tokyo concentrates academic medical center capacity for severe burn reconstruction.
Australia
TGA classification rules for biological wound products align with EU MDR frameworks, streamlining parallel approval strategies for multinational manufacturers. State-level trauma network designation of burn receiving centers in New South Wales and Victoria funnels severe cases into equipped facilities. The country's cadaveric tissue donation rates fluctuate seasonally, creating allograft supply volatility that drives interest in autologous cell therapy alternatives.
Burns Treatment Market Competitive Environment
The competitive structure tilts toward integrated wound care conglomerates with captive biologics manufacturing. Hospital procurement consolidation favors vendors offering bundled product-service contracts that span acute intervention through post-discharge monitoring. Three archetypes dominate: vertically integrated wound care specialists controlling cryopreservation networks, diversified medical device conglomerates leveraging surgical portfolio breadth, and regional hydrofiber manufacturers anchoring Nordic and Central European supply chains. Dominant competitive moves include M&A to secure biologic manufacturing assets and strategic partnerships with academic medical centers for clinical validation.
Among diversified healthcare conglomerates, Johnson & Johnson and 3M occupy positions spanning traditional dressings through advanced biologics, representing scale-driven procurement consolidation. Smith & Nephew exemplifies the wound care specialist archetype with integrated biologics platforms. Mölnlycke Health Care AB anchors Nordic supply chain positioning through specialized manufacturing concentration.
| Leading Market Players |
|---|
| Smith & Nephew |
| Mölnlycke Health Care AB |
| Johnson & Johnson |
| 3M |
| ConvaTec Group |
| Integra LifeSciences |
| Cardinal Health |
| B. Braun |
| Medline Industries |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up wound care specialists have consolidated cryopreservation networks and biologics manufacturing assets, creating concentrated supply-side ownership that translates into pricing power over hospital procurement committees. This ownership pattern tightens margin discipline across engineered skin substitutes while forcing mid-tier competitors toward commodity dressing segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and biologic origin. Premium tiers capture CMS reimbursement premiums for cultured epithelial autografts with 510(k) or BLA pathways, while standard tiers compete on split-thickness autograft substitution. Price erosion runs through topical antiseptic segments as generic silver sulfadiazine alternatives multiply. Medicaid programs exhibit highest price sensitivity, constraining adoption of engineered substitutes for injuries under 20% TBSA.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Sweden anchor hub-and-spoke patterns for temperature-controlled biologics. Manufacturing draws from bovine collagen suppliers in Bavaria and North Rhine-Westphalia, human keratinocyte culture facilities in Massachusetts and Pennsylvania, and silver sulfadiazine API sources in India. Single-source vulnerability concentrates in liquid nitrogen logistics networks for engineered tissue cold chains. Distribution runs through hospital procurement networks and GPO contracts rather than wholesale pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU MDR Annex XVI expansion and FDA 510(k) pathway revisions continuously reshape competitive access and pricing power.
For Market Incumbents: Anchor biologics manufacturing capacity through captive cryopreservation networks and backward integration into collagen sourcing. Secure multi-year IDN contracts bundling engineered substitutes with remote wound monitoring services. Defend against 3D bioprinting entrants by accelerating clinical validation partnerships with Level I burn centers in Texas and California. For New Entrants and Emerging Players: Ambulatory surgical centers in Arizona, Nevada, and Georgia represent an underserved buyer archetype with expanding burn bay capacity and limited biologics vendor relationships. Target second-degree partial-thickness protocols with single-application hydrofiber dressings carrying integrated antimicrobial coatings. Pursue GPO contract participation through demonstrated readmission reduction rather than price undercutting. For Investors and Strategic Acquirers: Diversified medical device conglomerates with surgical portfolio breadth are the most active acquirer in this space, seeking biologics manufacturing assets to complete wound care platform coverage. The 5-10 year viability window favors targets with EU MDR certification and established hospital procurement relationships over pre-revenue cell therapy platforms. Monitor CMS reimbursement schedule revisions for autologous keratinocyte therapies as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Quality Certification | Notified body approval under 2017/745 unlocks 20-35% price premiums in French and Belgian tenders. |
| Hospital System Partnership | IDN contracts in North Carolina, Tennessee, and Virginia bundle biologics with telemedicine monitoring protocols. |
| Backward Integration into Collagen Sourcing | Captive bovine matrix supply secures margin control against Bavarian and North Rhine-Westphalian supplier concentration. |
| Reimbursement Strategy | CMS RVU alignment for engineered substitutes redirects hospital capital away from autograft harvesting infrastructure. |
| 3D Bioprinting Platform Development | Patient-matched scaffold fabrication eliminates tissue bank intermediaries and associated cold chain cost structures. |
Study Parameters
Multiple input streams — structured interviews with burn surgeons and hospital procurement managers, GPO contract database analysis, and FDA 510(k) filing review — were reconciled against secondary validation from CMS Medicare reimbursement schedules and EMA MDR technical documentation. Bottom-up modeling of product-level demand across skin grafts, dressings, and topical solutions was triangulated with top-down hospital capacity and trauma network designation data.
Historical utilization patterns were cross-referenced against panel input from formulary directors and biomedical engineers to construct segment-level projections across the analysis window. Modeled dimensions include wound depth classification, biologic versus synthetic origin, end-user channel, and regional regulatory cluster. CAGRs were derived from surgical volume trends, reimbursement weight adjustments, and biologics manufacturing capacity expansion trajectories.
Underlying measurement precision varies by segment; third-degree burn applications with established CMS coding carry tighter precision than emerging autologous cell therapy categories. Forecasts reflect documented assumptions regarding trauma network centralization and MDR compliance timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Malaria Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Isovaleric Acidemia Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Iron Deficiency Anemia Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Non-Invasive Surgery Market
Medical Treatment
Tissue Repair Technologies Market
Medical Treatment
Urea Cycle Disorders Treatment Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market