
 Carbon Monoxide (Co) Detector Market | 2026-2036
Carbon Monoxide (Co) Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Monoxide (Co) Detector Market Intelligence
Expanded manufacturing capacity in China is tilting the supply landscape for core sensor components, affecting cost structures for device assemblers. Kidde sustains its market presence through extensive retail channel distribution in North America. Honeywell leverages its brand in both residential and commercial automation systems to bundle safety products. Robert Bosch GmbH competes on technology, integrating advanced electrochemical sensors into its smart home ecosystem, which appeals to property developers focused on premium builds.
A carbon monoxide detector is a life-safety device engineered to sense dangerous concentrations of CO gas in an enclosed space. These units typically utilize an electrochemical sensor where ambient CO reacts with an electrode, generating a measurable electrical current that triggers an alarm above a specific parts-per-million threshold. Battery-operated and plug-in models dominate the residential application segment due to their ease of installation. The electrochemical technology segment holds the largest share, while demand for smart, wireless combination smoke and CO detectors is accelerating within commercial complexes.
Regulatory frameworks such as the UL 2034 standard in the United States and the EN 50291 standard in Europe define critical performance and safety requirements. These mandates, often incorporated into national building codes in countries like Canada and Australia, make installation non-negotiable in new residential constructions and many commercial facilities. The key decision for manufacturers revolves around balancing production cost against the integration of advanced smart features and multi-gas detection capabilities.
Market Dynamics
The market's trajectory is fundamentally shaped by the codification of safety mandates into law. Stricter building codes are transforming carbon monoxide detectors from discretionary safety products into non-negotiable components for residential and commercial occupancy, particularly in new constructions.
Growth Catalysts
- Regulatory Mandates:Increasingly stringent safety regulations for rental properties and new homes in countries like Canada and Germany make detector installation a legal requirement, creating a baseline of guaranteed demand.
- Smart Home Integration:Demand from property developers focused on premium residential builds is pulling advanced detectors into smart home ecosystems, where they are bundled with other automation and security features.
- Sensor Technology Maturation:The widespread availability of reliable and cost-effective electrochemical sensors, supported by expanded manufacturing in China, lowers the barrier for mass-market adoption and retrofitting programs.
Market Restraints
- Cost of Retrofitting:The upfront cost of purchasing and installing detectors across large portfolios of older buildings without existing mandates remains a significant financial barrier for property owners and managers.
- Technical Limitations:Lingering consumer skepticism due to false alarms from older or lower-end sensor technologies can impede adoption in markets where detectors are not legally required.
- Product Cannibalization:The market for standalone CO detectors faces pressure from combination smoke and CO alarms, which offer consolidated functionality and can reduce the total number of discrete devices purchased.
Strategic Opportunities
- Underpenetrated Geographies:Rapidly urbanizing regions in Latin America and Southeast Asia with nascent building safety regulations represent a long-term growth opportunity as their standards evolve to match those in North America and Europe.
- Data and Service Monetization:Integrating smart detectors with building management systems allows for new revenue streams from data analytics, predictive maintenance alerts, and compliance reporting services for commercial clients.
- Application Expansion:Targeting non-residential applications such as enclosed parking structures, warehouses with forklift traffic, and commercial kitchens provides a path for diversification beyond the core residential segment.
Industry Challenges
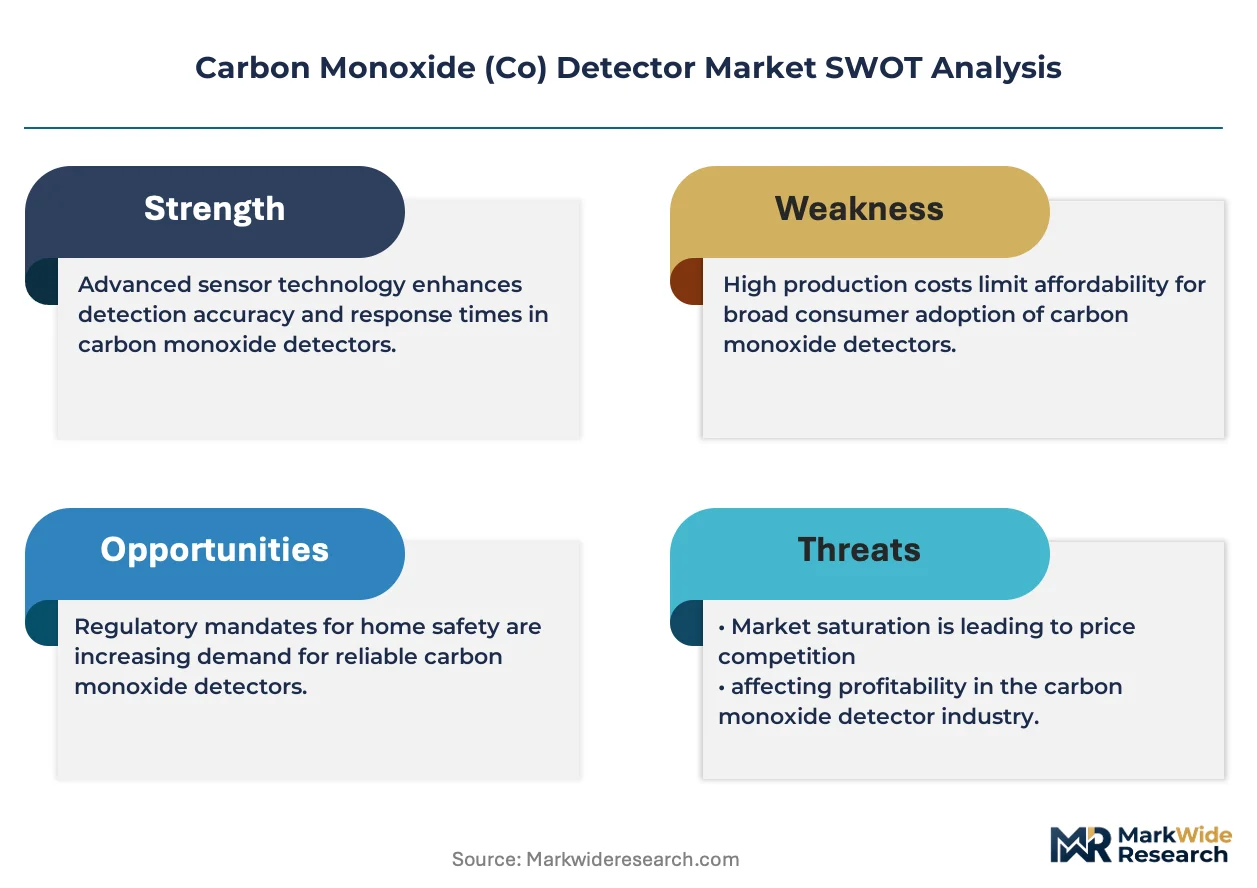
- Certification Complexity:Manufacturers face significant delays and costs in navigating the fragmented and rigorous certification processes required by standards like UL 2034 in the US and EN 50291 in Europe.
- Supply Chain Concentration:Heavy reliance on a small number of specialized suppliers in Asia for critical electrochemical sensor components creates vulnerabilities to logistical disruptions and geopolitical risk.
- Interoperability Hurdles:Ensuring that smart detectors can reliably communicate across a diverse and fragmented landscape of third-party smart home platforms and protocols remains a persistent technical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Monoxide (Co) Detector Market |
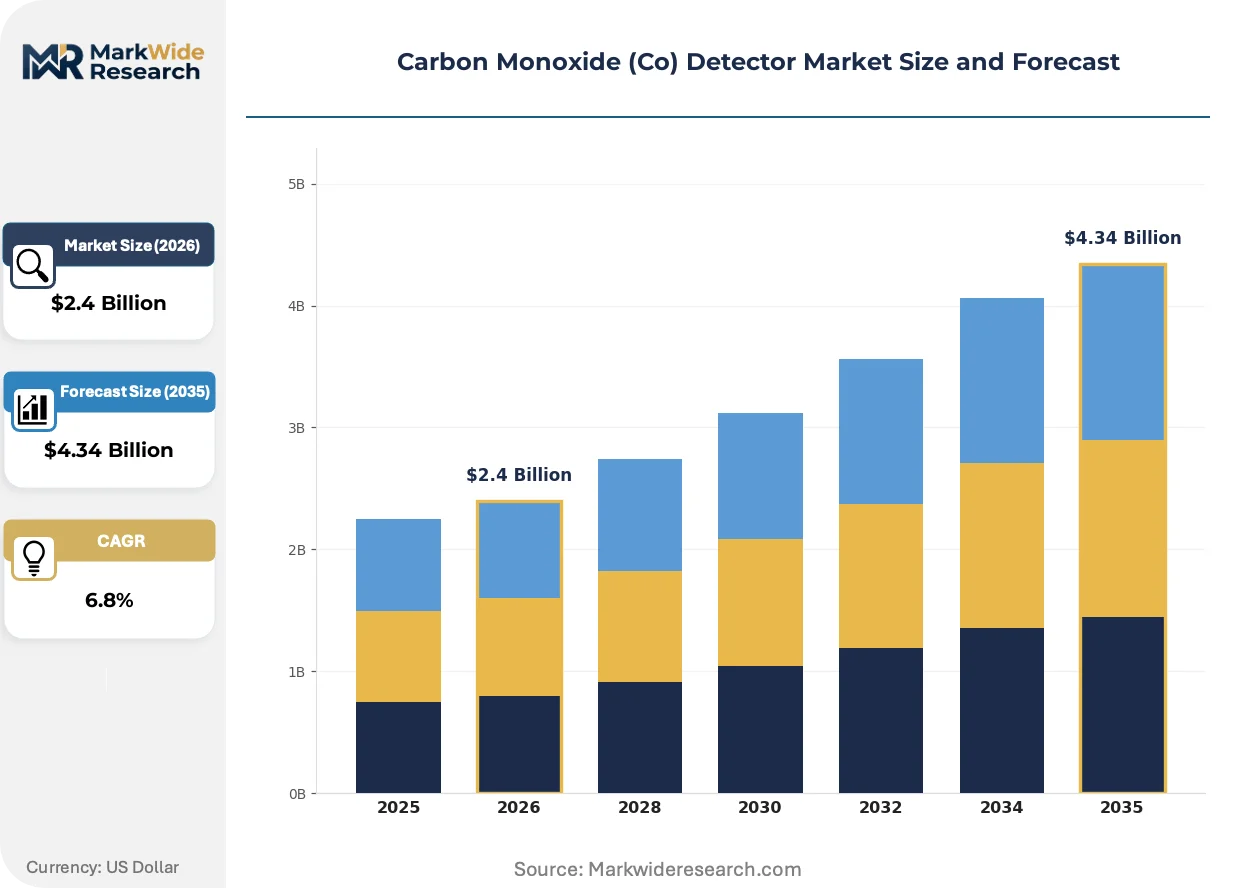
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery-operated, Hardwired, Plug-in, Combination Smoke & CO, Wireless Technology: Electrochemical, Metal Oxide Semiconductor, Biomimetic Sensor, Digital, Optical Application: Residential Buildings, Commercial Complexes, Industrial Facilities, Hospitality Establishments, Educational Institutions End User: Homeowners, Facility Managers, Safety Inspectors, Property Developers |
| Companies Covered | Kidde, First Alert, Honeywell, Robert Bosch GmbH, Siemens AG, ABB Ltd., Aeroqual Ltd., Universal Security Instruments, System Sensor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Monoxide (Co) Detector Market Strategic Shifts & Innovations
Device intelligence is transforming carbon monoxide detectors from single-purpose alarms into connected data points within a building's broader health and safety infrastructure. This evolution is driven by sensor enhancements, updated regulatory hurdles, and new purchasing models.
Advanced electrochemical sensors incorporating digital signal processing offer superior accuracy in measuring CO concentrations. Property developers and commercial building managers are adopting these systems to minimize liability and improve tenant safety. This technological shift is rendering obsolete older, less stable biomimetic sensor designs that were susceptible to nuisance alarms from common household vapors.
Updated performance standards, including revisions to UL 2034 in the United States, impose stricter requirements for sensor longevity and resistance to false alarm triggers. This regulatory tightening compels manufacturers to engineer more sophisticated devices with improved filtering algorithms. The residential sector is most affected, as product cycles accelerate to phase out legacy models that no longer meet the criteria referenced in modern building codes.
A distinct shift in purchasing behavior favors integrated safety packages over individual device sales. This pattern disrupts the traditional DIY retail channel, creating an advantage for professional installers and smart home service providers who bundle CO detection with smoke alarms and security systems. The trend is most pronounced in the North American new home construction market, where builders often standardize on a single, comprehensive safety ecosystem.
Carbon Monoxide (Co) Detector Market Segmentation
The Carbon Monoxide (CO) Detector Market is highly stratified across various dimensions, reflecting diverse user needs and technological advancements. Understanding these segments is crucial for manufacturers to tailor product development, pricing strategies, and distribution channels effectively. Regulatory mandates often dictate minimum product specifications, influencing adoption patterns across different applications.
Product Type:
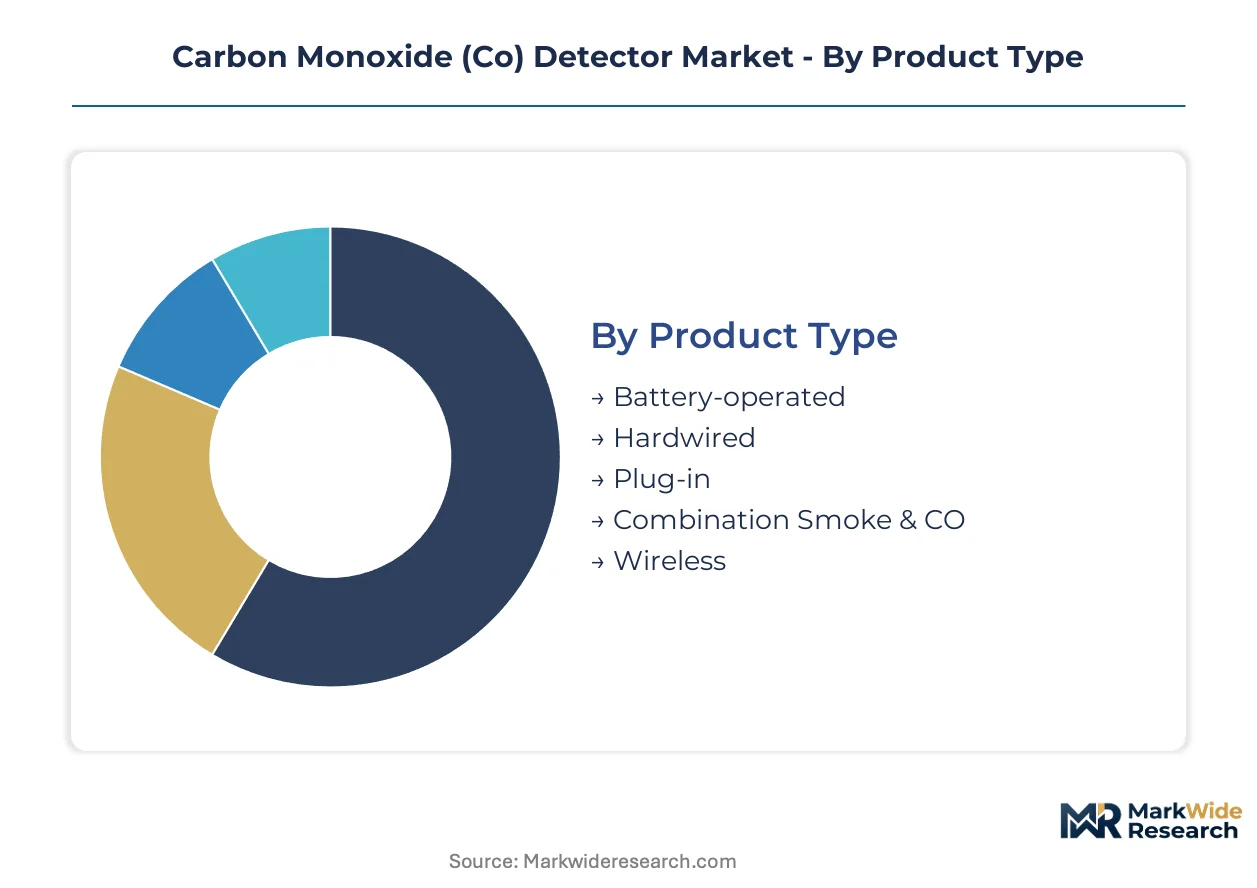
The product type segment illustrates a clear maturity spectrum, from established standalone units to integrated smart safety solutions.
- Combination Smoke & CO:These integrated devices combine smoke and carbon monoxide detection into a single unit, often featuring smart capabilities for remote monitoring. Demand is accelerating within commercial complexes and new residential constructions due to consolidated functionality and easier installation.
- Wireless:Wireless detectors communicate via radio frequencies to a central hub or smart home system, offering flexible placement and simplified installation without extensive wiring. Property developers focused on premium builds increasingly integrate these into comprehensive smart home ecosystems.
- Battery-operated:These detectors function independently using internal batteries, providing ease of installation and portability for residential applications.
- Hardwired:Hardwired units connect directly to a building's electrical system, often featuring battery backup, and are common in new residential and commercial constructions.
- Plug-in:Plug-in models offer simple installation by plugging into a standard electrical outlet, primarily serving the residential application segment.
Battery-operated models retain volume leadership; combination smoke and CO detectors hold the steepest expansion curve.
Technology:
Technology choices critically influence detector performance across diverse application environments, from residential to industrial settings.
- Electrochemical:This technology utilizes a chemical reaction between CO and an electrode to generate an electrical current, offering high accuracy and stability over time. Electrochemical sensors hold the largest share due to their proven reliability and cost-effectiveness for mass-market adoption.
- Digital:Digital sensors incorporate advanced signal processing and algorithms to enhance accuracy, reduce false alarms, and enable integration with smart home systems. Property developers and commercial building managers are adopting these for superior performance and data capabilities.
- Metal Oxide Semiconductor:These sensors detect CO through changes in electrical resistance when exposed to the gas, typically used in lower-cost or industrial applications.
- Biomimetic Sensor:Older biomimetic sensors mimic the body's reaction to CO, but are largely being phased out due to susceptibility to nuisance alarms from common household vapors.
- Optical:Optical sensors are less common for CO detection but are prevalent in smoke alarms, with some advanced units combining technologies.
Electrochemical sensors command the largest market share due to their proven reliability, while digital integration is rapidly gaining adoption in premium segments.
Application:
Regulatory frameworks profoundly shape demand patterns across various application sectors, mandating specific detector types in new constructions.
- Residential Buildings:This segment includes single-family homes, multi-family units, and rental properties, driven by stringent building codes and tenant safety regulations in countries like Canada and Germany. Stricter mandates make CO detector installation non-negotiable in new constructions.
- Commercial Complexes:Commercial complexes, such as office buildings and retail spaces, require integrated safety systems for occupant protection and compliance with local fire and safety codes. Demand for smart, wireless combination detectors is accelerating within this segment.
- Industrial Facilities:Industrial facilities like manufacturing plants and warehouses utilize detectors to monitor CO levels in areas with combustion sources or vehicle exhaust.
- Hospitality Establishments:Hotels and motels install detectors to ensure guest safety, often driven by local ordinances and brand safety standards.
- Educational Institutions:Schools and universities implement CO detection systems to protect students and staff within classrooms and dormitories.
Residential buildings represent the foundational demand segment, with commercial complexes showing strong growth driven by integrated safety system adoption.
End User:
End-user segments are differentiated by their primary purchasing motivations, ranging from individual safety to large-scale property management.
- Homeowners:Individual homeowners purchase detectors for personal and family safety, often prioritizing ease of installation and affordability for residential application.
- Property Developers:These stakeholders integrate CO detectors into new construction projects, favoring advanced, bundled solutions that align with smart home ecosystems and building codes.
- Facility Managers:Facility managers oversee safety systems in commercial and industrial buildings, focusing on compliance, system integration, and long-term reliability.
- Safety Inspectors:Safety inspectors enforce building codes and regulations, influencing the types and standards of detectors installed in various properties.
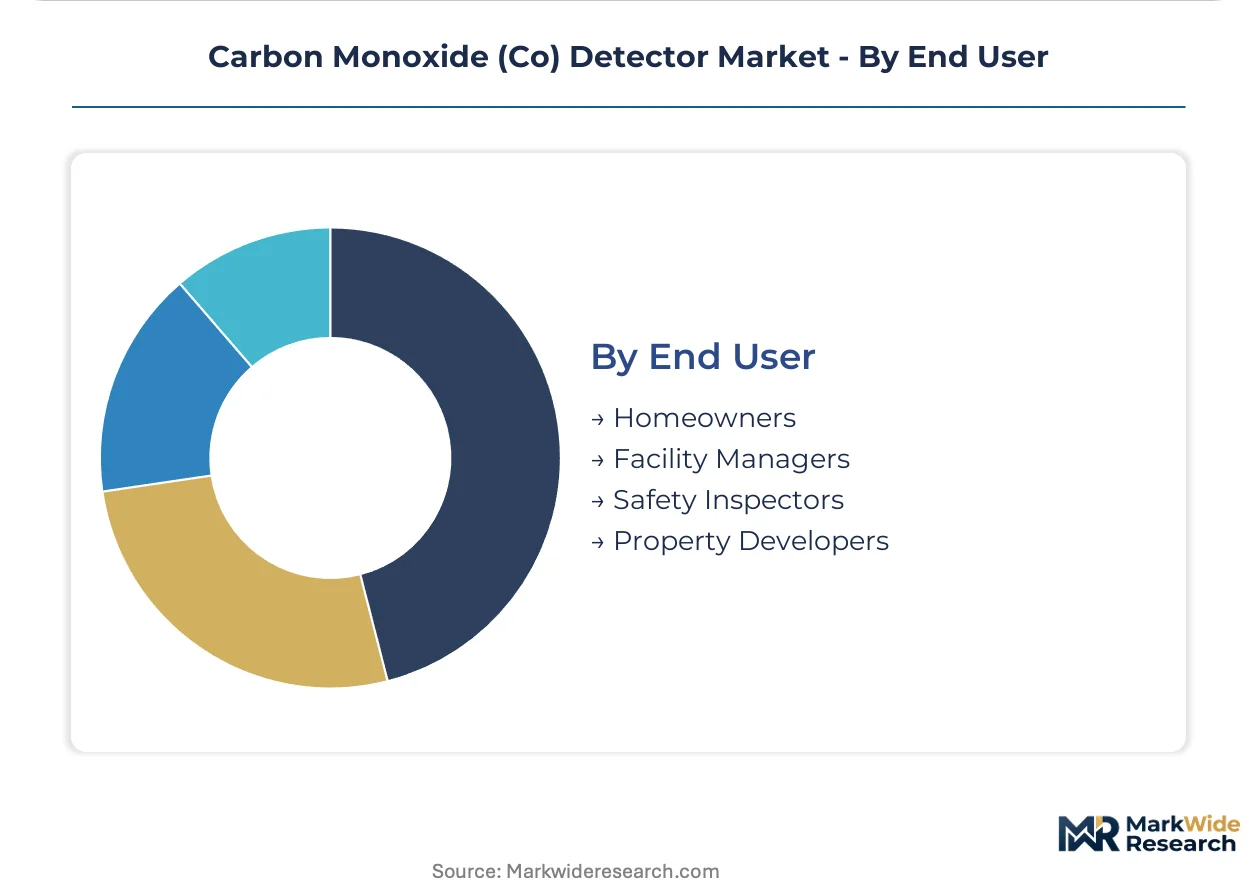
Homeowners constitute a significant volume driver, while property developers exert substantial influence on technology adoption in new constructions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for carbon monoxide detectors vary significantly by region. Developed economies prioritize advanced smart home integration and regulatory compliance. Emerging markets focus more on foundational safety and basic battery-operated units. This differential shapes product adoption and market growth trajectories.
United States
Demand for CO detectors in the United States stems from new residential construction and smart home ecosystem integration. The UL 2034 standard revisions impose stricter requirements for sensor longevity and false alarm resistance. Major metropolitan areas like New York City and Los Angeles see strong demand for bundled safety solutions in high-rise residential projects.
Germany
Germany exhibits strong demand for CO detectors due to stringent safety regulations in rental properties and new builds. The EN 50291 standard mandates critical performance and safety requirements for these devices. Cities such as Munich and Berlin are adopting advanced electrochemical sensors within premium smart home developments.
Canada
Canadian provinces enforce strict building codes that make CO detector installation non-negotiable in new residential constructions. Health Canada guidelines influence product specifications and safety standards for consumer devices. Toronto and Vancouver's rapidly expanding urban centers drive demand for hardwired and combination smoke/CO alarms in multi-unit dwellings.
China
China's market for CO detectors is expanding, driven by urbanization and an increasing focus on industrial safety standards. GB standards are evolving to align with international safety benchmarks for building materials and safety equipment. Manufacturing hubs in the Yangtze River Delta are increasing production capacity for core sensor components, influencing global supply.
Brazil
Brazil represents an underpenetrated geography with nascent building safety regulations beginning to emerge. Local municipalities are slowly introducing ordinances for CO detection in new residential and commercial developments. São Paulo and Rio de Janeiro are experiencing growth in commercial complex installations, driven by multinational corporate safety policies.
Carbon Monoxide (Co) Detector Market Key Industry Players
Capability concentration sits with one tier, primarily integrating advanced sensor technologies and smart home ecosystems, while scale advantage sits with another, focusing on mass-market distribution and cost-effective production. The market structure exhibits a tiered consolidation, with established brands competing against specialized technology providers. Strategic archetypes include diversified safety solution providers, smart home integrators, and core component manufacturers. Market players often engage in strategic partnerships to expand product portfolios and geographic reach.
At the scale-driven end of the market, Kidde exemplifies extensive retail channel distribution, particularly in North America, ensuring broad consumer access for standalone and battery-operated models. Honeywell occupies a position as a diversified safety solution provider, leveraging its established brand in both residential and commercial automation systems to bundle safety products effectively. Robert Bosch GmbH represents the premium-tier vector, integrating advanced electrochemical sensors into its smart home ecosystem, which appeals to property developers focused on high-end builds and comprehensive smart living solutions.
| Leading Market Players |
|---|
| Kidde |
| First Alert |
| Honeywell |
| Robert Bosch GmbH |
| Siemens AG |
| ABB Ltd. |
| Aeroqual Ltd. |
| Universal Security Instruments |
| System Sensor |
| Others |
Cost & Logistics Intelligence
Expanded manufacturing capacity in China for electrochemical sensors influences global component pricing and device assembler cost structures. This utilization dynamic directly shapes supplier behavior and overall market pricing posture for CO detectors.
Pricing Analysis
Contract-based long-term offtake agreements increasingly define pricing for large property developers integrating CO detectors into new builds. Price differentiation stems from certification levels, such as UL 2034 or EN 50291 compliance, and the integration of advanced smart features. Pricing softness for standalone units reflects product cannibalization from combination smoke and CO alarms. Homeowners remain highly price-sensitive, while property developers focused on premium builds prioritize technology and integration over cost.
Supply Chain Analysis
Heavy reliance on a small number of specialized suppliers in Asia for critical electrochemical sensor components creates significant single-source vulnerability. Geographic supply concentration for these core components centers primarily in China, influencing global availability. The industry relies on electrochemical sensors as its primary input. Downstream distribution runs through extensive retail channels for homeowners and direct partnerships with property developers and professional installers for new constructions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon monoxide detector market is experiencing a notable buyer-power shift, driven by property developers consolidating purchases for integrated safety packages. This trend disrupts traditional retail channels and favors comprehensive smart home ecosystem providers.
For Market Incumbents:Harden existing retail channel distribution networks, particularly in North America, to maintain broad consumer access for standalone units. Incumbents must invest in R&D for advanced electrochemical sensors to counter product cannibalization from combination smoke and CO alarms. Deepen strategic partnerships with professional installers and smart home service providers to leverage the shift towards integrated safety packages. Prioritize certification investment to meet evolving UL 2034 and EN 50291 standards.
For New Entrants and Emerging Players:Rapidly urbanizing regions in Latin America and Southeast Asia represent the most penetrable entry points for foundational CO detector solutions. Non-residential applications like enclosed parking structures and commercial kitchens offer specialized market niches for diversification. New entrants should focus on cost-effective, reliable electrochemical sensor technology to meet nascent building safety regulations. A direct sales approach targeting local municipalities and commercial facility managers can facilitate market entry.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upward across core sensor manufacturing, particularly in Asia, driven by expanded production capacity. The market offers long-term viability, anchored by non-negotiable regulatory mandates in residential and commercial sectors. Acquisition targets should include specialized technology providers offering advanced electrochemical sensors or robust smart home integration capabilities. The widespread adoption of next-generation digital sensors and multi-gas detection represents a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Core Sensor Manufacturing | Increasing production capacity in China lowers component costs for global device assemblers. |
| Strengthen Retail Channel Partnerships | Ensures broad consumer access for standalone and battery-operated models, especially in North America. |
| Integrate Smart Home Ecosystems | Appeals to property developers seeking bundled safety solutions for premium residential builds. |
| Invest in Advanced Sensor R&D | Enhances accuracy and reduces false alarms, meeting stricter UL 2034 and EN 50291 standards. |
| Diversify into Non-Residential Applications | Captures new revenue streams from industrial facilities and commercial kitchens beyond core residential. |
Research Approach
Desk research of UL 2034 standards, EN 50291 standards, national building codes, and industry association reports preceded structured interviews with property developers, facility managers, sensor manufacturers, and safety inspectors. This approach combined primary insights with secondary validation across diverse data points. Bottom-up data collection and top-down market sizing ensured comprehensive triangulation.
Assumptions regarding regulatory mandates and smart home integration rates were held fixed across the analysis window, while sensor technology maturation was varied. The analytical framework modeled segments by product type, technology, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected new construction starts. Sensor component pricing and evolving building codes served as key forecast inputs.
Practitioners should monitor for early signals from new regulatory changes, evolving supply chain concentration, and geopolitical risks that could impact market dynamics. Forecasts reflect assumptions documented at the time of publication. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Global Ultrasonic Air Bubble Detectors Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
Europe Portable Gas Detector Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Global Inflation Device Market
Detection and Regulation Devices
X-Ray Detectors Market
Detection and Regulation Devices
Transient Voltage Suppressor (TVS) Diode Market
Detection and Regulation Devices
Global Gas Detection System Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Leak Detection Equipment Market