
 Negative Temperature Coefficient (NTC) Thermistor Market | 2026-2036
Negative Temperature Coefficient (NTC) Thermistor Market Size, Share, and Industry Trends Forecast 2026-2036
Negative Temperature Coefficient (NTC) Thermistor Market Analysis
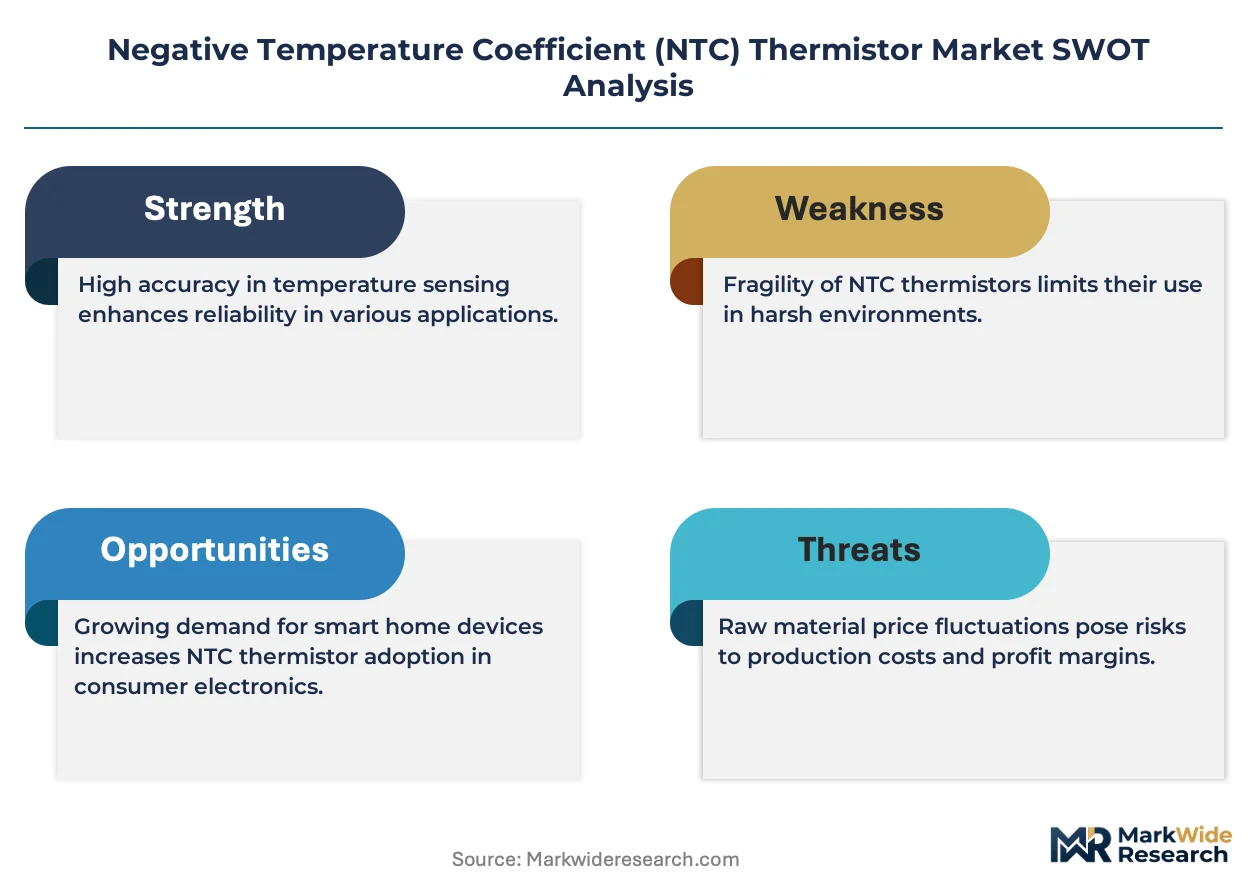
Specialized ceramics engineering talent is rotating toward precision temperature sensing as electric vehicle programs scale thermal runaway protection needs. Murata Manufacturing leverages its multilayer ceramic expertise to dominate chip-style NTC production for compact electronics. TE Connectivity sustains aerospace and industrial channel control through calibrated probe assemblies with extended temperature ranges. Vishay Intertechnology anchors automotive qualification programs with AEC-Q200 compliant disc and glass-encapsulated portfolios.
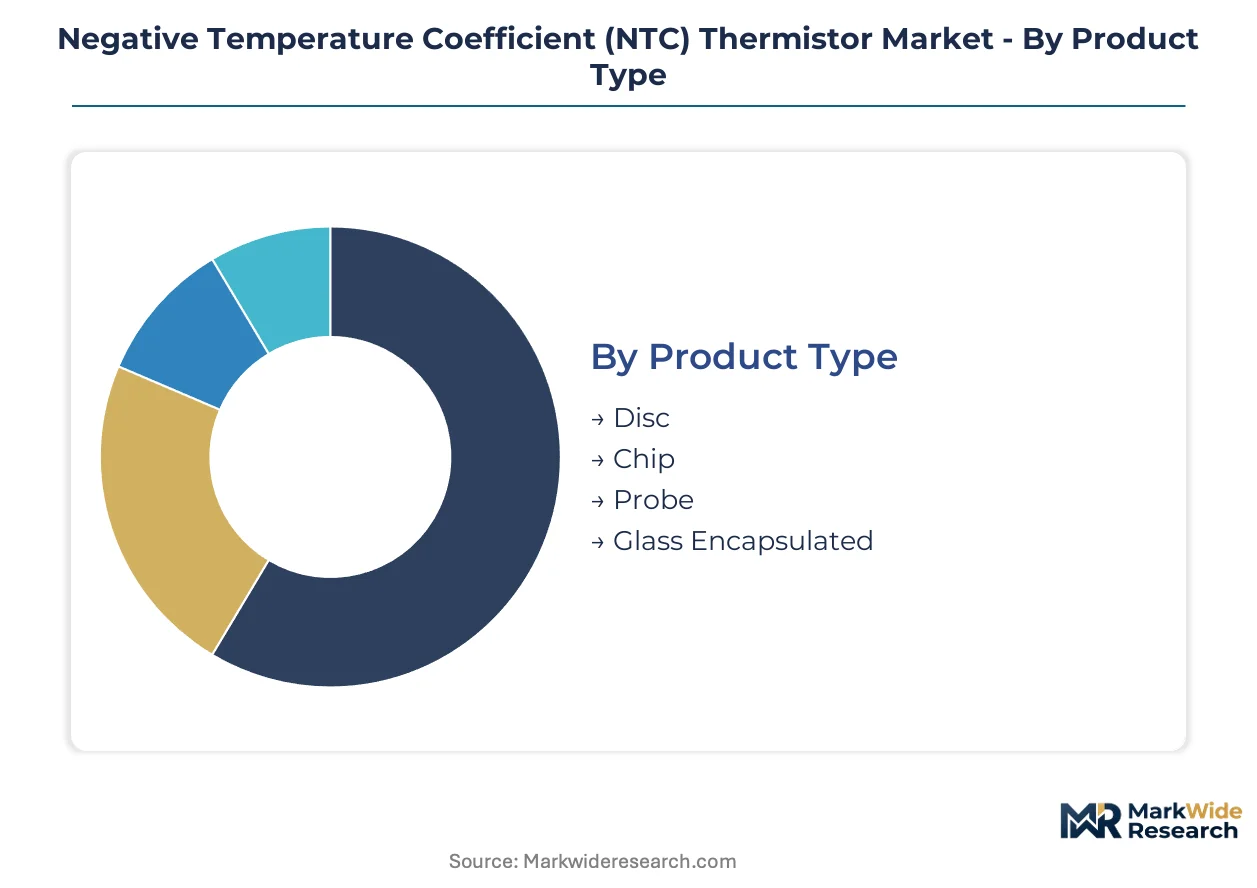
A negative temperature coefficient thermistor is a semiconductor ceramic device, typically formulated from manganese, cobalt, nickel, and copper oxide transitions, whose electrical resistance decreases nonlinearly as temperature rises; manufacturers sinter these metal oxide powders at controlled temperatures to achieve precise B-value constants and beta tolerances for accurate thermal sensing. The component's primary commercial purpose is to provide cost-effective, repeatable temperature measurement and inrush current suppression across circuits subject to thermal drift or startup surge conditions. Chip thermistors command the largest volume share as wearable and handheld device miniaturization demands surface-mount compatibility, while probe-style configurations capture premium margin pools in medical and automotive fluid monitoring where hermetic sealing and response time specifications tighten. Glass-encapsulated variants represent the fastest-growing product category for high-humidity and corrosive environments, particularly in industrial equipment and outdoor energy infrastructure applications.
Automotive homologation through NHTSA FMVSS and UN ECE R100 shapes NTC thermistor reliability standards for traction battery thermal management, while IEC 60751 and JIS C 1604 define interchangeability tolerances that determine supplier eligibility for industrial and Japanese domestic markets. REACH substance restrictions and RoHS compliance requirements constrain electrode material selections and solder formulations, pushing manufacturers toward lead-free and reduced-cobalt compositions. Stakeholders must monitor how battery-electric platform thermal architectures evolve their sensor density and placement strategies, as these design choices will determine which thermistor form factors and accuracy grades secure long-term design wins.
Market Dynamics
Automotive electrification programs are compressing thermal sensor placement cycles, forcing NTC thermistor manufacturers to synchronize qualification timelines with battery platform launches rather than traditional component refresh schedules.
Growth Catalysts
- UN ECE R100:Traction battery thermal management mandates in Europe and aligned markets require redundant temperature sensing arrays, expanding per-vehicle thermistor counts.
- Chip-style surface-mount form factors:Wearable electronics manufacturers specify 0402 and 0201 case sizes for continuous skin temperature monitoring, pulling precision ceramic processing investments.
- South Korean battery manufacturing clusters:LG Energy Solution and Samsung SDI cell plants concentrate procurement authority for high-accuracy probe assemblies serving pack-level thermal runaway detection.
Market Restraints
- Cobalt oxide supply concentration:Electrode material formulations depend on cobalt oxide processing capacity concentrated in Central African mining and Chinese refining operations, creating input cost volatility.
- Platinum thin-film RTD substitution:Aerospace and laboratory calibration applications tolerate higher unit costs for linear temperature response, displacing glass-encapsulated NTCs in precision segments.
- REACH substance authorization:ECHA scrutiny of nickel oxide compounds extends formulation approval timelines, constraining European-qualified product portfolios.
Strategic Opportunities
- India BIS certification expansion:Domestic solar inverter and EV charger manufacturing under PLI scheme incentives creates demand for humidity-resistant glass-encapsulated thermistors qualified to Indian standards.
- Edge AI thermal monitoring convergence:Integration of NTC arrays with on-chip machine learning inference enables predictive overheating alerts in industrial motor drives without cloud dependency.
- Direct procurement from cell manufacturers:Bypassing tiered automotive supplier hierarchies allows thermistor specialists to capture specification influence in next-generation solid-state battery programs.
Industry Challenges
- AEC-Q200 Rev E certification timelines:Extended qualification cycles for automotive-grade chip thermistors delay revenue recognition from platform wins secured 18-24 months prior.
- Multilayer ceramic co-firing expertise scarcity:Chip thermistor manufacturing requires precision between ceramic sintering and electrode patterning that few facilities outside Japan and South Korea have mastered.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Negative Temperature Coefficient (NTC) Thermistor Market |
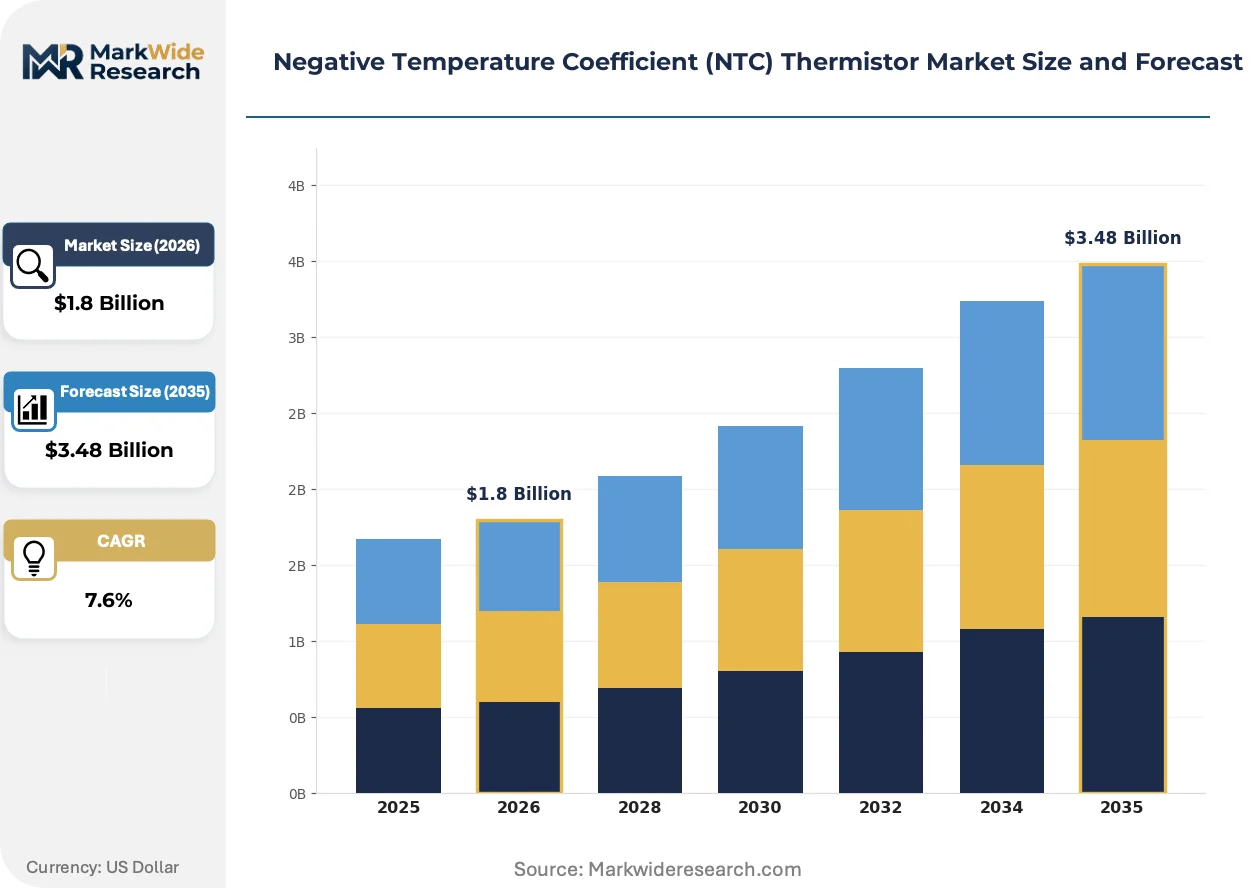
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc, Chip, Probe, Glass Encapsulated Application: Temperature Measurement, Overcurrent Protection, Inrush Current Limiting, Temperature Compensation End User: Consumer Electronics, Automotive, Industrial Equipment, Home Appliances Temperature Range: -40 to 100°C, 0 to 150°C, 150 to 250°C, 250 to 300°C |
| Companies Covered | Vishay Intertechnology, Murata Manufacturing, Mitsubishi Materials Corporation, Vancera Technology, TE Connectivity, TDK Corporation, Shibaura Electronics, Thinking Electronic Industrial, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Negative Temperature Coefficient (NTC) Thermistor Market Emerging Trajectories
NTC thermistor evolution is bifurcating between extreme miniaturization for consumer electronics and ruggedized packaging for energy infrastructure, with manufacturing process innovation determining competitive position in each trajectory.
Multilayer ceramic chip thermistors are miniaturizing below 1.0mm case sizes while maintaining beta tolerance tightness, enabling smartwatch manufacturers to embed continuous temperature tracking without industrial design compromise. Medical device OEMs specify these reduced-footprint components for continuous glucose monitor substrates where space competes with sensor density. The dimensional compression is forcing Murata and TDK to retool co-firing lines for sub-micron electrode alignment.
China's dual carbon goals issued through MEE are tightening energy efficiency verification requirements for industrial motor drives and HVAC equipment, mandating calibrated temperature sensing for performance certification. GB standard harmonization with IEC 60751 is accelerating domestic thermistor accuracy grade adoption. Domestic equipment builders are upgrading from uncalibrated thermistor-discount suppliers to interchangeability-tolerance-qualified sources.
Battery-electric vehicle procurement teams are consolidating temperature sensor specifications across cell, module, and pack monitoring layers, reducing qualified supplier lists from twelve to four vendors per platform. Tier-1 automotive thermal management suppliers are responding with integrated probe-assembly-plus-connector modules that compress installation labor. This consolidation is most visible in German and South Korean automotive programs where platform standardization committees have eliminated single-point thermistor specifications.
Negative Temperature Coefficient (NTC) Thermistor Market Segmentation
NTC thermistor procurement patterns diverge sharply across form factor, thermal application, and end-use qualification requirements. Regulatory mandates from NHTSA and UN ECE R100 enforce segment-specific reliability standards that reshape supplier eligibility and pricing power.
Product Type:
AEC-Q200 automotive qualification tiers separate commodity disc thermistors from precision chip and probe variants that command specification influence in battery-electric platforms.
- Chip:Multilayer ceramic construction achieves 0402 and 0201 case sizes through sub-micron electrode alignment. Wearable OEMs in South Korea and Japan specify these for continuous skin temperature monitoring in smartwatches and continuous glucose monitors.
- Glass Encapsulated:Hermetic sealing withstands high-humidity and corrosive environments. India's solar inverter manufacturing under PLI scheme incentives is pulling demand for BIS-certified variants in outdoor energy infrastructure.
- Disc:Cost-optimized manganese-cobalt-nickel oxide formulations serve consumer electronics and home appliance volume markets.
- Probe:Calibrated assemblies with extended temperature ranges capture automotive fluid monitoring and medical device applications requiring fast response times.
Chip thermistors handle the majority of throughput; Glass Encapsulated is the fastest mover on share.
Application:
Functional differentiation determines margin structure, with measurement applications demanding interchangeability tolerances while protection functions tolerate wider beta tolerances.
- Temperature Measurement:IEC 60751 and JIS C 1604 interchangeability standards constrain supplier pools to qualified Japanese and European manufacturers. Battery management systems require redundant sensor arrays per UN ECE R100 mandates.
- Temperature Compensation:Circuit stability applications in precision oscillators and power supplies specify tight B-value constants. Telecom infrastructure deployment in Germany and South Korea drives specification tightening.
- Overcurrent Protection:Self-heating characteristics enable resettable circuit protection without fuse replacement. Industrial motor drives under China's MEE efficiency verification requirements mandate calibrated sensing.
- Inrush Current Limiting:High initial resistance suppresses startup surges in power supplies and HVAC equipment. Cost pressure dominates specification in residential appliance markets.
Temperature Measurement commands the highest average selling prices; Temperature Compensation is expanding most quickly on specification upgrade cycles.
End User:
Customer concentration patterns concentrate procurement authority in automotive platform committees and East Asian electronics contract manufacturers.
- Automotive:Traction battery thermal management requires AEC-Q200 Rev E qualified components with extended temperature cycling validation. German and South Korean OEMs have consolidated qualified supplier lists from twelve to four vendors per platform.
- Consumer Electronics:Wearable and handheld device miniaturization demands surface-mount compatibility at sub-1.0mm footprints. Murata Manufacturing and TDK dominate co-firing capacity for precision chip production.
- Industrial Equipment:China's dual carbon goals mandate calibrated temperature sensing for motor drive and HVAC efficiency certification. GB standard harmonization with IEC 60751 accelerates accuracy grade adoption.
- Home Appliances:Cost-optimized disc thermistors serve refrigerator and air conditioner compressor protection. REACH substance restrictions constrain electrode material selections toward reduced-cobalt compositions.
Automotive absorbs the premium margin pool; Industrial Equipment is climbing the fastest on regulatory enforcement.
Temperature Range:
Extended-range qualification requirements fragment manufacturing capability, with 250°C+ capability concentrated in specialized glass-encapsulated and probe assembly facilities.
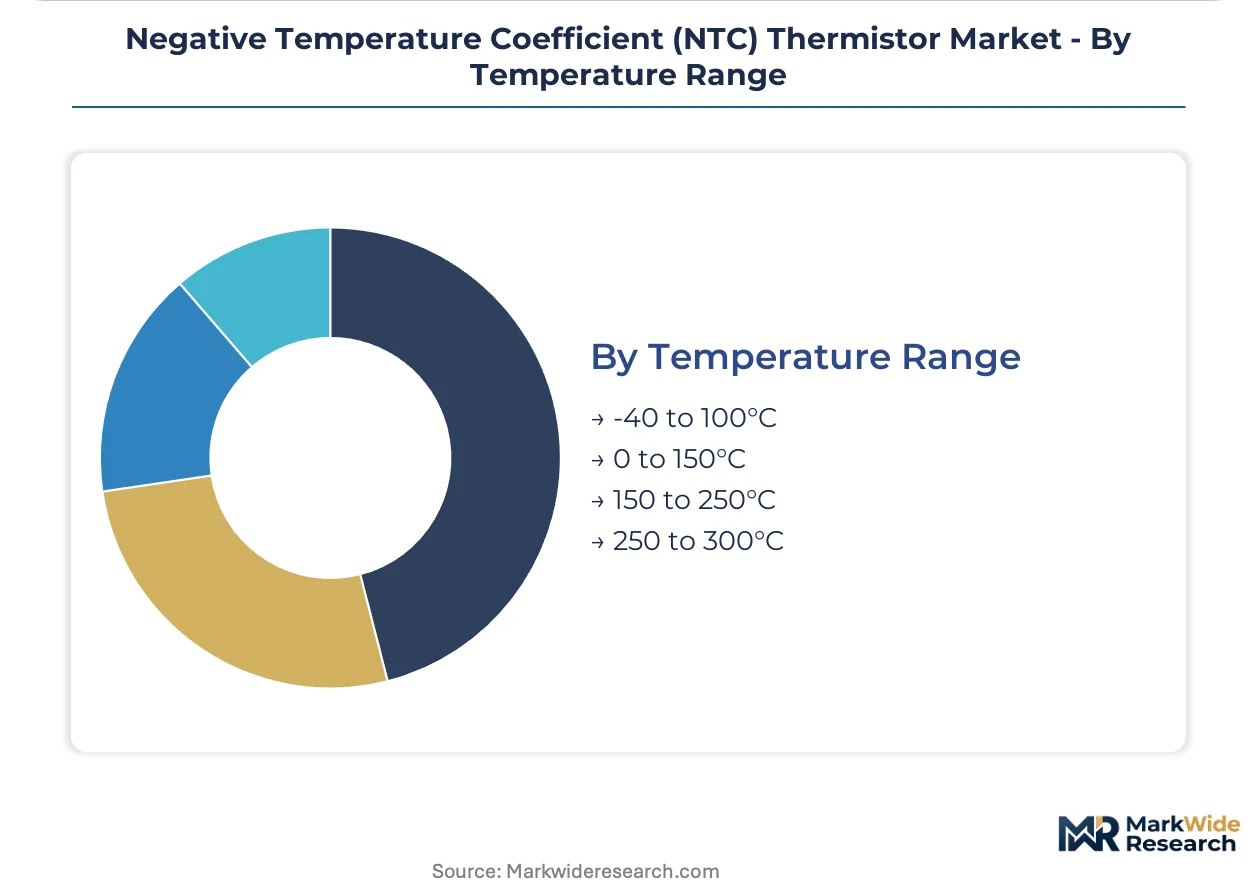
- 0 to 150°C:Standard automotive and industrial operating range covers the majority of battery management and motor drive applications. TE Connectivity and Vishay Intertechnology anchor qualification programs in this band.
- -40 to 100°C:Cold-start and consumer electronics range demands tight tolerance maintenance at temperature extremes. Aerospace applications in the US tolerate higher unit costs for linear response alternatives.
- 150 to 250°C:High-temperature automotive underhood and industrial process applications require specialized ceramic formulations. REACH nickel oxide scrutiny extends ECHA approval timelines for European-qualified products.
- 250 to 300°C:Extreme environment applications in downhole drilling and exhaust gas sensing depend on platinum electrode and glass-encapsulated constructions. Limited qualified supplier base supports premium pricing.
0 to 150°C carries the volume base; 150 to 250°C is gaining share fastest on industrial electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standard harmonization with IEC 60751 anchors China's regulatory influence over precision thermistor interchangeability requirements. The country's dual carbon goals issued through MEE are tightening thermal monitoring mandates across industrial motor drives and HVAC equipment. East Asian manufacturing clusters in South Korea and Japan concentrate procurement authority for high-accuracy probe assemblies.
China
Domestic solar inverter and EV charger manufacturing under the PLI scheme incentives is pulling demand for humidity-resistant glass-encapsulated thermistors. GB standard alignment with IEC 60751 is accelerating accuracy grade adoption among industrial equipment builders. The Yangtze River Delta and Pearl River Delta manufacturing belts are upgrading from uncalibrated suppliers to interchangeability-tolerance-qualified sources.
Germany
Automotive platform standardization committees have consolidated qualified supplier lists from twelve to four vendors per battery-electric platform. KBA enforcement of UN ECE R100 mandates is driving redundant temperature sensing arrays in traction battery thermal management. The Baden-Württemberg and Bavaria automotive clusters are specifying integrated probe-assembly-plus-connector modules.
United States
NHTSA FMVSS homologation requirements are shaping NTC thermistor reliability standards for electric vehicle battery management systems. Aerospace applications in California and Texas tolerate higher unit costs for linear temperature response alternatives. The Pacific Northwest and Greater Boston precision electronics corridors are concentrating demand for medical device probe configurations.
Japan
JIS C 1604 interchangeability tolerances determine supplier eligibility for domestic industrial and automotive markets. METI efficiency mandates are tightening thermal monitoring requirements across factory automation equipment. The Kanto and Kansai electronics manufacturing belts maintain dense precision ceramics supply chains for chip-style thermistor production.
India
Domestic solar inverter manufacturing under PLI scheme incentives is creating demand for BIS-certified glass-encapsulated thermistors in outdoor energy infrastructure. CEA grid integration standards are mandating calibrated temperature sensing for renewable energy equipment. The Maharashtra and Gujarat industrial corridors are attracting humidity-resistant thermistor qualification programs.
Negative Temperature Coefficient (NTC) Thermistor Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the NTC thermistor market. Multilayer ceramic co-firing expertise concentrates in East Asian facilities, fragmenting manufacturing capability for sub-micron electrode alignment. Three archetypes dominate: precision chip specialists, probe assembly integrators, and commodity disc manufacturers. Competitive moves center on AEC-Q200 automotive qualification programs and direct procurement relationships with battery cell manufacturers.
Among Japanese multilayer ceramic specialists, Murata Manufacturing and TDK Corporation exemplify the precision chip tier through their co-firing line investments for wearable electronics. Vishay Intertechnology anchors the automotive qualification vector with AEC-Q200 compliant portfolio positioning. TE Connectivity occupies the probe assembly integration tier, serving aerospace and industrial channels through calibrated configurations.
| Leading Market Players |
|---|
| Vishay Intertechnology |
| Murata Manufacturing |
| Mitsubishi Materials Corporation |
| Vancera Technology |
| TE Connectivity |
| TDK Corporation |
| Shibaura Electronics |
| Thinking Electronic Industrial |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between South Korean battery cell manufacturers and Japanese ceramic component suppliers lock in cobalt oxide feedstock access while stabilizing unit cost visibility for AEC-Q200 qualified probe assemblies. These contracts insulate precision thermistor producers from spot market volatility in Central African mining operations.
Pricing Analysis
Price spreads between Japanese-qualified chip thermistors and Chinese commodity disc variants reach threefold multiples, with AEC-Q200 Rev E certification and sub-micron electrode alignment driving premium tiers. Cost compression in standard-grade manganese-cobalt-nickel formulations intensifies as uncalibrated suppliers in the Yangtze River Delta expand capacity. Automotive platform committees exhibit lowest price sensitivity due to thermal runaway liability exposure, while home appliance OEMs prioritize unit economics over interchangeability tolerances.
Supply Chain Analysis
Japan and South Korea anchor multilayer ceramic co-firing capacity for sub-1.0mm chip thermistors, while China dominates manganese oxide powder processing and disc thermistor stamping operations. Electrode patterning draws from cobalt oxide refining concentrated in Chinese state-owned enterprises, creating single-source vulnerability for European-qualified formulations. Distribution runs through Tier 1 automotive thermal management suppliers who integrate probe assemblies with connector modules for German and South Korean OEM platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UN ECE R100 thermal management mandates are compressing sensor placement cycles, creating high-growth disruption as battery-electric platforms force qualification timelines to synchronize with cell manufacturing ramp rates rather than traditional component refresh schedules.
For Market Incumbents: Shield AEC-Q200 Rev E certification portfolios from platinum thin-film RTD substitution in aerospace segments by extending temperature range capabilities above 250°C through glass-encapsulated constructions. Deepen backward integration into cobalt oxide electrode formulations to offset REACH nickel oxide scrutiny and ECHA approval timeline extensions. For New Entrants and Emerging Players: Anchor in India's PLI scheme-subsidized solar inverter manufacturing corridor, where BIS certification gaps create white-space for humidity-resistant glass-encapsulated thermistors in outdoor energy infrastructure. Bypass tiered automotive hierarchies through direct procurement relationships with solid-state battery cell developers seeking specification influence. For Investors and Strategic Acquirers: Capital is best deployed toward multilayer ceramic specialists with sub-micron electrode alignment expertise concentrated in East Asian manufacturing belts, as capability scarcity in co-firing precision widens competitive moats. Monitor battery platform standardization committee decisions as the signal for which thermistor form factors secure long-term design wins across German and South Korean automotive programs.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Rev E Certification Investment | Automotive platform committees in Germany and South Korea restrict qualified supplier lists to certified vendors. |
| Backward Integration into Cobalt Oxide Processing | REACH substance restrictions and Central African supply concentration reward captive electrode material production. |
| Direct Procurement Relationships with Cell Manufacturers | LG Energy Solution and Samsung SDI consolidation creates specification influence opportunities outside tiered hierarchies. |
| Sub-Micron Co-Firing Capacity Expansion | Murata Manufacturing and TDK dominance in 0402 and 0201 case sizes limits viable competitor entry. |
| BIS Certification for Indian Solar Infrastructure | CEA grid integration standards under PLI scheme incentives mandate calibrated temperature sensing for inverter qualification. |
Methodological Framework
Initial hypotheses were tested against primary input from Tier 1 automotive thermal management procurement directors, ceramic component plant managers, and battery platform standardization engineers, then refined through secondary validation against UN ECE R100 regulatory filings, IEC 60751 interchangeability databases, and customs trade data for manganese-cobalt-nickel oxide powder shipments. Bottom-up unit economics from probe assembly bill-of-materials were triangulated with top-down market sizing from vehicle production databases and wearable electronics shipment forecasts.
Variance decomposition across the projection horizon isolates volume drivers by form factor, thermal application function, end-use qualification tier, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation with named OEM platform launch schedules and MEE efficiency mandate enforcement timelines in China's industrial motor drive sector.
Material uncertainties — cobalt oxide price volatility, ECHA nickel oxide authorization delays, and solid-state battery thermal architecture shifts — sit outside the modeled envelope. Forecasts reflect assumptions about AEC-Q200 Rev E adoption curves and GB standard harmonization velocity. Recalibration cycles align with material shifts in UN ECE regulatory amendments and battery cell manufacturer procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Arc Fault Detection Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Hitoxic Gas Detector Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Noise Monitoring Device Market