
 Wireless Gas Detection System Market | 2026-2036
Wireless Gas Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Gas Detection System Market Analysis
Certified instrumentation technician availability is bifurcating market growth between mature industrial economies and emerging manufacturing hubs. Honeywell International leverages its distributed sensor architecture to sustain channel dominance across North American chemical corridors. Drägerwerk AG & Co. KGaA anchors European demand through specialized calibration services and regulatory compliance tooling. MSA Safety competes aggressively in portable detector segments where worker mobility requirements command premium positioning.
Wireless gas detection systems combine battery-powered electrochemical, infrared, or catalytic bead sensors with mesh-network radio protocols to transmit ppm-level concentration data to centralized safety management platforms without hardwired infrastructure. Fixed detector installations dominate capital expenditure flows while portable multi-gas monitors capture the fastest replacement cycle velocity due to battery degradation and sensor drift timelines. Electrochemical technology occupies the largest installed base for toxic gas identification, though infrared sensing extends into hydrocarbon leak detection where cross-sensitivity elimination justifies higher unit costs.
OSHA permissible exposure limit enforcement and EPA Risk Management Plan amendments shape product certification requirements and procurement specifications across United States industrial facilities. The EU ATEX directive and IECEx certification schemes govern equipment approval for explosive atmosphere deployment, creating compliance moats for pre-qualified suppliers. Stakeholders must monitor evolving hydrogen economy infrastructure codes as fuel cell and ammonia supply chain buildouts introduce novel leak detection protocols and sensor calibration standards.
Market Dynamics
Mesh-network radio protocols are collapsing installation cost barriers for hazardous environment monitoring, enabling rapid sensor deployment without conduit trenching or cable tray infrastructure across chemical corridors.
Growth Catalysts
- OSHA Process Safety Management:Enforcement of 29 CFR 1910.119 mandates continuous monitoring in high-hazard chemical processes, compelling facility upgrades to wireless architectures that bypass legacy wiring constraints.
- Battery chemistry advances:Lithium-thionyl chloride cells now deliver 5-year lifespans in Class I Division 1 enclosures, eliminating the maintenance burden that previously discouraged wireless adoption in remote process units.
- Gulf Coast petrochemical buildout:Texas and Louisiana refinery expansions concentrate demand for scalable detection networks that accommodate brownfield retrofit constraints.
Market Restraints
- Sensor drift calibration cycles:Electrochemical cells require 6-month validation intervals that offset wireless labor savings with recurring technician visits.
- Semiconductor supply concentration:RF transceiver chip fabrication concentrates in Taiwan, exposing lead time volatility for mesh-network hardware procurement.
- Infrared unit cost premiums:Photoacoustic sensing packages cost 3-4x electrochemical equivalents, limiting penetration beyond hydrocarbon leak detection applications.
Strategic Opportunities
- Hydrogen economy infrastructure codes:ASME B31.12 and NFPA 2 amendments for fuel cell supply chains create first-mover advantage for hydrogen-specific sensor calibration protocols.
- Portable monitor aftermarket services:Unbundled sensor replacement and cloud-based drift tracking transform single-unit sales into recurring revenue streams.
- 5G private network integration:Ultra-reliable low-latency communication overlays enable deterministic alarm transmission that satisfies safety instrumented system requirements.
Industry Challenges
- IECEx certification timeline compression:Equipment qualification for explosive atmospheres averages 14-18 months, delaying product launch windows behind technology refresh cycles.
- Legacy 4-20mA integration:Hardwired control system architectures in existing plants resist wireless gateway adoption without expensive distributed control system reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Gas Detection System Market |
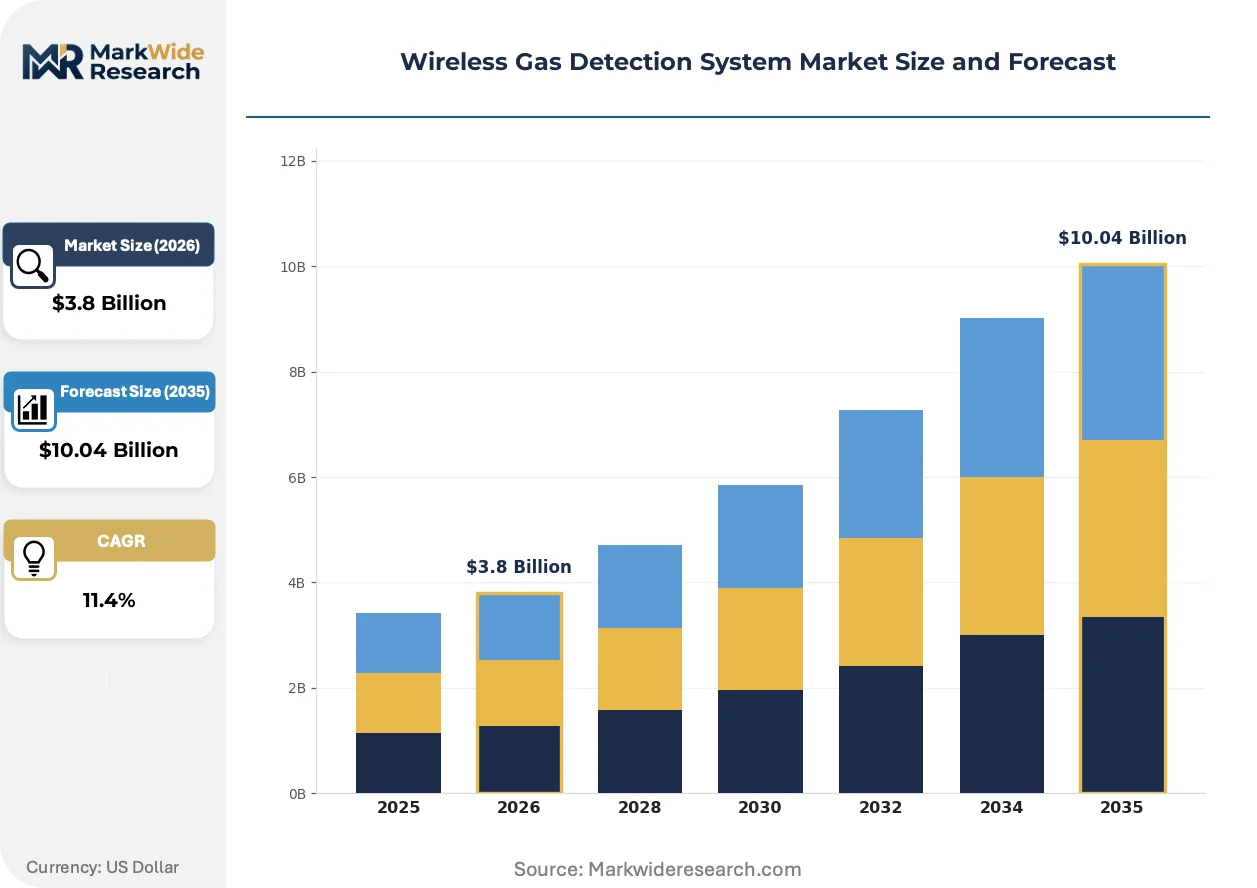
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Multi-Gas Monitors, Single-Gas Monitors Technology: Chemical Sensors, Infrared Sensors, Ultrasonic Sensors, Electrochemical Sensors Application: Industrial Safety, Environmental Monitoring, Oil & Gas Exploration, Mining Operations End User: Manufacturing Facilities, Construction Sites, Chemical Plants, Utilities |
| Companies Covered | Honeywell International, Drägerwerk AG & Co. KGaA, MSA Safety, Siemens AG, Emerson, Industrial Scientific, Yokogawa Electric Corporation, RAE Systems, Pem-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Gas Detection System Market Emerging Trajectories
Digital twin integration is compressing commissioning timelines for hazardous area sensor networks, while regulatory mandates accelerate hardware refresh cycles beyond traditional depreciation schedules.
Edge computing architectures are decomposing centralized safety system dependencies by embedding ppm threshold logic directly within battery-powered detector housings. Offshore platform operators in the North Sea deploy these autonomous units to eliminate single points of failure from cable runs across modular process skids. The shift is decomposing traditional safety instrumented system hierarchies into distributed decision nodes.
EPA Risk Management Plan amendments now mandate root cause analysis for alarm exceedances, forcing facilities to timestamp concentration data with GPS coordinates and meteorological conditions. Chemical plants in Texas and Louisiana respond by specifying wireless systems with embedded environmental sensors and blockchain-anchored audit trails. The compliance burden elevates data integrity specifications above raw detection sensitivity in procurement criteria.
Buyer consolidation among integrated supermajors is compressing vendor qualification lists to pre-approved frameworks that bundle detection hardware with calibration service contracts. Procurement teams at ExxonMobil and Shell facilities now demand 10-year total cost of ownership guarantees that internalize sensor replacement and firmware update obligations. This contractual shift disadvantages pure hardware manufacturers lacking field service infrastructure across the Gulf Coast chemical corridor.
Wireless Gas Detection System Market Segmentation
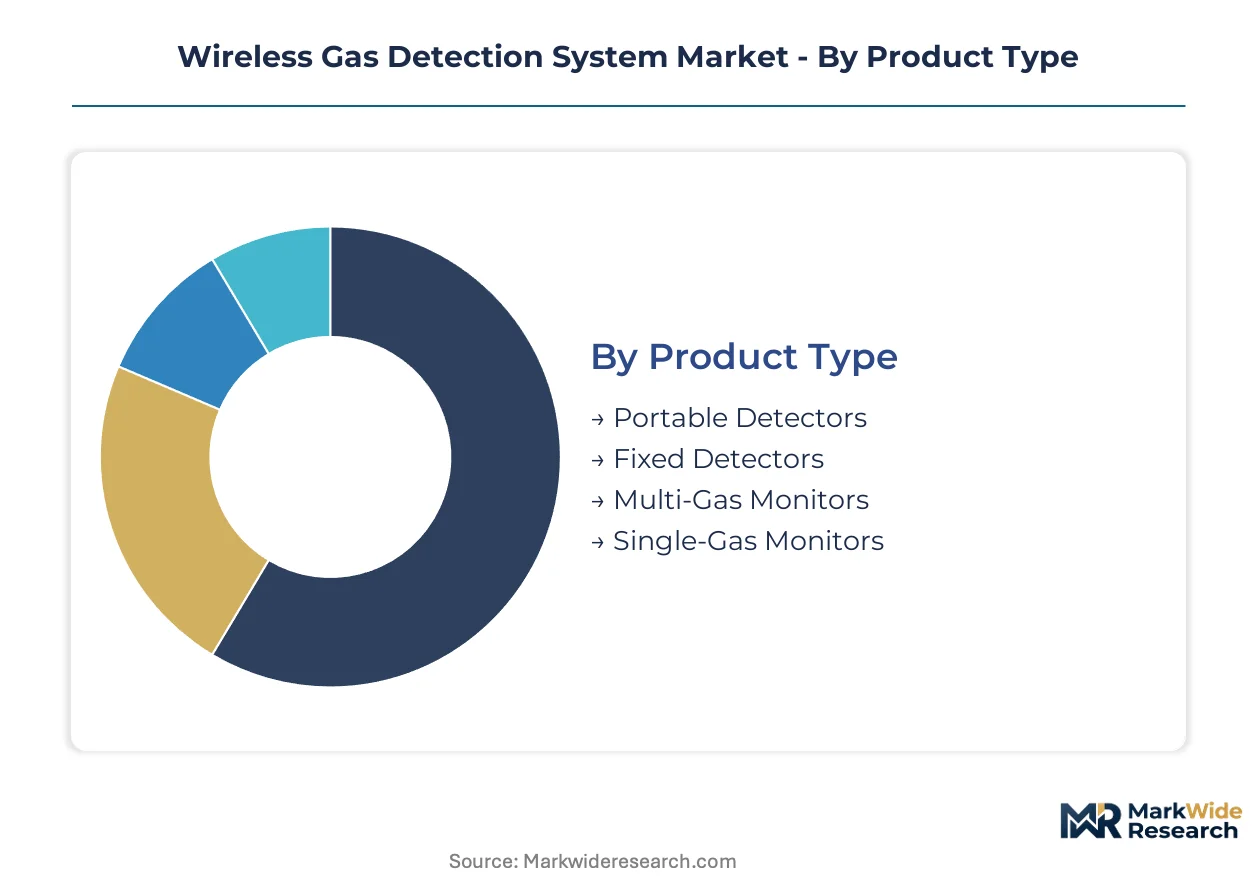
Wireless gas detection systems fragment across four dimensions that shape procurement specifications and compliance pathways. Product type determines installation topology and battery architecture. Technology selection governs cross-sensitivity performance and calibration intervals. Application context dictates enclosure ratings and mesh-network range requirements. End-user concentration in chemical corridors creates regional demand clusters with distinct service expectations.
Product Type:
OSHA 29 CFR 1910.119 enforcement differentiates fixed installations from portable deployments through continuous monitoring mandates versus personal protective equipment classifications.
- Fixed Detectors:Wall-mounted or pole-mounted units with lithium-thionyl chloride power systems deliver 5-year maintenance-free operation in Class I Division 1 zones. Gulf Coast petrochemical expansions in Texas and Louisiana concentrate capital expenditure here, driven by brownfield retrofit constraints where conduit trenching costs exceed wireless hardware premiums.
- Portable Detectors:Handheld multi-gas units with rechargeable lithium-ion packs serve confined space entry protocols and turnaround maintenance crews. These command the steepest replacement cycle velocity as battery degradation and sensor drift timelines compress refresh intervals to 18-24 months.
- Multi-Gas Monitors:Simultaneous detection of combustible gases, oxygen deficiency, and toxic species (H2S, CO, SO2) through integrated sensor arrays.
- Single-Gas Monitors:Dedicated hydrogen sulfide or carbon monoxide detection for specialty contractor fleets with narrow exposure profiles.
Established volume favors fixed installations; emerging adoption favors portable multi-gas configurations.
Technology:
Cost tier stratification separates commodity electrochemical platforms from premium infrared architectures with 3-4x unit cost multiples.
- Electrochemical Sensors:Amperometric cells with liquid electrolyte matrices dominate toxic gas identification for H2S, CO, and chlorine. Chemical plants in the United States anchor demand here, though 6-month calibration cycles offset wireless labor savings with recurring technician visits.
- Infrared Sensors:Non-dispersive infrared or photoacoustic detection eliminates cross-sensitivity for hydrocarbon leak monitoring. Oil and gas exploration applications justify higher unit costs where methane and propane quantification accuracy prevents false evacuation triggers.
- Chemical Sensors:Metal oxide semiconductor films for broad-spectrum combustible gas detection at reduced specificity.
- Ultrasonic Sensors:Acoustic leak detection for pressurized gas systems where point-source concentration measurement proves impractical.
Electrochemical platforms dominate installed base economics; infrared architectures gain share fastest in hydrocarbon-intensive applications.
Application:
Customer type maturity separates safety-critical industrial mandates from environmental compliance monitoring with divergent data retention requirements.
- Industrial Safety:Process hazard analysis and safety instrumented system integration for high-consequence chemical releases. United States refineries drive specification complexity here, with EPA Risk Management Plan amendments demanding GPS-timestamped concentration records and blockchain-anchored audit trails.
- Oil & Gas Exploration:Offshore platform and shale patch deployment where mesh-network redundancy eliminates single points of failure across modular process skids.
- Environmental Monitoring:Fenceline and community air quality surveillance with meteorological correlation for regulatory reporting.
- Mining Operations:Underground methane and carbon monoxide detection with intrinsic safety certification for gassy coal seams.
Industrial safety commands premium positioning; environmental monitoring applications expand most quickly under tightening air quality enforcement.
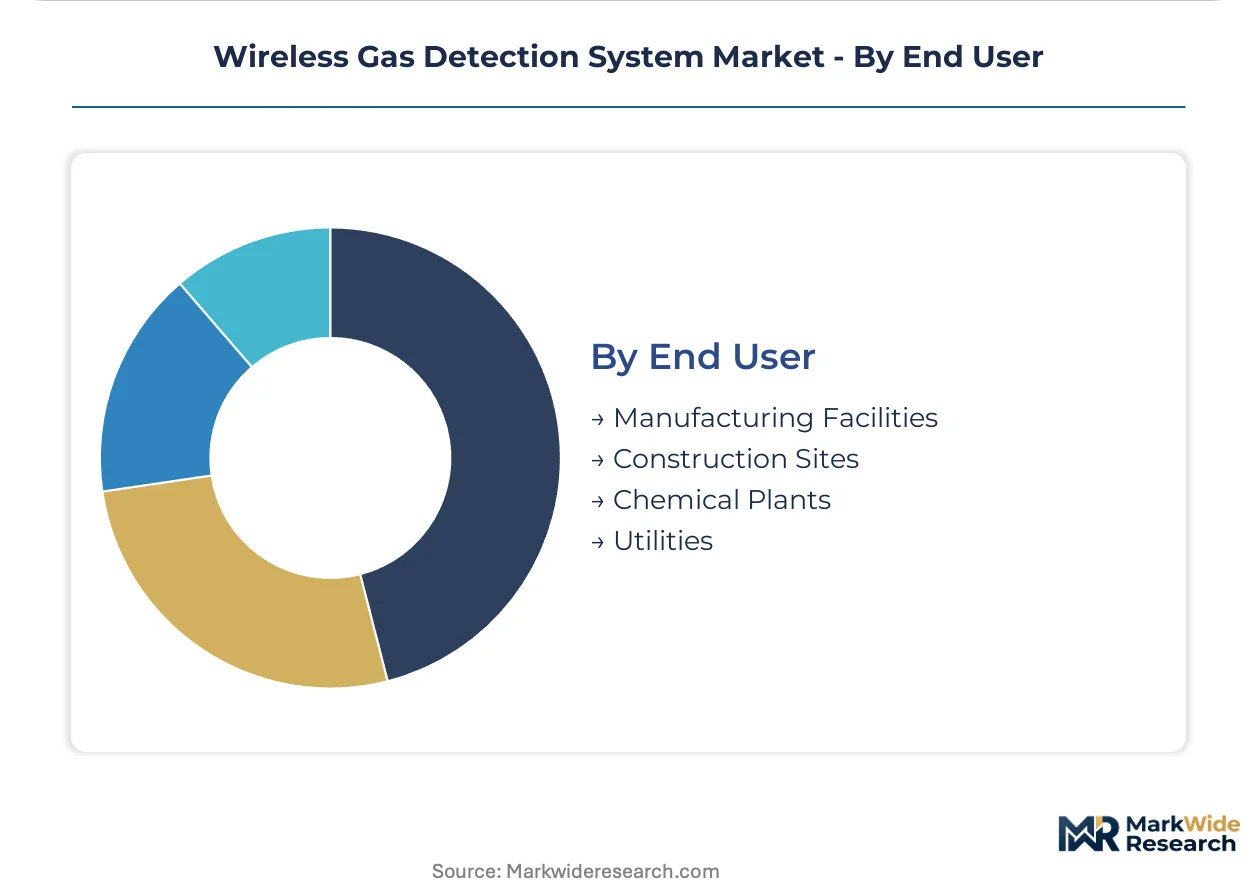
End User:
Supply concentration in Gulf Coast chemical corridors concentrates vendor qualification and service infrastructure investment.
- Chemical Plants:High-hazard process units with OSHA PSM coverage and ammonia, chlorine, or phosgene inventories. Texas and Louisiana facility counts drive procurement scale and 10-year total cost of ownership contracting frameworks.
- Manufacturing Facilities:Semiconductor fabrication and battery cell production with exotic gas detection requirements for silane, arsine, or phosphine.
- Utilities:Natural gas distribution and power generation with hydrogen sulfide monitoring for odorant verification.
- Construction Sites:Temporary deployment for excavation and tunneling projects with rental-based procurement models.
Chemical plants anchor vendor service infrastructure; manufacturing facilities represent the fastest-climbing adoption trajectory for exotic gas detection protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wireless gas detection consumption patterns diverge sharply by geography: United States facilities prioritize fixed-installation networks for OSHA compliance, while European adopters emphasize portable multi-gas units for ATEX-certified worker mobility.
United States
Gulf Coast petrochemical corridors in Texas and Louisiana anchor capital deployment, where brownfield retrofit constraints favor mesh-network architectures over conduit trenching. OSHA 29 CFR 1910.119 enforcement mandates continuous monitoring for high-hazard chemical processes. Houston and Lake Charles facility expansions concentrate procurement scale for 10-year total cost of ownership contracting.
Germany
Ruhr industrial basin chemical complexes drive demand for IECEx-certified fixed detectors with embedded edge-computing capabilities. EU ATEX directive compliance creates qualification moats for pre-approved equipment suppliers. BASF and Bayer legacy sites in Ludwigshafen and Leverkusen accelerate wireless gateway adoption to bypass legacy 4-20mA control system dependencies.
China
Yangtze River Delta petrochemical zones in Shanghai and Ningbo deploy photoacoustic infrared sensors for methane leak detection where cross-sensitivity elimination justifies premium unit costs. MIIT industrial safety standards tighten certification requirements for explosive atmosphere equipment. Sinopec refining expansions in Zhejiang province concentrate procurement for scalable detection networks.
Saudi Arabia
Eastern Province hydrocarbon processing complexes at Jubail and Yanbu industrial cities anchor Middle East demand for battery-powered electrochemical sensors in Class I Division 1 enclosures. Saudi Aramco safety specifications mandate GPS-timestamped concentration data for root cause analysis compliance. NEOM giga-project construction introduces rental-based portable monitor procurement for temporary excavation protocols.
India
Gujarat chemical corridor facilities in Vadodara and Ankleshwar adopt wireless architectures to circumvent hardwired infrastructure gaps in aging process units. BIS certification timelines for hazardous area equipment average 12-16 months, compressing vendor qualification windows. Reliance Industries Jamnagar refinery expansions specify multi-gas monitors with 5-year lithium-thionyl chloride battery lifespans.
Wireless Gas Detection System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding procurement frameworks that bundle hardware with decade-long service obligations. The middle tier fragments across regional calibration service providers and portable detector specialists. Three archetypes dominate: full-stack safety system integrators, portable equipment pure-plays, and component-focused sensor technology suppliers. Competitive moves concentrate on backward integration into battery chemistry and RF transceiver sourcing, plus geographic expansion through distributor network acquisition.
Within the integrated safety systems tier, Honeywell International and Siemens AG exemplify full-stack positioning that spans fixed-installation hardware through cloud-based safety management platforms. Drägerwerk AG & Co. KGaA anchors the European specialist segment with calibration service infrastructure. MSA Safety occupies the portable detector premium tier where worker mobility requirements command replacement cycle velocity. These three represent distinct competitive vectors: scale-driven platform bundling, regional service depth, and premium portable specialization.
| Leading Market Players |
|---|
| Honeywell International |
| Drägerwerk AG & Co. KGaA |
| MSA Safety |
| Siemens AG |
| Emerson |
| Industrial Scientific |
| Yokogawa Electric Corporation |
| RAE Systems |
| Pem-Tech |
| Others |
Supply Flow & Price Mechanics
Fourteen-month lead times for IECEx-certified RF transceiver modules concentrate pricing power with pre-qualified suppliers while compressing margins for second-tier assemblers competing on undifferentiated electrochemical sensor hardware. Inventory buffers above 90 days of semiconductor components separate vendors capable of 10-year total cost of ownership contracting from spot-market dependent competitors.
Pricing Analysis
Long-term service bundling contracts dominate procurement frameworks across Gulf Coast chemical corridors, with ExxonMobil and Shell facilities demanding decade-spanning agreements that internalize calibration labor and sensor replacement costs. Price differentiation rests on ATEX certification tier and embedded edge-computing capability, with infrared-equipped units commanding substantial premiums over electrochemical equivalents. Cost compression in portable detector segments is intensifying as battery degradation timelines compress replacement cycles and erode hardware margins. Turnaround maintenance contractors exhibit highest price sensitivity, while integrated supermajors prioritize total lifecycle guarantees over unit economics.
Supply Chain Analysis
Port congestion on the Shanghai-Ningbo corridor and container availability constraints on transpacific lanes elevate inbound logistics costs for mesh-network hardware sourced from Yangtze River Delta manufacturing zones. RF transceiver chip fabrication concentrates in Taiwan, with lithium-thionyl chloride cell production anchored in Japan and South Korea, creating single-source vulnerability for Class I Division 1 battery architectures. Semiconductor supply concentration exposes lead time volatility that ripples through procurement schedules. Distribution runs through authorized distributor networks with certified technician training obligations rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless gas detection sits in early-cycle expansion as hydrogen economy infrastructure codes create first-mover calibration protocol opportunities ahead of fuel cell supply chain buildouts. OSHA enforcement tightening and EPA Risk Management Plan amendments accelerate hardware refresh velocities beyond traditional depreciation schedules.
For Market Incumbents: Fortify Gulf Coast service infrastructure against emerging portable-detector pure-plays by embedding calibration technician networks within 50-mile radii of Texas and Louisiana chemical corridors. Deepen backward integration into lithium-thionyl chloride cell sourcing to secure five-year maintenance-free operation guarantees that anchor 10-year contracting frameworks. Pre-empt hydrogen-specific sensor protocols through early engagement with ASME B31.12 code committees.
For New Entrants and Emerging Players: Aftermarket calibration service gaps in India's Gujarat chemical corridor expose penetrable white-space where BIS certification timelines compress incumbent response windows. Target construction-site rental procurement for NEOM-scale giga-projects where temporary deployment models bypass long-term vendor qualification barriers. Lead with cloud-based drift tracking platforms that transform hardware sales into recurring revenue streams absent in legacy supplier portfolios.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive safety divisions lacking standalone scale to service 10-year total cost of ownership mandates. Five-to-ten year viability hinges on hydrogen economy code adoption velocity. Monitor IECEx certification queue lengths as inflection indicator: compression below 12 months signals technology refresh cycle acceleration that favors agile specialists over bureaucratic incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Embedded technician presence within 50 miles of Texas and Louisiana chemical corridors satisfies 10-year contracting demands from ExxonMobil and Shell procurement teams. |
| Hydrogen-Specific Sensor Protocol Development | Early ASME B31.12 and NFPA 2 code engagement creates first-mover advantage for fuel cell supply chain leak detection standards. |
| Cloud-Based Drift Tracking Platform Launch | Recurring revenue transformation of portable monitor sales offsets 18-24 month replacement cycle compression in turnaround maintenance segments. |
| Backward Integration into Battery Chemistry | Captive lithium-thionyl chloride supply secures five-year maintenance-free operation guarantees for Class I Division 1 wireless deployments. |
| 5G Private Network Certification | Ultra-reliable low-latency communication overlays enable deterministic alarm transmission that satisfies safety instrumented system requirements. |
Methodological Framework
Desk research of IECEx certification databases, OSHA enforcement records, and EPA Risk Management Plan amendment filings preceded structured interviews with plant safety managers, instrumentation procurement leads at integrated supermajors, certified calibration service technicians, and wireless sensor network integration specialists. Primary fieldwork across Texas, Louisiana, and Ruhr industrial basin facilities combined with secondary validation through customs trade data and chemical industry association reports. Bottom-up unit economics modeling triangulated against top-down capital expenditure tracking across Gulf Coast petrochemical expansions.
Variance decomposition across technology segments, product architectures, and end-user concentration zones shaped the analytical framework over the projection horizon. Segmentation dimensions spanned fixed versus portable installation topology, electrochemical versus infrared sensing modality, and chemical plant versus oil and gas exploration application context. CAGRs derived from replacement cycle velocity analysis and brownfield retrofit constraint modeling. Hydrogen economy infrastructure code evolution and semiconductor supply concentration served as industry-specific forecast sensitivity inputs.
Forecasts assume regulatory continuity in OSHA process safety enforcement and EPA air quality mandates; material policy shifts would require re-modeling. Sensor drift calibration cycle compression or IECEx timeline extension represent specific risk factors that could revise adoption trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global Surge Protection Devices Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Electronic Article Surveillance Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Neutron Detector Market
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market
Detection and Regulation Devices
Arc Fault Detection Market
Detection and Regulation Devices
Global Gas Sensors Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
Active Buzzer Market
Detection and Regulation Devices
Digital Attenuators Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market