
 Volatile Organic Compound (VOC) Detector Market | 2026-2036
Volatile Organic Compound (VOC) Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Volatile Organic Compound (VOC) Detector Market Analytics
Capital-intensity divergence between photon-counting sensor fabricators and assembly-only OEMs is unwinding the traditional competitive map. Honeywell International Inc. leverages captive semiconductor foundry relationships to sustain margin on fixed-installation detectors. Riken Keiki Co., Ltd. anchors its position through JIS-certified calibration protocols that dominate Asia-Pacific tender requirements.
A volatile organic compound detector quantifies airborne hydrocarbons, halogenated solvents, and oxygenated species through photoionization or electrochemical transduction, typically resolving concentrations from parts-per-billion to percent-level thresholds for compliance and safety intervention. Portable detectors command the largest shipment volumes due to OSHA and EPA mandate-driven plant walkthrough protocols, while benchtop configurations retain the highest margin pools in third-party environmental laboratory accreditation chains. Metal oxide sensors are displacing legacy electrochemical architectures in battery-operated units where power budget and form factor constrain design.
EPA NESHAP standards for hazardous air pollutants and EU Industrial Emissions Directive enforceable limits are mandating continuous perimeter monitoring at petrochemical and coating operations, directly expanding the installed base of fixed detectors. China's MEE ambient VOC control scheme and Japan's METI chemical management framework are tightening cross-border product certification requirements. Stakeholders must calibrate R&D roadmaps against evolving photoionization lamp duty-cycle specifications and emerging electrochemical polymer electrolyte stability thresholds.
Market Dynamics
Photoionization lamp duty-cycle specifications and electrochemical polymer electrolyte stability thresholds are forcing simultaneous recalibration of R&D roadmaps and manufacturing tolerances across detector fabricators.
Growth Catalysts
- EPA NESHAP hazardous air pollutant standards:These mandates enforce continuous perimeter monitoring at petrochemical and coating operations, directly expanding fixed detector installations.
- China's MEE ambient VOC control scheme:Cross-border product certification requirements are tightening, accelerating procurement from compliant suppliers.
- Metal oxide sensor architectures:These designs are capturing share in battery-operated units where power budget and form factor constraints dominate.
Market Restraints
- Semiconductor foundry concentration:Captive relationships with Asian foundries create supply vulnerability for photon-counting sensor fabricators.
- Calibration protocol fragmentation:JIS-certified requirements in Asia-Pacific, EPA methods in the United States, and EU Industrial Emissions Directive specifications force redundant testing.
- Photoionization lamp degradation:Ultraviolet source lifetime limitations impose recurring maintenance costs and downtime.
Strategic Opportunities
- Third-party environmental laboratory accreditation chains:Benchtop configurations serving these networks retain premium margin pools.
- Japan's METI chemical management framework:Evolving substance tracking requirements create demand for higher-sensitivity detection thresholds.
- Convergence of electrochemical and optical transduction:Hybrid architectures promise expanded analyte coverage in single-instrument platforms.
Industry Challenges
- Polymer electrolyte stability expertise:Electrochemical engineering talent scarcity constrains development timelines for next-generation sensors.
- Multi-jurisdiction certification sequencing:Parallel approval processes for EPA, EU Industrial Emissions Directive, and MEE compliance extend time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volatile Organic Compound (VOC) Detector Market |
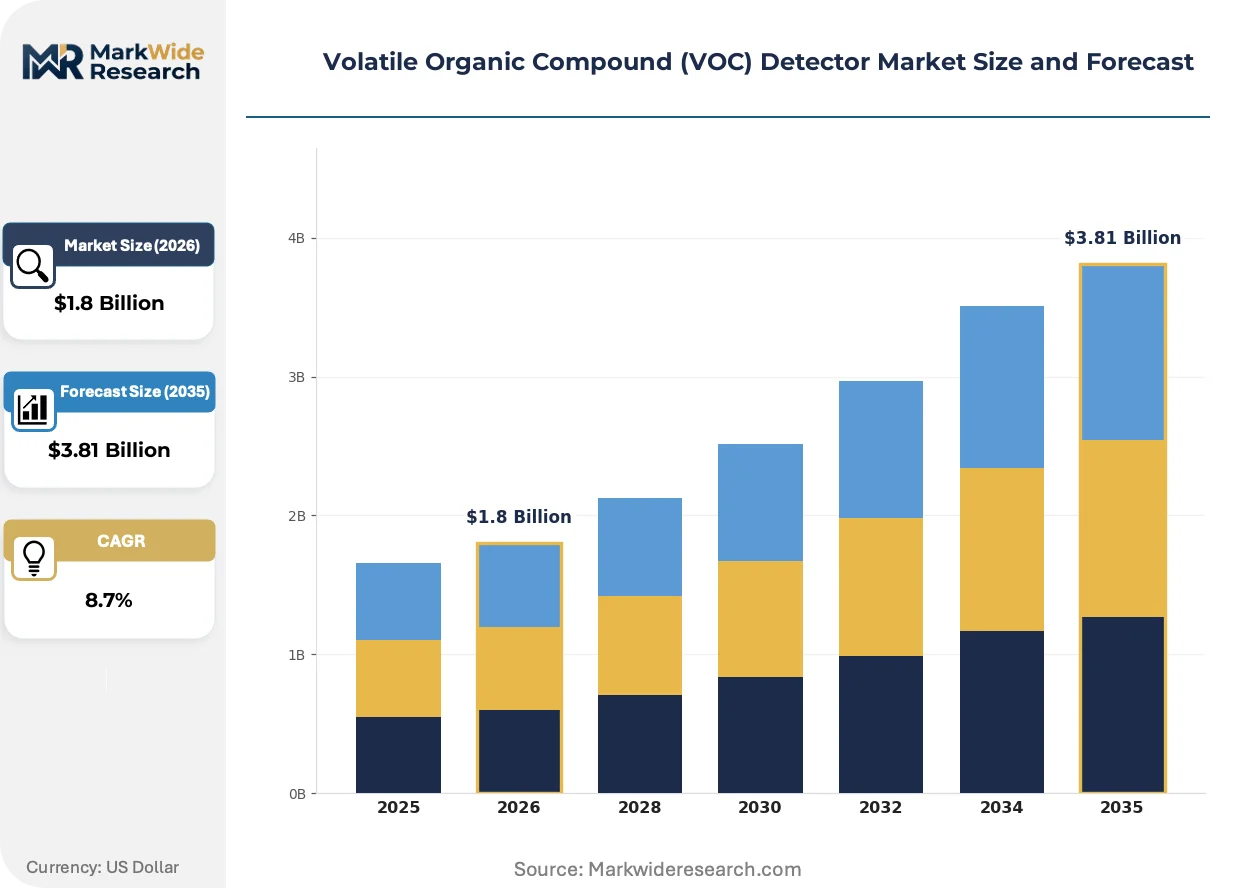
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Battery-Operated Detectors, Benchtop Detectors Technology: Photoionization Detection, Electrochemical Sensors, Metal Oxide Sensors, Flame Ionization Detection Application: Industrial Safety, Environmental Monitoring, Indoor Air Quality, Research Laboratories End User: Manufacturing Facilities, Hospitals, Educational Institutions, Government Agencies |
| Companies Covered | Ion Science Ltd., Alphasense Ltd., Honeywell International Inc., Global Detection Systems Corp., Riken Keiki Co., Ltd., Sensirion AG, Aeroqual Limited, Siemens AG, Bosch Sensortec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volatile Organic Compound (VOC) Detector Market Evolving Landscape
Detector architecture is splitting between high-performance fixed installations and power-optimized portable units, with sensor modality selection increasingly dictated by deployment context rather than universal performance benchmarks.
Photoionization detection is bifurcating between 10.6 eV lamp configurations for general hydrocarbon screening and 11.7 eV variants for halogenated species resolution. Refinery operators are specifying 11.7 eV systems for benzene-specific monitoring while coating facilities standardize on 10.6 eV units. This technical segmentation is bifurcating supplier qualification lists and fragmenting procurement pools.
REACH substance restriction amendments are expanding the catalog of VOCs requiring workplace monitoring beyond traditional solvents to include siloxanes and fluorinated compounds. German chemical manufacturers are retrofitting fixed detector networks to capture these species. The compliance burden falls heaviest on semiconductor fabrication and electronics assembly operations with complex chemical inventories.
Service contract unbundling is separating hardware procurement from calibration and data management. Petrochemical operators in Texas and Louisiana are negotiating direct relationships with accredited calibration laboratories, bypassing OEM service arms. This disintermediation compresses recurring revenue for detector manufacturers while expanding third-party service provider margins.
Volatile Organic Compound (VOC) Detector Market Segmentation
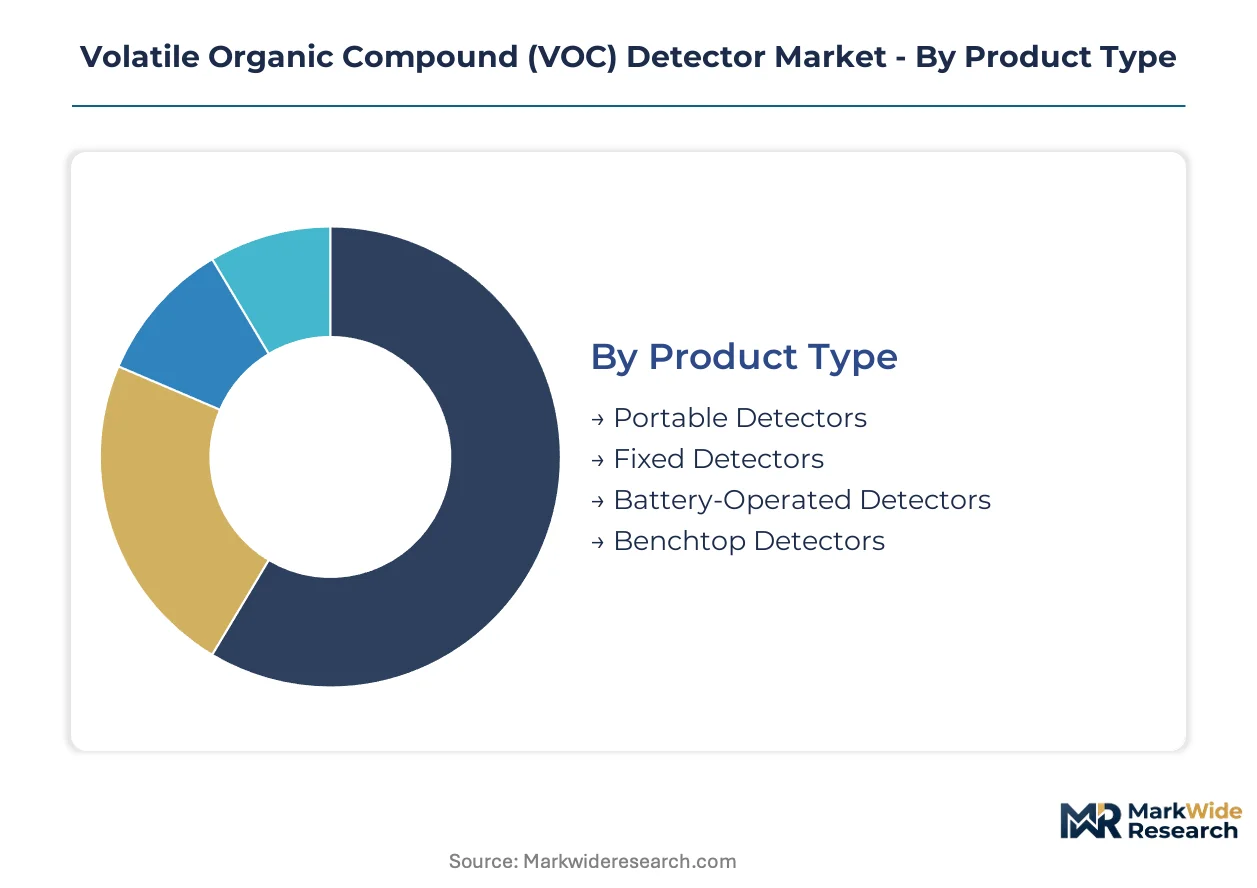
VOC detector procurement splits sharply between compliance-driven bulk purchases and premium laboratory instrumentation. Margin distribution follows deployment durability and certification burden rather than raw unit economics.
Product Type:
Margin pools concentrate in benchtop configurations where laboratory accreditation requirements sustain premium pricing, while portable units dominate shipment volumes through OSHA-mandated plant walkthrough protocols.
- Portable Detectors:Handheld units resolve concentrations from parts-per-billion to percent-level thresholds through photoionization or electrochemical transduction. Demand clusters in Texas and Louisiana petrochemical corridors where EPA NESHAP mandates drive replacement cycles for plant safety officers.
- Fixed Detectors:Continuous perimeter monitoring installations enforce regulatory compliance at coating operations and refinery boundaries. Germany's Industrial Emissions Directive enforcement is accelerating retrofit demand from Rhine-Ruhr chemical manufacturers.
- Battery-Operated Detectors:Metal oxide sensor architectures are displacing legacy electrochemical designs where power budgets constrain field deployment.
- Benchtop Detectors:Third-party environmental laboratory accreditation chains retain the highest margin pools through precision calibration requirements.
Fixed detectors hold installed capacity. Battery-operated units are rotating up the share rankings.
Technology:
Technology selection increasingly tracks deployment context rather than universal performance benchmarks, with photoionization dominating field applications and electrochemical retaining laboratory precision markets.
- Photoionization Detection:Ultraviolet lamp configurations at 10.6 eV and 11.7 eV ionization energies differentiate hydrocarbon screening from halogenated species resolution. Refinery operators in the United States specify 11.7 eV systems for benzene-specific monitoring while coating facilities standardize on 10.6 eV units.
- Metal Oxide Sensors:Semiconductor-based transduction elements capture market share in portable and battery-operated units where form factor and power consumption dominate design constraints. China's MEE ambient VOC control scheme is tightening certification requirements for these architectures.
- Electrochemical Sensors:Polymer electrolyte stability thresholds constrain development timelines for next-generation units targeting lower detection limits.
- Flame Ionization Detection:Combustion-based measurement retains position in stationary laboratory settings requiring absolute quantification of total hydrocarbon content.
Photoionization detection holds installed capacity. Metal oxide sensors are rotating up the share rankings.
Application:
Application segmentation reflects regulatory enforcement intensity, with industrial safety commanding the largest procurement volumes and research laboratories sustaining premium pricing through precision requirements.
- Industrial Safety:Workplace exposure limit compliance drives continuous monitoring at manufacturing facilities. OSHA permissible exposure limits and EPA hazardous air pollutant standards mandate detector deployment across petrochemical, coating, and electronics assembly operations.
- Environmental Monitoring:Perimeter and ambient air quality surveillance enforces emissions standards. Germany's Federal Immission Control Act and China's MEE regulations are expanding continuous monitoring requirements.
- Indoor Air Quality:Commercial building ventilation control and occupant health protection drive demand in healthcare and educational settings.
- Research Laboratories:Method development and substance identification applications require highest sensitivity thresholds and multi-analyte coverage.
Industrial safety holds installed capacity. Environmental monitoring is rotating up the share rankings.
End User:
End user segmentation tracks regulatory exposure and capital availability, with manufacturing facilities absorbing volume procurement and government agencies setting certification standards that shape supplier qualification.
- Manufacturing Facilities:Petrochemical, semiconductor fabrication, and electronics assembly operations with complex chemical inventories face the heaviest compliance burden from REACH substance restriction amendments. German chemical manufacturers are retrofitting fixed detector networks to capture siloxanes and fluorinated compounds.
- Government Agencies:Environmental enforcement bodies and occupational safety regulators specify equipment standards that cascade through procurement requirements. EPA method certifications and JIS calibration protocols in Japan create qualification barriers.
- Hospitals:Indoor air quality and anesthetic gas monitoring applications drive specialized detector configurations.
- Educational Institutions:Research and teaching laboratory safety budgets constrain procurement toward portable and benchtop units.
Manufacturing facilities hold installed capacity. Government agencies are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German calibration-certified benchtop units while Chinese metal oxide sensor fabricators compete on volume procurement contracts. Enforcement intensity across three regulatory jurisdictions is redrawing procurement geography. The Rhine-Ruhr corridor, Texas Gulf Coast, and Yangtze River Delta now anchor detector deployment velocity.
United States
EPA NESHAP hazardous air pollutant standards mandate continuous perimeter monitoring at petrochemical and coating operations. OSHA permissible exposure limits drive portable detector replacement cycles for plant safety officers. The Texas and Louisiana Gulf Coast corridor dominates fixed installation demand from refinery and chemical manufacturing clusters.
Germany
REACH substance restriction amendments are expanding workplace monitoring requirements to siloxanes and fluorinated compounds. The Federal Immission Control Act enforces emissions limits that accelerate fixed detector retrofits. Rhine-Ruhr chemical manufacturers are upgrading networks to capture complex chemical inventories from semiconductor fabrication operations.
China
MEE ambient VOC control scheme tightening is cross-border certification requirements for metal oxide sensor architectures. Dual carbon goals pressure manufacturing facilities toward continuous emissions monitoring. The Yangtze River Delta and Pearl River Delta industrial clusters absorb bulk procurement for environmental compliance infrastructure.
Japan
METI chemical management framework evolution creates demand for higher-sensitivity detection thresholds. JIS-certified calibration protocols dominate Asia-Pacific tender requirements and create qualification barriers for non-compliant suppliers. The Kanto and Kansai industrial corridors concentrate procurement from electronics assembly and precision chemical operations.
Volatile Organic Compound (VOC) Detector Market Competitive Landscape
Concentration sits with diversified industrial conglomerates controlling captive semiconductor foundry relationships and captive calibration laboratory networks. The vendor base spans three strategic tiers: integrated technology conglomerates with in-house sensor fabrication, specialized detector OEMs relying on outsourced transduction elements, and third-party calibration service providers unbundling from hardware procurement. Dominant competitive moves include backward integration into photon-counting sensor production and geographic expansion through JIS or EPA certification acquisition.
Within the integrated technology tier, Honeywell International Inc. and Siemens AG exemplify scale-driven positioning through diversified safety and automation portfolios. Among Asia-Pacific specialists, Riken Keiki Co., Ltd. anchors regional qualification requirements through calibration protocol dominance. Sensirion AG represents the precision sensor archetype with Swiss-based semiconductor fabrication heritage.
| Leading Market Players |
|---|
| Ion Science Ltd. |
| Alphasense Ltd. |
| Honeywell International Inc. |
| Global Detection Systems Corp. |
| Riken Keiki Co., Ltd. |
| Sensirion AG |
| Aeroqual Limited |
| Siemens AG |
| Bosch Sensortec GmbH |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day lead times for ultraviolet lamp assemblies from German suppliers compress margin flexibility for detector OEMs while amplifying pricing power among captive foundry operators. This inventory pressure concentrates procurement leverage with Honeywell and Siemens, who buffer supply volatility through in-house photon-counting sensor fabrication.
Pricing Analysis
The customization-premium spread widens to three-to-five multiples between JIS-certified benchtop configurations and standard portable units. Pricing stratifies across premium laboratory accreditation tiers, mid-tier fixed installation contracts, and economy portable walkthrough devices. Cost compression in battery-operated metal oxide sensor tiers intensifies because Chinese fabricators compete on volume procurement for MEE compliance infrastructure. Government agencies and third-party calibration laboratories exhibit lowest price sensitivity, while educational institutions and small coating operations absorb the tightest budget constraints.
Supply Chain Analysis
Japan and Germany anchor precision photoionization lamp manufacturing, while China dominates metal oxide semiconductor wafer output for cost-optimized portable units. The supply chain draws from borosilicate glass envelopes, noble gas fill mixtures, and polymer electrolyte membranes. Single-source vulnerability concentrates in 11.7 eV lamp architectures where two German suppliers qualify for refinery benzene monitoring specifications. Distribution runs through direct OEM channels for fixed installations and industrial distribution partnerships for portable unit volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal oxide sensor displacement of electrochemical architectures constitutes a high-growth disruption, with China's MEE enforcement tightening cross-border certification requirements that favor compliant suppliers.
For Market Incumbents: Secure captive calibration laboratory networks before third-party service unbundling accelerates. Deepen backward integration into photon-counting sensor production to defend margin against assembly-only competitors. Acquire JIS certification capabilities to maintain Asia-Pacific tender access as METI chemical management frameworks evolve. For New Entrants and Emerging Players: Lead with metal oxide sensor platforms targeting China's Yangtze River Delta environmental compliance retrofit wave. Exploit underpenetrated indoor air quality segments in healthcare and educational settings where OSHA mandates have not yet standardized procurement. Deploy direct-to-laboratory calibration service models that bypass OEM service arms. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core safety instrumentation divisions. Long-term viability hinges on regulatory certification moats rather than hardware differentiation alone. Watch for EPA NESHAP expansion announcements as inflection indicators for fixed detector installation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photon-Counting Sensors | Captive semiconductor foundry relationships insulate margin from Asian supply volatility. |
| JIS Certification Acquisition | Asia-Pacific tender barriers require Japanese calibration protocol compliance for market access. |
| Calibration Laboratory Network Expansion | Third-party service unbundling in Texas and Louisiana redirects recurring revenue from OEMs. |
| Metal Oxide Sensor Platform Launch | MEE ambient VOC control scheme tightening accelerates procurement from certified architectures. |
| 11.7 eV Lamp Specialty Production | Benzene-specific refinery monitoring specifications fragment supplier qualification lists. |
Research Methodology
The analysis maps portable detector replacement cycles, fixed installation retrofits, and laboratory accreditation procurement, each validated through plant safety officers, environmental compliance managers, and calibration laboratory directors. Primary interviews with OEM product managers, semiconductor foundry engineers, and petrochemical maintenance directors combined with EPA enforcement databases, MEE regulatory filings, and JIS certification registries. Bottom-up shipment data triangulated against top-down emissions monitoring infrastructure spending estimates.
Consistency checks validated volume outputs against EPA NESHAP compliance timelines, EU Industrial Emissions Directive enforcement schedules, and China's dual carbon goal implementation trajectories. The analytical framework modeled technology modality, product configuration, application severity, and end-user regulatory exposure across the projection horizon. CAGRs derived from segment-level adoption curves weighted by jurisdiction-specific enforcement intensity and replacement cycle dynamics.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or semiconductor supply stability would require recalibration. Forecasts reflect assumptions about photoionization lamp duty-cycle evolution and polymer electrolyte stability thresholds. Recalibration cycles align with material shifts in EPA, EU, and MEE regulatory amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
IR Detector Market
Detection and Regulation Devices
Global Inflation Device Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Photoionization Detectors Market
Detection and Regulation Devices
Transient Voltage Suppressor (TVS) Diode Market
Detection and Regulation Devices
Noise Monitoring Device Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Vapour Particle Barrier Market
Detection and Regulation Devices
Global Gas Detection System Market
Detection and Regulation Devices
Audio Signaling Devices Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Pin and Sleeve Devices Market