
 South East Asia Gas Detection Device Market | 2026-2036
South East Asia Gas Detection Device Market Size, Share, and Industry Trends Forecast 2026-2036
South East Asia Gas Detection Device Market Outlook
The ASEAN Agreement on Disaster Management and Emergency Response is restructuring safety equipment procurement across member states. MSA Safety Incorporated leverages its respiratory protection heritage to anchor portable detector sales in Indonesian mining concessions. Honeywell Analytics Inc. dominates fixed system installations across Thai petrochemical complexes with integrated building management interfaces.
A gas detection device is an instrument that senses and quantifies atmospheric concentrations of combustible, toxic, or oxygen-deficient gases through electrochemical reaction, infrared absorption, or catalytic oxidation, typically calibrated to trigger alarms at threshold limit values to prevent occupational fatalities or process explosions. Portable detectors lead unit shipments across Southeast Asian construction and turnaround maintenance cycles, while fixed detector networks capture the majority of installed value through multi-point monitoring architectures in oil and gas processing. Electrochemical sensors occupy the largest technology share given their cost efficiency for carbon monoxide and hydrogen sulfide detection, though infrared sensors are displacing legacy catalytic types in methane-rich applications.
Indonesia's Ministry of Manpower, Thailand's Department of Industrial Works, and Malaysia's Department of Occupational Safety and Health collectively enforce mandatory gas monitoring protocols in confined spaces and process areas, creating compliance-driven replacement cycles for obsolete equipment. Stakeholders must monitor diverging national certification timelines as ASEAN member states advance toward mutual recognition arrangements for safety device approvals.
Market Dynamics
Malaysia's Department of Occupational Safety and Health amendments are forcing immediate hardware replacement cycles across petrochemical corridors, compressing procurement timelines from typical capital planning cycles into emergency compliance sprints.
Growth Catalysts
- Confined Space Mandates:Indonesia's Ministry of Manpower regulations now require continuous atmospheric monitoring in tank cleaning and vessel entry operations across refining and LNG facilities.
- Electrochemical Sensor Economics:The cost efficiency of hydrogen sulfide and carbon monoxide detection modules is accelerating detector penetration in Vietnamese construction and Indonesian mining concessions.
- LNG Processing Corridor Expansion:Indonesia's Bontang and Tangguh train additions are generating fixed-system demand for multi-point methane monitoring architectures.
Market Restraints
- Sensor Calibration Drift:Electrochemical cells require 90-day recalibration cycles in tropical humidity, elevating total cost of ownership beyond initial hardware outlays.
- Import Dependency:Infrared source components and catalytic bead substrates concentrate in Japanese and German supply chains, exposing Thai and Malaysian integrators to currency fluctuation risk.
- Certification Fragmentation:Divergent national approval timelines between Indonesia's SNI marking, Thailand's TISI requirements, and Malaysia's SIRIM certification delay cross-border product launches.
Strategic Opportunities
- Vietnam Refinery Greenfield Development:The Nghi Son and Long Son complex expansions represent uncontracted demand for integrated fire-and-gas safety systems.
- Wireless Mesh Architectures:Battery-powered, self-hearing networks eliminate cabling costs in retrofit applications across aging Thai and Indonesian process plants.
- ASEAN Mutual Recognition Arrangements:Harmonized safety device approvals under AFTA protocols would collapse regulatory duplication costs for multi-country operators.
Industry Challenges
- Field Technician Scarcity:Calibrated gas blending and sensor replacement requires certified instrumentation specialists that Indonesian and Vietnamese vocational pipelines currently undersupply.
- Legacy System Integration:4-20mA analog outputs from 1990s-era detectors must interface with modern Modbus and Ethernet-IP building management networks without process shutdown.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South East Asia Gas Detection Device Market |
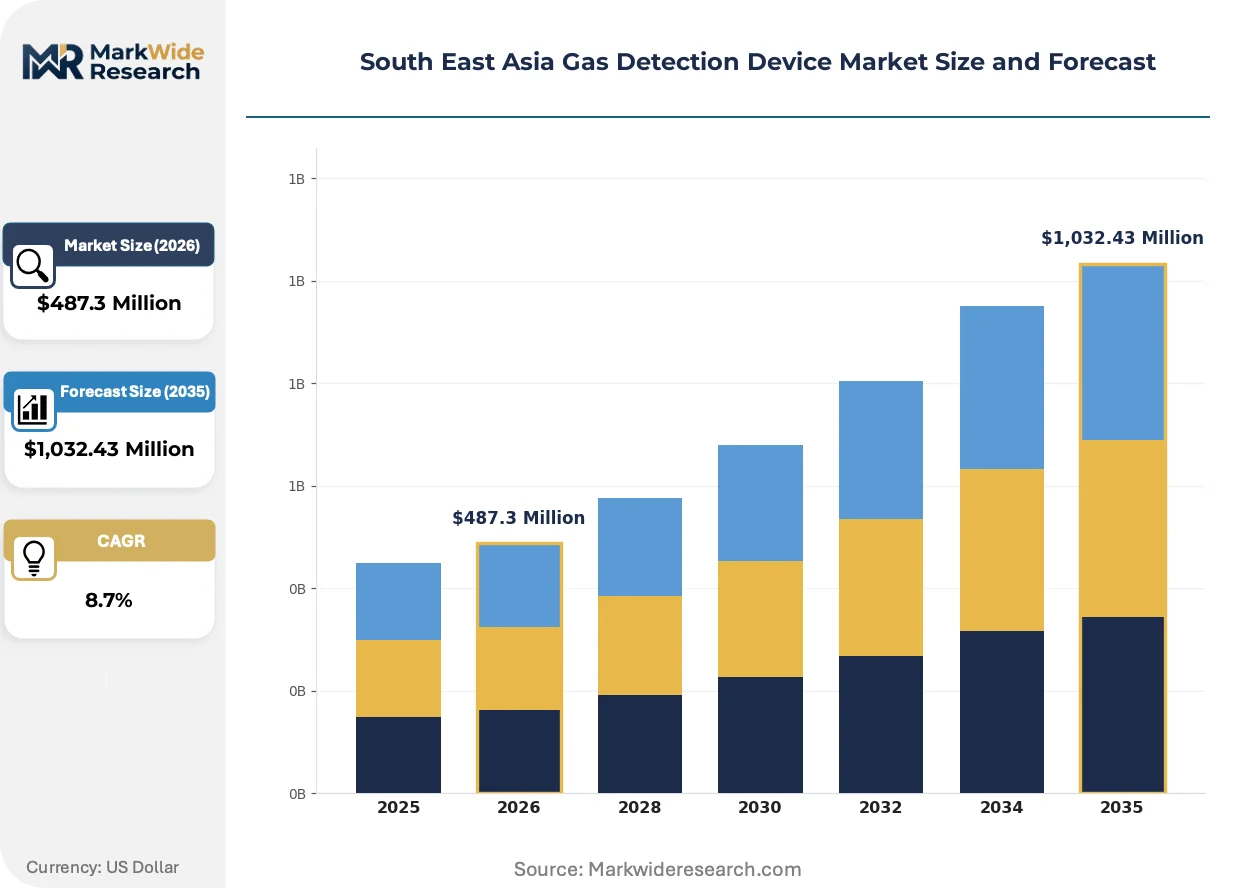
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Area Monitors, Multi-Gas Detectors Technology: Infrared Sensors, Electrochemical Sensors, Catalytic Sensors, Laser-Based Sensors End User: Manufacturing, Oil & Gas, Chemicals, Mining Application: Leak Detection, Emission Monitoring, Safety Compliance, Environmental Monitoring |
| Companies Covered | Xylem Inc., Honeywell Analytics Inc., Emerson Electric Co., MSA Safety Incorporated, Drägerwerk AG & Co. KGaA, Halma plc., Yokogawa Electric Corporation, Teledyne Gas & Flame Detection, Schneider Electric SE, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South East Asia Gas Detection Device Market Strategic Shifts
Sensor fusion architectures and cloud-connected analytics platforms are compressing the traditional separation between portable personal monitors and fixed process safety systems across Southeast Asian industrial facilities.
Multi-gas detector platforms are unifying electrochemical, infrared, and photoionization sensing modalities within single handheld or fixed-point housings. Thai petrochemical maintenance contractors and Indonesian mining safety officers are adopting these consolidated instruments to reduce device inventory and training burden. This convergence is unifying procurement specifications that previously segmented by single-gas application, pressuring pure-play sensor suppliers to expand their detection portfolios or exit maintenance-heavy segments.
Malaysia's amendments to the Occupational Safety and Health Act now mandate real-time data logging and incident traceability for confined space entries. Industrial facility operators must deploy detectors with timestamped atmospheric records and supervisor notification protocols. Fixed-system vendors with integrated data historians are capturing retrofit contracts in Penang and Pasir Gudang chemical zones ahead of enforcement deadlines.
Maintenance service unbundling is separating hardware ownership from calibration and sensor replacement obligations. Indonesian LNG operators and Vietnamese refinery projects are contracting third-party instrumentation service providers on multi-year agreements rather than training captive technicians. This shift concentrates aftermarket revenue with regional service networks in Jakarta, Bangkok, and Kuala Lumpur, displacing traditional distributor markup models.
South East Asia Gas Detection Device Market Segmentation
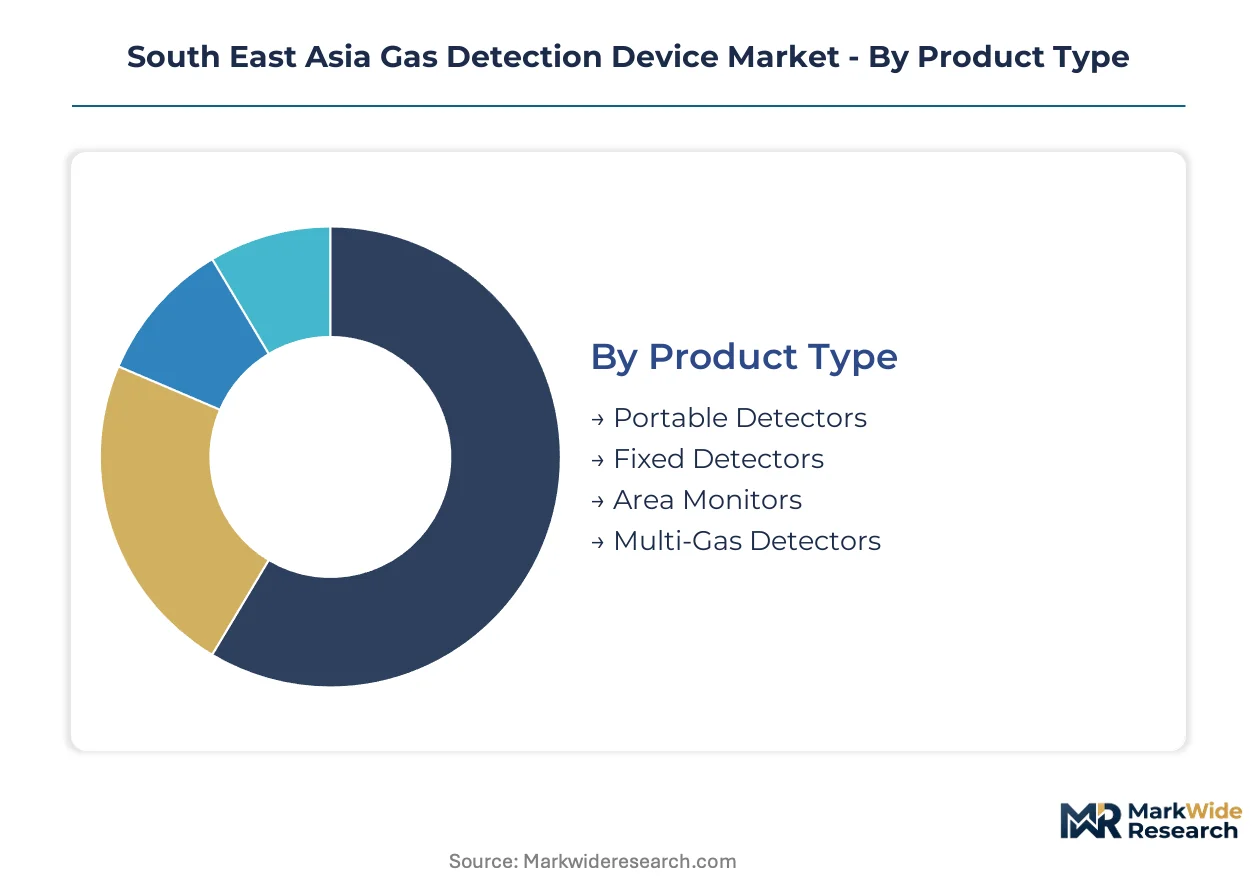
Segmentation in the South East Asia gas detection device market reveals how certification burdens, sensor economics, and application intensity concentrate procurement power across distinct equipment categories and industrial verticals.
Product Type:
Certification requirements diverge sharply across portable and fixed installations. Indonesia's SNI marking mandates accelerated testing cycles for battery-powered personal monitors, while Malaysia's SIRIM certification imposes stricter documentation burdens on hardwired fixed systems in petrochemical corridors.
- Portable Detectors:Handheld units employing electrochemical or catalytic sensing elements for personal protection during confined space entry and turnaround maintenance. Indonesian mining concessions and Vietnamese construction sites drive unit volumes through mandatory worker-wear programs under Ministry of Manpower protocols. Leading the category by volume: Portable Detectors. Growing fastest: Multi-Gas Detectors.
- Fixed Detectors:Permanently mounted multi-point architectures integrating with building management systems for continuous process area surveillance. Thai petrochemical complexes in Map Ta Phut and Rayong anchor installed value through integrated fire-and-gas safety retrofits.
- Area Monitors:Temporary perimeter deployment systems for construction zones and maintenance turnarounds requiring rapid atmospheric boundary establishment without permanent infrastructure.
- Multi-Gas Detectors:Consolidated platforms unifying electrochemical, infrared, and photoionization modalities within single housings to reduce device inventory and training burden across Indonesian LNG and Vietnamese refinery projects.
Fixed systems command premium pricing through installation complexity; portable units dominate shipment volumes.
Technology:
Sensor selection hinges on target gas chemistry, ambient humidity exposure, and replacement cost economics across tropical Southeast Asian operating environments.
- Electrochemical Sensors:Cost-efficient modules for hydrogen sulfide and carbon monoxide quantification through redox reaction at electrode surfaces. Indonesian refining and Vietnamese construction sectors absorb the highest volumes despite 90-day recalibration burdens in high-humidity conditions. Electrochemical platforms retain the largest installed base.
- Infrared Sensors:Non-dispersive absorption spectroscopy for methane and hydrocarbon detection without oxygen dependence or poisoning vulnerability. Indonesia's Bontang and Tangguh LNG trains specify infrared architectures for multi-point monitoring reliability.
- Catalytic Sensors:Wheatstone bridge oxidation detectors for combustible gas screening, now retreating to budget-constrained applications as infrared costs decline.
- Laser-Based Sensors:Tunable diode absorption spectroscopy for open-path perimeter monitoring and remote emission quantification in Malaysian petrochemical fence-line applications.
Infrared platforms displace legacy catalytic types fastest; electrochemical retains volume leadership through H2S and CO ubiquity.
End User:
Procurement authority concentrates with safety managers and instrument engineers in capital-intensive process industries subject to mandatory continuous monitoring regulations.
- Oil & Gas:Upstream LNG processing, midstream pipeline compression, and downstream refining operations generating the highest per-facility detector counts. Indonesia's expanding Tangguh train additions and Vietnam's Nghi Son complex anchor regional demand.
- Chemicals:Petrochemical crackers, aromatics complexes, and specialty chemical production requiring area classification-compliant detection in Zone 1 and Zone 2 hazardous locations. Thai Map Ta Phut industrial estates represent the densest installation clusters.
- Mining:Underground coal and hard-rock operations mandating personal H2S and CH4 monitors under Indonesia's Ministry of Manpower confined space protocols. MSA Safety leverages respiratory protection heritage in Indonesian concession sales.
- Manufacturing:General industrial facilities with intermittent exposure risks, typically procuring portable units for maintenance crews rather than fixed system investments.
Oil and gas absorbs the highest absolute spending; mining generates the steepest portable unit shipment growth.
Application:
Regulatory enforcement intensity varies by application, with safety compliance and leak detection commanding mandatory hardware deployment while environmental monitoring remains discretionary.
- Safety Compliance:Confined space entry protocols and worker protection mandates under Malaysia's Occupational Safety and Health Act amendments. Real-time data logging and timestamped atmospheric records are now compulsory for supervisor notification and incident traceability.
- Leak Detection:Process seal monitoring, flange surveys, and pipeline integrity verification to prevent ignition events and unplanned releases. Indonesian LNG and Thai petrochemical operators prioritize this application for insurance and regulatory defense.
- Emission Monitoring:Voluntary or permit-driven quantification of fugitive methane and volatile organic compounds for sustainability reporting and carbon accounting frameworks.
- Environmental Monitoring:Ambient air quality surveillance around industrial perimeters, typically procured by regulatory agencies rather than facility operators and subject to budget cyclicality.
Safety compliance anchors procurement budgets; leak detection shows the strongest retrofit momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia produces the bulk of regional gas detection demand through LNG expansion and mining safety mandates, while Thailand and Malaysia concentrate fixed-system installations across petrochemical corridors. Vietnam's emerging refinery sector absorbs imported equipment as domestic manufacturing remains nascent.
Indonesia
Tangguh and Bontang LNG train expansions anchor fixed detector procurement for multi-point methane monitoring. Indonesia's Ministry of Manpower mandates continuous atmospheric surveillance in confined vessel entry operations. Kalimantan mining concessions drive portable unit volumes through worker-wear programs.
Thailand
Map Ta Phut and Rayong industrial estates anchor integrated fire-and-gas safety retrofits across petrochemical crackers. Thailand's Department of Industrial Works enforces mandatory gas monitoring protocols in process areas and tank farms. Eastern Economic Corridor infrastructure concentrates detector deployment in aromatics complexes.
Malaysia
Penang and Pasir Gudang chemical zones absorb fixed-system retrofit contracts ahead of Occupational Safety and Health Act enforcement deadlines. Malaysia's Department of Occupational Safety and Health amendments compress procurement timelines into emergency compliance cycles. Johor petrochemical corridors generate premium demand for data-logging architectures.
Vietnam
Nghi Son and Long Son refinery greenfield developments represent uncontracted demand for integrated safety systems. Vietnam's emerging regulatory framework for industrial safety is accelerating detector adoption in construction and turnaround maintenance. Southern refinery zones concentrate first-wave fixed-system installations.
Singapore
Jurong Island chemical complexes maintain replacement cycles for legacy detector networks through integrated building management upgrades. Singapore's Workplace Safety and Health Council guidelines for process industries sustain premium equipment procurement. Marine and offshore engineering sectors absorb specialized portable units for vessel repair operations.
South East Asia Gas Detection Device Market Competitive Environment
The competitive structure tilts toward diversified industrial safety conglomerates with respiratory protection and process automation heritage. Market positions concentrate around three archetypes: integrated safety solution providers leveraging building management interfaces, portable equipment specialists with mining sector relationships, and sensor technology licensors supplying infrared and electrochemical modules to regional integrators. Capacity expansion and certification harmonization partnerships dominate competitive moves as vendors navigate fragmented ASEAN approval timelines.
Within the integrated safety tier, Honeywell Analytics Inc. and MSA Safety Incorporated exemplify divergent positioning strategies. Honeywell anchors fixed-system value through process automation integration, while MSA occupies the portable detector vector through respiratory protection cross-selling. Emerson Electric Co. represents the automation-centric archetype with distributed control system adjacencies. Drägerwerk AG & Co. KGaA and Teledyne Gas & Flame Detection sit within the specialist tier, anchoring premium positioning through sensor technology depth rather than portfolio breadth.
| Leading Market Players |
|---|
| Xylem Inc. |
| Honeywell Analytics Inc. |
| Emerson Electric Co. |
| MSA Safety Incorporated |
| Drägerwerk AG & Co. KGaA |
| Halma plc. |
| Yokogawa Electric Corporation |
| Teledyne Gas & Flame Detection |
| Schneider Electric SE |
| Others |
Value Chain & Pricing Dynamics
Infrared sensor miniaturization and domestic assembly transitions are simultaneously compressing module costs and redistributing manufacturing footprints across Southeast Asian detector supply chains. Indonesian LNG operators and Thai petrochemical buyers now capture price advantages from regional electrochemical cell production while facing elevated exposure to Japanese infrared source import volatility.
Pricing Analysis
Cost-down pressure on fixed-system installations accelerates because Malaysian SIRIM certification delays compress procurement timelines into emergency replacement cycles. Three-tier pricing structure across premium data-logging architectures, standard 4-20mA analog systems, and economy catalytic sensor modules dominates the market. Price differentiation rests on certification grade and after-sales calibration bundling. Mining sector buyers in Indonesian Kalimantan concessions exhibit highest price sensitivity due to volume procurement of disposable portable units, while Singaporean Jurong Island chemical operators accept premium positioning for integrated building management interfaces.
Supply Chain Analysis
Indonesia's domestic-content mandates for government-linked LNG procurement are reshaping sourcing patterns for final assembly and calibration gas blending operations. Infrared source components and electrochemical sensor substrates concentrate in Japan, Germany, and South Korea, exposing Thai and Malaysian integrators to yen-euro currency fluctuation risk. Raw material dependencies include catalytic bead substrates, tunable diode laser elements, and certified reference gas mixtures. Single-source vulnerability characterizes Japanese NDIR source supply for methane detection applications. Distribution runs through Jakarta, Bangkok, and Kuala Lumpur-based regional service networks that unbundle calibration obligations from hardware ownership.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with integrated data-logging capabilities and regional certification expertise as Malaysia's Occupational Safety and Health Act amendments force smaller distributors into acquisition or exit. Certification fragmentation and field technician scarcity are eliminating pure-play sensor suppliers lacking service infrastructure.
For Market Incumbents: Anticipate margin compression in portable detector segments as Indonesian mining concessions consolidate procurement around multi-year service contracts. Defensive moves require backward integration into electrochemical cell production within ASEAN free-trade zones and acquisition of calibration service networks in Ho Chi Minh City and Surabaya to capture aftermarket revenue concentration. The threat of wireless mesh architectures eliminating cabling-intensive fixed-system margins demands immediate R&D allocation toward battery-powered, self-healing network platforms. For New Entrants and Emerging Players: Launch via third-party instrumentation service partnerships targeting Vietnamese refinery greenfield developments at Nghi Son and Long Son where incumbent relationships remain unformed. White-space opportunities concentrate in temporary area monitor deployment for construction turnaround cycles and cloud-connected analytics platforms for timestamped atmospheric record compliance. The most penetrable segment is wireless retrofit architectures for aging Thai and Indonesian process plants with legacy 4-20mA analog infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial safety conglomerates seeking ASEAN certification portfolios and regional service density. Long-term viability favors targets with captive electrochemical sensor production and SNI-SIRIM-TISI triple certification capabilities rather than pure distribution plays. Acquisition target archetype: mid-cap regional integrators with calibration service contracts at Indonesian LNG facilities. The signal to watch is ASEAN mutual recognition arrangement implementation collapsing regulatory duplication costs and accelerating cross-border consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Harmonization Partnership | Collapses SNI, SIRIM, and TISI duplication costs for multi-country operators under ASEAN protocols. |
| Backward Integration into Sensor Production | Captures electrochemical cell margins and insulates against Japanese-German component currency exposure. |
| Wireless Mesh Architecture Launch | Eliminates cabling retrofit costs in aging Thai and Indonesian process plants with analog legacy infrastructure. |
| Calibration Service Network Acquisition | Concentrates aftermarket revenue in Jakarta, Bangkok, and Kuala Lumpur as operators unbundle maintenance obligations. |
| Multi-Gas Platform Consolidation | Reduces device inventory and training burden across Indonesian LNG and Vietnamese refinery project specifications. |
Study Parameters
Trade data from Indonesian Ministry of Industry import registries, Malaysian SIRIM certification databases, and Thai Department of Industrial Works safety equipment filings formed the secondary backbone for market sizing validation. Primary interviews with safety managers at Tangguh LNG operations, instrumentation engineers at Map Ta Phut petrochemical complexes, and procurement leads at Vietnamese refinery EPC contractors combined with bottom-up and top-down triangulation across portable and fixed detector shipment estimates.
Historical trendline analysis of electrochemical and infrared sensor penetration rates informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, sensor technology, end-use industry vertical, and national regulatory cluster. CAGRs derived from unit shipment trajectories and average selling price evolution in Indonesian mining and Thai petrochemical corridors. Industry-specific forecast inputs incorporate Malaysia's Occupational Safety and Health Act enforcement timeline and Vietnam's refinery construction cadence.
The model assumes a particular technology adoption path; alternative pathways for wireless mesh architectures displacing hardwired fixed systems would alter the outlook for installation service revenue pools. Forecasts reflect assumptions regarding ASEAN mutual recognition arrangement progress and field technician training pipeline expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
X-Ray Detectors Market
Detection and Regulation Devices
Indeflator Devices Market
Detection and Regulation Devices
Hitoxic Gas Detector Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Positive Temperature Coefficient (PTC) Thermistor Market
Detection and Regulation Devices
Latin America Trace Detection Market
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Transient Voltage Suppressor (TVS) Diode Market
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Electronic Article Surveillance Market