
 Gastrointestinal Stromal Tumor (GIST) Therapeutics Market | 2026-2036
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market Foresight
The capital-intensity divergence between large-cap oncology incumbents and precision-medicine biotechs is bifurcating competitive dynamics in GIST therapeutics. Novartis leverages its established imatinib infrastructure and companion diagnostic relationships to sustain market presence in first-line settings. Blueprint Medicines specializes in KIT exon 17 mutant populations with avapritinib, occupying a narrow but defensible molecular niche where standard tyrosine kinase inhibitors fail.
Gastrointestinal Stromal Tumor therapeutics comprise targeted small-molecule kinase inhibitors that interrupt oncogenic signaling through KIT or PDGFRA receptor blockade, with imatinib mesylate functioning as a competitive ATP-site antagonist that halts tumor proliferation in CD117-positive malignancies. Oral tyrosine kinase inhibitors anchor commercial volume due to outpatient administration convenience and established reimbursement pathways, while injectable and infusion delivery modes serve resistant or intolerant populations requiring hospital-based salvage protocols. The oncology therapy area dominates value capture given GIST's classification as a molecularly defined sarcoma subtype, whereas rare diseases designation unlocks orphan drug incentives that compress development economics for sponsors.
FDA breakthrough therapy designation and EMA PRIME eligibility reshape clinical trial investment by compressing regulatory review timelines for GIST compounds addressing unmet resistance mechanisms. The FDA's accelerated approval pathway and EMA's conditional marketing authorization framework both predicate full approval on confirmatory overall survival data, creating post-market obligation risk for sponsors. Stakeholders must monitor emerging resistance mutation landscapes and corresponding diagnostic coverage decisions to align pipeline positioning with evolving standard-of-care sequences.
Market Dynamics
The GIST therapeutics landscape is being reshaped by the FDA's accelerated approval pathway, which compresses development timelines for kinase inhibitors targeting KIT exon 17 mutations and other resistance mechanisms. This regulatory mechanism is redrawing competitive boundaries between established oncology incumbents and precision-medicine specialists.
Growth Catalysts
- Orphan Drug Incentives:Rare disease designation unlocks tax credits and market exclusivity provisions that compress development economics for sponsors pursuing molecularly defined sarcoma subtypes.
- Companion Diagnostic Integration:Molecular profiling for KIT/PDGFRA mutations is expanding across tertiary hospital oncology departments, anchoring targeted therapy selection to specific mutational signatures.
- Breakthrough Therapy Designation:The FDA's breakthrough pathway and EMA PRIME eligibility compress regulatory review timelines for compounds addressing unmet resistance mechanisms in heavily pretreated populations.
Market Restraints
- Post-Market Obligation Risk:Accelerated approvals predicate full authorization on confirmatory overall survival data, creating regulatory exposure for sponsors if confirmatory trials fail.
- Resistance Mutation Complexity:Secondary KIT mutations and PDGFRA variant heterogeneity limit duration of response across sequential tyrosine kinase inhibitor lines.
- Centralized Treatment Concentration:Referral networks for rare sarcoma subtypes concentrate patient volume at academic medical centers, constraining community oncology penetration.
Strategic Opportunities
- Sequential Therapy Positioning:Pipeline assets can anchor fourth-line and beyond sequences where standard tyrosine kinase inhibitors have exhausted efficacy.
- Liquid Biopsy Integration:Circulating tumor DNA monitoring is converging with radiographic response assessment to enable earlier resistance detection and therapy switching.
- Japan and South Korea Expansion:MFDS and PMDA regulatory pathways for orphan oncology indications present accelerated entry opportunities in concentrated sarcoma treatment networks.
Industry Challenges
- Bioinformatics Talent Scarcity:Interpretation of complex KIT/PDGFRA co-mutation patterns requires specialized computational pathology expertise that outpaces current training pipelines.
- Diagnostic Coverage Alignment:Payer decisions on comprehensive genomic profiling reimbursement lag behind therapeutic availability, creating access friction for molecularly matched therapy.
- Manufacturing Scale Constraints:Kinase inhibitor API synthesis for precision indications faces batch-size optimization challenges given small patient populations per mutation subtype.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastrointestinal Stromal Tumor (GIST) Therapeutics Market |
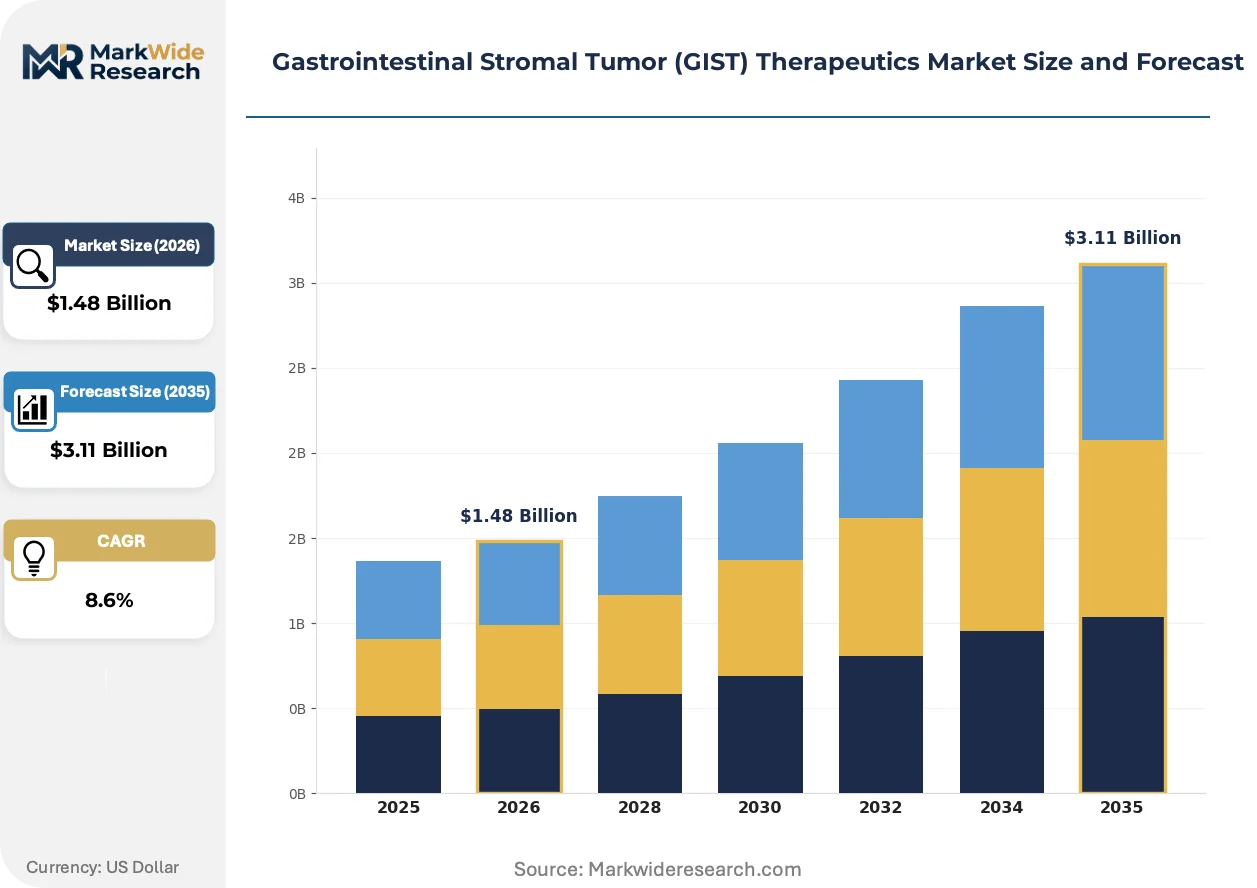
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $3.11 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunitinib, Imatinib, Regorafenib, Avapritinib Delivery Mode: Oral, Injectable, Infusion, Subcutaneous End User: Hospitals, Clinics, Research Institutes, Homecare Settings Therapy Area: Oncology, Hematology, Rare Diseases, Palliative Care |
| Companies Covered | Deciphera Pharmaceuticals, Taiho Pharmaceutical, Novartis, Roche, Daiichi Sankyo, Pfizer, Blueprint Medicines, Bristol-Myers Squibb, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market Shifts & Advancements
Active transformation in GIST therapeutics centers on three vectors: the physical integration of diagnostic and therapeutic decision-making, regulatory frameworks adapting to molecular stratification, and care delivery models compressing time-to-treatment for resistant disease.
Liquid biopsy platforms for circulating tumor DNA detection are miniaturizing the diagnostic footprint required for resistance monitoring, enabling real-time mutational tracking without invasive tissue sampling. Academic medical centers in the United States are adopting these platforms for routine surveillance of patients on imatinib or sunitinib, compressing the interval between radiographic progression and therapy modification. This technology is miniaturizing the infrastructure required for precision oncology, allowing community settings to adopt molecular monitoring previously confined to major referral centers.
EMA's conditional marketing authorization framework and FDA's Project Orphan are synchronizing regulatory expectations for GIST therapeutics addressing defined resistance mutations. Sponsors must now design single-arm trials with overall survival endpoints to satisfy post-market commitments, elevating the evidentiary bar for accelerated pathways. European oncology networks are responding by consolidating molecular tumor boards to standardize patient selection for these trials.
Centralized procurement through hospital system formularies is displacing individual physician prescribing autonomy for high-cost kinase inhibitors. United States academic medical centers are negotiating system-level contracts that bundle companion diagnostic access with therapeutic volume commitments. This consolidation is most visible in the Northeast and Midwest, where integrated delivery networks dominate sarcoma referral patterns and can extract preferential pricing through consolidated purchasing.
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market Segmentation
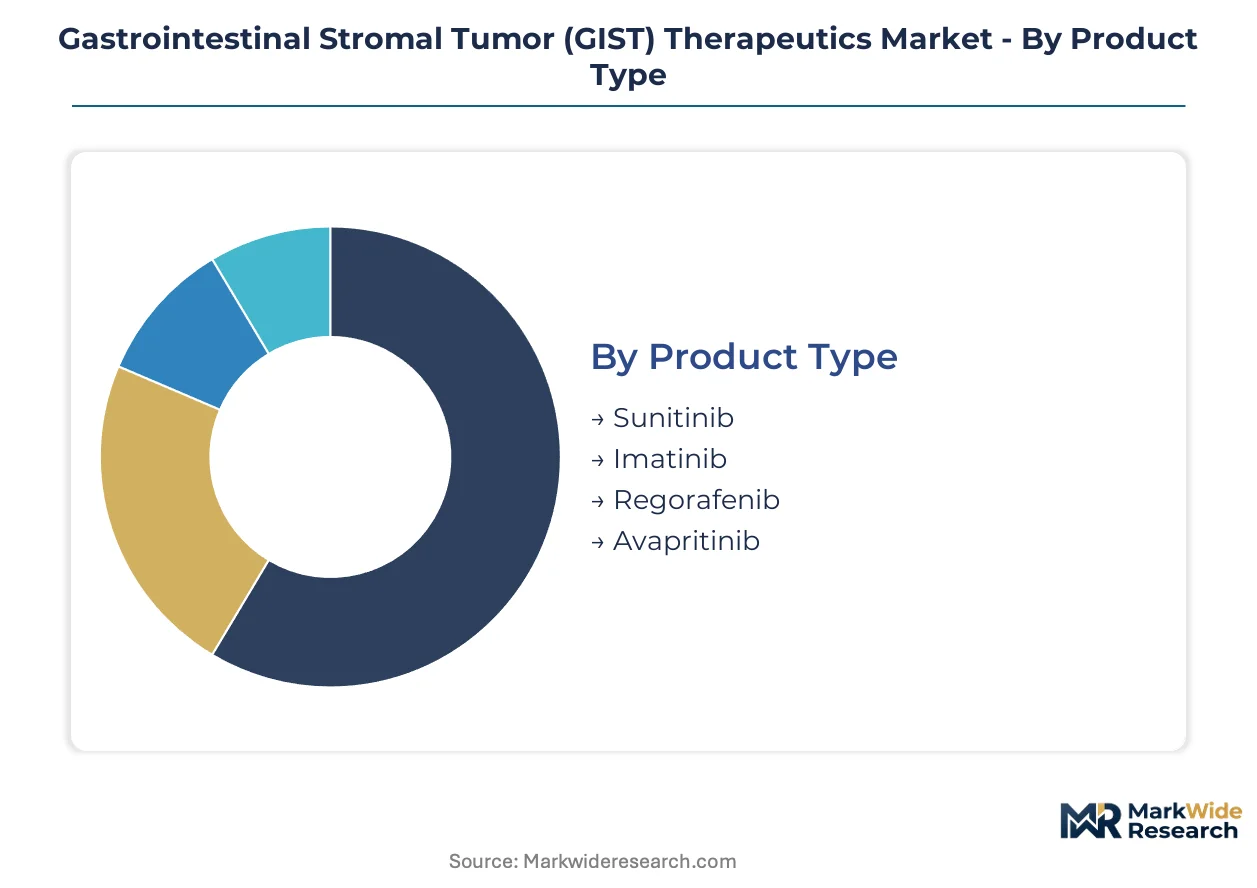
Molecular stratification of GIST subtypes necessitates precise segment alignment between mutational profiles and therapeutic mechanisms. Each segmentation dimension carries distinct reimbursement, regulatory, and clinical trial design implications that sponsors must navigate.
Product Type:
FDA breakthrough therapy designation and EMA PRIME eligibility compress review timelines differently across kinase inhibitor generations, creating asymmetric competitive windows for first-line versus salvage agents.
- Imatinib:The ATP-competitive KIT/PDGFRA antagonist anchors first-line protocols through established companion diagnostic relationships with CD117 immunohistochemistry. Academic medical centers in the United States drive volume concentration where imatinib infrastructure supports centralized sarcoma referral networks.
- Sunitinib:A multi-targeted tyrosine kinase inhibitor with VEGFR and PDGFR blockade occupies the second-line position following imatinib resistance, with demand concentrating at tertiary hospital oncology departments managing progressive disease.
- Regorafenib:Broad-spectrum kinase inhibitor approved for third-line GIST settings where sequential resistance mutations exhaust prior targeted options.
- Avapritinib:Selective KIT exon 17 mutant inhibitor with FDA accelerated approval for PDGFRA D842V-mutant disease and fourth-line resistant populations.
Imatinib handles the majority of throughput; avapritinib is climbing the fastest on share as resistance profiling expands.
Delivery Mode:
Cost tier stratification separates outpatient oral convenience from hospital-based salvage administration, with reimbursement differentials widening between community and academic settings.
- Oral:Tyrosine kinase inhibitors in tablet or capsule form dominate commercial volume through outpatient administration convenience and established pharmacy benefit coverage pathways.
- Injectable:Hospital-administered formulations serve intolerant or resistant populations requiring parenteral delivery, with demand concentrating at academic medical centers equipped for infusion monitoring.
- Infusion:Intravenous delivery modes anchor salvage protocols where oral bioavailability fails or gastrointestinal obstruction precludes enteral absorption.
- Subcutaneous:Emerging delivery innovation for investigational agents seeking administration flexibility between outpatient and supervised settings.
Oral formulations capture the dominant patient volume; subcutaneous development programs are expanding most quickly as sponsors seek administration differentiation.
End User:
Customer type concentration reflects referral pattern economics, with rare sarcoma expertise concentrating at designated centers of excellence that influence therapy sequencing decisions.
- Hospitals:Tertiary and academic medical centers anchor GIST therapeutics volume through integrated molecular tumor boards and clinical trial access.
- Clinics:Community oncology practices manage stable first-line patients with remote molecular profiling support from referral networks.
- Research Institutes:National cancer centers and cooperative groups drive pipeline enrollment for resistance mechanism trials.
- Homecare Settings:Oral kinase inhibitor administration shifts to ambulatory management as treatment lines extend and performance status permits.
Hospitals manage the dominant share of treatment initiations; homecare settings are gaining volume fastest as oral therapy duration lengthens.
Therapy Area:
Maturity differentiation separates established oncology reimbursement pathways from rare disease incentive structures that compress development economics for molecularly defined indications.
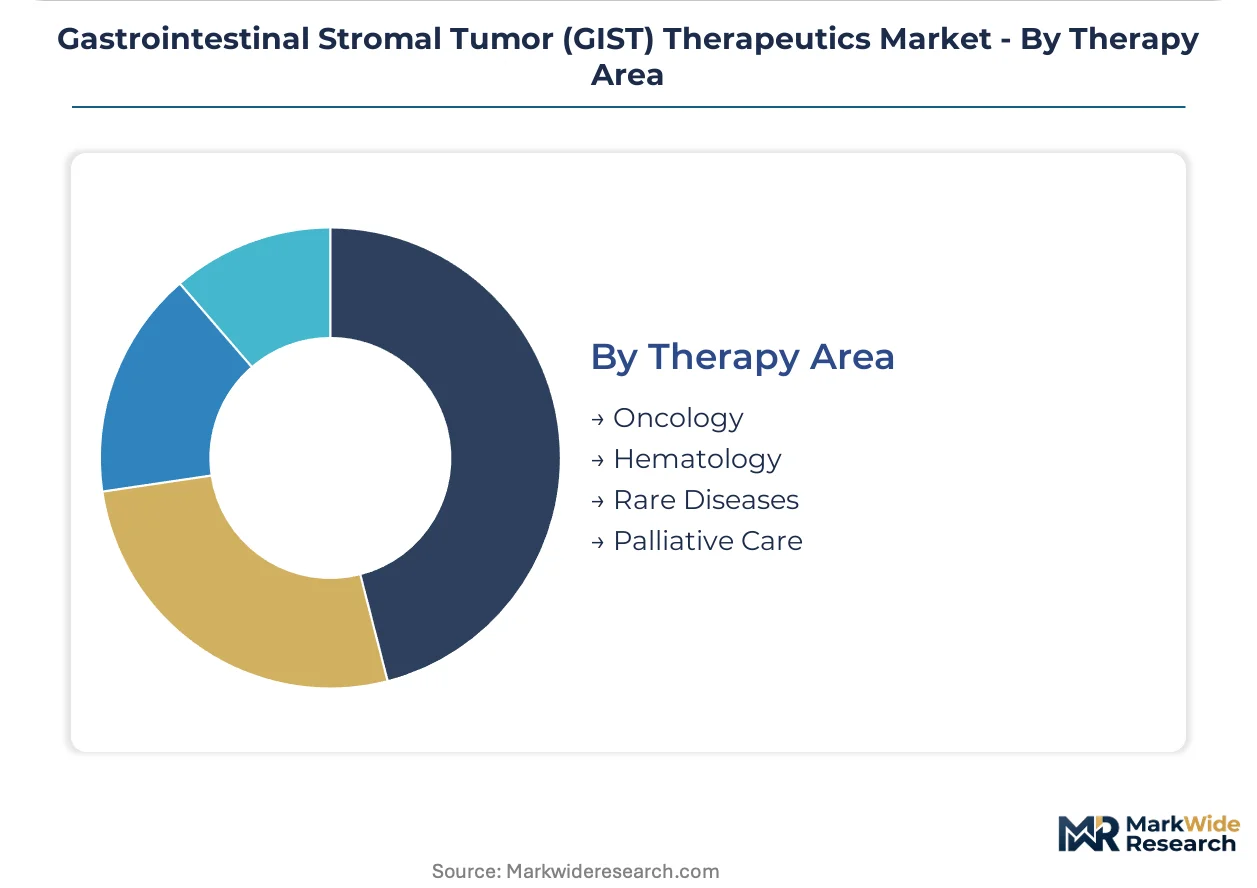
- Oncology:GIST's classification as a molecularly defined sarcoma subtype anchors commercial value capture within solid tumor therapeutic frameworks.
- Rare Diseases:Orphan drug designation unlocks tax credits and market exclusivity provisions that reshape sponsor investment calculations for small patient populations.
- Hematology:Cross-disciplinary management overlaps where GIST presents with coagulopathy or requires transfusion support during surgical intervention.
- Palliative Care:End-stage disease management concentrates at hospice-eligible populations where systemic therapy discontinuation requires symptom-focused transition.
Oncology represents the core value anchor; rare diseases designation is expanding fastest as molecular stratification multiplies addressable subpopulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European markets extract steeper discounts through centralized procurement. Germany and France negotiate reference pricing that compresses margins for kinase inhibitor sponsors. Japan and South Korea present accelerated regulatory pathways that reward early entrants with premium positioning.
United States
Academic medical centers in Boston and New York anchor sarcoma referral networks that centralize GIST patient volume. The FDA's breakthrough therapy designation compresses review timelines for resistance-targeting compounds. Memorial Sloan Kettering and Dana-Farber Cancer Institute drive molecular tumor board standardization that shapes therapy sequencing decisions.
Germany
Comprehensive cancer centers in Munich and Heidelberg integrate liquid biopsy monitoring into routine resistance surveillance. EMA conditional marketing authorization frameworks align with German federal reference pricing that benchmarks against European averages. The German Cancer Research Center coordinates multi-site trials for KIT exon 17 mutant populations.
Japan
PMDA orphan drug designation unlocks priority review for GIST therapeutics addressing unmet resistance mechanisms. Tokyo and Osaka academic hospitals concentrate sarcoma expertise through designated cancer care networks. The Japanese Society of Medical Oncology standardizes companion diagnostic requirements for KIT/PDGFRA profiling.
South Korea
MFDS accelerated approval pathways for rare oncology indications attract sponsors seeking early Asian market entry. Seoul National University Hospital and Samsung Medical Center anchor molecular tumor board networks. The Korean Cancer Study Group coordinates investigator-initiated trials for sequential tyrosine kinase inhibitor sequences.
Switzerland
Swissmedic streamlined review processes align with Basel and Zurich cancer center participation in pan-European sarcoma trials. Roche and Novartis headquarters proximity creates diagnostic-therapeutic partnership density. The Swiss Group for Clinical Cancer Research standardizes patient selection criteria for resistance mechanism studies.
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in GIST therapeutics. Large-cap oncology incumbents leverage established kinase inhibitor infrastructure and companion diagnostic relationships to sustain first-line positioning. Precision-medicine biotechs occupy narrow molecular niches where standard tyrosine kinase inhibitors fail. Competitive moves center on sequential therapy positioning and liquid biopsy integration partnerships.
Among large-cap pharmaceutical developers, Novartis and Pfizer anchor the established infrastructure tier with ATP-competitive KIT antagonists. Blueprint Medicines occupies the precision-medicine specialist position with selective KIT exon 17 mutant inhibition. Deciphera Pharmaceuticals represents the resistance-mechanism focused archetype targeting salvage populations where prior lines have failed.
| Leading Market Players |
|---|
| Deciphera Pharmaceuticals |
| Taiho Pharmaceutical |
| Novartis |
| Roche |
| Daiichi Sankyo |
| Pfizer |
| Blueprint Medicines |
| Bristol-Myers Squibb |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between academic medical centers and kinase inhibitor sponsors lock in supply access for precision oncology populations while anchoring price visibility across multi-year treatment protocols. These contracts bundle companion diagnostic volume with therapeutic commitments, compressing procurement friction for molecularly matched GIST therapies.
Pricing Analysis
The customization-premium spread separates standard ATP-competitive KIT antagonists from configured-to-order regimens targeting rare exon 17 mutations. Pricing stratifies across premium, standard, and economy tiers based on mutation specificity and line of therapy, with fourth-line salvage agents commanding the widest spreads. Cost compression in the standard-tier intensifies as imatinib faces biosimilar pressure and payer formulary tightening. Community oncology practices exhibit the highest price sensitivity, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Inventory lead times for kinase inhibitor APIs extend six to eighteen months given batch-size constraints for small patient populations per mutation subtype. Active pharmaceutical ingredient synthesis concentrates in India, Switzerland, and the United States, with specialized fermentation and crystallization capacity tethered to orphan drug manufacturing standards. Key dependencies include high-purity solvents, specialized catalysts, and chromatography resins. Single-source vulnerability runs through Swiss contract manufacturers holding FDA-approved facilities for controlled-substance handling. Distribution runs through hospital system formularies and specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against next-generation allosteric inhibitors and antibody-drug conjugates that could displace oral tyrosine kinase inhibitors in resistant populations.
For Market Incumbents: Fortify companion diagnostic infrastructure to lock in molecular profiling workflows before liquid biopsy platforms democratize resistance detection. Deepen backward integration into API synthesis to capture margin from Swiss and Indian contract manufacturers. The priority lever centers on securing long-term formulary contracts with integrated delivery networks before precision-medicine biotechs establish molecular niche positions. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-tracks compress regulatory timelines for entrants targeting KIT exon 17 mutant populations where Novartis and Pfizer lack efficacy. White-space targets include fourth-line salvage sequences and Japan's concentrated sarcoma treatment networks. The most penetrable segment sits in community oncology settings seeking remote molecular tumor board support for therapy sequencing decisions. For Investors and Strategic Acquirers: Resistance-mechanism focused biotechs with single-arm trial data and accelerated approval pathways represent the acquisition archetype with highest strategic optionality. Long-term viability hinges on confirmatory overall survival data satisfying post-market commitments. Watch FDA confirmatory trial readouts as the inflection signal separating sustainable franchise value from regulatory exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Bundles molecular profiling access with therapeutic volume commitments at Memorial Sloan Kettering and Dana-Farber. |
| Liquid Biopsy Integration | Enables real-time resistance monitoring through circulating tumor DNA platforms miniaturizing diagnostic infrastructure. |
| Orphan Drug Designation Pursuit | Unlocks tax credits and market exclusivity provisions compressing development economics for KIT exon 17 inhibitors. |
| Academic Medical Center Contracting | Secures system-level formulary placement through consolidated purchasing at Northeast and Midwest integrated delivery networks. |
| Regulatory Fast-Track Navigation | Compresses FDA review timelines through breakthrough therapy designation for compounds addressing unmet resistance mechanisms. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchored the qualitative base for this analysis. Primary interviews with payer access specialists and molecular pathology laboratory directors combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov entries, and hospital formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation converged on segment-level estimates.
Sensitivity analysis tested forecast robustness across regulatory approval timing, resistance mutation prevalence, and companion diagnostic adoption curves. The analytical framework segmented by treatment line, dosage form, administration route, and regional regulatory cluster across the projection horizon. CAGRs derived from log-linear trend fitting adjusted for patent expiry impacts and biosimilar entry assumptions. Forecast inputs incorporated mutation-specific addressable populations and sequential therapy sequencing patterns.
Underlying assumptions cover confirmatory trial success rates, reimbursement persistence for accelerated approvals, and liquid biopsy platform penetration, with deviation risk concentrated in regulatory reversals and diagnostic coverage lag. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Monoclonal Antibody Therapy Market
Specialty Medicine
Dupuytrens Disease Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Personalized Medicine Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Bacteriophages Therapy Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
SPINA Bifida and Hydrocephalus Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market