
 Robotic Total Stations (RTS) Market | 2026-2036
Robotic Total Stations (RTS) Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Total Stations (RTS) Market Intelligence
ISO 17123-4 instrument qualification is bifurcating vendor eligibility between certified precision manufacturers and uncertified assemblers. Trimble Inc. leverages its North American calibration network to sustain premium positioning in permanent installation contracts. Hexagon AB anchors European demand through its Leica Geosystems AG subsidiary, which dominates high-precision surveying workflows. Topcon Corporation competes aggressively on electro-optical product specialization across Asian civil engineering markets.
Robotic Total Stations are motorized theodolites with electronic distance measurement, typically achieving angular accuracy of 0.5 to 5 arcseconds and operating via remote controller or automated target recognition for unmanned surveying operations. Their primary purpose is to execute high-precision coordinate measurement, layout, and monitoring tasks in construction, mining, and infrastructure projects where manual operation introduces efficiency losses or safety risks. Electro-optical units command the largest installed base, though GNSS-integrated configurations represent the fastest-expanding margin pool as hybrid positioning demand intensifies. Laser scanning technology within the technology dimension attracts premium pricing, while total station legacy protocols retain volume leadership in developing markets.
The US Federal Communications Commission governs radio frequency emissions from robotic station telemetry, while China's Ministry of Industry and Information Technology enforces GB standards for geodetic instrument accuracy. Japan's Ministry of Economy, Trade and Industry coordinates JIS certification reciprocity that shapes cross-border procurement eligibility. Stakeholders must monitor evolving electromagnetic compatibility mandates and dual-use export control classifications that could restrict component sourcing for automated surveying platforms.
Market Dynamics
ISO 17123-4 instrument qualification is bifurcating vendor eligibility between certified precision manufacturers and uncertified assemblers, compressing procurement pools for permanent installation contracts while elevating calibration network density as a competitive moat.
Growth Catalysts
- MIIT Certification Mandates:China's GB standards for geodetic instrument accuracy are accelerating domestic manufacturer consolidation, eliminating marginal producers from state-backed infrastructure tenders.
- GNSS-Integrated Configurations:Hybrid positioning demand is intensifying across precision construction applications, with electro-optical units commanding installed base leadership while integrated systems capture margin expansion.
- Infrastructure Resilience Standards:German and Japanese civil engineering firms are expanding procurement of GNSS-integrated units as seismic and climate-load specifications tighten for transportation and utility networks.
Market Restraints
- Electro-Optical Component Concentration:Precision encoder and distance measurement module supply concentrates among Japanese and German optical specialists, exposing buyers to lead-time volatility.
- Dual-Use Export Controls:Automated target recognition and telemetry subsystems face tightening classification under multilateral regimes, restricting component sourcing for certain geodetic platforms.
- Laser Scanning Substitution:Terrestrial LiDAR systems are displacing conventional total stations in high-density as-built documentation workflows, compressing addressable market for legacy protocols in developed economies.
Strategic Opportunities
- Brazilian Infrastructure Modernization:Federal investment programs in transportation corridors are creating first-mover advantages for vendors establishing local calibration and service infrastructure.
- Automated Target Recognition Convergence:Integration of machine vision with motorized theodolite control systems is enabling unmanned monitoring applications in mining slope stability and dam deformation.
- JIS Certification Reciprocity:Japan's METI-coordinated mutual recognition agreements are opening procurement eligibility for certified manufacturers across Southeast Asian public works agencies.
Industry Challenges
- Geodetic Surveyor Talent Scarcity:Pipeline shortages in precision measurement technician training are extending commissioning timelines and elevating total cost of ownership for complex installation projects.
- Legacy Protocol Integration Friction:Electromechanical total station fleets in developing markets resist seamless data handoff to modern BIM and digital twin environments, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Total Stations (RTS) Market |
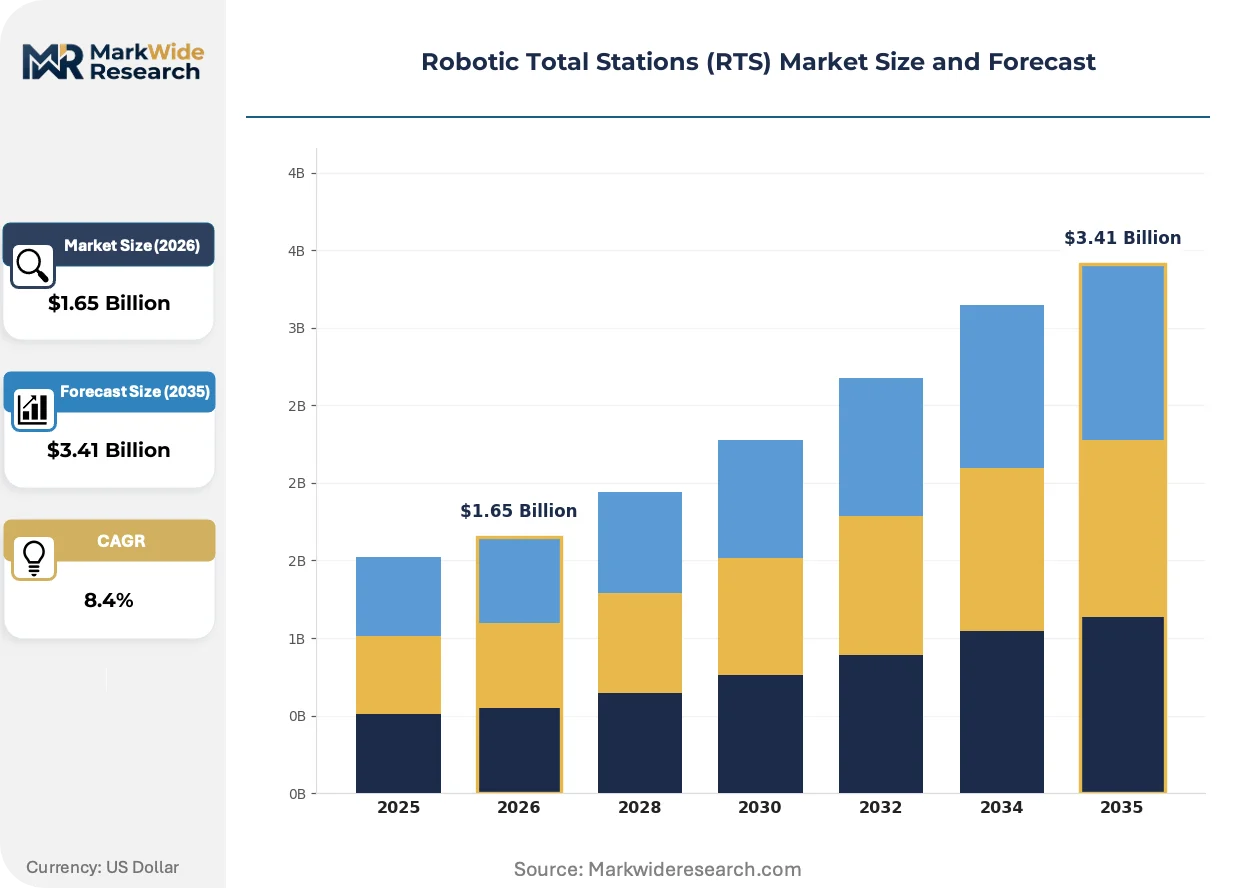
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electro-Optical, GNSS Integrated, Mechanical, Hybrid Technology: Laser Scanning, Photogrammetry, 3D Modeling, Total Station End User: Construction, Surveying, Mining, Civil Engineering Installation: Permanent, Temporary, Mobile, Fixed |
| Companies Covered | Trimble Inc., Hexagon AB, Topcon Corporation, Leica Geosystems AG, South Surveying & Mapping Technology Co., Ltd., Hi-Target Surveying Instrument Co., Ltd., Suzhou FOIF Co., Ltd., Guangdong Kolida Instrument Co., Ltd., STONEX Srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Total Stations (RTS) Market Strategic Shifts & Innovations
Active sensor fusion and edge computing architectures are redefining field-data processing latency, enabling real-time coordinate validation without tethered controller dependency.
Multi-sensor payloads combining robotic total station cores with integrated photogrammetry and IMU drift correction are miniaturizing into single-tripod configurations. Australian mining contractors are deploying these consolidated units for blast-pattern layout and stockpile volumetrics, eliminating separate instrument swaps. The form-factor compression is displacing two-operator survey crews with single-technician workflows across remote extraction sites.
China's MIIT enforcement of electromagnetic compatibility testing for geospatial telemetry is hardening RF emission standards for automated target recognition systems. Industrial consequence includes mandatory pre-market certification extending product launch timelines by six to nine months. South Korean and Australian importers are responding by pre-qualifying component suppliers against GB/T 17626 immunity test protocols.
Subscription-based instrument access models are replacing capital purchase cycles for mid-tier civil engineering contractors. Equipment-as-a-service providers in Germany and Japan are unbundling hardware, calibration, and software maintenance into usage-tiered contracts. This shift is most visible among municipal surveying departments facing compressed annual capital appropriations and preference for operational expenditure treatment.
Robotic Total Stations (RTS) Market Segmentation
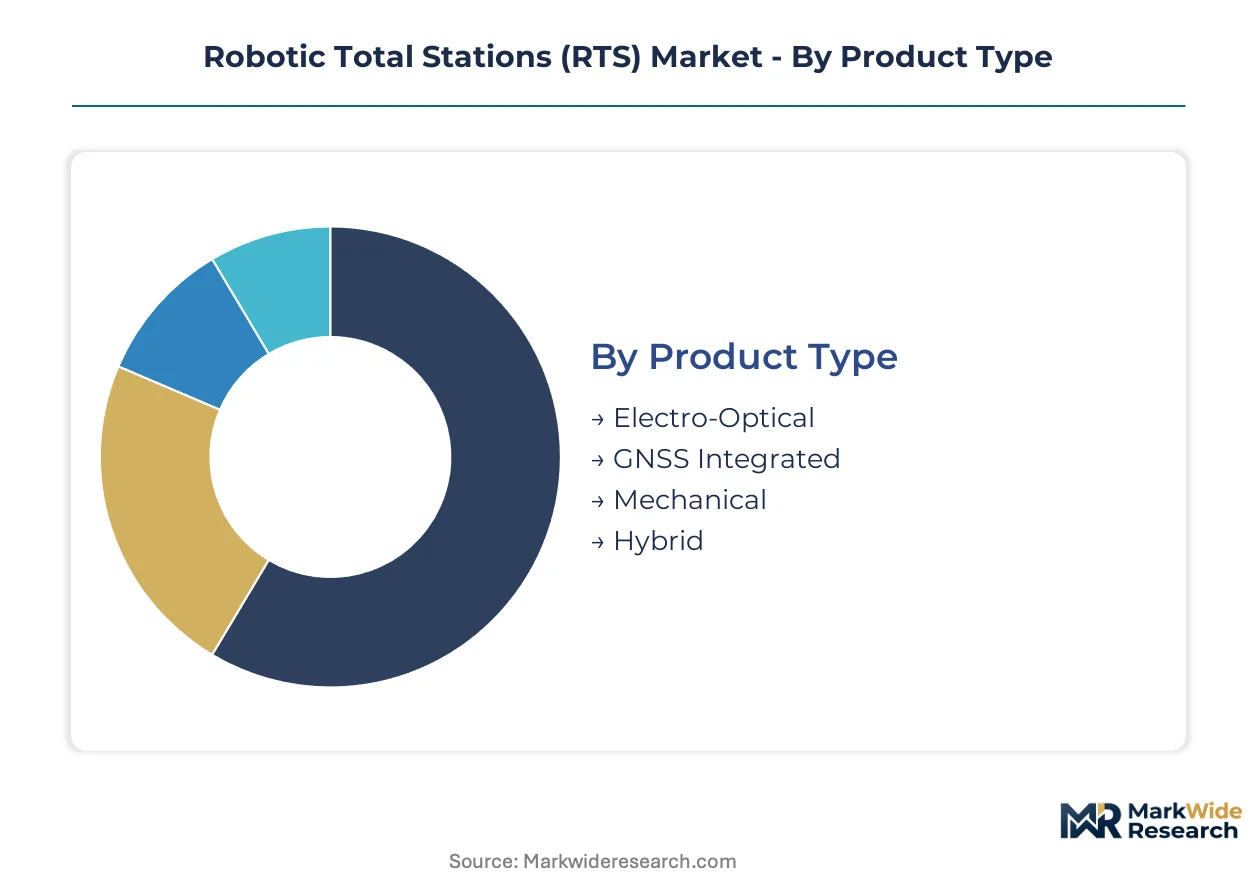
Segmentation in the Robotic Total Stations (RTS) Market reveals divergent procurement patterns across precision tiers and deployment contexts. Product architecture, sensing modality, end-use discipline, and installation permanence each shape vendor positioning and margin capture differently.
Product Type:
Domestic production concentrates in electro-optical units across Germany and Japan, while GNSS-integrated configurations rely more heavily on cross-border component flows from Chinese optical specialists.
- Electro-Optical:Motorized theodolites with electronic distance measurement achieve angular accuracy between 0.5 and 5 arcseconds. German civil engineering firms anchor procurement for permanent installation contracts where calibration network density determines vendor eligibility.
- GNSS Integrated:Hybrid positioning systems combine satellite reception with electro-optical cores for seamless coordinate validation. South Korean and Australian precision construction applications are expanding procurement as infrastructure resilience standards tighten for seismic and climate-load specifications.
- Mechanical:Legacy manual units retain volume presence in developing markets where capital constraints favor established protocols over automated target recognition.
- Hybrid:Multi-sensor configurations merge robotic station cores with photogrammetry and IMU drift correction into single-tripod deployments.
Electro-Optical commands the established base. The steepest expansion runs through GNSS Integrated.
Technology:
Cost stratification separates premium sensing modalities from legacy total station protocols, with laser scanning units capturing three to four times the unit economics of conventional electro-optical cores.
- Laser Scanning:Terrestrial LiDAR systems enable high-density as-built documentation workflows with premium pricing structures. Japanese and German mining contractors are displacing conventional total stations for slope stability monitoring and stockpile volumetrics.
- Photogrammetry:Image-based measurement integrated with motorized theodolite control enables unmanned monitoring applications. Australian blast-pattern layout operations are consolidating previously separate instrument swaps into single-technician workflows.
- 3D Modeling:Point cloud processing and mesh generation capabilities embedded at the edge reduce tethered controller dependency.
- Total Station:Legacy protocols retain installed base leadership in Brazil and other developing markets where middleware friction complicates BIM handoff.
Total Station protocols anchor volume in price-sensitive procurement pools. The steepest climb in margin capture belongs to Laser Scanning.
End User:
Customer type determines specification stringency and replacement cadence, with mining and civil engineering demanding continuous monitoring capabilities that municipal surveying departments rarely require.
- Construction:General contractors prioritize layout speed and single-operator efficiency over sub-millimeter precision. Brazilian federal investment programs in transportation corridors are creating first-mover advantages for vendors with local calibration infrastructure.
- Surveying:Geodetic professionals enforce ISO 17123-4 qualification requirements that bifurcate vendor eligibility between certified precision manufacturers and uncertified assemblers.
- Mining:Extraction operators deploy automated target recognition for dam deformation and pit wall stability in remote sites where crew reduction delivers operational savings.
- Civil Engineering:Transportation and utility network designers face tightening seismic specifications in Japan and climate-load requirements in Germany.
Construction anchors unit volume through mid-tier contractor procurement. Mining is gaining share fastest through unmanned monitoring adoption.
Installation:
Permanence correlates with calibration investment and service contract attachment, with fixed installations generating recurring revenue streams that temporary deployments rarely capture.
- Permanent:Continuous monitoring installations for dam deformation and structural health require dense calibration networks. Trimble Inc. leverages its North American infrastructure to sustain premium positioning in these contracts.
- Temporary:Project-based deployment favors rental and subscription models. German and Japanese equipment-as-a-service providers are unbundling hardware, calibration, and software maintenance into usage-tiered contracts for municipal surveying departments.
- Mobile:Rapid relocation capabilities serve blast-pattern layout and emergency response surveying where site conditions shift frequently.
- Fixed:Semi-permanent installations balance stability with relocation flexibility for multi-phase infrastructure projects.
Permanent installations command the highest service attachment rates. Mobile configurations are expanding most quickly through Australian mining contractor adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German civil engineering firms anchor premium procurement for GNSS-integrated units, while Chinese domestic consolidation and Australian mining automation reshape regional demand patterns across precision construction markets.
United States
Federal transportation resilience programs drive permanent installation contracts for dam deformation monitoring. The FCC governs radio frequency emissions from robotic station telemetry, creating compliance thresholds for automated target recognition systems. Trimble Inc. leverages its North American calibration network to sustain premium positioning in infrastructure corridors across California and Texas.
Germany
Climate-load specifications for utility networks intensify hybrid positioning demand among civil engineering consortia. ECHA and national standards bodies enforce electromagnetic compatibility mandates for geodetic equipment deployment. The Rhine-Ruhr metropolitan cluster concentrates procurement authority for transportation corridor modernization projects.
China
State-backed infrastructure tenders eliminate marginal producers as MIIT certification mandates harden GB standards for geodetic instrument accuracy. The Ministry of Industry and Information Technology accelerates domestic manufacturer consolidation through mandatory pre-market electromagnetic compatibility testing. Yangtze River Delta engineering clusters absorb consolidated supply from surviving certified manufacturers.
Australia
Mining slope stability automation drives unmanned monitoring adoption across remote extraction sites. The TGA coordinates equipment safety frameworks that intersect with geospatial telemetry classifications. Western Australian pit operations deploy single-technician workflows replacing two-operator survey crews for blast-pattern layout.
Japan
Seismic resilience standards tighten procurement criteria for transportation network designers. METI coordinates JIS certification reciprocity agreements shaping cross-border eligibility for Southeast Asian public works agencies. Kanto region civil engineering firms expand GNSS-integrated unit deployment for earthquake-resistant infrastructure.
Robotic Total Stations (RTS) Market Key Industry Players
Player mix skews toward precision instrumentation conglomerates with dense calibration networks, compressing viable vendor pools for permanent installation contracts. The vendor base stratifies across three tiers: certified precision manufacturers sustaining ISO 17123-4 qualification, regional assemblers serving price-sensitive temporary deployments, and emerging domestic consolidators capturing state-backed infrastructure tenders. Dominant competitive moves include geographic expansion of service infrastructure and technology licensing for automated target recognition convergence.
Within the certified precision tier, Trimble Inc., Hexagon AB, and Topcon Corporation exemplify divergent geographic anchoring strategies. Trimble Inc. occupies a position calibrated to North American permanent installation density. Hexagon AB anchors European demand through its Leica Geosystems AG subsidiary concentration. Topcon Corporation sits within Asian civil engineering market specialization, competing on electro-optical product development.
| Leading Market Players |
|---|
| Trimble Inc. |
| Hexagon AB |
| Topcon Corporation |
| Leica Geosystems AG |
| South Surveying & Mapping Technology Co., Ltd. |
| Hi-Target Surveying Instrument Co., Ltd. |
| Suzhou FOIF Co., Ltd. |
| Guangdong Kolida Instrument Co., Ltd. |
| STONEX Srl |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Japanese and German precision encoder facilities shapes both component availability and price floors for electro-optical units. Dense calibration network investments by certified manufacturers create fixed-cost absorption advantages that uncertified assemblers cannot replicate, compressing viable competition in permanent installation contracts.
Pricing Analysis
Cost-plus contracts with semiconductor and optical component indexation dominate procurement agreements for GNSS-integrated configurations. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17123-4 certified precision manufacturers from regional assemblers and legacy mechanical unit suppliers. Pricing pressure stems from terrestrial LiDAR substitution in high-density documentation workflows. Municipal surveying departments exhibit highest price sensitivity, while mining operators prioritize unmanned monitoring capabilities over unit cost.
Supply Chain Analysis
Strategic stockpiling of precision encoder and distance measurement modules prevails among certified manufacturers, contrasting with just-in-time preferences for standard electro-optical assemblies. Component concentration in Japan and Germany for optical subsystems, plus Chinese domestic consolidation for GNSS modules, creates geographic dependency. Single-source vulnerability runs through Japanese electro-optical specialists for sub-arcsecond angular encoders. Distribution runs through authorized dealer networks with mandatory calibration service attachment for certified precision tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geodetic surveyor talent scarcity constrains commissioning velocity and elevates total cost of ownership, making technician pipeline investment as critical as hardware innovation for sustained market participation.
For Market Incumbents: Consolidate calibration network density in transportation corridor clusters to defend against equipment-as-a-service entrants. Deepen backward integration into precision encoder supply through captive relationships with Japanese optical specialists. Counter terrestrial LiDAR substitution by embedding edge-computing coordinate validation in hybrid robotic station cores. For New Entrants and Emerging Players: Anchor in Brazilian federal infrastructure programs where local service infrastructure gaps create first-mover advantages for vendors establishing calibration and maintenance presence. Target temporary deployment segments among municipal surveying departments facing compressed capital appropriations. Pursue JIS certification reciprocity pathways for Southeast Asian public works agency eligibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision instrumentation conglomerates with dense calibration networks and ISO 17123-4 qualification moats. Long-term viability hinges on automated target recognition convergence with machine vision and unmanned monitoring application expansion. Acquisition target archetype: regional assemblers with MIIT certification compliance and Yangtze River Delta manufacturing footprint. Watch electromagnetic compatibility mandate enforcement velocity in China as inflection indicator for domestic manufacturer consolidation pace.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | Dense service infrastructure in German and Australian mining clusters locks in permanent installation contracts. |
| Automated Target Recognition Convergence | Machine vision integration enables unmanned dam deformation monitoring for Japanese civil engineering consortia. |
| MIIT Certification Compliance | GB standards adherence qualifies vendors for state-backed Chinese infrastructure tenders eliminating marginal producers. |
| Equipment-as-a-Service Model Deployment | Usage-tiered contracts convert municipal surveying departments from capital to operational expenditure treatment. |
| Photogrammetry Payload Miniaturization | Single-tripod multi-sensor configurations displace two-operator crews in Western Australian blast-pattern layout. |
Research Approach
Initial hypotheses were tested against primary input from geodetic surveyors, civil engineering procurement managers, mining operations directors, and calibration service technicians and refined through secondary validation. Primary fieldwork combined structured interviews with equipment-as-a-service providers in Germany and Japan alongside aftermarket service heads at authorized dealer networks. Secondary sources encompassed FCC equipment authorization databases, MIIT certification registries, JIS standard documentation, and customs records for electro-optical component trade flows. Bottom-up unit economics triangulated against top-down infrastructure investment pipeline assessments.
Variance decomposition across product type, technology modality, end-user discipline, and installation permanence dimensions structured the analytical framework. Segmentation modeling incorporated precision tier, sensing configuration, geographic regulatory cluster, and customer sophistication level throughout the forecast period. CAGRs derived from installed base replacement cadence analysis and greenfield infrastructure procurement pipeline tracking. Industry-specific inputs included electromagnetic compatibility testing timeline impacts and dual-use export control classification volatility for automated target recognition subsystems.
Underlying assumptions cover infrastructure resilience standard enforcement continuity, with deviation risk concentrated in MIIT certification timeline extensions and geodetic surveyor training pipeline recovery rates. Forecasts reflect these conditions without scenario weighting. Revision becomes warranted when terrestrial LiDAR cost-performance ratios cross thresholds displacing conventional total stations in developed economy documentation workflows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Piling Machine Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Bulldozer Market
Construction Equipment
Tower Crane Market
Construction Equipment
ASEAN Construction Equipment Rental Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Cold Heading Machine Market
Construction Equipment
Global Excavators Market
Construction Equipment
Extrusion Equipment Market
Construction Equipment
Cutter Suction Dredger (CSD) Market