
 Through the Wall Radar Market | 2026-2036
Through the Wall Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Through the Wall Radar Market Insights
Buyer concentration is shifting as military and defense agencies consolidate procurement around fewer certified vendors while public safety agencies fragment demand across regional emergency response units. L3Harris Security & Detection Systems leverages its long-standing defense relationships to anchor premium contract flows. Camero competes through specialized ultra wideband radar expertise for urban operations. STM Savunma Teknolojileri Mühendislik dominates niche military specifications in Eastern European markets.
Through the wall radar systems detect motion and presence behind solid barriers using radio frequency signals typically operating between 1-10 GHz for concrete penetration and 10-20 GHz for drywall resolution. These systems serve primary commercial purposes in hostage rescue, collapsed structure search, and tactical building clearance where optical sensors fail. Ultra wideband radar leads product type margins due to superior range resolution and material penetration, while millimeter wave technology grows fastest among technology segments driven by semiconductor integration. Search and rescue applications sustain the largest application volume, though law enforcement segments attract higher per-unit pricing through ruggedization requirements.
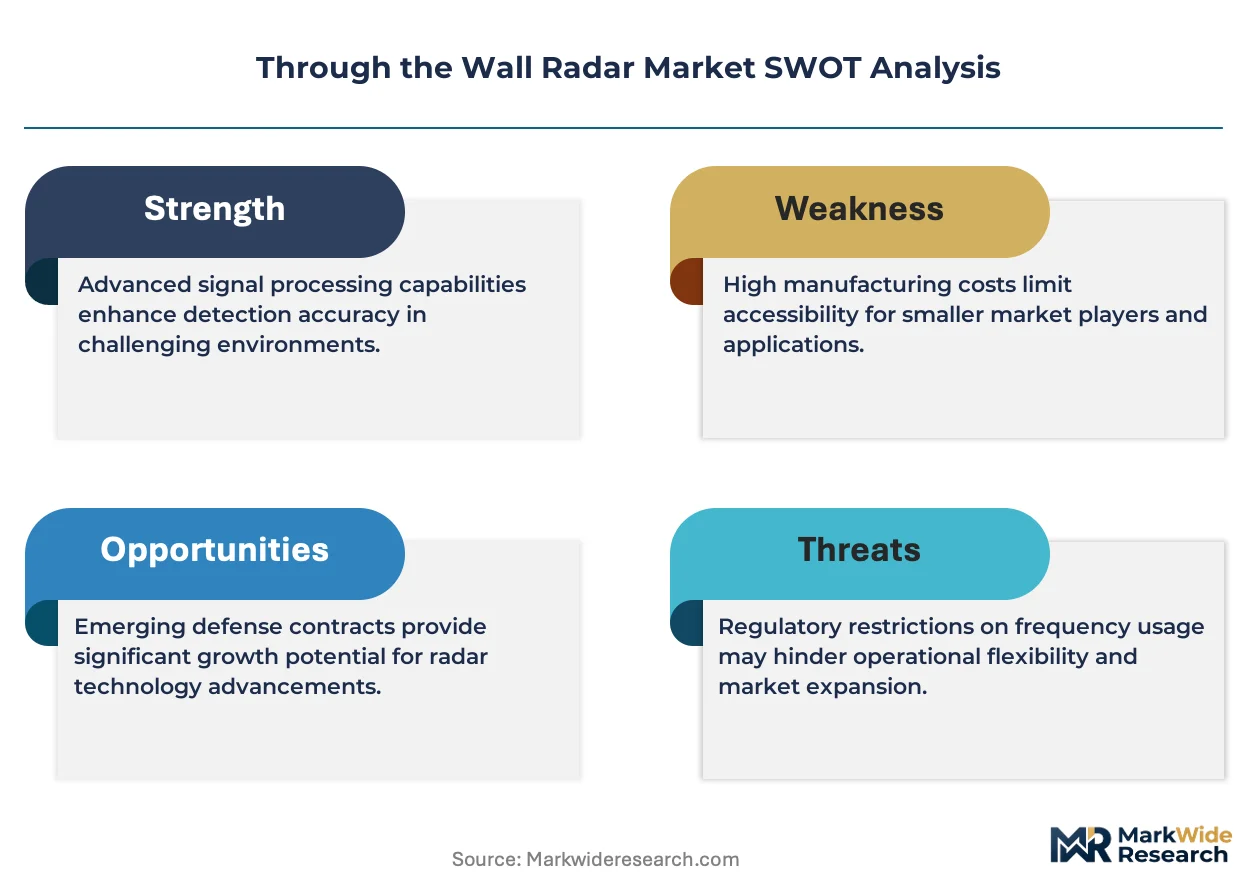
FCC equipment authorization shapes United States market access by mandating radio frequency emissions compliance for through wall radar devices. ETSI standards in Europe and China's MIIT radio regulations create parallel certification tracks that fragment vendor compliance costs. Military end users navigate ITAR export controls and country-specific defense procurement standards that limit technology transfer. Stakeholders must monitor evolving spectrum allocation decisions as 5G and Wi-Fi 6E expansion threatens interference management for ultra wideband deployments.
Market Dynamics
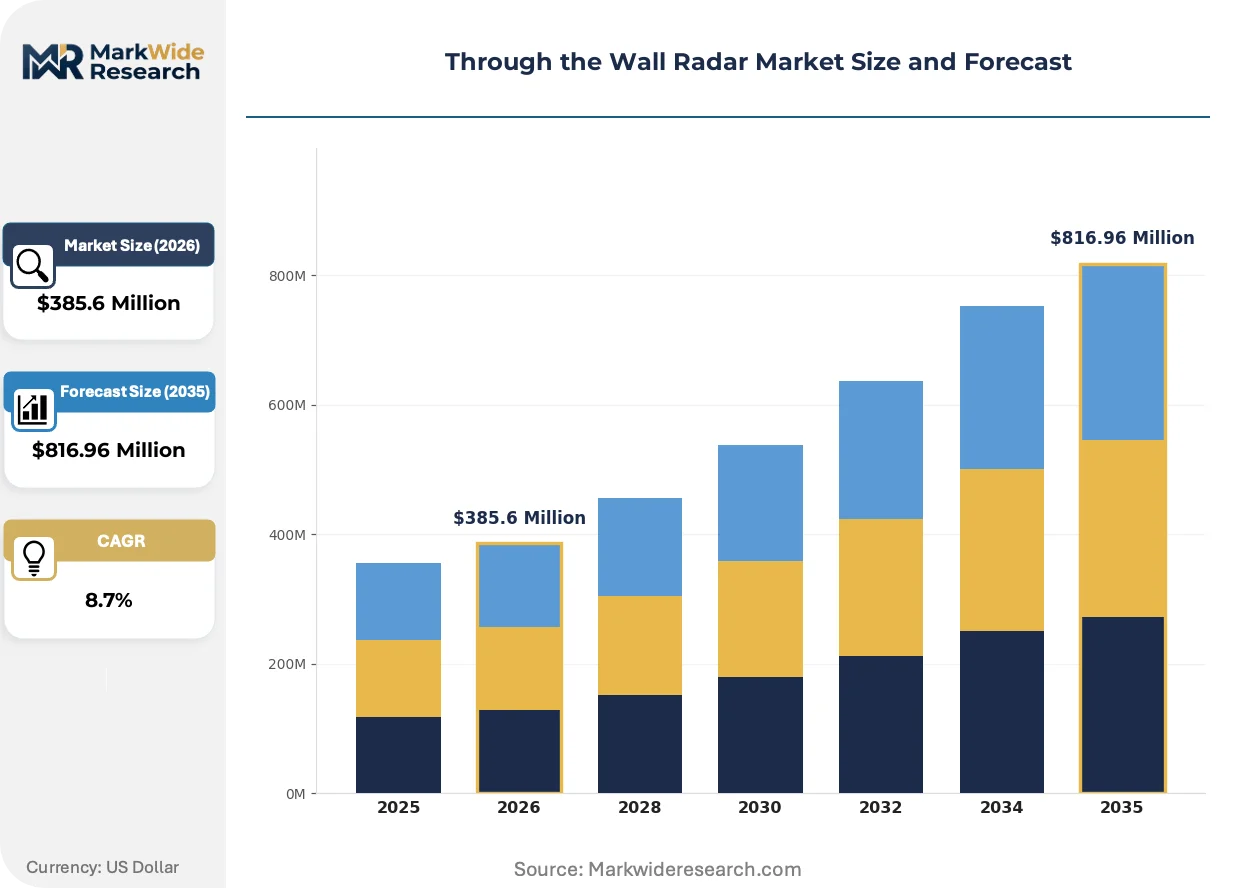
Military procurement consolidation around fewer certified vendors is compressing contract flows toward defense-integrated suppliers while fragmenting public safety demand across municipal emergency response units. FCC equipment authorization requirements create asymmetric compliance burdens that favor established players with dedicated regulatory affairs infrastructure.
Growth Catalysts
- Homeland Security Infrastructure:United States federal investments in urban counterterrorism capabilities are expanding deployment of through-wall radar systems for tactical building clearance and hostage rescue operations.
- Ultra Wideband Semiconductor Integration:Advances in gallium nitride and silicon germanium chipsets are reducing unit costs while improving range resolution for concrete penetration applications.
- ETSI Standard Harmonization:European Telecommunications Standards Institute radio equipment directives are creating unified certification pathways that reduce vendor compliance fragmentation across EU member states.
Market Restraints
- Spectrum Interference Risk:5G and Wi-Fi 6E expansion into C-band frequencies is crowding ultra wideband operational channels and forcing costly filter redesigns.
- ITAR Export Controls:United States International Traffic in Arms Regulations restrict technology transfer to non-allied nations and limit addressable market scope for defense-grade systems.
- Semiconductor Supply Concentration:Advanced RF component fabrication concentrates in East Asian foundries, exposing lead times to geopolitical disruption.
Strategic Opportunities
- Fire Service Integration:Underpenetrated municipal fire departments present white space for handheld through-wall radar deployment in collapsed structure search operations.
- AI-Enhanced Signal Processing:Machine learning algorithms for motion classification and false-positive reduction are converging with radar hardware to differentiate human signatures from environmental noise.
- India Smart Cities Mission:Urban disaster response infrastructure mandates under the national smart cities program are creating procurement channels for search and rescue equipment.
Industry Challenges
- RF Engineer Scarcity:Specialized expertise in antenna design and electromagnetic propagation for building materials remains concentrated in defense contractor talent pools.
- Multi-Jurisdiction Certification:Simultaneous FCC, ETSI, and MIIT compliance timelines extend product launch cycles by twelve to eighteen months.
- Legacy System Interoperability:Integration with existing command and control networks requires custom protocol adaptation for each defense procurement agency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Through the Wall Radar Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Wave Radar, Ultra Wideband Radar, Synthetic Aperture Radar, Frequency Modulated Radar Technology: Millimeter Wave, Doppler Radar, Pulse Radar, Phased Array Application: Search & Rescue, Law Enforcement, Disaster Management, Structural Inspection End User: Military & Defense, Public Safety Agencies, Civil Engineering Firms, Emergency Response Teams |
| Companies Covered | L3Harris Security & Detection Systems, Camero, STM Savunma Teknolojileri Mühendislik, Hunan NovaSky Electronic Technology, RETIA, AKELA, Acustek, VAWD Engineering, NovoQuad Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Through the Wall Radar Market Trends and Innovations
Semiconductor miniaturization and software-defined radio architectures are collapsing the traditional trade-off between penetration depth and spatial resolution. These technical shifts are enabling new form factors and use cases that expand addressable demand beyond military origins.
Ultra wideband radar is rewriting competitive positioning in urban operations by delivering centimeter-scale resolution through concrete and reinforced masonry. SWAT teams and special operations units are adopting handheld UWB systems for room-clearing scenarios where millimeter wave fails. This penetration capability is compressing the addressable market for competing acoustic and thermal imaging technologies in built-environment applications.
China's MIIT radio regulations for ultra wideband devices are tightening emission masks and mandating additional interference testing for civilian deployments. These requirements are extending product certification timelines and favoring domestic manufacturers with established regulatory relationships. Foreign vendors are responding by establishing joint ventures with local partners to navigate type approval processes.
Buyer preference is rotating toward multi-sensor fusion platforms that combine through-wall radar with video and acoustic inputs. Defense procurement agencies are consolidating specifications around integrated situational awareness systems rather than standalone radar units. This bundling trend is most visible in United States Special Operations Command requirements, where single-vendor platform awards are displacing component-level acquisitions.
Through the Wall Radar Market Segmentation
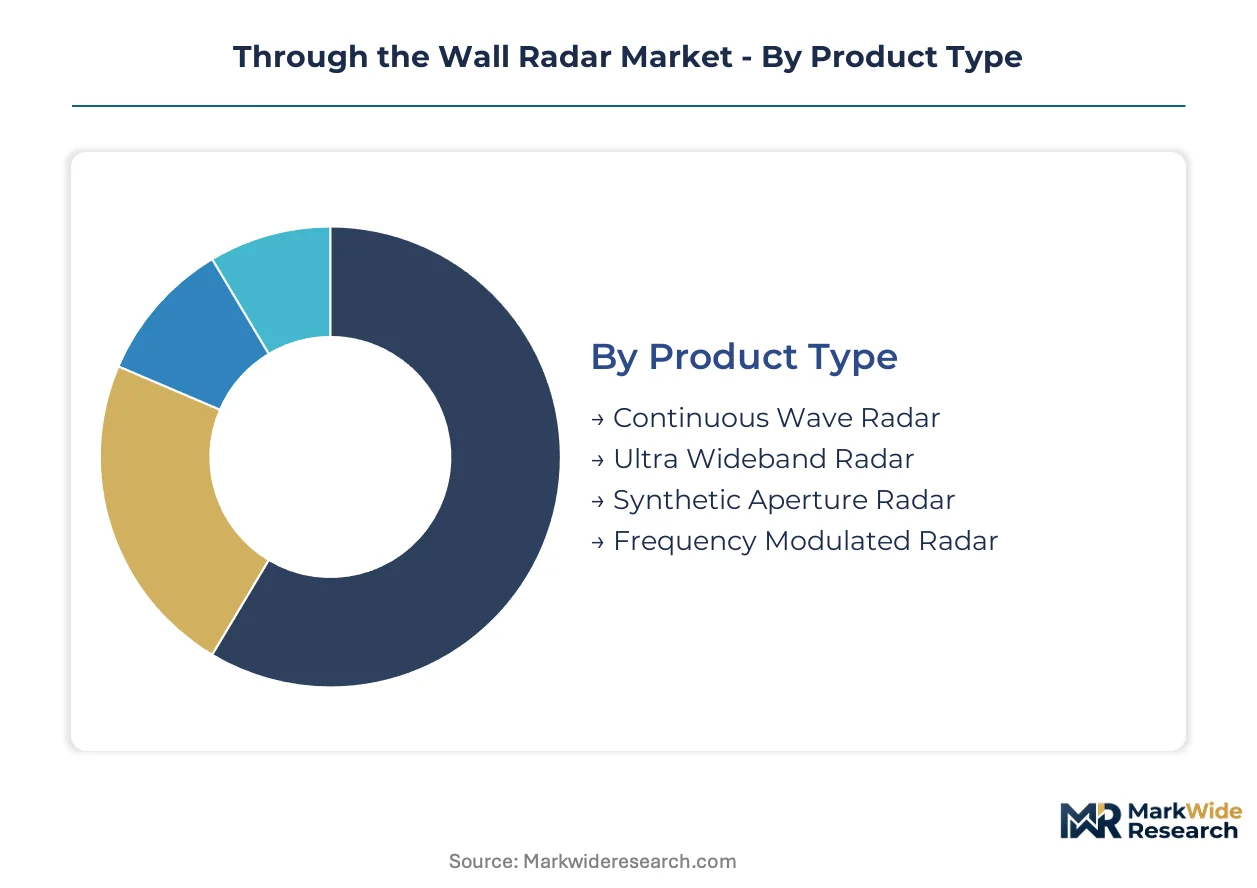
Through the wall radar systems fragment across four distinct segmentation axes, each reflecting divergent technical specifications and procurement pathways. Product type and technology dimensions capture hardware differentiation, while application and end-user categories map demand concentration across defense, public safety, and civil infrastructure verticals.
Product Type:
Ultra wideband architectures command premium positioning through superior material penetration and range resolution characteristics.
- Continuous Wave Radar:Emits unmodulated sinusoidal signals optimized for Doppler-based motion detection in short-range scenarios. Procurement concentrates in municipal law enforcement agencies seeking cost-effective handheld units for routine warrant service, constrained by limited concrete penetration depth.
- Ultra Wideband Radar:Leverages nanosecond-scale pulse transmission across gigahertz bandwidths to achieve centimeter-scale resolution through reinforced masonry. United States Special Operations Command and allied special forces units anchor demand through tactical building clearance contracts requiring simultaneous range and penetration performance.
- Synthetic Aperture Radar:Deploys signal processing algorithms to synthesize larger antenna apertures from mobile platforms. Civil engineering firms in Germany and Japan utilize SAR variants for bridge deck and tunnel linings inspection.
- Frequency Modulated Radar:Linear frequency sweep modulation enables simultaneous range and velocity measurement. Emerging adoption in India Smart Cities Mission urban disaster response procurement channels.
Mature deployment sits with Continuous Wave Radar. Newer deployment is concentrated in Ultra Wideband Radar.
Technology:
Semiconductor integration trajectories diverge across frequency bands, with millimeter wave and phased array architectures capturing divergent application requirements.
- Millimeter Wave:Operates above 30 GHz for fine spatial resolution in drywall and wooden barrier penetration. United States law enforcement SWAT teams drive volume through room-clearing scenarios where concrete penetration is unnecessary.
- Doppler Radar:Detects frequency shifts from moving targets to distinguish human signatures from static clutter. Search and rescue units in Turkey and Italy deploy Doppler systems for collapsed structure victim location.
- Pulse Radar:Time-of-flight measurement architecture enables straightforward range calculation with moderate component complexity. Emergency response teams in Brazil and South Africa favor pulse systems for budget-constrained municipal procurement.
- Phased Array:Electronically steerable beam forming eliminates mechanical scanning latency. Military end users in United Kingdom and Australia specify phased array for rapid multi-room surveillance in hostage rescue operations.
Phased Array commands the steepest expansion trajectory among defense-grade specifications. Pulse Radar dominates unit volume in emerging market public safety procurement.
Application:
Operational use cases stratify across threat response urgency and environmental complexity, with search and rescue sustaining baseline demand while law enforcement attracts premium pricing.
- Search & Rescue:Collapsed structure and wilderness victim location applications prioritize penetration depth over spatial precision. Fire departments in California, Texas, and Florida represent concentrated state-level procurement clusters.
- Law Enforcement:Tactical building clearance and warrant service operations demand rapid deployment with minimal training burden. FBI Hostage Rescue Team and equivalent federal units in France and Spain specify ruggedized handheld configurations.
- Disaster Management:Earthquake and industrial collapse response requires integration with urban search and rescue task force equipment caches. Japan's Fire and Disaster Management Agency maintains centralized procurement for prefecture-level distribution.
- Structural Inspection:Non-destructive evaluation of concrete integrity and rebar corrosion detection. German civil engineering consortiums and Dubai-based construction consultancies deploy vehicle-mounted systems for infrastructure monitoring.
Structural Inspection exhibits the most extended sales cycle due to engineering certification requirements. Law Enforcement generates the highest per-unit margins through ruggedization and training package bundling.
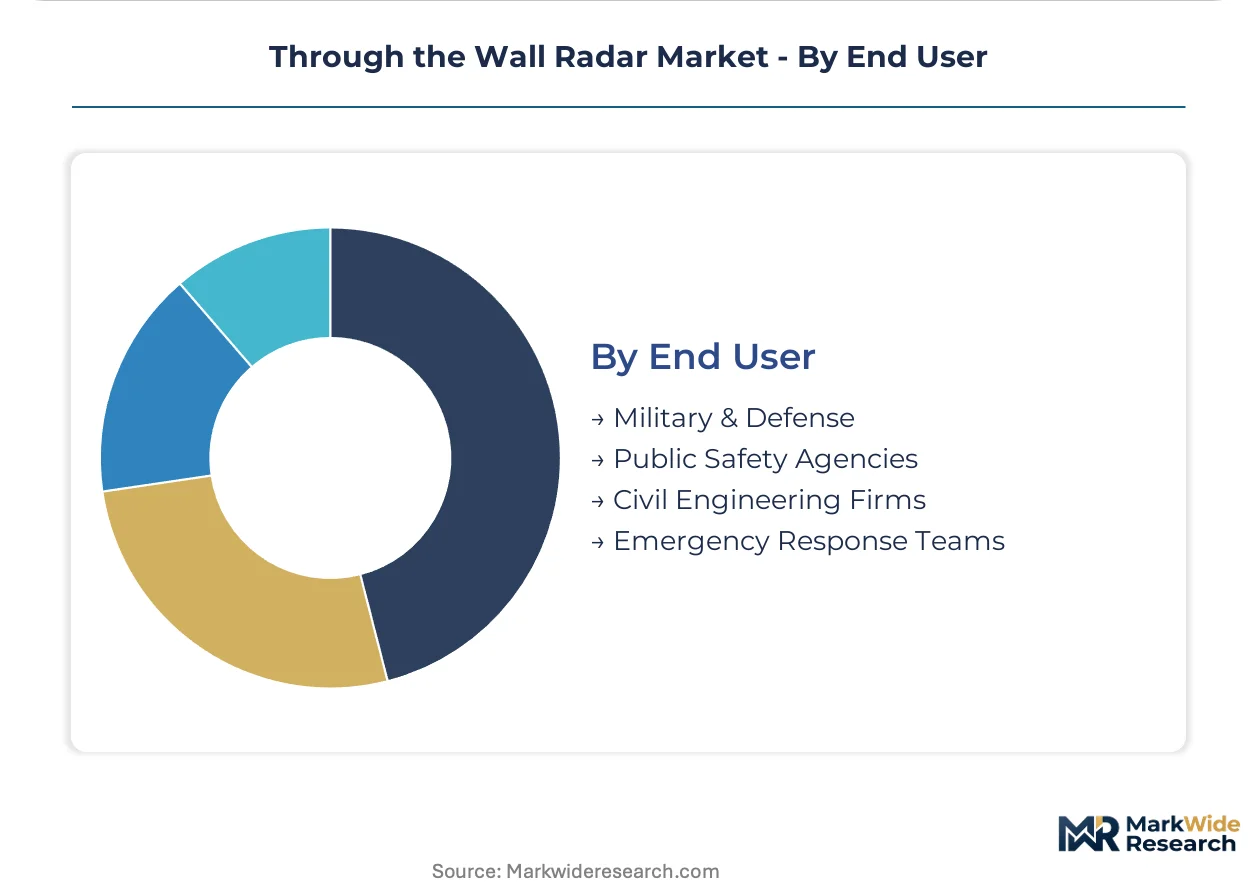
End User:
Procurement authority concentration varies sharply across customer categories, with defense agencies consolidating around integrated platform awards while public safety fragments across municipal jurisdictions.
- Military & Defense:Country-specific defense procurement agencies specify ITAR-controlled systems with custom protocol integration. United States Department of Defense, United Kingdom Ministry of Defence, and Turkish Defence Industry Agency anchor contract concentration.
- Public Safety Agencies:State and municipal police, fire, and emergency management departments operate fragmented procurement with heterogeneous technical requirements. California Office of Emergency Services and Texas Division of Emergency Management represent state-level aggregation points.
- Civil Engineering Firms:Commercial infrastructure inspection contractors seek FCC Part 15 compliant civilian variants without defense-grade encryption overhead. AECOM, WSP, and equivalent multinational engineering consultancies specify rental and lease arrangements over capital purchase.
- Emergency Response Teams:Urban search and rescue task forces and technical rescue squads require interoperability with existing thermal imaging and acoustic sensor suites. FEMA National USAR System and equivalent European Union Civil Protection Mechanism teams standardize equipment specifications.
Military & Defense procurement is consolidating around fewer certified platform vendors. Emergency Response Teams present the most heterogeneous specification environment due to international deployment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal agencies concentrate procurement authority for through-wall radar systems, while defense ministries in allied nations and municipal emergency services in emerging markets fragment demand across heterogeneous specifications.
United States
Department of Defense procurement through United States Special Operations Command and FBI Hostage Rescue Team drives premium-tier volume for tactical building clearance applications. FCC equipment authorization mandates under Part 15 and ITAR export controls shape vendor certification pathways and limit technology transfer scope. Defense contractors cluster around Washington D.C.-Northern Virginia corridor and Florida's Space Coast, where L3Harris Security & Detection Systems maintains established relationships with federal procurement channels.
Germany
Federal Police and state-level SEK units specify ETSI-compliant ultra wideband systems for counterterrorism operations, while civil engineering firms deploy synthetic aperture variants for infrastructure inspection. ETSI radio equipment directives harmonize certification across EU member states, reducing compliance fragmentation for vendors serving German procurement agencies. Industrial concentration in Bavaria and Baden-Württemberg hosts specialized RF component suppliers supporting domestic system integrators.
China
Ministry of Public Security procurement for urban counterterrorism and MIIT radio regulations for ultra wideband emission masks drive domestic manufacturer preference. MIIT tightens civilian deployment standards with additional interference testing requirements, extending certification timelines for foreign vendors. Domestic producers cluster in Shenzhen and Beijing technology corridors, where established regulatory relationships accelerate type approval processes.
United Kingdom
Ministry of Defence special forces procurement and Home Office counterterrorism grants sustain demand for phased array configurations in hostage rescue scenarios. ITAR alignment and post-Brexit UKCA marking requirements create parallel certification tracks for defense-grade systems. Defense technology suppliers concentrate in South East England and Scotland's central belt, serving integrated platform specifications from United Kingdom Special Forces.
India
Smart Cities Mission urban disaster response mandates and state police modernization programs create procurement channels for search and rescue equipment. Bureau of Indian Standards and Ministry of Home Affairs specifications guide equipment selection for municipal emergency response units. Industrial activity concentrates in Bengaluru and Hyderabad defense technology corridors, where local system integrators partner with foreign component suppliers.
Through the Wall Radar Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in AI-enhanced signal processing and multi-sensor fusion platforms. Contract flows compress toward defense-integrated suppliers with dedicated regulatory affairs infrastructure, while municipal procurement fragments across regional emergency response units. Three archetypes dominate: defense-anchored primes leveraging long-standing agency relationships, specialized ultra wideband technology developers, and regional system integrators navigating country-specific certification requirements. Competitive moves center on strategic partnerships for AI software integration and geographic expansion through joint ventures to satisfy local content mandates.
Within the defense-anchored tier, L3Harris Security & Detection Systems occupies a position exemplifying premium contract concentration around federal procurement channels. Camero represents the specialized technology archetype, with its company name signaling ultra wideband radar expertise. STM Savunma Teknolojileri Mühendislik anchors regional supply relationships in Eastern European defense markets. Hunan NovaSky Electronic Technology exemplifies domestic Chinese producers benefiting from MIIT regulatory alignment. These named entities illustrate how vendor positioning stratifies across certification infrastructure, technology specialization, and geographic regulatory access rather than scale alone.
| Leading Market Players |
|---|
| L3Harris Security & Detection Systems |
| Camero |
| STM Savunma Teknolojileri Mühendislik |
| Hunan NovaSky Electronic Technology |
| RETIA |
| AKELA |
| Acustek |
| VAWD Engineering |
| NovoQuad Group |
| Others |
Pricing and Supply Chain Analysis
United States Special Operations Command consolidation around integrated platform awards is compressing component-level procurement volumes and forcing suppliers to bundle AI-enhanced signal processing modules at fixed contract rates. This specification creep elevates certification costs for smaller vendors while locking in defense-anchored primes with existing FCC Part 15 and ITAR compliance infrastructure.
Pricing Analysis
Volume concentrates in Pulse Radar configurations for municipal emergency response units while margins concentrate in Phased Array systems for hostage rescue operations. Three-tier pricing structure across ITAR-controlled defense grade, ETSI-compliant commercial grade, and FCC Part 15 civilian certification levels separates buyer segments by compliance burden. Cost compression in the commercial tier is intensifying because semiconductor foundry allocation prioritizes defense-grade gallium nitride chipsets. Municipal fire departments exhibit the highest price sensitivity due to capital budget constraints, while United Kingdom Special Forces procurement shows minimal elasticity for rapid multi-room surveillance capabilities.
Supply Chain Analysis
Dual-sourcing requirements from United States Department of Defense procurement officers mandate qualified second sources for gallium nitride RF power amplifiers and silicon germanium transceiver chipsets. Advanced semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with backend packaging and testing distributed across Malaysia and Vietnam. Raw material dependencies include high-purity gallium substrates, ceramic antenna substrates, and specialized electromagnetic shielding alloys. Single-source vulnerability in East Asian foundry capacity exposes lead times to geopolitical disruption. Distribution runs through defense contractor prime channels for military end users and regional equipment distributors for municipal public safety agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FCC equipment authorization and ITAR export control compliance costs create a structural barrier-to-entry moat that favors incumbent vendors with dedicated regulatory affairs teams and existing federal procurement relationships.
For Market Incumbents: Cement platform-level contracts with United States Special Operations Command by integrating AI-enhanced motion classification software into existing ultra wideband hardware architectures. Expand backward integration into gallium nitride RF component supply to mitigate foundry allocation risk from East Asian concentration. Prioritize ETSI harmonization investments to capture European Union procurement consolidation under unified certification pathways. For New Entrants and Emerging Players: Launch via equipment rental and lease arrangements targeting civil engineering firms in Germany and Japan seeking synthetic aperture radar for infrastructure inspection without capital purchase burden. Target underpenetrated municipal fire departments in California, Texas, and Florida with handheld continuous wave radar units for collapsed structure search. Differentiate through machine learning false-positive reduction algorithms that reduce training requirements for volunteer emergency responders. For Investors and Strategic Acquirers: Re-rating potential sits with specialized ultra wideband technology developers given semiconductor miniaturization convergence with software-defined radio architectures expanding addressable use cases. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone, favoring acquisition targets with established FCC, ETSI, and MIIT certification timelines. Watch for spectrum allocation decisions affecting ultra wideband channel availability as the inflection indicator for hardware redesign cycles and filter cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Signal Processing Integration | Machine learning motion classification reduces false positives for FBI Hostage Rescue Team deployment scenarios. |
| Multi-Sensor Fusion Platform Development | Combined radar-video-acoustic systems meet United States Special Operations Command integrated situational awareness specifications. |
| ETSI Certification Harmonization Investment | Unified EU member state approval pathways reduce vendor compliance fragmentation for German Federal Police procurement. |
| Gallium Nitride RF Component Backward Integration | In-house power amplifier production secures foundry allocation priority for defense-grade ultra wideband systems. |
| Municipal Fire Service Channel Expansion | State-level emergency management aggregation points in California and Texas concentrate fragmented public safety demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with defense procurement officers, RF systems engineers, municipal emergency management directors, and regulatory affairs specialists at FCC-authorized equipment manufacturers. Secondary sources included FCC equipment authorization databases, ETSI radio equipment directive compliance registries, MIIT type approval records, Department of Defense contract award announcements, and Bureau of Indian Standards certification listings. Bottom-up unit shipment estimates by product type and technology segment were triangulated against top-down defense budget allocation analysis.
Granularity-level modeling captured product type differentiation across Continuous Wave, Ultra Wideband, Synthetic Aperture, and Frequency Modulated architectures; technology segmentation across Millimeter Wave, Doppler, Pulse, and Phased Array implementations; application stratification across Search and Rescue, Law Enforcement, Disaster Management, and Structural Inspection; and end-user categorization across Military and Defense, Public Safety Agencies, Civil Engineering Firms, and Emergency Response Teams. CAGRs were derived from regression analysis of historical procurement patterns and projected budget authorization trajectories across the analysis window. Forecast inputs incorporated semiconductor cost curves for gallium nitride and silicon germanium chipsets, plus spectrum allocation probability scenarios for ultra wideband operational channels.
The model assumes a particular technology adoption path; alternative pathways for millimeter wave semiconductor integration displacing ultra wideband in concrete penetration applications would alter the outlook. Forecasts reflect assumptions regarding sustained United States federal homeland security infrastructure investment, stable East Asian foundry capacity, and gradual ETSI standard harmonization across EU member states. Deviation in FCC spectrum reallocation decisions or MIIT emission mask tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
UWB Anchor Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Industrial Inertial Systems Market
Communication Navigation & Surveillance
Over the Horizon Radar Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
Space Situational Awareness (SSA) Systems Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market