
 Quicklime Market | 2026-2036
Quicklime Market Size, Share, and Industry Trends Forecast 2026-2036
Quicklime Market Outlook
Bulk-to-tote packaging flexibility is hardening buyer preference across the quicklime supply chain. Mississippi Lime leverages regional kiln networks to sustain just-in-time delivery for water treatment utilities. Carmeuse anchors European flue gas treatment demand through dedicated marine terminals. Lhoist Group competes on high-reactivity product grades for metallurgical clients.
Quicklime is calcium oxide produced by calcining limestone at temperatures exceeding 900 degrees Celsius, yielding a highly reactive alkaline material with typical calcium oxide content above 90 percent. Primary industrial purposes include steel slag conditioning, flue gas desulfurization, and water pH adjustment. Hydrated lime commands premium positioning in municipal water treatment where reactivity consistency matters. Metallurgy remains the volume anchor but flue gas treatment shows the fastest structural expansion as utilities retrofit scrubber systems. Bulk bag logistics dominate construction and agriculture where price sensitivity shapes procurement.
EPA emissions standards under the Clean Air Act mandate sulfur dioxide capture that directly expands quicklime consumption at coal-fired power plants. OSHA workplace exposure limits and REACH registration requirements in Europe shape product handling specifications and market access conditions. China's MEE enforces stricter industrial emission ceilings that filter low-purity suppliers from qualified vendor lists. Stakeholders must track regulatory divergence between emission-control stringency and carbon border adjustments to anticipate which product grades retain cross-border competitiveness.
Market Dynamics
Steelmakers in eastern China face GB standards tightening emission ceilings, forcing rapid purification upgrades across slag-conditioning operations and filtering marginal quicklime suppliers from qualified vendor lists.
Growth Catalysts
- EPA Clean Air Act mandates:Coal-fired utilities retrofit flue-gas scrubber systems, expanding high-reactivity quicklime consumption for sulfur dioxide capture.
- Water treatment infrastructure:Municipal utilities across the US Southeast prioritize pH adjustment consistency, driving specification-grade hydrated lime procurement.
- Marine terminal consolidation:Dedicated bulk-handling facilities at Rotterdam and Antwerp reduce demurrage costs for European metallurgical buyers.
Market Restraints
- Limestone feedstock volatility:Quarry permitting delays in the US Midwest constrain kiln input supply and elevate production costs.
- Single-source supply risk:High-calcium quicklime for specialized metallurgy concentrates among three coastal Chinese producer clusters.
- Dolomitic lime substitution:Magnesium-bearing alternatives capture share in agricultural soil amendment where reactivity tolerance is wider.
Strategic Opportunities
- Carbon capture integration:Direct air capture facilities in Texas and Louisiana pilot quicklime-based sorbent regeneration loops.
- India's PLI-linked chemical parks:Dedicated caustic-chlorine clusters in Gujarat create captive lime demand for captive brine processing.
- EU Green Deal carbon border adjustments:Low-carbon kiln technologies qualify for preferential tariff treatment, rewarding early adopters.
Industry Challenges
- Kiln operator skill scarcity:Experienced calcination engineers retire faster than vocational programs in Poland and Ukraine replenish talent pipelines.
- Legacy ERP integration:Batch-process quality data from older vertical-shaft kilns resist real-time connectivity with cloud-based procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quicklime Market |
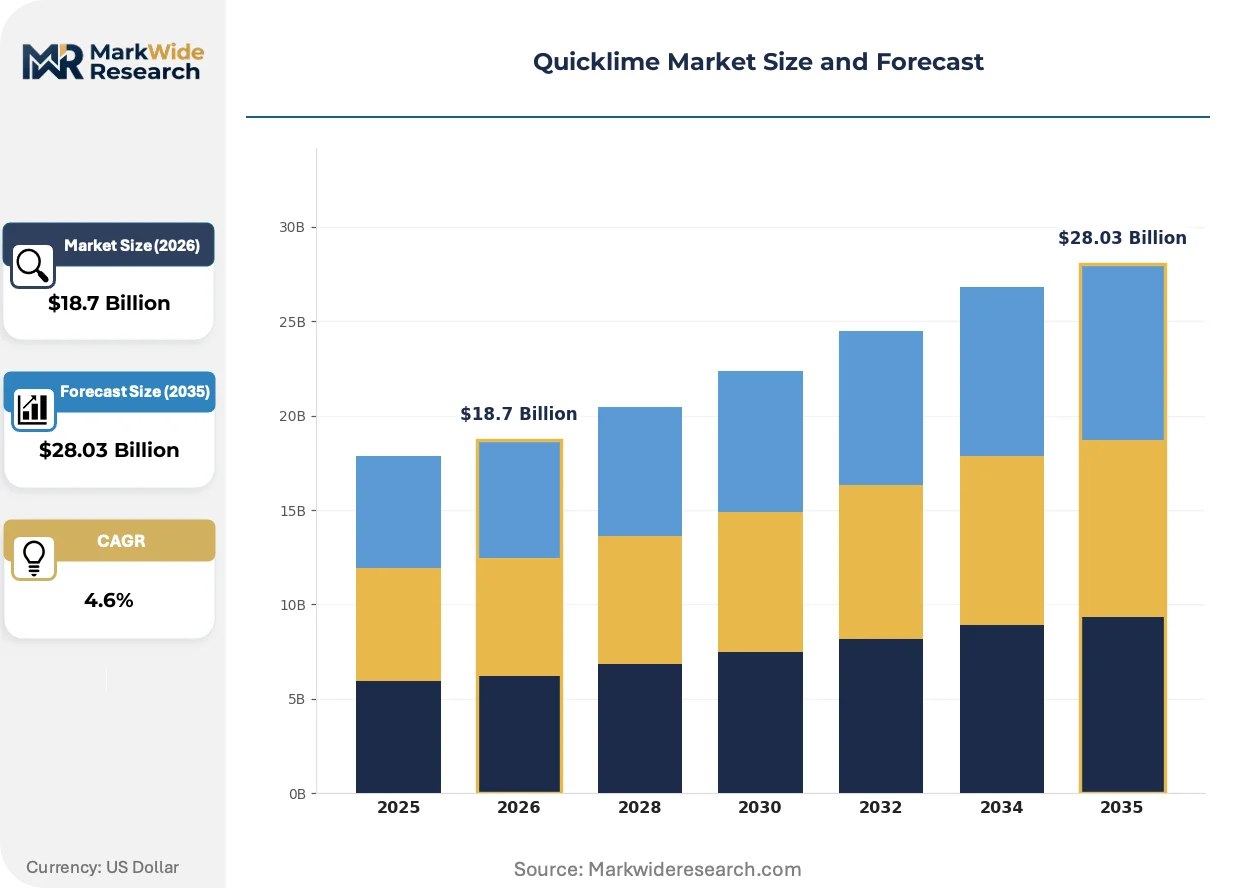
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
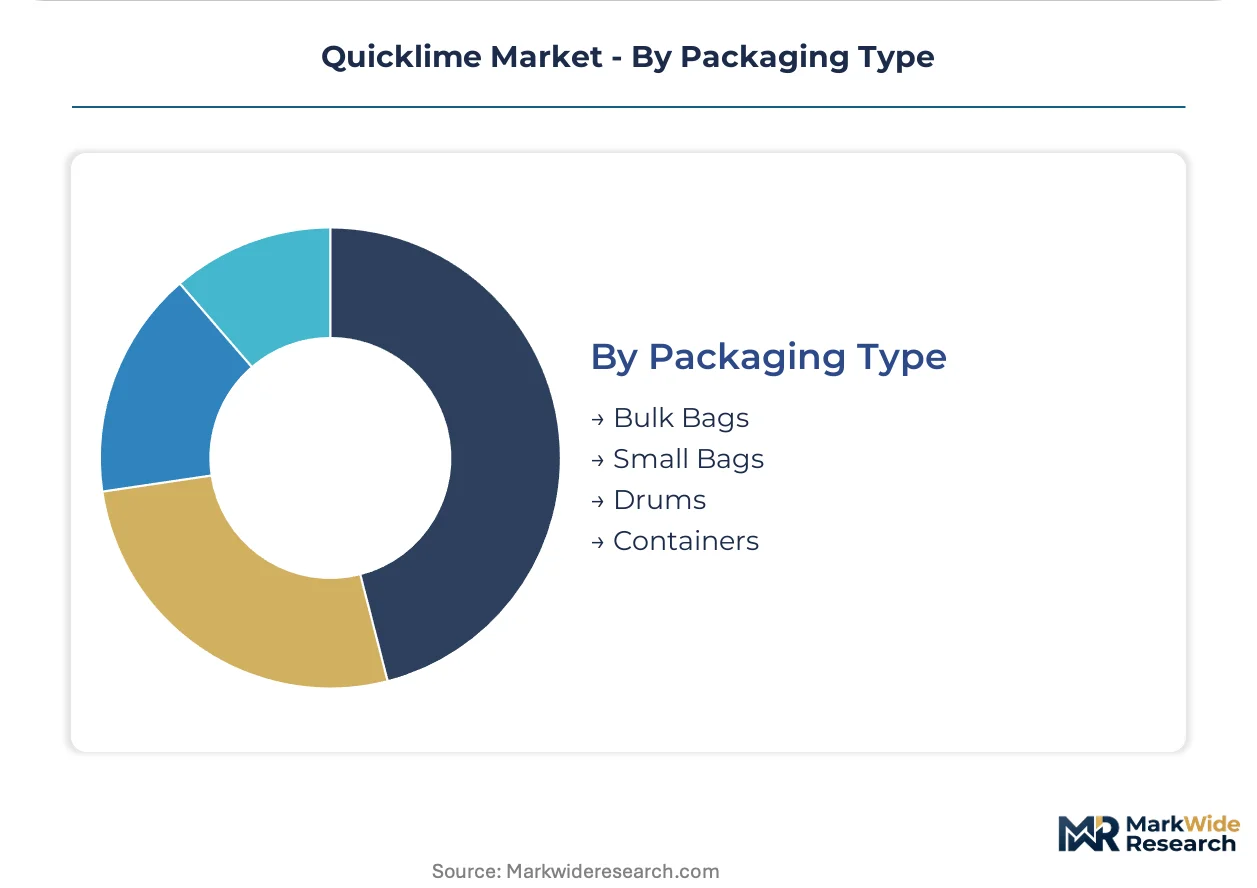
| Segmentation | Product Type: Shaped, Unshaped, Hydrated Lime, Quicklime End Use Industry: Chemicals, Metallurgy, Construction, Agriculture Application: Flue Gas Treatment, Water Treatment, Soil Stabilization, Pulp & Paper Packaging Type: Bulk Bags, Small Bags, Drums, Containers |
| Companies Covered | Martin Marietta Materials, Mississippi Lime, Carmeuse, Austin White Lime, Schäfer Kalk, Lhoist Group, United States Lime & Minerals, Pete Lien & Sons, Graymont Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quicklime Market Strategic Shifts
Calcination technology and logistics platforms are compressing delivery windows while regulatory stringency redefines product-grade specifications across steel, power, and water treatment verticals.
Parallel-flow regenerative kiln designs is modularizing capacity deployment for mid-scale producers. Water treatment utilities in the Ohio River Valley adopt containerized 50-ton-per-day units to bypass rail-dependent supply chains. This distributed architecture is modularizing the historical bulk-terminal model and enabling just-in-time inventory at municipal scale.
China's MEE enforcement of stricter industrial emission ceilings is disqualifying low-purity quicklime from qualified vendor lists. Steelmakers in Shandong and Jiangsu provinces now require calcium oxide content above 92 percent with controlled reactivity indices. High-specification product grades command procurement preference as environmental audits intensify.
Specification-driven buying is consolidating vendor relationships around certified reformance guarantees. Municipal water departments in Florida and Georgia replace spot-market purchasing with multi-year tolling agreements tied to delivered alkalinity outcomes. This contractual shift is most visible where EPA Safe Drinking Water Act compliance deadlines compress procurement decision cycles.
Quicklime Market Segmentation
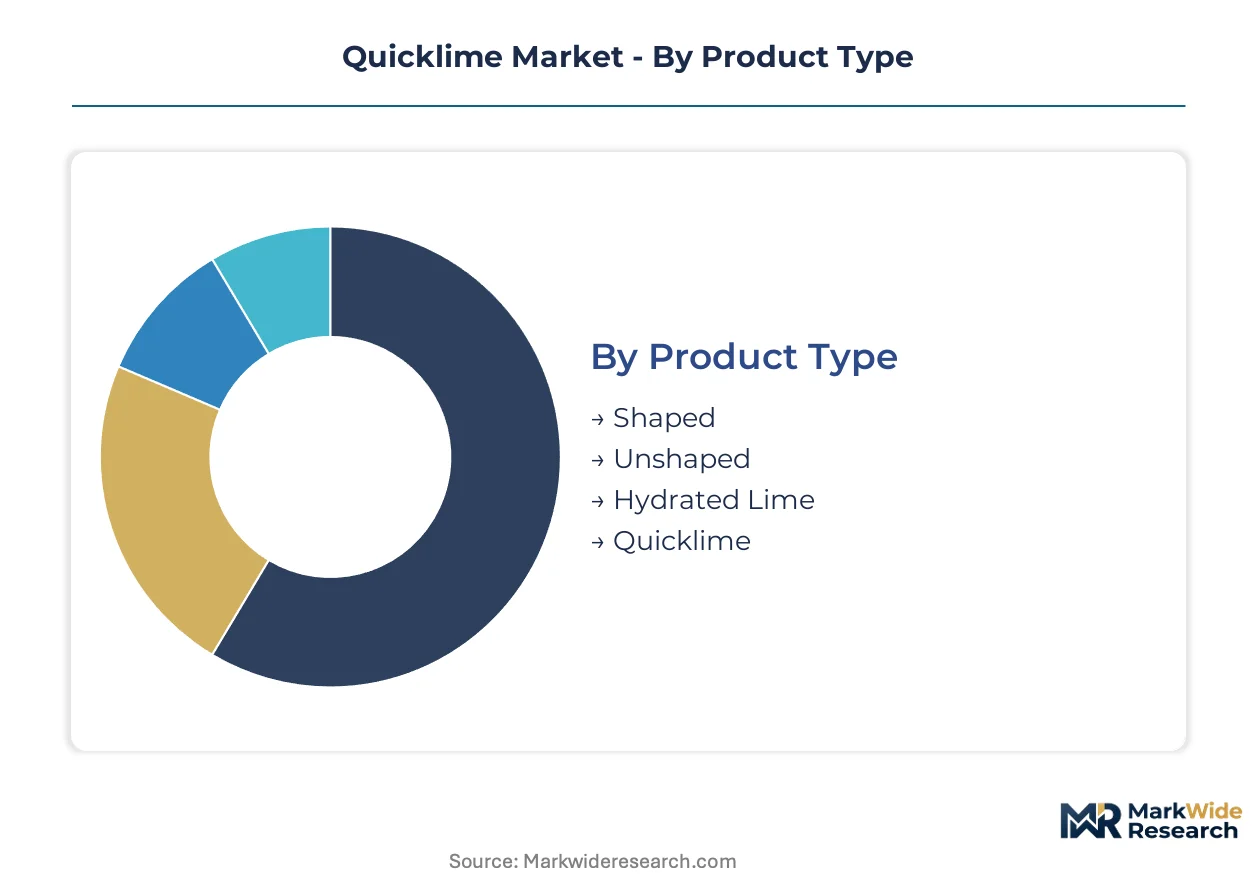
Quicklime procurement patterns diverge sharply across product chemistry, end-use specifications, and logistics requirements. Buyers in metallurgy prioritize reactivity consistency while water treatment utilities lock in multi-year supply contracts based on delivered alkalinity outcomes.
Product Type:
Product chemistry determines handling protocols, shelf stability, and reactivation requirements that separate premium from commodity procurement tiers.
- Shaped:Briquetted or pelletized quicklime offers controlled surface area for consistent reactivity in automated steel slag conditioning systems. Demand clusters in eastern Chinese coastal steel mills where GB standards enforce calcium oxide content above 92 percent.
- Unshaped:Crushed or ground quicklime in irregular particle distributions serves flue gas scrubber applications where rapid dissolution kinetics matter more than feed consistency. Coal-fired utilities across the US Southeast retrofit scrubber systems under EPA Clean Air Act mandates, expanding consumption of high-reactivity unshaped grades.
- Hydrated Lime:Calcium hydroxide produced through controlled slaking commands municipal water treatment premiums where pH adjustment precision affects Safe Drinking Water Act compliance.
- Quicklime:The base calcined product dominates metallurgical procurement volumes but faces purity filtering as China's MEE tightens industrial emission ceilings.
Volume sits with unshaped grades for power sector desulfurization; growth tilts toward shaped formats as steelmakers automate slag conditioning.
End Use Industry:
Industry-specific process temperatures and contamination tolerance create divergent specification ladders that reshape supplier qualification criteria.
- Chemicals:Caustic-chlorine and soda ash production consumes high-calcium quicklime for brine processing and alkali regeneration. India's PLI-linked chemical parks in Gujarat anchor captive demand for specification-grade material.
- Metallurgy:Steel slag conditioning represents the volume anchor, with calcium oxide content and reactivity indices directly affecting blast furnace efficiency. Shandong and Jiangsu province steel clusters enforce vendor list filtering that eliminates marginal purity suppliers.
- Construction:Soil stabilization and asphalt modification absorb lower-purity grades where price sensitivity outweighs reactivity precision. Quarry permitting delays in the US Midwest constrain kiln input supply for this segment.
- Agriculture:Soil pH amendment tolerates wider reactivity variance, opening substitution pressure from dolomitic lime alternatives with magnesium-bearing chemistry.
Metallurgy commands procurement concentration; chemicals exhibit the steepest expansion trajectory as chlor-alkali capacity scales in South Asia.
Application:
Environmental compliance deadlines and infrastructure retrofit cycles determine whether buyers prioritize spot availability or long-term tolling arrangements.
- Flue Gas Treatment:Sulfur dioxide capture at coal-fired power plants drives high-reactivity quicklime consumption under EPA mandates. Utilities prioritize bulk terminal access over product differentiation.
- Water Treatment:Municipal pH adjustment and softening processes favor hydrated lime for consistent reactivity. Florida and Georgia water departments shift from spot purchasing to multi-year tolling agreements tied to delivered alkalinity outcomes.
- Soil Stabilization:Highway construction and earthwork projects consume bulk quicklime for clay modification and bearing capacity improvement. Price sensitivity shapes procurement through construction seasonality.
- Pulp & Paper:Alkaline pulping and effluent neutralization require controlled reactivity for fiber quality protection. Mills in the US Pacific Northwest and Scandinavia specify low-impurity grades.
Water treatment anchors specification-grade premiums; flue gas treatment scales fastest as scrubber retrofits compress decision cycles.
Packaging Type:
Logistics economics and inventory turnover rates separate bulk-dependent industrial buyers from bagged-product distributors serving fragmented end-users.
- Bulk Bags:One-ton flexible intermediate bulk containers dominate construction and agriculture where mechanized handling and price sensitivity align. Mississippi Lime leverages regional kiln networks to sustain just-in-time delivery for water treatment utilities using this format.
- Small Bags:25-50 kilogram multi-wall paper bags serve agricultural retailers and specialty chemical formulators requiring inventory flexibility. Higher per-unit logistics costs limit this format to premium product grades.
- Drums:Steel or fiber drums contain hydrated lime for laboratory, food-grade, and specialty chemical applications where contamination control overrides cost.
- Containers:Intermodal tank and dry bulk containers enable marine terminal consolidation at Rotterdam and Antwerp, reducing demurrage costs for European metallurgical buyers.
Bulk bags concentrate procurement volume; containerized formats gain share fastest as marine terminal infrastructure consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the majority of quicklime output while the United States and Germany concentrate production capacity for export-grade material. Regional regulatory divergence on emission ceilings is fragmenting product specifications across steel and power sectors.
China
Steel slag conditioning absorbs bulk volumes in Shandong and Jiangsu provinces where coastal mill clusters enforce calcium oxide purity above 92 percent. MEE emission ceiling enforcement filters marginal suppliers from qualified vendor lists. Shandong steelmakers now require controlled reactivity indices for automated slag conditioning systems.
United States
Coal-fired utilities across the Southeast retrofit flue-gas scrubbers under EPA Clean Air Act mandates, expanding high-reactivity quicklime consumption. OSHA workplace exposure limits shape bulk-handling specifications at power plants. Mississippi Lime leverages regional kiln networks to sustain just-in-time delivery for Ohio River Valley water treatment utilities.
Germany
Metallurgical buyers prioritize marine terminal access at Rotterdam and Antwerp to reduce demurrage costs on high-calcium imports. REACH registration requirements govern product handling specifications and cross-border market access. Schäfer Kalk anchors supply relationships through dedicated bulk-handling infrastructure.
India
PLI-linked chemical parks in Gujarat generate captive lime demand for caustic-chlorine and soda ash production clusters. CEA power sector mandates on sulfur dioxide capture expand flue-gas treatment applications. Western India industrial corridors concentrate procurement around specification-grade material for chlor-alkali capacity expansion.
Belgium
Carmeuse anchors European flue gas treatment demand through dedicated marine terminals serving coal-to-gas transition utilities. EU Green Deal carbon border adjustments reward low-carbon kiln technology adopters with preferential tariff treatment. Antwerp-Rotterdam port complexes consolidate bulk logistics for metallurgical buyers.
Quicklime Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across quicklime supply chains. The vendor base organizes around three strategic archetypes: integrated construction-materials conglomerates with captive limestone reserves, regional kiln operators serving single-industry verticals, and marine-terminal specialists optimizing European bulk logistics. Dominant competitive moves include kiln network consolidation for just-in-time delivery coverage and backward integration into quarry assets to secure feedstock supply.
Within the integrated materials tier, Martin Marietta Materials exemplifies conglomerate positioning through construction-aggregate and lime verticals. Regional specialists Mississippi Lime and Lhoist Group occupy positions defined by geographic kiln density and metallurgical-grade product focus respectively. Carmeuse anchors the marine-terminal specialist archetype through Antwerp and Rotterdam bulk-handling infrastructure.
| Leading Market Players |
|---|
| Martin Marietta Materials |
| Mississippi Lime |
| Carmeuse |
| Austin White Lime |
| Schäfer Kalk |
| Lhoist Group |
| United States Lime & Minerals |
| Pete Lien & Sons |
| Graymont Limited |
| Others |
Value Chain & Pricing Dynamics
Steelmaker procurement concentration in eastern China's coastal mill clusters anchors contract-based long-term offtake pricing, with GB standards enforcement compressing spot-market flexibility for marginal purity grades.
Pricing Analysis
Margin tightening in specification-grade quicklime reflects MEE emission ceiling enforcement and kiln feedstock permitting delays. Three-tier pricing structure across high-purity metallurgical, standard flue-gas treatment, and economy construction grades separates certified reactivity guarantees from commodity spot material. Cost-down pressure on construction-grade material accelerates because quarry permitting bottlenecks in the US Midwest constrain kiln input supply. Water treatment utilities exhibit lowest price sensitivity due to Safe Drinking Water Act compliance deadlines, while agricultural soil amendment buyers face widest substitution pressure from dolomitic lime alternatives.
Supply Chain Analysis
Limestone feedstock supply rests on quarry operations in the United States, China, and Germany where permitting timelines and emission regulations shape kiln input availability. High-calcium quicklime production draws from pure limestone deposits, metallurgical coke or natural gas for calcination energy, and specialized refractory linings for kiln longevity. Single-source vulnerability concentrates in three coastal Chinese producer clusters serving specialized metallurgy. Distribution runs through marine terminal consolidation at Rotterdam and Antwerp for European buyers, regional kiln networks for just-in-time water treatment delivery, and bulk bag logistics for construction seasonality.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quicklime supply chains favor consolidation plays as MEE purity enforcement and carbon border adjustments filter marginal producers from qualified vendor lists.
For Market Incumbents: Deepen backward integration into captive limestone reserves to secure feedstock supply against quarry permitting delays. Anchor metallurgical relationships through certified reactivity guarantees that GB standards enforcement now mandates. Add modular kiln capacity in the Ohio River Valley to capture water treatment tolling agreement demand. For New Entrants and Emerging Players: Marine terminal operators in India and Southeast Asia represent the most penetrable channel partnership type for regional market entry. Target chlor-alkali capacity expansion in Gujarat's PLI-linked chemical parks where captive lime demand outstrips local supply. Pursue tolling agreement structures with municipal water departments replacing spot purchasing. For Investors and Strategic Acquirers: The window for entry favors regional kiln operators with marine terminal access and low-carbon kiln technology credentials. Mid-cap specialists with backward-integrated quarry assets and European carbon border adjustment readiness offer strongest long-term viability. Watch MEE audit intensity in Shandong and Jiangsu provinces as the signal for vendor list consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Secures limestone feedstock supply against US Midwest permitting delays and input cost volatility. |
| Low-Carbon Kiln Technology Transition | Qualifies European producers for EU Green Deal preferential tariff treatment on cross-border shipments. |
| Marine Terminal Infrastructure Expansion | Reduces demurrage costs for Rotterdam and Antwerp metallurgical buyers through dedicated bulk-handling facilities. |
| Multi-Year Tolling Agreements | Locks in Florida and Georgia water treatment demand through delivered alkalinity outcome contracts. |
| Modular Kiln Capacity Deployment | Enables Ohio River Valley utilities to bypass rail-dependent supply chains with containerized units. |
Study Parameters
Independent corroboration across plant managers at calcination facilities, procurement leads at steel mills and power utilities, distribution channel partners, and technical R&D directors underwrites the qualitative findings. Secondary validation draws from customs and trade data, EPA and MEE regulatory filings, SEC 10-K disclosures from listed lime producers, and industry association reports. Bottom-up capacity and consumption estimates triangulate against top-down macroeconomic indicators.
Historical reference periods anchor volume and value projections across the analysis window through regression-based modeling of kiln capacity utilization, end-use industry output correlations, and regulatory compliance cycle timing. Segmentation dimensions include product chemistry grade, end-use industry vertical, packaging format, and regional production hub clustering. CAGRs derive from elasticity-adjusted demand curves incorporating steel production forecasts, scrubber retrofit installation rates, and water infrastructure investment pipelines.
Several conditions sit outside the modeled scope, including abrupt limestone quarry moratoriums, unilateral tariff escalations on cross-border lime trade, and breakthroughs in alternative sulfur capture sorbents. Forecasts reflect assumptions about regulatory enforcement continuity and kiln technology adoption curves. A small set of named triggers warrants ongoing watch: MEE audit intensity escalation, EU carbon border adjustment implementation pace, and chlor-alkali capacity commissioning delays in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Mold Powders and Casting Fluxes Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
Oilfield Scale Inhibitors Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Bleaching Clay Market
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market