
 Cockroach Gel Baits Market | 2026-2036
Cockroach Gel Baits Market Size, Share, and Industry Trends Forecast 2026-2036
Cockroach Gel Baits Market Insights
The EPA's re-registration review of neonicotinoid compounds is restructuring active ingredient portfolios across the pest management industry. Bayer leverages its agrochemical heritage to sustain manufacturing scale in fipronil-based formulations. Syngenta anchors European distribution networks for professional applicators through specialized channel partnerships.
Cockroach gel baits are viscous, slow-acting toxicant formulations delivered in syringe tubes or bait stations, designed for targeted placement in harborage areas where palatability and delayed mortality enable horizontal transfer to colony members. The active ingredient dimension shows fipronil and hydramethylnon occupying distinct efficacy profiles against German and American cockroach species, while natural bait formulations are gaining shelf space in retail channels sensitive to pet and child safety concerns. Application segmentation reveals commercial kitchens and food processing plants generating premium pricing for professional-grade baits with documented HACCP compliance, whereas residential demand clusters around disposable tube formats in urban apartment markets.
The EPA regulates all pesticide products under FIFRA, requiring efficacy data and label restrictions that determine commercial versus residential sale classifications. REACH compliance in Europe governs active ingredient import thresholds and biocidal product authorization timelines. India's Central Insecticides Board mandates registration under the Insecticides Act for all imported formulations. Stakeholders must monitor regulatory divergence on neonicotinoid restrictions between the United States and European Union, as this will determine which chemistries retain multi-regional manufacturing viability.
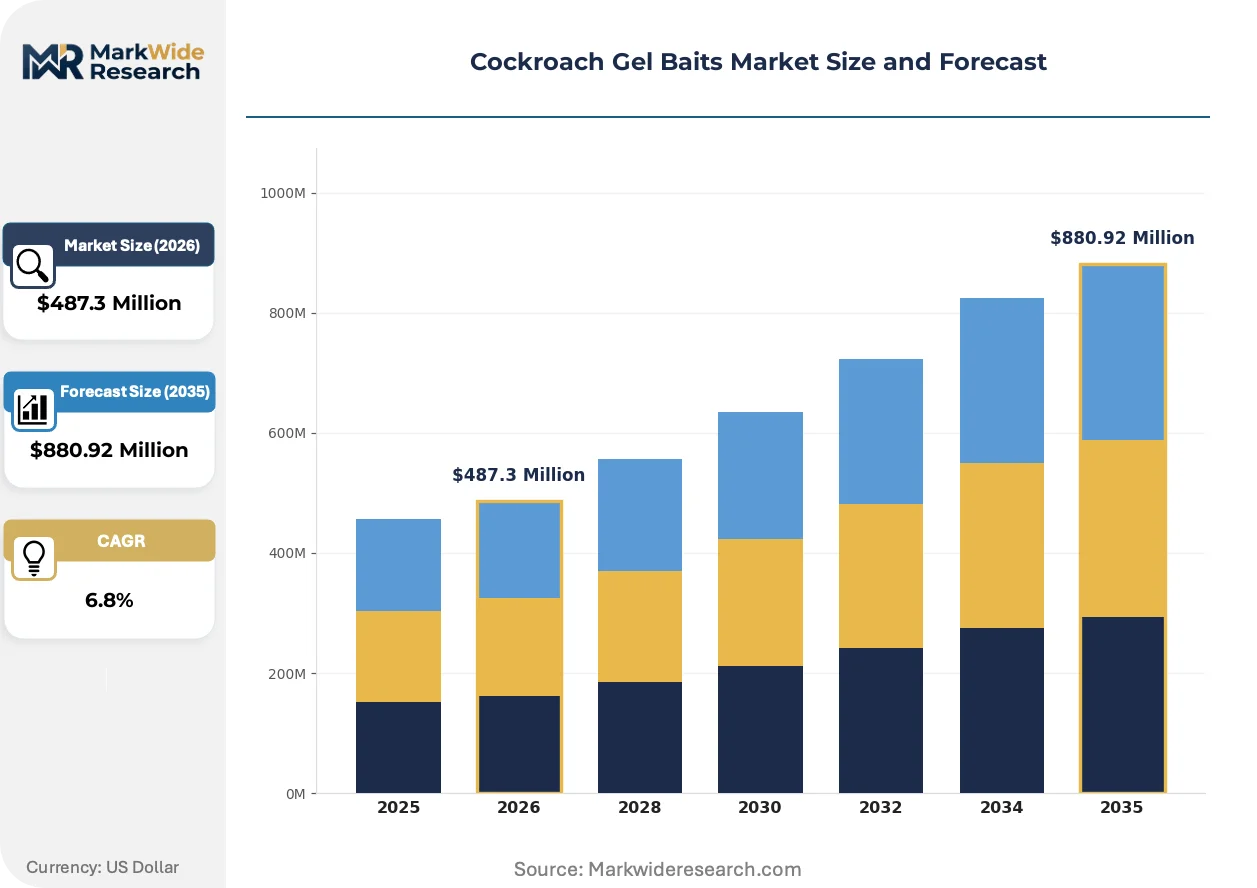
Market Dynamics
Regulatory pressure on neonicotinoid chemistries is fragmenting active ingredient supply chains across the pest management industry, forcing manufacturers to rebuild formulation portfolios around alternative toxicants.
Growth Catalysts
- Urban Vector Control Budgets:Municipal spending on integrated pest management programs in São Paulo, Mumbai, and Houston is expanding procurement volumes for professional-grade gel baits in dense residential corridors.
- FIFRA Registration Pathways:The EPA's streamlined biopesticide registration process is accelerating market entry for botanical active ingredient formulations targeting pet-sensitive retail channels.
- HACCP Compliance Mandates:Food processing facilities under USDA inspection are requiring documented bait rotation protocols, creating premium demand for multi-chemistry professional portfolios.
Market Restraints
- Active Ingredient Concentration:Fipronil technical manufacturing is consolidating among Chinese and Indian suppliers, exposing formulators to input cost volatility and supply interruption risks.
- REACH Authorization Timelines:ECHA's extended biocidal product evaluation periods are delaying new formulation launches across European professional channels by 18-36 months.
- Biological Substitute Performance:Boric acid and diatomaceous earth formulations remain less effective against German cockroach strains, limiting displacement of synthetic toxicants in severe infestation scenarios.
Strategic Opportunities
- Underpenetrated Municipal Sectors:Brazilian and Indian public housing authorities are adopting integrated vector management frameworks, opening institutional procurement channels previously served by spray contractors.
- IoT-Enabled Monitoring Convergence:Sensor networks detecting cockroach activity patterns are creating data-driven bait placement services that chemical manufacturers can bundle with consumable formulations.
- Green Building Certification Tailwinds:LEED and BREEAM standards rewarding reduced pesticide applications are driving specification of gel bait systems in commercial construction projects.
Industry Challenges
- Toxicology Assessment Capacity:Formulators face acute shortages of entomologists and regulatory toxicologists capable of navigating divergent residue tolerance standards across the US, EU, and India.
- Horizontal Transfer Validation:Demonstrating colony-level mortality efficacy requires specialized laboratory facilities and extended study protocols that strain R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cockroach Gel Baits Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticide Baits, Natural Baits, Professional-Grade Baits, Retail Baits Active Ingredient: Hydramethylnon, Fipronil, Abamectin, Imidacloprid Application: Commercial, Residential, Industrial, Institutional Packaging Type: Tubes, Sachets, Disposable Units, Refillable Containers |
| Companies Covered | Bayer, Syngenta, MGK, Combat, Rockwell Labs, Sumitomo Chemical, BASF, McLaughlin Gormley King, Ensystex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cockroach Gel Baits Market Trends and Innovations
Formulation science is pivoting toward precision delivery systems that minimize non-target exposure while maximizing colony-level mortality through secondary transfer mechanisms.
Microencapsulated bait matrices are modularizing active ingredient release profiles, enabling formulators to tune palatability duration against specific cockroach species feeding behaviors. Commercial kitchen operators in the United States are adopting these systems to reduce bait replacement frequency in high-temperature environments. The technology is compressing service intervals for pest management professionals and shifting revenue models toward product-centric rather than labor-centric contracts.
REACH's evolving substance restriction criteria are forcing European manufacturers to eliminate certain synergist compounds from gel bait formulations. The regulatory consequence is a search for alternative penetration enhancers that maintain efficacy without triggering authorization requirements. Professional applicators in Germany and France are responding by stockpiling legacy formulations ahead of anticipated compliance deadlines.
Facility managers are consolidating vendor relationships around full-service pest management contracts that unbundle chemical supply from application labor. Food processing plants in the US Midwest are leading this transition, specifying multi-year service agreements with guaranteed efficacy metrics. The shift is most visible in large-scale bakery and protein processing operations where audit frequency has intensified under customer-driven food safety certifications.
Cockroach Gel Baits Market Segmentation
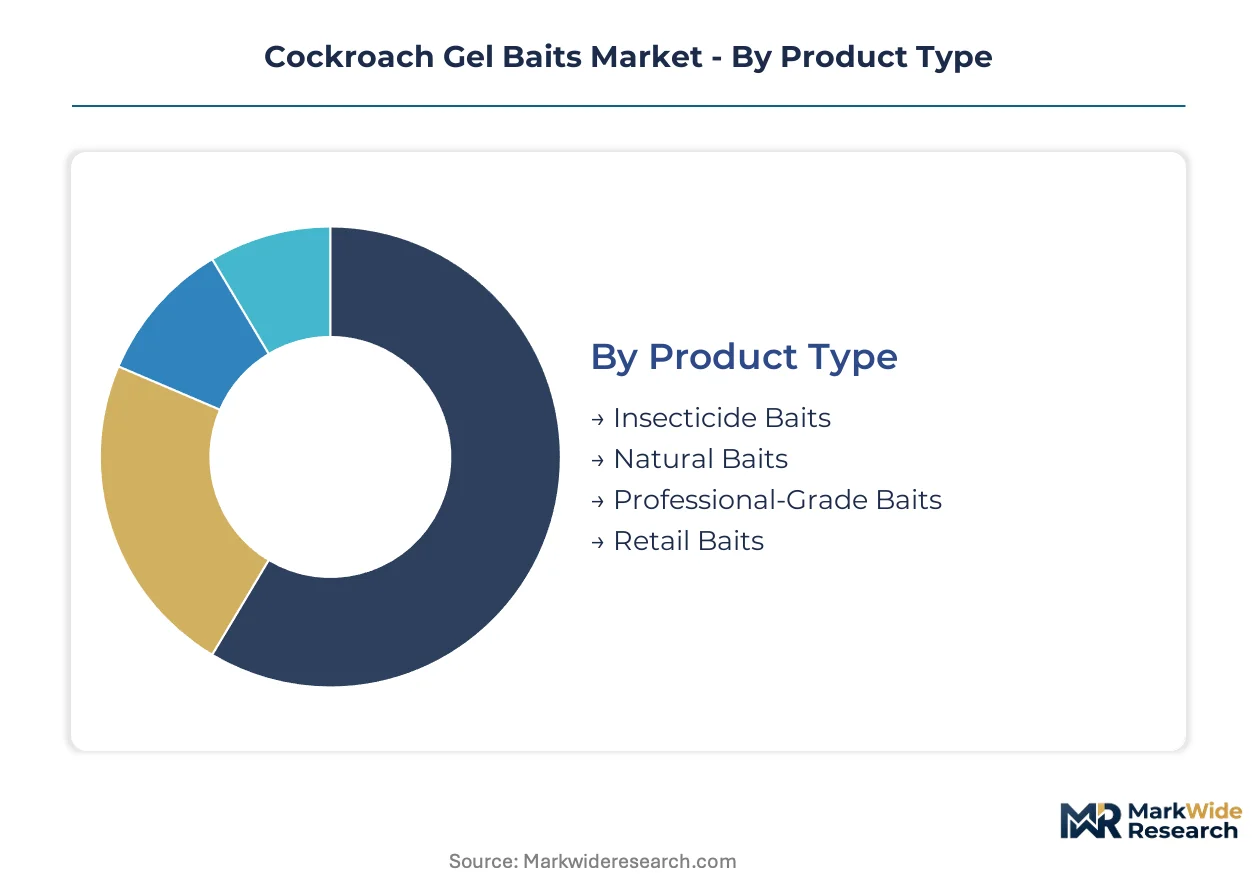
Segmentation in cockroach gel baits reveals how procurement specifications diverge between regulatory environments and end-use risk tolerances. Buyers sort formulations by toxicity classification, application setting, and packaging economics rather than brand loyalty alone.
Product Type:
Professional buyers prioritize efficacy documentation and regulatory compliance over unit cost when selecting formulation tiers.
- Insecticide Baits:Synthetic toxicant formulations leveraging fipronil, hydramethylnon, or neonicotinoid chemistries deliver rapid knockdown and horizontal transfer. Municipal vector control programs in Houston and São Paulo specify these for severe infestation corridors where colony elimination is mandatory.
- Natural Baits:Botanical and mineral-based formulations using boric acid or essential oil extracts target pet-sensitive households and LEED-certified facilities. Retail channels in Germany and France are expanding shelf space for these products ahead of REACH authorization deadlines for synthetic synergists.
- Professional-Grade Baits:Concentrated formulations with documented HACCP compliance and bait rotation protocols for food processing audits.
- Retail Baits:Pre-filled disposable tubes and bait stations designed for consumer self-application in urban apartment markets.
Insecticide baits lead on scale; natural baits lead on momentum.
Active Ingredient:
Regulatory re-registration timelines determine which chemistries retain multi-regional manufacturing viability.
- Fipronil:Phenylpyrazole compound disrupting GABA-gated chloride channels delivers delayed mortality enabling secondary transfer. Chinese and Indian technical manufacturers dominate supply, exposing formulators to input cost volatility.
- Hydramethylnon:Metabolic inhibitor effective against both German and American cockroach species with established residue tolerance databases. USDA-inspected protein processing plants in the US Midwest specify this chemistry for documented rotation protocols.
- Abamectin:Fermentation-derived avermectin compound with distinct resistance profile from phenylpyrazoles and neonicotinoids.
- Imidacloprid:Neonicotinoid facing EPA re-evaluation and EU restrictions, compressing its addressable market to regions with less stringent pollinator protection standards.
Fipronil dominates current procurement volumes; hydramethylnon offers the steadiest regulatory pathway.
Application:
Facility audit frequency and liability exposure determine whether buyers self-apply or contract professional services.
- Commercial:Food service and hospitality operations requiring documented pest management for insurance and brand protection. Fast-casual restaurant chains in US urban corridors are consolidating vendor relationships around full-service contracts with guaranteed efficacy metrics.
- Residential:Urban apartment dwellers in Mumbai and São Paulo purchasing disposable tube formats through retail and e-commerce channels.
- Industrial:Manufacturing and logistics facilities with integrated pest management specifications tied to customer-driven certifications.
- Institutional:Public housing authorities, schools, and healthcare facilities adopting vector management frameworks with public procurement transparency requirements.
Commercial applications command premium pricing; institutional channels are expanding most quickly in Brazil and India.
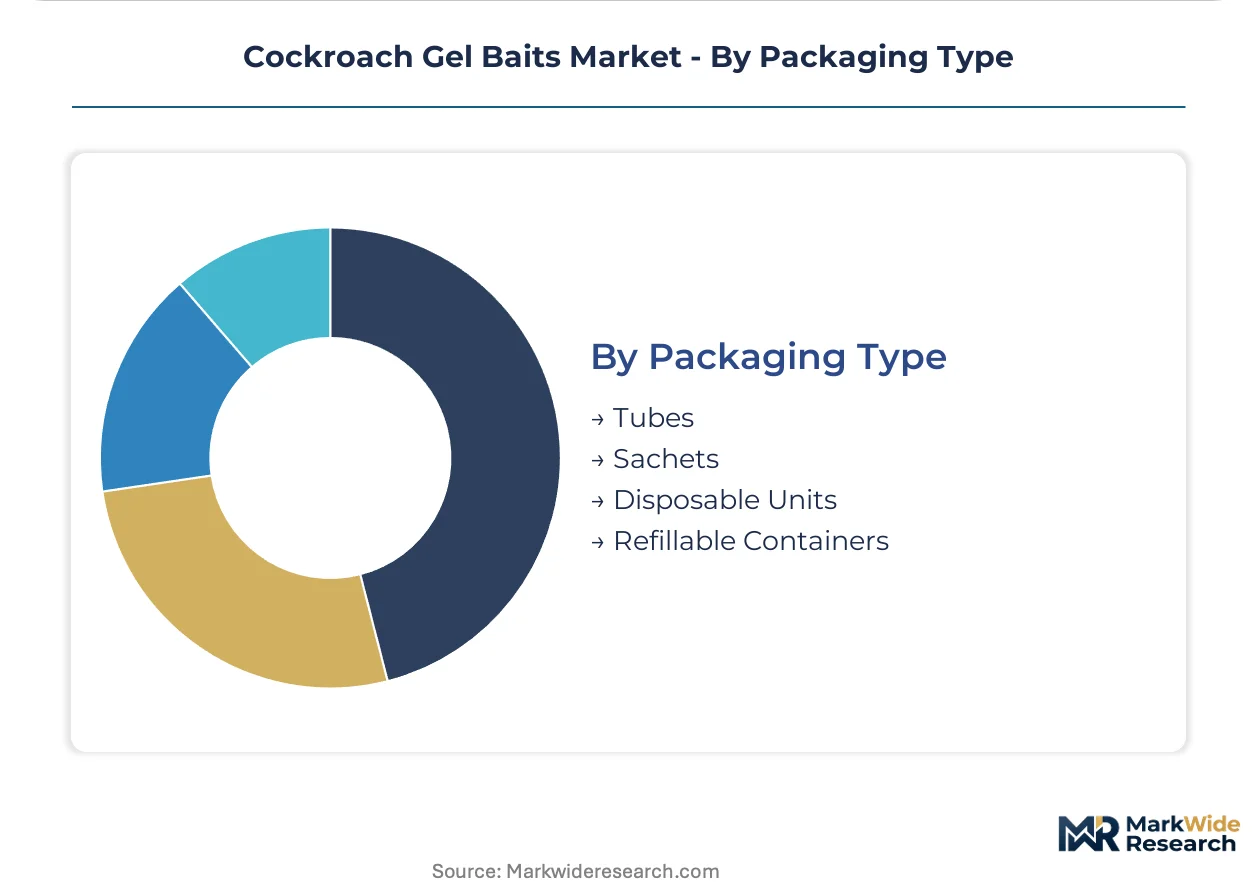
Packaging Type:
Service interval economics and storage conditions determine format selection across climate zones.
- Tubes:Syringe-dispensed gel enabling precise placement in harborage cracks and crevices. Pest management professionals in high-temperature commercial kitchens prefer microencapsulated tube formulations that extend palatability duration.
- Disposable Units:Pre-loaded bait stations with tamper-resistant housings for residential and institutional settings where child and pet safety is paramount.
- Sachets:Single-use pouches for bulk procurement in municipal vector control programs.
- Refillable Containers:Reusable bait station systems for facilities with permanent monitoring infrastructure.
Tubes dominate professional service revenue; disposable units are gaining share fastest in retail channels sensitive to safety perceptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cockroach gel baits industry traces its commercial origins to post-war urban pest management programs in the United States, where syringe-dispensed toxicant formulations first displaced spray-based methods in municipal housing authorities during the 1980s.
United States
Commercial food service operators in Houston and Chicago are expanding procurement of professional-grade fipronil formulations for HACCP-compliant facilities. EPA re-registration reviews of neonicotinoid compounds are compressing the addressable market for imidacloprid-based products ahead of pollinator protection rulemakings. Fast-casual restaurant chains across the Midwest are consolidating vendor relationships around full-service contracts with guaranteed efficacy metrics.
Brazil
Municipal vector control programs in São Paulo are adopting integrated pest management frameworks with expanded gel bait procurement for dense public housing corridors. ANVISA's biocidal product registration timelines are accelerating relative to European counterparts, attracting formulation investments from multinational suppliers. Brazilian public housing authorities are opening institutional channels previously served exclusively by spray contractors.
Germany
Professional applicators in Bavaria and North Rhine-Westphalia are stockpiling legacy formulations ahead of REACH authorization deadlines for certain synergist compounds. ECHA's extended biocidal product evaluation periods are delaying new formulation launches by 18-36 months across German distribution networks. Retail channels in Frankfurt and Munich are expanding shelf space for botanical formulations targeting pet-sensitive households.
India
Urban apartment dwellers in Mumbai and Delhi-NCR are driving retail demand for disposable tube formats through e-commerce and modern trade channels. The Central Insecticides Board's registration requirements under the Insecticides Act govern all imported formulations entering Indian ports. Municipal corporations in Maharashtra are expanding vector-borne disease control budgets with integrated cockroach management in slum rehabilitation projects.
China
Technical manufacturing of fipronil active ingredient concentrates in Jiangsu and Zhejiang provinces supplies formulators across Asia-Pacific and North American markets. MEE environmental compliance inspections are consolidating production capacity among larger chemical manufacturers with captive waste treatment infrastructure. Pest management professionals in Shanghai and Guangzhou are adopting microencapsulated bait matrices for high-temperature commercial kitchen environments.
Cockroach Gel Baits Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance and documentation capabilities in this market. The vendor base clusters around three distinct tiers: multinational agrochemical conglomerates with FIFRA registration infrastructure, mid-scale specialty formulators serving regional professional channels, and private-label assemblers competing on unit cost in retail segments. Dominant competitive moves include portfolio diversification into botanical formulations ahead of neonicotinoid restrictions and backward integration into active ingredient technical manufacturing.
Within the multinational tier, Bayer and Syngenta occupy positions anchored by agrochemical heritage and global registration infrastructure. BASF represents the specialty chemical conglomerate archetype with integrated formulation science capabilities. Among mid-scale specialists, Rockwell Labs and Ensystex exemplify focused players serving professional applicator channels with documented efficacy portfolios. MGK and Combat sit within the consumer-accessible segment, with the latter representing brand-driven retail positioning. Sumitomo Chemical anchors the Asia-Pacific technical manufacturing vector for phenylpyrazole supply chains.
| Leading Market Players |
|---|
| Bayer |
| Syngenta |
| MGK |
| Combat |
| Rockwell Labs |
| Sumitomo Chemical |
| BASF |
| McLaughlin Gormley King |
| Ensystex |
| Others |
Pricing and Supply Chain Analysis
Microencapsulated bait matrix technology is compressing service intervals and shifting revenue models toward product-centric contracts, simultaneously concentrating manufacturing scale among technical suppliers in China and India while fragmenting pricing power across regional formulators.
Pricing Analysis
Three-tier pricing structure across professional-grade, retail, and municipal procurement levels dominates transaction economics. Price differentiation hinges on HACCP certification documentation and volume scale in institutional tenders. Cost compression in retail channels is intensifying because private-label assemblers are eroding brand premiums in disposable tube formats. Municipal vector control programs exhibit lowest price sensitivity due to audit-driven efficacy mandates, while urban apartment dwellers in emerging markets drive hardest bargain negotiations.
Supply Chain Analysis
Freight cost volatility from Chinese and Indian technical manufacturing hubs to North American and European formulation plants is reshaping regional sourcing strategies. Active ingredient supply concentrates in Jiangsu and Zhejiang provinces of China, with secondary technical manufacturing in Gujarat and Maharashtra states of India. Raw material dependencies include fipronil technical, hydramethylnon intermediates, and microencapsulation polymers. Single-source vulnerability in phenylpyrazole technical supply exposes formulators to input cost shocks. Distribution runs through specialized pest management professional channels in developed markets, with modern trade and e-commerce gaining share in retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
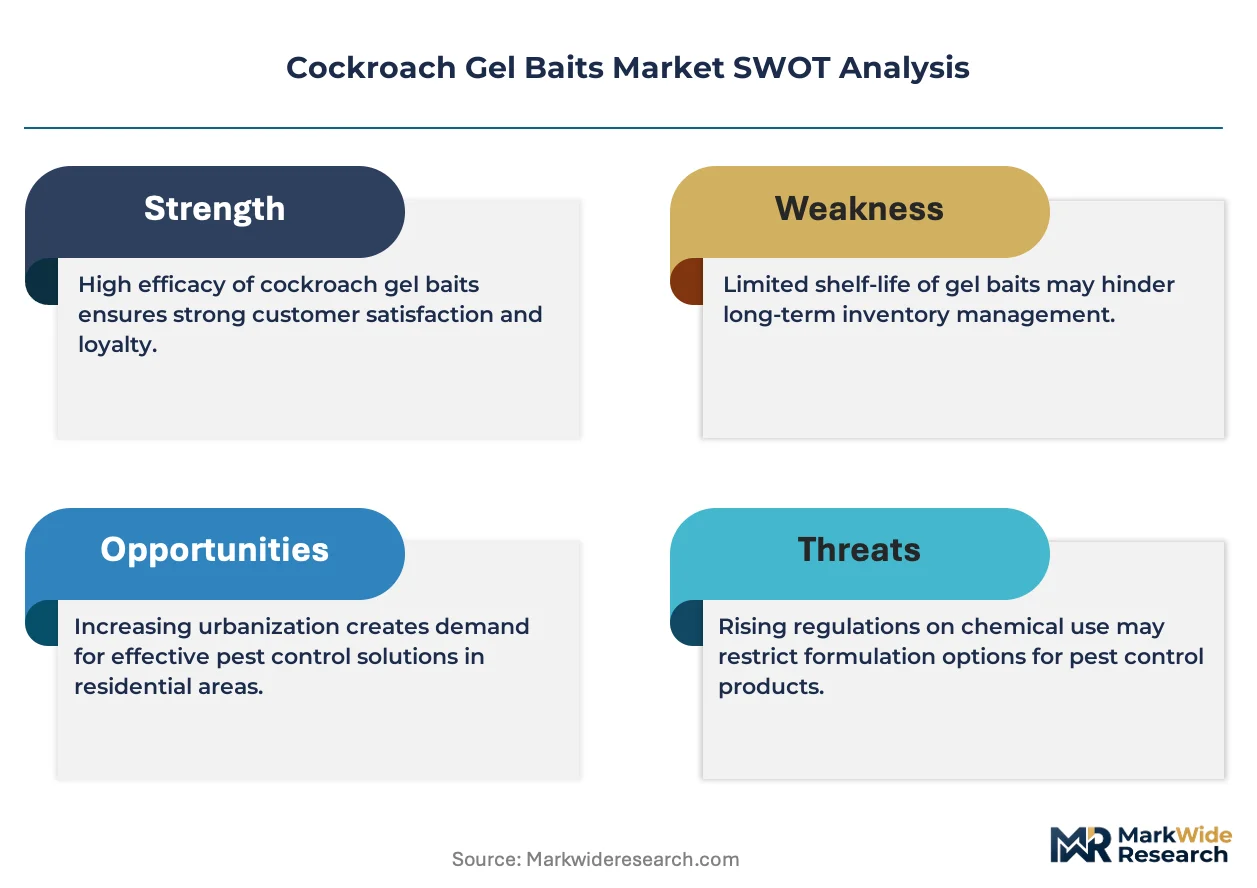
This market functions as a geographic-arbitrage play between EPA's streamlined biopesticide registration in the United States and ECHA's extended REACH authorization timelines in Europe, enabling faster payback periods for botanical formulation investments in North American channels.
For Market Incumbents: Deploy backward integration into fipronil technical manufacturing to insulate margin structures from Chinese supplier consolidation. Capture channel control through exclusive distribution partnerships with pest management professional networks in Houston and São Paulo. Fortify position against neonicotinoid regulatory restrictions by accelerating botanical formulation R&D pipelines ahead of EPA re-registration deadlines.
For New Entrants and Emerging Players: Capture white-space in Brazilian and Indian municipal vector control procurement channels previously served exclusively by spray contractors. Target institutional public housing authorities adopting integrated pest management frameworks with guaranteed efficacy service contracts. Penetrate fastest through IoT-enabled monitoring bundling that differentiates from commodity bait suppliers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale specialty formulators with documented efficacy portfolios but limited geographic registration infrastructure. Long-term viability over the projection horizon rests on multi-regional regulatory compliance capabilities rather than single-market dominance. Monitor EPA neonicotinoid re-registration outcomes as the critical inflection signal for chemistry portfolio rotations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical Manufacturing | Captive fipronil supply from Jiangsu producers insulates formulators against input cost volatility. |
| Botanical Formulation Portfolio Expansion | Pre-empts EPA neonicotinoid restrictions while accessing pet-sensitive retail channel growth. |
| IoT-Enabled Monitoring Service Bundling | Sensor networks from Shanghai vendors create recurring revenue streams beyond consumable sales. |
| REACH-Compliant Synergist Substitution | ECHA authorization deadlines force elimination of legacy penetration enhancers from European formulations. |
| Municipal Vector Control Contract Consolidation | São Paulo and Mumbai public housing authorities shift procurement from spray contractors to gel bait systems. |
Research Methodology
Multiple input streams — regulatory filing databases, customs trade records, and primary stakeholder interviews — were reconciled to construct market estimates. Conversations with pest management professionals, formulation R&D directors, municipal procurement officers, and distribution channel managers provided operational validation. Secondary sources included EPA registration databases, ECHA biocidal product notifications, ANVISA filings, and Central Insecticides Board records. Bottom-up volume modeling and top-down value triangulation across the analysis window ensured cross-verification.
Data-stream reconciliation anchored the forecast framework to segment-specific growth trajectories. Segmentation dimensions encompassed product type tier, active ingredient chemistry, application setting, and packaging format. CAGRs were derived from trend extrapolation of procurement volumes in Houston, São Paulo, Mumbai, and Shanghai corridor markets. Industry-specific inputs included bait rotation protocol adoption rates in USDA-inspected facilities and REACH authorization timeline assumptions for European synergist compounds.
EPA pollinator protection rulemakings, ECHA substance restriction expansions, and Brazilian ANVISA registration acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on regulatory trajectory and procurement budget elasticity. A model refresh is warranted upon material change in neonicotinoid registration status or fipronil technical supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Global Continuous Stirred Tank Reactors Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
Biobased Degreaser Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market